Daily Stock Market Report (Wed 11 June 2025) - TENG, WPHO, RCDO/SAG, FDEV, CGS, IIG, FSTA, IBST, VP.

Good morning! We'll have the agenda up for you as soon as we can.
Spreadsheet that accompanies this report: link.
1.20pm: we are finished for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BT (LON:BT.A).A | Considering rescue of Talk Talk (media story, not RNS) | Various papers reporting. No formal approach made. BT declined to comment. | |
Weir (LON:WEIR) (£6.46bn) | Single largest order for Weir’s GEHO pumps. No change to Weir’s 2025 financial guidance. | ||
Assura (LON:AGR) (£1.59bn) | KKR and Stonepeak make a best and final offer at 50.42p per share (last AGR share price: 48.9p). | PINK | |
GlobalData (LON:DATA) (£1.39bn) | GlobalData ends discussions with investment firm re: possible cash offer. “Offer period” ends today. | PINK | |
Ibstock (LON:IBST) (£762m) | Profit warning due to price/mix and incremental costs. New adj. EBITDA expectation £77-82m. | BLACK (RED) (Graham) In the immediate aftermath of a profit warning, I often turn AMBER/RED to flag the risk of follow-on downgrades. But Ibstock carries significant debts and so to reflect the additional risks involved, it makes sense to me to be fully RED on it, temporarily. I do hope and expect that performance will improve as it ramps up production (gaining greater efficiencies) and as cost inflation is eventually passed onto customers. | |
Warehouse Reit (LON:WHR) (£454m) | Net tangible assets per share up 2.9% to 128p (last share price: 106.8p). | ||
Oxford BioMedica (LON:OXB) (£354m) | On track to deliver the outlook set out in the preliminary results | ||
Fuller Smith & Turner (LON:FSTA) (£353m) | Revenue +4.8% to £376m. Like-for-like sales +5.2%. First ten weeks of new year: LfL +4.2%. | AMBER/GREEN (Graham) Solid results with adj. PBT rising from £20.5m to £27m. A key feature is the predominantly freehold estate and in that regard I note that the balance sheet has tangible equity of around £380, higher than the current market cap. Cash generation is strong with about £37m generated by the business in FY25, according to my calculations. Share buybacks are ongoing. At a cheaper P/E multiple I’d be fully GREEN. At the current level it might still be worth a closer inspection | |
Intuitive Investments (LON:IIG) (£251m) | SP down 12% Fundraise at £1 (last share price: 122.5p), funds to be invested in IIG’s Chinese lottery company. | AMBER (Graham) [no section below] I’m at least AMBER/GREEN on most UK-listed investment companies, but this is a special case as IIG focuses all of its efforts on a company called “Hui10”, which is responsible for over 90% of IIG’s stated portfolio value. Furthermore, IIG says that its NAV per share is 153.2p (March 2025) but it’s raising money at only £1. I prefer investment companies that can buy back their shares at a discount, not issue more of them! So I would treat this one with a high degree of caution. | |
VP (LON:VP.). (£239m) | Rev +3% to £380m, Adj EPS -10% to 67.3p, Dividend +1%to 39.5p. Net debt excl leases up 11% to £138.5m. Outlook: performance for the new financial year to be in line with current market expectations (essentially flat). | AMBER/GREEN (Mark) | |
Cash offer at 430p per share. Buyer has agreed to buy shares from Science (LON:SAG). | PINK (Graham) (GREEN on SAG) | ||
Castings (LON:CGS) (£119m) | Rev -21% to £177m, Op Profit -76% to £4.8m, EPS -75% to 9.6p. Net cash down £17m to £15.6m. Dividend held. Outlook: schedules suggest that the current lower levels of demand will continue in the short-term with improvements in the autumn. | AMBER (Mark) | |
Frontier Developments (LON:FDEV) (£107m) | Rev +1% to £90.6m, adj. EBITDA £8-9m. Cash +£13m to £42.5m. £10m share buyback proposed. Outlook: confident in ability to deliver further annual growth in FY26. | GREEN (Graham) Happy to be fully GREEN on this once again; it’s now a Super Stock with a bright outlook. The major uncertainty is the success (or otherwise) of Jurassic World Evolution 3, scheduled for release in October. | |
Digital 9 Infrastructure (LON:DGI9) (£78.6m) | Completed the sale of its interests in SeaEdge UK1, asub-lease of a data centre and subsea fibre landing station for £10.7m. Used to imminently repay and cancel the RCF balance of c. £13million | ||
Ten Lifestyle (LON:TENG) (£58m) | …a new multi-year contract with one of Japan's leading financial services providers from an incumbent competitor. Expected to support revenue growth in FY26. | AMBER (Mark) [No section below] | |
Windar Photonics (LON:WPHO) (£50m) | Order shipped in late December did not meet accounting requirements to be booked in FY24. “As a result of this adjustment, expectations for 2024 revenue are €4.6m with an EBITDA loss for the year of circa €0.4m.” | BLACK (AMBER/RED) (Mark) [No section below] Prior guidance was €5.7m sales & €0.4m EBITDA due to a previously announced customer delay, so not quite sure how a €1.25m delay to revenue recognition makes these numbers add up! It is tempting to think this is just accounting and not material. However, that there can be some doubt on revenue recognition on shipped product raises a whole heap of questions about their internal processes. The investment case here is based on a huge jump in sales and profits for FY25. Roland rated this AMBER earlier this year, but with revenue recognition issues and the algos declaring this a momentum trap, I think a downgrade is in order. | |
Caffyns (LON:CFYN) (£12.3m) | Rev +5% to £275.5m, U/L EPS 16.4p (FY24: -17.3p), FY dividend held at 10p.Outlook: healthy order book but early part of the year remained challenging. |
Graham's Section
Ricardo (LON:RCDO)
Up 25% to 418.4p (£260m) - Offer for Ricardo Plc - Graham - PINK
Ricardo has jumped before it was pushed, finding a buyer for the entire company which will end the ongoing friction with Science (LON:SAG).
The offer comes from WSP, a major global engineering/professional services firm with over 72,000 employees.
The price: 430p, a 28% premium to yesterday’s close and a much higher premium against the average price of recent months:

The rationale: nothing too out-of-the-ordinary.
WSP Group believes that the integration of Ricardo into the WSP Group will accelerate the implementation of Ricardo's strategic objectives and provide additional opportunities for cost savings and revenue synergies through increased scale and complementary offerings.
They specifically praise Ricardo’s “EE” business (a recent acquisition that attracted some criticism for the price paid).
The Ricardo directors recommend the bid and will vote their 0.19% of shares in favour of it.
Other major shareholders have promised to vote their 44.9% of shares in favour of it, too. This does not include Science Group, although Science Group also supports the takeover.
Timeline: expected to complete in Q4 2025.
Comment by Ricardo’s Chair (emphasis added by me):
"Ricardo has made significant progress with its strategy to transform the business into a world leading environmental and energy transition consultancy, with its prospects underpinned by global mega trends supportive of long-term growth.
However, while good progress has been made, there are further steps required to complete the transformation which bring some execution risks against the background of short-term market challenges and the uncertain geopolitical and macroeconomic backdrop.
Against this background, WSP has made a compelling offer which represents a highly attractive premium to recent average trading levels and provides certain value in cash today for Ricardo shareholders.
Graham’s view: I was overly sceptical on the value of Ricardo, putting it AMBER/RED (see here and previous comments). But I must be honest that I still struggle to see the value in it.
A recent update from Panmure suggested that the company would have net debt of c. £85m as of June 2025. I knew it would be high, but not that high, when I turned AMBER/RED on the stock in January.
Panmure’s EBIT forecast was only £20.8m, rising to £24m the following financial year.
In my experience, debt-ridden consultancies or professional services businesses can be toxic investments and even in the absence of debt, I wouldn’t want to put them on high earnings multiples - they are people businesses, at the end of the day!
At 430p, Ricardo is being valued at £267m or an enterprise value of over £350m if we add in net debt.
The implied P/E multiple is 17x if I apply a 25% tax rate to the EBIT forecast for this year. I get the same 17x multiple if I calculate EV/EBIT.
That’s not a multiple I’d wish to pay, but WSP will presumably be able to strip out some costs and maximise the growth potential of these earnings within a much larger organisation.
I should also note in passing that WSP’s Canadian-listed shares (here) trade on a forecast P/E multiple of 27x.
So it’s yet another example of a North American company finding a relatively cheap acquisition target in London.
Science (LON:SAG)
Up 9% to 505p (£225m) - Ricardo Investment Realisation - Graham - GREEN
Science have done extremely well in a short timeframe:
Between 16 February and 27 May 2025, Science Group acquired 13,537,623 shares in Ricardo plc ("Ricardo"), equivalent to approximately 21.8% of the voting rights, at an average price of 239 pence per share (including brokerage fees).
Selling up at 430p will mean profits of c. £26m on a £32m investment.
They’ve agreed to sell 12.4m of their shares in a standalone agreement, and the funds from this are expected “before the end of June”, which is very nice for them - an accelerated timeline for them vs. the expected takeover which is not expected until Q4.
This concludes the spat between Science and Ricardo, with an outcome that I imagine all parties are satisfied with.
I can now turn GREEN on Science again, as my only reason for turning AMBER/GREEN on it in the first place was the risk surrounding their Ricardo investment - it drained their cash and, I’m sure, management’s attention. I was concerned that this saga could drag on indefinitely - perhaps for several years.
But soon their cash balance will be very full once again, and Executive Chair Martyn Ratcliffe will be free to move on and focus on other matters. Well done - I should never have doubted him!
Frontier Developments (LON:FDEV)
Up 13% to 304p (£120m) - FY25 Update - Graham - GREEN
I upgraded my stance on this recently thanks to an ahead-of-expectations update, which hinted that this troubled company might be on the cusp of a rebound.
That was on 28th May. Now we get the scheduled full-year update from FY May 2025, with more details on the company’s improved performance.
Some key points:
Revenue up 1% to £90.6m.
Within that, the company’s flagship “creative management simulations” games grew 25% per year, providing 77% of total revenues (previous year: 62%).
CMS games are once again at the heart of the company’s strategy, seen as providing the route for the company to restore its fortunes.
Continuing with today’s update:
Adj. EBITDA of £8 - 9m (previous year: £0.9m), including a £3.5m one-off gain on the sale of a game.
Cash £42.5m (previous year: £29.5m).
Thanks to the strong cash position, we have:
£10m buyback (subject to shareholder approval):
The Board is confident in the future cash position of the Group, and that this can adequately fund future growth plans, which remains the Group's core capital allocation priority…
After considering the Company's balance sheet position and prevailing share price, the Board believes that it would be beneficial to return capital to shareholders through a share buyback.
This makes good sense to me. It seems reasonable that even after spending £10m on a buyback, the remaining funds, plus future profits, should be sufficient to fund future development spending.
Game franchise headlines: revenues from Planet Coaster saw very strong growth thanks to the release of a sequel in November, Planet Zoo was stable, and Jurassic World Evolution fell slightly.
In an RNS on Monday, the company announced that JWE 3 will be released in October, and is available to pre-order now. Here’s the trailer (YouTube).
Outlook:
Having achieved growth in revenue, profit and cash in FY25, the Board is confident in Frontier's ability to deliver further annual growth in FY26 through nurturing and expanding our genre-leading game franchises.
Estimates
After the unscheduled May update, PanLib had an FY25 revenue forecast of £90m, an adj. EBITDA forecast of £7.4m and a net cash forecast of £37.9m.
These have been beaten and are lifted again to £90.6m, £8.1m and £42.5m, respectively.
For FY26, they lift the EPS forecast in light of the planned buyback (fewer shares means higher earnings per share!).
The new FY26 underlying EPS forecast is 19.9p, rising to 28.6p in FY27.
(Previous forecasts: 17.5p in FY26, 26.6p in FY27.)
Graham’s view
This is a stock where I’ve had some difficulty in the past. I’ve wanted to be GREEN on it fundamentally, due to its strong balance sheet and the potential for future flagship titles to meet with success.
However, I’ve also needed to respect the negative momentum and the uncertainty that goes with investing in turnarounds.
Now, however, the turnaround appears to be in full swing as the company has returned to its original CMS strategy.
Stockopedia categorises it as a Super Stock:

I think I can go fully GREEN on this with a clean conscience.
There is a major uncertainty, which is more elevated than you might get in other industries: I can’t guarantee that JWE 3 won’t be a flop. Game developers get it wrong sometimes - and Frontier have got it wrong about as often as they’ve got it right in recent years. And even when game developers have done everything right, the reaction of audiences is unpredictable.
While acknowledging this major uncertainty, I think that the risk:reward is positive here now, and I’m happy to be fully positive on it again. The P/E multiple is 15x for the financial year that has just begun (FY May 2026), without making any adjustment for the cash balance or buyback.
Ibstock (LON:IBST)
Down 12% to 170p (£672m) - Second Quarter Trading Update - Graham - BLACK (RED)
Ibstock Plc ("Ibstock" or the "Group"), a leading UK manufacturer of a range of building products and solutions, today issues a trading update.
Unfortunately, it’s a profit warning.
The RNS starts out well:
Activity levels in the Group's markets have continued to be well above the prior year period, reflecting increased demand in residential construction markets. Accordingly, we continue to expect first half sales volumes in the core business to be materially above the prior year level.
The problem: building back up capacity at Ibstock’s factories has created some additional fixed costs. There seems to be a lag between incurring these costs and getting the factories back up to higher productivity.
On top of that, it has been “challenging” to pass on cost inflation to customers, due to the sales mix and to “a more competitive market backdrop”. As a result, clay and concrete pricing in H1 is “broadly in line” with H1 last year.
The result of higher costs and weaker revenues than needed: full year adjusted EBITDA is now forecast at £77 - 82m (so it should be in the region of last year’s £79m result).
I believe that this is a miss of about 14% against expectations.
More positively, various organic growth projects are said to be on track.
CEO comment:
"Despite ongoing uncertainty, we are encouraged by signs of recovery in the UK housing market. As such, we remain committed to taking steps to ensure we are well placed to support customers and benefit from the recovery as it gathers pace. Notwithstanding the margin headwinds encountered in 2025, we remain confident that our recent actions alongside our strategic investments leave us well positioned as activity levels continue to pick up."
Graham’s view
It should perhaps come as little surprise that a brick manufacturer should meet competitive pressures - this meets the definition of a commoditised product!
Historically, Ibstock’s performance has been highly variable, which makes sense given its exposure to various macro factors beyond its control. While it usually posts a profit, its return on equity has ranged from excellent to mediocre.
Before today’s profit warning, the StockRanks weren’t too impressed. I note the following momentum score;

Consistent with Stockopedia’s view that profit warnings tend to follow other profit warnings, I’m going to take a RED stance on this, temporarily.
I’d like to lift this stance as soon as possible, but I think it does make sense to be cautious - in the results for FY December 2024, I see that the company finished the year with net debt of £122m, and a leverage multiple of 1.8x.
While that debt load was at the lower end of the company’s prior expectations, and the leverage multiple does not suggest that it’s suffering any distress, it creates an extra risk factor when we combine it with today’s profit warning.
Readers may have noticed that I’m often AMBER/RED on companies that have just issued a warning. But in a case like this, where there is significant debt involved, I think it makes sense to be RED in the short-term.
Mark's Section
Castings (LON:CGS)
Down 4% to 262p - Final Results - Mark - AMBER
There’s no results table, but the comparisons here are pretty unfavourable. Revenue is down 21% to £177m, Operating Profit plummets by 76% to £4.8m, EPS is now just 9.6p. Strangely, this appears to be a fairly sizeable beat on revenue, but a miss on PBT. Their broker, Zeus, say:
Revenue decreased by 21.1% to £177.0m in FY25 (6.5% ahead of our estimate due to higher-than-expected Foundry volumes)...Because of the inherent operational gearing in the Group, EBIT decreased by 75.8% to £4.8m, broadly in line with our £5.0m forecast.
Although Zeus notes that Castings has played with a very straight bat when it comes to adjustments and and not classified the £1.5m penalties enforced on forward purchased electricity volumes or the £1.3m losses from the first nine months of the Scunthorpe acquisition as exceptional.
Outlook:
This is what the company says we can look forward to:
The schedules from our heavy truck customers suggest that the current lower levels of demand will continue in the short-term with improvements in the autumn.
This is undoubtedly a cyclical business and we can expect this year’s trading to be at a nadir. However, the market never likes a H2-weighting as it introduces considerable uncertainty over the next period’s results. Zeus make only minor revisions to their forecasts and introduce FY28 estimates. Here is a summary:
FY26E | FY27E | FY28E | |
Revenue (£m) | 174.9 | 182.2 | 189.7 |
EPS (p) | 17.0 | 22.4 | 23.0 |
Cannacord’s numbers are very similar. They represent a big recovery in EPS versus the results released today. However, these are rather uninspiring. The forward P/E of 15 looks high in current markets, especially as the H2-weighting adds to the risk.
Dividends
For many investors, the long-term dividend track record is a big attraction:

So income investors will be pleased with this:
The directors are proposing a final dividend of 14.19 pence (2024 - 14.19 pence) per share totalling £6,166,700 (2024 - £6,166,700). This dividend has not been accrued at the balance sheet date.
This gives a very slight increase for the year (excluding the special dividend paid last year), and with further small increases forecast, the yield is around 7%. However, this was uncovered by EPS in FY25 and forecast to be uncovered again in FY26. This means that they have been using their cash balance to fund the payout.
Net cash has fallen by £17m during FY25 to £15.6m. The main reasons are the uncovered dividend and that the capex of £19.8m has exceeded the depreciation of £8.9m. The payment of the £6.2m final dividend will presumably reduce the cash balance in the short term. Zeus forecasts £16.6m of operating cash flow for FY26 and capex reducing to £8m, meaning that this cash balance should start to grow modestly again, barring any mishaps.
It is worth noting that this increasing dividend has not driven up the long-term share price, which is largely flat over the last 20 years:

Valuation
Zeus include a DCF calculation in their note, which seems a good way of valuing a business which is essentially a mature, slow-growing one. This assumes a 2% terminal revenue growth outside their forecast window, 90% conversion of EBITDA to Operating Cash Flow and £8m capex growing with inflation. With their 10% discount rate, they come up with a 343p valuation. Personally, at £100m market cap size and given the issues the company has had, I’d want a slightly higher discount rate than that. Although I don’t have my own DCF, one of the most interesting things is to work out what discount rate the current share price implies, and I’d imagine it was around 14% from extrapolating their sensitivity chart. So the current share price looks around fair value. Logically, this is what holders can expect to receive for holding over the long term. As in the last 20 years, I expect the bulk of the returns to be from the dividend payment. So this is a 7% yield, rising at around 5% in real terms and a share price tracking inflation. This may be attractive to some investors, but I struggle to get excited by it.
The other way of looking at this is based on the assets of the business. I make the current P/TBV from these results as 0.87. This highlights potential undervaluation. However, I doubt that their Property, Plant & Equipment has significant alternative use. There is £26.8m of freehold property, but there is little sign that this in excess of the business needs. So it really comes down to what returns they can generate from those assets. The recent past is not very promising on this front:

Nor is the future, by my calculations:
| FY26E | FY27E | FY28E | |
|---|---|---|---|
EBIT (£m) | 9.1 | 12.3 | 12.8 |
Net Assets (£m) | 126.9 | 130.8 | 139.1 |
ROCE % | 7.1% | 9.4% | 9.2% |
These firmly single-figure numbers suggest that the current modest discount to tangible book value is likely around fair value.
Mark’s view
Whichever way I look at this, I come to the conclusion that the current price represents fair value, given the history of the business and current forecasts. While there may be some conservatism in these medium-term estimates, there is also the risk of a near-term miss due to the weak current trading conditions. Some investors may be attracted by the 7% yield, which will probably rise slightly above inflation. However, I struggle to get excited by that prospect. Hence, it is an AMBER for me.
VP (LON:VP.)
Up 1% to 606p - Final Results - Mark - AMBER/GREEN
These results to 31st March this year are very similar to the previous year, on an adjusted basis:

The revenue looks like a small miss and the adjusted EPS a small miss versus the Stockopedia consensus, but not enough to really move the needle:
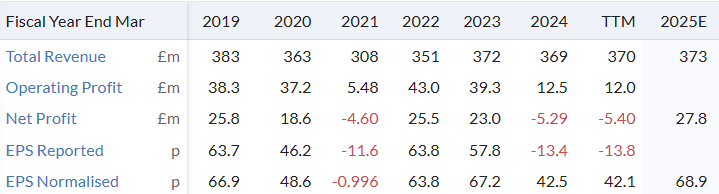
Despite looking a bit better than last year on this front, there is a big gap between adjusted and statutory EPS. Here are the details:

These strike me as not very exceptional. Restructuring appears to be fairly normal over the last couple of years. While the acquisition-related costs are more of a one-off, they don’t break out the revenue or EBITDA impact of the acquisition on the results elsewhere. Meaning there is a bit of having your cake and eating it here, in my opinion. They provide some more details of their impairment charges in the narrative:
Impairment charges against property, plant and equipment and right-of-use assets, alongside the impairment of intangible assets (see below), have been recognised against assets held in the Brandon Hire Station cash generating unit (CGU), where challenges in the general construction sector continue to impact performance. These non-cash impairments have been calculated by comparing the carrying value of the CGU against its recoverable amount. Restructuring costs mainly relate to branch closure costs in the Group's Brandon Hire Station and UK Forks divisions.
While having to write down the value of equipment in one go may be non-cash, it suggests that their depreciation policy has not matched the reality of operating this part of the business. Ongoing depreciation would, of course, be non-cash but booked to the income statement as a cost and reflected in EPS. These differences are probably behind the difference between what the company considers their adjusted EPS and the figures provided to Stockopedia by Refinitiv.
One nice aspect about the company is that they quote ROCE as their third metric in the table. This shows an unusual focus on this for the sector. That marks them out amongst peers for caring about the returns their assets generate, not just growing at any cost. However, again, adjustments matter here, and the average figures in Stockopedia are less impressive:

Net debt excluding leases is up by £13.3m. However, £10m went on an acquisition and £15.4m on paying dividends, so this doesn’t seem unreasonable. This excludes around £3m of provisions that are on the balance sheet, and their lease liabilities currently exceed lease assets by £7.6m.
Outlook:
They say performance for the new financial year is expected to be in line with current market expectations, and helpfully give those:
Vp compiled analyst consensus for 2025/2026: Revenue of £383.2m, Profit before tax, amortisation and impairment of goodwill, trade names and customer relationships and exceptional items of £37.3m and pre-IFRS 16 net debt of £137.2m.
These are pretty much flat on the current year. However, this is worse than it seems as the acquisition they made in October last year will have had a full year of trading. This means that LFL revenue and profits are forecast to decline.
Valuation
If we accept the company’s adjustments, this is modestly rated going forward:

This is undoubtedly still a tough market for the sector, and there is scope for results to improve further as construction markets recover. The P/TBV is rated as green compared to the market but only amber versus the sector. It is worth noting that other plant hire companies, such as Speedy Hire, trade at a discount to TBV. This certainly reflects VP’s higher average long-term ROCE, but may mean that there is greater upside elsewhere if the sector enters a new boom.
The dividend increase is modest, but still represents over 6% yield on current prices, so investors get paid to wait for a market recovery. When the accounts are muddied by adjustments and large capex and depreciation charges, the payment of a reasonable dividend gives confidence that the underlying business is cash-generative.
One factor to consider is that this can be a very illiquid share for its size. The stock is tightly held, including by a controlling shareholder. While the spread doesn’t seem too bad today and can often be traded inside the published bid-ask, it isn’t always this tight:

The Exchange Market Size (which is the minimum market makers have to make available to phone traders at their published bid/ask) is only £3k, which doesn’t seem much for a £200m+ company.
Finally, the major shareholder put the company up for sale in 2022, but clearly didn’t get acceptable offers. This may mean that the business has undesirable characteristics. After all, its top-line growth has been mediocre over the last few years. However, that may also mean that the current UK takeover boom may finally make its way here, as it seems there is a deal to be done at the right price.
Presentations
VP commit one of the faux pas I particularly dislike. They talk to analysts immediately but wait a few days to present to the likes of us:
Analyst Briefing: 9.30am BST Today, Wednesday 11 June 2025
A live briefing for sell-side analysts…at 9.30am BST today. After the briefing has finished, an audio webcast of the presentation will be made available on the Group's Investor Relations website here.
Presentation with Equity Development: 10am BST, Friday 13 June 2025
Vp management will host an online presentation for retail investors via Equity Development at 10am BST on Friday 13 June.
At least they provide the audio of the analysts call. However, at £200m market cap, with Jeremy Pilkington holding 51% of the shares, individual investors probably set the price here and may be more engaged than the analysts. (I also don’t like the term retail investors as it suggests a certain naivety that is often not there, certainly amongst Stockopedia subscribers.)
Mark’s view
There’s a lot to like here. A modest rating if you believe management's adjustments, and a decent yield. However, management have rather blotted their copybook in my opinion by being a bit aggressive on the adjustments they make. Current trading may be in line, but on a like-for-like basis, this looks to be a decline in revenue and profits. However, this is a cyclical business, and there is the potential for organic growth once their end markets improve. When Graham looked at this last year, he just about kept it as a GREEN but was sitting on the fence heading towards AMBER/GREEN. Having seen the scale of the adjustments in these results, and the not particularly inspiring StockRank:

I’m going to make the jump to AMBER/GREEN. However, if there are signs of good organic topline growth in the future, I think I could be persuaded to jump back.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Thank you to all subscribers who responded to my post this morning.
It is reassuring to learn that I am not alone in feeling apprehensive at the present time.
I have top sliced or sold whole holdings, not finding much to buy at all, in the last month or so. Many shares are looking peaky, going by the charts, sure some will go higher but l don't want to risk it. Waiting for some pullbacks.
Thank you for your assessment of Castings Mark, we've held for those twenty years and failed to take profits, with hindsight we should have done. As I'm trying to turn our portfolio Green your Amber rating is a disappointment but I agree with everything you've said. I also think this is probably their nadir and will continue to hold in expectation of a slowly rising share price next year!
As we enter my favourite time of the year ,Royal Ascot, Wimbledon, Open Golf Championship and long days I am feeling apprehensive. Why?
Although my portfolio is up led by 'Fresnillo (LON:FRES) up over 100% since January and commentators are still saying Aim is full of bargains the negatives weigh heavily.
I refer to talk of a recession in the USA as Trump defies all political norms and Putin continues his War against Ukraine. The British high streets are being decimated by closures with a shop near me saying 50% of his takings go in various forms of taxation. Law and Order is a growing worry and our politicians abilities descend to new lows.
Seasoned experts are suggesting top slicing profits now while you can.
Am I right to feel apprehensive?
Like you, I'm happy with my portfolio performance year-to-date and I don't want it to go up in a puff of smoke. I've currently got a third in cash and equivalents so that, if there is a market slump, I'll have plenty of ammo for a buying spree.
portugull I feel the same.
Need a balanced portfolio: defensive shares, cash, gold and silver
Worry about rising share prices
Portugal
Like you I am a bit worried about my portfolio rising so much this year.
I agree with all the points you raised but it’s all compensated by the walls of money being redeployed from US to UK and Europe.
Anecdotes speak of large volumes finding its way into a diminishing UK market.
Just look at the take over premiums . I expect more to come .
Having said all that I have kept all dividends in cash.
Portugull, I feel exactly the same, last few years have not been great and despite recent goods times within my portfolio none of us should let our guard down. My standout is Rolls-Royce Holdings (LON:RR.) I have held on way past the point of being comfortable and my finger is over the button to sale!! All points you raise I agree in particular Law and order from my own experience I would go further to say is out of control.
Castings (LON:CGS) has released inline FY25 results today. Read a copy here
Heavy truck demand has been weak but there are signs of some improvement from the Autumn. The company has a rock solid balance sheet and will pay a final dividend of 14.19 pence per share giving a total dividend for the year of 18.40p, a yield of 6.7%.
Listen to the management tomorrow at 12.00pm when Adam Vicary, CEO, and Steve Mant, CFO present these results at a webinar for private investors. Register https://us02web.zoom.us/webinar/register/1017467847460/WN_LFwylnyUSteilsQt7__r6Q
I too am looking at the Ibstock (LON:IBST) statement - my interest being as a previous holder of Forterra (LON:FORT) once upon a time.
I struggle to see why the headwinds holding back profitability at Ibstock (LON:IBST) are not sector-wide. I guess my misgivings are:
1. Brick building is hugely energy intensive. The UK has the highest energy prices in the developed world.....
2. Imports are competitive - despite their weight it seems to be cheaper than you would expect to ship bricks between markets. It is interesting to hear Ibstock (LON:IBST) say they are struggling to pass on cost inflation - brick buyers have the upper hand at the moment?
3. There is mothballed capacity lurking - I recall Forterra (LON:FORT) mothballed older, less efficient production when new facilities came online. Any surge in pricing/demand and I guess this capacity could be brought back into play, capping prices? And as Ibstock has just pointed out, bringing back capacity has a cost that defers profitability!
4. Brick-laying is hugely labour-intensive, and it requires skilled labour. The govt can talk about how many new houses they wish to build and even make meaningful changes to speed up the planning process (Berkeley group (LON:BKG) have commented on progress here). But this means very little if the builders don't have the capacity to build more houses, and NI changes have made labour more expensive. The current tone on immigration will make it difficult to import brickies/trades?
5. Given the constraints above you've got to wonder if the social housing constructors will increasingly look to designs that are less brick-dependent that are more scalable/dense? Also a much larger proportion of new build homes are likely to be in blocks of flats rather than the traditional semi-detached? These may use more steel/cladding and fewer bricks per unit? So construction could do well, but bricks benefit less than the past?
6. The customer base is more concentrated these days, with smaller builders struggling to stay in business - this means you are selling to well-informed buyers with chunky market share who will be looking for bulk discounts?
Now if someone could please list the bull points for me....I presume the operational gearing here could really kick in on any sustained upswing, once stock clears and the factories start running at full capacity.
'you've got to wonder if the social housing constructors will increasingly look to designs that are less brick-dependent'
According to the FT Barratt Redrow (LON:BTRW) are building more timber-framed houses for this very reason.
Electric prices are the highest in the UK but gas is below the EU average.
No one wants boring facts on energy.The city projects lower prices The Telegraph does not.
"Given the constraints above you've got to wonder if the social housing constructors will increasingly look to designs that are less brick-dependent that are more scalable/dense?"
Fairly essential in my view but we have dithered for years with alternative methods. I posted a while ago that houses were now being built elsewhere using 3D printing which seems to solve many problems with labour shortages and high energy cost materials
Even with traditional construction the various methods such as steel and timber framing have failed to gain acceptance. Poorly implemented timber framed set us back some years and steel framed, despite being supported by British Steel ( Surebuild) never got much interest from main stream builders. We just don't seem very receptive to new ideas.
Have looked at the brick manufacturers in the UK as potential investments and decided that energy costs will be a major problem. I cant see energy costs ever coming down significantly unless the Government makes a strategic decision to support key manufacturing in the UK with subsidised energy. Probably not going to happen.
Noble Francis is a useful follow on UK housebuilding/ construction - he has frequently covered labour shortages and particularly the ageing demographic of the UK construction workforce, high dropout rate of apprenticeships (over 40% if I remember correctly) etc.
Recent thread on brick deliveries:
https://x.com/NobleFrancis/sta...
A number of portfolio companies reporting this morning. Brief thoughts on a quick initial read:
Fuller Smith & Turner (LON:FSTA) A modest holding bought at around 520p a few months ago when no one was interested. Results look to be ahead of consensus which is for EPS of 30.7p. Adjusted earnings have come in at 34.22p and basis earnings at 47.49p. A well run hospitality business with a mainly freehold estate providing good asset backing.
Oakley Capital Investments (LON:OCI) Peter Dubens and his team have been busy. Two acquisitions. The shares continue to trade at a significant discount to NAV.
TR Property Investment Trust (LON:TRY) One of three investment trusts held, the third being Rockwood Strategic (LON:RKW) . The commercial property market is improving from a subdued base. Happy to bow the Marcus Phayre-Mudge expertise and receive the near 5% yield with the shares trading at around a 8% discount.
VP (LON:VP.) Adjusted eps of67.3 looks marginally below consensus, but in my view this is by far the best in its peer group and I am happy to be patient and collect the handsome dividend of 6.5% while waiting for rail and general construction/house building to improve.
A general comment on Ibstock (LON:IBST) I don't hold. This morning's profit warning looks to be company specific, but the general takeaway is that demand for bricks appears to be picking up. I hold Brickability (LON:BRCK) which operates a capex light approach and doesn't manufacture and Michelmersh Brick Holdings (LON:MBH) a manufacturer of specialist bricks and ancillary's. It reported trading in line at its AGM on 15 May.
Long-term holder of Fuller Smith & Turner (LON:FSTA) here, and not just for the generous shareholder discount! This is undoubtedly a pleasing set of results, which reinforces my confidence that this is a well-managed business. That said, I have two notes of caution.
First, while the results state that like-for-like trading is up 4.2% in the new financial year, the Chief Executive mentioned in a Radio 4 interview this morning that the business requires 3–4% LFL growth just to stand still, given the increase in employer National Insurance contributions and the rise in minimum wage effective from 1 April.
Second, the longstanding Chairman is stepping down and will be replaced by the current CEO, who is becoming Executive Chairman. While a new Non-Executive Director has been appointed to maintain Board balance, I would personally have preferred to see a new independent Non-Executive Chairman take over the role.
Thanks Daniel - Maybe this explains why despite such excellent results announced this morning, the shares are marked down - as indeed were Young & Co's Brewery (LON:YNGA) with their results last week
Yes, a slight dip today on a very strong set of results. It's fair to say the shares have had a good run over the past 3 months so perhaps there's a bit of profit taking going on. I'm happy to continue to hold, but will continue to monitor closely.
Roland covered Castings on Feb 18th and gave it Amber/Green on its Black PW. Mark was less impressed when it passed one of his screens. Today's thorough Chairman's statement with FY results is a long list of everything the company is going through and doing about it. The dividend record is maintained and as an optimist with a weakness for British metal bashers, as long term holders we will continue to hold. Results today are in line with reduced forecasts and FY 26 forecasts held. I hope one of the team will have time to comment on this.
£CAST
i remember buying castings briefly back in the day - i soon came to the opinion that there is more stuff that can materially hamper them from making good profits with external issues beyond their control than there is potential to get new profitable revenue streams and drive the business forward with consistent increasing profits not relying on something else to throw a spanner in the works.
dont get me wrong is probably a reliable plodder makes some profit each year - pays out chunky dividends and may do well if one buys on the dips - or when company is hitting a purple patch. But i feel i learned something with companies that just have too much externmal stuff gfoing on that can scupper them. Have i totally leared my lesson here ? possibly not as within the last 12 months i have bought into zotefoams probably a similarly capital intensive business with similar possibilities for their prozed profits being torn away at short notice - i have always been a sucker for bottom fishing - not sure thats a recomemnded strategy for long term gains.
Getting back to the company at point - they can easily churn out £10 mill profit in a good year (unless times have moved on) so with current market cap of £120 mill - if i held not sure i would be rushing to exit at 260p exit price - but i am not over tempted to get back in here despite the fact it probably will bounce back at some stage with some decent divis in the meantime.
Hey ho every every sucker stock has its day temporarily - now i am off to bask in the current shareprice glory of Northern Bear (LON:NTBR) a sucker stock that is currently having its day (note stocky has always liked this company even when teh market didnt there ya go)
As a fellow bottom fishers rmillaree we also bought into Zotefoams, also Bioventix hopefully near its bottom. I know it's not what good investors recommend and not what Warren Buffet did or Terry Smith does with his funds, maybe as young people would say, "You're smoking copium". Well done on Northern Bear.
Science (LON:SAG) Ricardo (LON:RCDO)
Bravo the Board of Science Group, they've practically doubled their money in the space of a few months in plain sight of a sceptical dopey market.
The price dislocation to intrinsic value in the UK market is off the scale now, just look at the bids and the premiums being paid.....
Frontier Developments (LON:FDEV) should have a big bounce today as profits increase from £0.9m to £8-9m together with cost cutting, £3.5m from sale of a foundry game plus plan for a £10m buyback.
It fell such a long, long way after the pandemic. If I knew how to share the sp graph you would be astonished though it’s unlikely to get back to the previous dizzy heights of 3316p -before today’s open it’s 270p..
Frontier Developments (LON:FDEV)
It fell such a long, long way after the pandemic. If I knew how to share the sp graph you would be astonished though it’s unlikely to get back to the previous dizzy heights of 3316p -before today’s open it’s 270p..
Well it was company with greaqt growth plans some excellent large franchise type licences and possibly on track for £30 mill per year profits with chnace of moving to the big boys table.
Since then is manged to eak out zero profits over 3 year period - sop the fall from grace is just pretty natural.
Thats the reality where a company makes no profit and the cash reserves are frittered away.
I would say if they can get back to £10 pa profits permanently then the current market cap of around £110 mill will look cheap. I have kind of lost interest here as i no longer believe they have the firepower to compete with the big boys.
Looking at the 2025 headlines it looks like its a trip back in times with the names of the brands - these are the tried and tested names from probably pre covid days. they could have pimped out these names with modicum of investment and done much better for shareholders.
looking at the 2019 annual report we have
• The launch of Jurassic World Evolution,combined with the ongoing performanceof all three titles, Jurassic World Evolution,Planet Coaster and Elite Dangerous, propelledthe Company to a record financial performancefor the year ended 31 May 2019.Frontier’s next major release is Planet Zoo.
and now its
FY25 Franchise Headlines
· Planet Coaster franchise revenue grew by almost 200% year-on-year through the release of Planet Coaster 2 in November 2024 on PC, PlayStation 5 and Xbox Series X|S.
· Planet Zoo franchise revenue grew by 2%, building on the release of Planet Zoo: Console Edition in March 2024, with new content in the year for both console and PC players.
· Jurassic World Evolution franchise revenue sustained at 96% of the prior year level, as we prepare the franchise for its next big step with the development of Jurassic World Evolution 3.
· Elite Dangerous revenue grew by 76% year-on-year through new content and player engagement.
anyone see the similarities ?
is it a coincidence that going right back to basics and ditching global domination is what is needed to return them to profits. very much evolution than revolution.
Agreed rmillarree. I would be delighted to get back to my entry price of nearly 12 quid. I had really hoped they would make something very successful with the licences they agreed with Games Workshop (LON:GAW) but this doesn’t even warrant a mention. I had incorrectly assumed this would be a massive opportunity. Maybe it is and might get a revival when Amazon do their thing with the filming/tv rights?
Frontier Developments (LON:FDEV) - i suspect they may struggle to deliver much more than £20 mill pa profits - and pe then of say 20 would be 1000p - so its not beyond the realms of possibilities that i could see this share bounding back strongly - easy for me to quote £20 mill - thats double the amount quoted though now though so i suspect that may be somewhat of a pipe dream. I agree with the possibilites - i did like this share when they were on the cusp of delvering 1 minimum blockbuster each year new licence and growing their catalogue - now though i just look at it as cashing in now on money spent years ago - as you say games workshop stuff could and should be huge - at least these tried brands churn out decent cash. Perhaps warhammer will come to the rescue ?
There you go. Quote a drop from the post pandemic high. Might break out from here?
Hi Revs8
Do you mind me asking where you are getting those graphs from?
I use Trading View. An alternative beginner tool is investing.com (free with ads).
Thank you for taking the trouble to reply - much appreciated!
For those of you interested in Ed's Jump Shares Frontier Developments (LON:FDEV) demonstrates this nicely. It has "jumped" about +12% today on YE numbers, +9% with its Trading Update in May and +25% with its H1 results in January.
The price may fall back again, but if it has turned itself around more 52Wk Highs and more jumps are probable, because behaviourally investors are cumulatively under-reacting to its positive news. I hold
I did put those in a folio for a while. Folio is up 10%, FTSE All share is up 7%, not bad but not special. There have been some big fallers such as 4imprint (LON:FOUR) and Ashtead Technology Holdings (LON:AT.). Best performer is Staffline (LON:STAF) up 79%.
Rusty,
You dont need to invest in every "Jump" stock. You can pick your preference.
Buffett once said; “The trick in investing is just to sit there and watch pitch after pitch go by and wait for the one right in your sweet spot. And if people are yelling, ‘Swing, you bum!,’ ignore them.”
How do you know which will be the best one? I did not buy Staffline (LON:STAF), who would have thought they would be, by far the best performer, with their history.
I did not buy them all, l just put 30 in a folio, that had jumped over 10%, on the day, to see how they performed.
Buffet has made plenty of mistakes, fancy buying Tesco (LON:TSCO).
Do human picks outperform system ones? Think Ed has written some articles on that.
Not sure why the directors are "pleased" with an offer of 430p for Ricardo (LON:RCDO. The shares were in 500p range a while back! No holding
Great piece of business by Science (LON:SAG) !!
Perhaps, but clearly got lucky with the bid.
Or did they...