Daily Stock Market Report (Wed 12th August 2026) - ATYM, BBY, SEE, HILS, EVOK

Hormuz progress? The Defence Minister of Pakistan says that the US and Iran are “close to some sort of arrangement” and that “things are shaping up in favour of peace”. But the oil price isn’t listening with November Brent crude still trading at $87 per barrel.
US inflation: This afternoon we’ll have US inflation data, as previewed in The Week Ahead on Friday. The July reading is expected to remain at 4.7%, a painfully high reading that reflects the strain in commodity markets. Core CPI, excluding food and energy, will be released at the same time and is expected to come in at 2.5%.
UK GDP is out first thing tomorrow, at 7am, so do keep an eye out for that.
Overnight market movements:
The FTSE is down 0.3% at 10,820
S&P 500 is flat at 7,735
Brent crude (November) is up 0.7% $87.20/bbl
Gold is up 0.5% at $4,390/oz
Bitcoin is flat at $63,700
Not much of interest today, let's leave it there and hope for more tomorrow! Cheers. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Balfour Beatty (LON:BBY) (£4.1bn | SR87) | H1 revenue +8% to £5,563m, adj pre-tax profit up 46% to £139m with adj EPS +51% to 21.7p. Order book £22.9bn (FY25: £22.7bn). 2026 outlook: increased guidance “following strong first half”. Now expect low double-digit growth from earnings-based businesses (previously high single-digit growth). | AMBER/GREEN = (Roland) A big increase in H1 underlying earnings was driven by a return to profitability for the US construction business and improved support services profits, primarily due to work on the UK’s power grid. Both trends could continue for a while yet and the broader group seems healthy enough, with a strong net cash position and stable order book. Although I feel the valuation is at the upper end of what’s reasonable, I have left my broadly-positive view unchanged today to reflect the evident momentum in the business currently. | |
Hill & Smith (LON:HILS) (£2.4bn | SR83) | H1 revenue +8% to $606.7m with adj pre-tax profit +7% to $96.1m and adj EPS +9% to 90.6c. Growth driven by “robust demand for infrastructure” in the US, offsetting weaker UK performance. Outlook: “underlying operating profit for FY26 is now expected to be modestly ahead of our previous expectations.” | AMBER/GREEN = (Roland) These results contain a few niggles and the group’s overall growth is being held back by weak conditions in the UK. However, the group’s continued US growth and strong profitability in that market is encouraging and I think the core qualities of this group remain intact. I think a broadly-positive view is a fair reflection of the stock’s High Flyer status and positive earnings momentum, so I’m making no change today. | |
Atalaya Mining Copper SA (LON:ATYM) (£1.53bn | SR91) | Long-time major shareholder Trafigura has sold 16.8m shares at 915p, raising c.£154m. “Following settlement of the Placing, Trafigura will have exited its shareholding in Atalaya Mining in full.” | AMBER = (Roland) [no section below] At the start of this year, Trafigura’s Urion Holdings vehicle controlled 21.9% of Atalaya shares. The commodity trading group halved its holding to 10.9% in February at 945p and has now completed its exit. Trafigura has been involved with this business since 2008 and I’ve previously estimated that it may have enjoyed a 10-bagger here. While we don’t know why Trafigura has chosen to exit Atalaya this year, the sale almost certainly locks in a healthy gain for this well-informed investor and seems consistent with my view that the upside opportunity here is potentially more speculative (based on the copper price) than it was previously. I don’t see any reason to change yesterday’s neutral view. | |
Yellow Cake (LON:YCA) (£1.40bn | SR86) | Yellow Cake has taken delivery of 1,160,766 lb of U3O8 from Kazatomprom at its Orano storage facility in France. The delivery completes the previously announced exercise of YCA’s 2026 uranium purchase option with Kazatomprom. | ||
Seeing Machines (LON:SEE) (£251m | SR22) | Secured a development contract with “a global industrial technology company focused on factory automation and human-robot interaction”. The initial program will deliver a proof-of-concept application for a factory automation environment. No financial details are provided. | AMBER = (Graham) | |
Evoke (LON:EVOK) (£205m | SR63) | H1 revenue flat at £887.5m with adj EBITDA -10% to £150.2m and adj pre-tax profit of £1.9m. Outlook: trading so far in H2 has been in line with expectations, with strong levels of engagement during the World Cup period. The acquisition of Bally’s Intralot is proceeding as planned with completion expected in Q4 26 or Q1 27. | TAKEOVER (Graham - I hold) I've been holding on to this for the moment but there is a decent chance that I will sell up at some point in advance of the planned takeover, so that I'm not left holding shares in Bally's Intralot. The takeover is expected to complete in late 2026 or early 2027. The Bally's StockReport exists here - it might even be worth my while looking into this Athens-listed stock to see whether holding a few shares in it, even temporarily, might not be the worst idea. Where I do have a strong view is that I'm very glad that this takeover is happening in the first place. Evoke's results weren't good even before the imposition of higher duties by Rachel Reeves, and they are still no good today. A mix of "exceptional" and "adjusting" items leaves a H1 pre-tax loss of £70m, and the company would still be loss-making even if you excluded all of the adjusting items. Like-for-like growth of 2% doesn't convince me that Evoke was capable of solving its debt problem; the levelrage multiple has increased to 5.6x. In the context of the higher gaming duties, it could have been a worse result and I applaud management for achieving even this, but the Bally's bailout was badly needed. | |
CLS Holdings (LON:CLI) (£197m | SR31) | EPRA earnings -32% to £10.9m with EPRA EPS -32.5% to 2.7p per share. Total accounting return of (9.5)% with EPRA NAVps -11.5% to 177.7p. Vacancy stable at 14.5%. Outlook: earnings under pressure from assets sales and “the departure of our largest tenant”. Now expects FY26 EPS to be 4.6p to 5.5p (previous consensus: 5.8p). | BLACK | |
Savannah Resources (LON:SAV) (£153m | SR36) | Signed three benefit sharing agreements with local communities that hold and manage communal lands. “These agreements say a great deal about how we want to develop this Project… This is not simply about securing access to land - it is about recognising that the baldios belong to the communities that have managed them for generations...” | ||
ECO Animal Health (LON:EAH) (£66m | SR92) | Signed a perpetual exclusive licence agreement with Vaxinano SAS for Vaxinano's sheep vaccine candidate against toxoplasmosis. The licence will enable ECO to complete the development of and commercialise the late-stage vaccine candidate. ECO will pay Vaxinano a modest upfront licence fee and a future development milestone payment as well as future royalty payments based on commercial product sales. | ||
Alternative Income REIT (LON:AIRE) (£57m | SR47) | “After five weeks, Glenstone has… secured negligible net acceptance of its Offer from AIRE Shareholders other than its own director.” Urges shareholders to not accept the Glenstone offer. | TAKEOVER | |
80 Mile (LON:80M) (£35m | SR6) | Jameson, East Greenland - following ongoing engagement with the Greenlandic authorities, the Company now expects the planned drilling programme to be delayed. This delay relates to the time required to complete the permitting and regulatory approval process. The Company has received a formal warning from the Government of Greenland concerning the landing of equipment at Nerlerit Inaat airport. | BLACK | |
Predator Oil & Gas Holdings (LON:PRD) (£27m | SR5) | The contract for the civil engineering works to prepare the Snowcap-3 drilling location to accommodate Star Valley drilling Rig 205 and the Production Facility Area has been awarded to NABI Construction (Trinidad and Tobago) Limited. Site works will commence immediately. | ||
Kazera Global (LON:KZG) (£17m | SR15) | Walviskop, South Africa: current planning targets a progressive ramp-up to monthly production of c. 30,000 tonnes of heavy mineral concentrate from the HMS plant, with production commencement slated for early 2027. Plant and equipment is being mobilised for anticipated arrival in South Africa during November 2026. | ||
Titon Holdings (LON:TON) (£11m | SR68) | …reflecting the delayed MVS (Mechanical Ventilation Systems) projects, lower WDH (Window and Door Hardware) sales and resulting lower margins, the Group now expects FY26 revenue of approximately £17m, representing growth of around 7.5%, with underlying EBITDA of approximately £0.3m. | BLACK (consensus revenue figure £18.3m). |
Graham's Section
Seeing Machines (LON:SEE)
Down 1% at 5.05p (£248m) - Graham - AMBER =
Two RNS’s to cover from this provider of driver monitoring systems:
FY2026 Trading Update and Q4 FY2026 Quarterly KPIs (yesterday)
Advanced Robotics Development Contract
Yesterday's trading update was well-received, with the shares up about 7%.
FY June 2026 revenues were up 45% to US $76.3m (these are adjusted revenues, but let’s not get too deep into the weeds).
H2 revenues were $52.9m as the business reached an inflection point, with nearly 70% of full-year revenues in the second half.
Cash at 30th June 2026 was $4.3m. I recall that this has historically burned through a lot of cash, but it didn’t burn any cash in H2. The company also points out that trade receivables and royalties owed increased from $11.6m (Dec 2025) to $25.3m (June 2026).
Adjusted EBITDA turned positive in H2 although the full-year result is still negative (minus $2m to minus $3m). That might not matter too much, if H2 is more representative of how the company is going to trade from now on.
The company’s explainer:
The significant improvement in Adjusted EBITDA reflects the operating leverage from higher Automotive royalty revenue, which carries a stronger margin profile than hardware-based revenue, combined with continued cost discipline across the business.
The EU has mandated camera-based driver monitoring systems as of July 2026. 8.2 million cars now use SEE’s driver/occupant monitoring system technology, vs. only 3.7 million cars 12 months ago.
Q4 KPI Highlights: production up 64% from the previous quarter, reaching 2.1 million units.
Trading and outlook: it’s all about momentum.
The Company exited FY2026 with strong momentum, particularly in Automotive, where royalty revenue growth accelerated through the second half. While it remains early in FY2027 and only a limited portion of the first quarter has elapsed, management continues to see the benefits of the operational and commercial progress achieved during H2 FY2026 and remains focused on sustaining that momentum through FY2027.
Convertible loan: discussions continue re: the refinancing of these notes, which mature in October in 2026.
Checking the most recent interim report to Dec 2025, the details were as follows:
Face value $47.5m
Conversion price 9.95p (so it looks like they aren’t being converted)
Interest expense as of Dec 2025: $16.8m
Yesterday’s update said “The Company has agreed indicative terms and is in an exclusive negotiation period to refinance the Convertible Loan Note obligation before its maturity on 4 October 2026.”
The interest rates on the existing notes are 11-13%. I wonder if they will be able to do better this time around? But then, aren’t they leaving it sort of late to get the refinancing done? For established companies, I like to see refinancings a year in advance of maturity, not a couple of months!
Today’s update:
Seeing Machines secures Advanced Robotics Development Contract with global industrial technology company
No numbers given, but SEE “has secured an Advanced Development Contract with a global industrial technology company focused on factory automation and human-robot interaction.”
It sounds interesting, but I have no idea what it might be worth.
Estimates: I don’t see any updated estimates this week, but the existing estimates from Singers were for the company to make a large loss this year (adj. pre-tax loss $17m) before swinging into profit in FY June 2027 (adj. PBT $5.8m).
In contrast to what the company reported in its trading update - adjusted FY26 revenues of $76.3m - Singers seem to be using unadjusted revenues, which are much bigger as they represent royalties upfront at the start of contracts. So the Singers FY2026 revenue estimate is $103.3m. This is seen dipping lower in FY27, to $99.1m, before rising strongly again in FY28.
Graham’s view
James put us AMBER on this in May and think AMBER is probably right at this point, too.
The growth that’s been achieved is truly impressive, with the swing into profitability apparently happening soon - hopefully in the current financial year.
However, I do think there are a couple of reasons not to be more positive on it just yet.
The first is that I’m a bit perplexed about the debt refinancing. In an ideal world, the company would have sorted that already. The more time passes, the more I wonder if the prospective lenders are driving a very hard bargain (a high interest rate) and/or if they have concerns that haven’t been addressed yet. Neither of those things would bode particularly well for the equity.
As I’ve said already, I like to see debt refinancings arranged very early. Seeing them done a year in advance is quite normal. These convertible notes have been outstanding since 2022, so I would have liked to see a refinancing in late 2025 if possible. But I guess the company hadn’t hit its inflection point by then. Now that point has been reached, hopefully we’ll get a successful refinancing announcement very soon?
My other concern is just around profitability and valuation. The ARR numbers here are really small ($15m) compared to the market cap. Quite a lot of work would be needed to understand the profitability that might be achieved in 3-5 years. A £250m market cap is not going to make sense in the short-term.
So for me, this is an AMBER: an interesting growth story, worthy of investigation, but I can’t get more enthusiastic than that at this stage.
Roland's Section
Balfour Beatty (LON:BBY)
Up 8% at 936p (£4.6bn) - Half-Year Results - Roland - AMBER/GREEN =
Strong first half performance delivering profitable growth. Full year performance expected to be slightly ahead of prior guidance.
Construction and infrastructure group Balfour Beatty is another FTSE 250 firm that’s in good shape at the moment. The group’s share price has tripled over the last four years, with momentum underpinned by a string of broker upgrades:
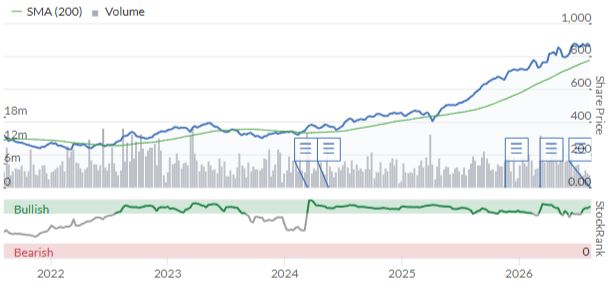
Today’s half-year results include another upgrade – albeit fairly small.
Half-year summary: “rising demand in US Buildings and UK power transmission”
Balfour Beatty’s headline figures for the half year show healthy revenue growth and rising (or falling) profits, depending on which profit measure you choose to follow.
The company’s accounts are slightly more complex than some others as it reports profits in three categories – earnings-based businesses, joint ventures and income from its £1.1bn investment portfolio of infrastructure and property assets.
For this summary, I’ve used the all-inclusive measure of pre-tax profit, as it’s representative of the overall shift in profits compared to H1 2025:
Revenue up 8% to £5,563m
Underlying pre-tax profit up 46% to £139m
Reported pre-tax profit down 2.3% to £129m
Underlying EPS up 51% to 21.7p
Interim dividend up 12% to 4.7p per share
There are also some positive KPIs:
Order book: £22.9bn (FY25: £22.7bn)
Average net cash up 33% to £1,616m
Trading commentary: the big increase in underlying pre-tax profit clearly needs some explanation.
Checking the company’s segmental results tells us that this increase has been driven by a return to profitability in the US and by much-improved margins in the Support Services segment. These two together account for a £53m positive swing in pre-tax profit, outweighing slightly weaker results elsewhere:
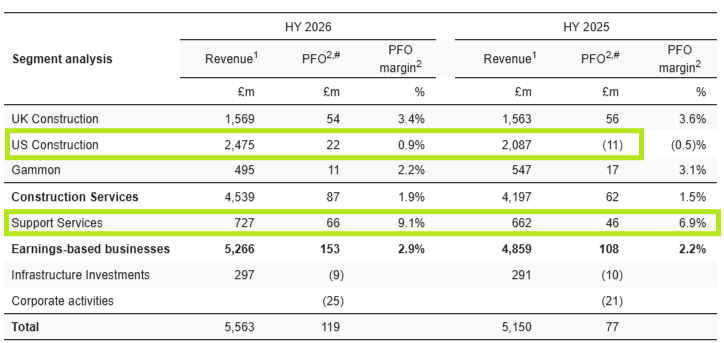
Source: Balfour Beatty H1 2026 results. Gammon is a 50/50 joint venture with Jardine Matheson in Hong Kong.
UK Construction: margins are rather higher in the group’s home market than in the US. This may be related to the heavy weighting towards public sector and regulated utility customers in the UK. Customer sectors include energy, defence and transport, as well as public services such as education and health.
Projects highlighted today include power grid work for SSE, a new school in Scotland and road and bridge works in Lincolnshire.
85% of orders are said to be on “target cost or cost-plus contractual terms” (FY25: 88%, FY24: 79%). This potentially mitigates the risk of expensive cost overruns – a perennial issue in this sector.
US Construction: when I covered Balfour Beatty’s 2025 results in March I noted “some localised problems in its US business” relating to cost overruns. Today management comments on “a much-reduced loss in US Civils” and notes that “further margin progress” is expected going forwards.
I don’t know how much further margins might improve in the US, but I can’t help what kind of return on capital the US construction business is generating (compared to the UK). Is the US really creating value for shareholders – or just adding volume?
Balfour Beatty’s quality metrics are notably lower than some others in this sector. Return on Capital Employed has averaged just 7% since 2020 – a figure that’s unlikely to cover the group’s cost of capital:
Support Services: this is essentially outsourced maintenance, with a focus on the energy, road and rail sectors. Strong growth in power transmission is said to have driven the improved performance – this appears to be a higher margin area than road maintenance.
Big profit adjustments! The wide divergence between underlying and reported profits also needs to be understood. One figure is rising while the other is falling…
While I don’t think there’s a fundamental problem with either measure of profit, the difference between them highlights one of the ever-present risks in this business – problems with historic projects:
| Period | Reported PBT | Main adjustment | Underlying PBT |
|---|---|---|---|
H1 2026 | £129m | £9m provision for Building Safety Act claims | £139m |
H1 2025 | £132m | £11m provision for Building Safety Act claims + the release of a previous £50m provision for problems with a Texas highway project originally completed in 2012. Following a court case, a multi-party settlement was reached, with Balfour’s share covered by its insurers. | £95m |
Resolving these issues – whether through repairs or legal settlements – requires actual cash outflows. Sometimes, these costs will be covered by insurers. Sometimes they may not be.
A conservative approach to profit is to look at the statutory figure each year and accept the lumpiness that will result. On the other hand, smoothed-out measures of underlying growth can also be useful.
I don’t think there’s a single correct answer. This is a situation where investors need to understand what the company is telling them and then form their own views.
As someone who is naturally a little sceptical about the quality of the construction sector as an investment, I lean towards reported profits. But that’s not necessarily the optimum approach – after all, I’ve missed the big rally in Balfour Beatty shares since 2022!
2026 Outlook
Today’s updated financial guidance is designed to be used by analysts who can plug the updated numbers into their financial models.
I think the main takeaway is that 2026 operating profits from earnings-based business (i.e. the group’s direct operations) are expected to increase by more than previously expected:
Updated guidance: “Low double digit percentage growth”
Previous guidance: “High single-digit percentage growth”
Finance income is also expected to be higher, at £35-40m, versus £28-32m previously. This reflects expectations for an increased average net cash balance of £1.5-1.7bn, from £1.3-1.5bn previously.
I don’t have a financial model nor access to broker forecasts.
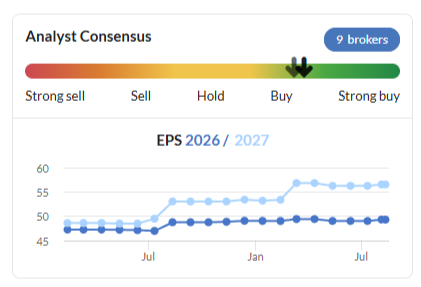
But guesstimating based on the above (and today’s share price action) suggests to me that earnings expectations may now be 4% to 6% higher than previously expected. Using this as a guide suggests EPS forecasts for this year could rise to c.52p.
If I’m right, this would help to close the gap that’s emerged between 2026 and 2027 forecasts over the last year:
Roland’s view
My estimates put Balfour Beatty on a forecast P/E of c.18x for 2026, falling to around 15x in 2027. This valuation is being underpinned at the moment by strong overall trading and expectations for double-digit EPS growth next year.
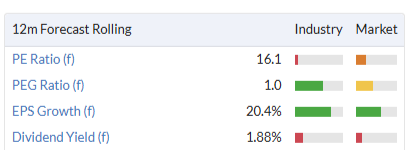
Personally, my feeling is that this valuation is at the upper end of what’s fair for this business. In particular, I wouldn’t be seduced by the large net cash position (around one-third of the market cap). In my experience, businesses in this sector need to run with large net cash balances in order to be able to fund working capital on big projects and reassure customers of their financial strength.
I would argue that Balfour Beatty’s dividend yield of 1.8% provides a more objective view of its valuation and of the level of truly surplus cash being generated. If earnings growth slows, I’d expect the valuation to ease as well.
Of course, this isn’t to say that the current strong run cannot continue. Strong structural demand in areas such as power transmission appear to be providing a welcome tailwind and any further margin improvement in the US could also lift profit estimates.
The StockRanks summarise the situation nicely with a strong MomentumRank and more average quality and value scores. I don’t see these scores changing all that much after today’s results:
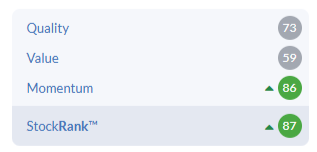
I was AMBER/GREEN on Balfour Beatty in March. I’m going to leave that view unchanged today out of respect for the evident momentum in the business at the moment. But I would be quick to turn neutral on any sign that profits could level out.
Hill & Smith (LON:HILS)
Down 2% at 3,030p (£2.4bn) - Half Year Results - Roland - AMBER/GREEN =
Hill & Smith owns a group of operating companies that provide products and solutions for “vital infrastructure and the built environment”. Examples include road barriers, bridge components and data centre flooring.
The company’s model is built around owning businesses that operate in “attractive niches with high barriers to entry”. Many of its products require certification or regulatory approval before they can be used in public infrastructure projects, for example.
Like Balfour Beatty, Hill & Smith isn’t obviously cheap and now generates much of its revenue in the US. However, my past coverage of this company has left me with the view that Hill & Smith is a higher quality business, with stronger, more defensible competitive advantages
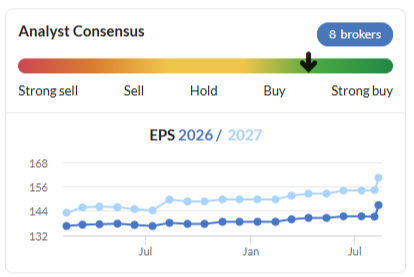
Today’s half-year results have been met with a shrug by the market, but the main takeaway is that full-year profit guidance has been upgraded, extending a run of upgrades over the last year:
Half-year summary: “sustained momentum in its larger US platform businesses”
Hill & Smith’s growth is being powered by similar drivers to Balfour Beatty. The company also reminds investors that its strategy of bolt-on acquisitions has the potential to drive additional growth:
Demand remains supported by structural investment in infrastructure renewal, grid modernisation, water infrastructure, data centres, and onshoring. We remain confident in our active and growing pipeline of attractive M&A opportunities aligned to our strategic framework.
Turning to the headline figures, H1 performance looks fairly strong. Once again, though, we see adjusted and reported numbers moving in opposite directions:
Revenue up 8% to $606.7m
Underlying pre-tax profit up 7% to $96.1m
Reported pre-tax profit down 16% to $69.2m
Adjusted earnings up 9% to 90.6c per share
Interim dividend up 7% to 25c per share
A laundry list of adjustments includes a number of items with cash costs, plus some non-cash entries suggesting past acquisitions may not have been as successful as hoped for. These adjustments are heavily weighted to the group’s UK operations:
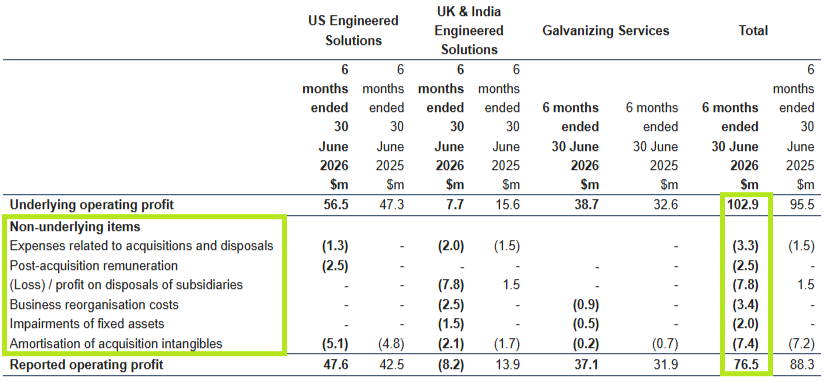
Source: Hill & Smith H1 2026 results
Turning to the cash flow statement for an idea of the cash impact of all these adjustments gives me a free cash flow estimate of £69m, before working capital movements and acquisitions.
That’s fairly close to the group’s underlying net profit of £71.8m for the half year, so my conclusion is that the majority of these items relate to past expenditure and/or are non-cash.
On balance there are too many adjustments for my liking, but they are all fairly standard and do not seem to be affecting the group’s cash conversion, so I’m prepared to take a neutral view on them.
Divisional trading: US up, UK down
Turning to the company’s divisional results shows a similar pattern to Balfour Beatty, with much stronger growth in the US than the UK.
US Engineered Solutions: revenue rose by 18% to £311.6m, of which 14% was organic growth. This generated an underlying operating profit of £56.5m, 20% higher than in H1 last year. The resulting 18% operating margin suggests strong demand and competitive positioning in this market.
Management highlights electrical grid infrastructure, data centre construction and industrial facilities and notes that some demand is being driven by “investment to upgrade and onshore vital infrastructure” – so there’s a geopolitical element.
UK & India Engineered Solutions: revenue fell by 12% to £144.2m, while underlying operating profit dropped 51% to £7.7m giving an underlying operating margin of just 5.3%. This division slumped to a reported operating loss of £(8.2)m due to accounting losses on subsidiaries that were sold during the period.
Management say that both road and building demand were weaker than in previous periods, although some improvement is expected in UK roads as the new Road Investment Strategy (RIS3) is delivered over the next five years.
Highlights include growth in demand for data centre flooring and perimeter security solutions, but these evidently weren’t enough to lift the overall top line.
The timing of a recovery sounds uncertain:
Whilst we anticipate a continuation of the challenging conditions in the UK during the second half of the year, we expect an improvement in margins over the medium term as a result of a combination of end market recovery and the benefit of measures being taken to strengthen our UK operations.
Galvanizing Services: this business operated in both the US and UK. Revenue rose by 13% to £150.9m while underlying operating profit climbed 19% to £38.7m, giving an underlying margin of 25.6%.
Revenue and volumes were higher in both the UK and US, although US growth of 16% was much stronger than the 6% seen in the UK.
Outlook
Given the strong first half performance, and with sustained momentum in our US businesses, underlying operating profit for FY26 is now expected to be modestly ahead of our previous expectations, with a small full year margin progression compared to the 2025 year.
Consensus earnings forecasts on the StockReport already appear to have been upgraded today:
FY26E adj EPS: 147.0p (prev. 141.3p)
FY27E adj EPS: 160.5p (prev. 154.4p)
These new estimates put the stock on a FY26E P/E of 20.6, falling to a P/E of 18.9x for 2027.
Roland’s view
I have to admit these accounts are slightly less impressive than I expected from this business. Impairment charges in 2025 have been followed by disposal losses and further restructuring charges, suggesting the group is not in optimum condition after a longish period under interim management (the current CEO started in late 2024).
Weaker demand in the UK is also disappointing, albeit probably largely outside Hill & Smith’s control: exposure to cyclical pressures and government spending plans is an inherent characteristic of this business.
Overall, I think the group’s core appeal remains intact. Selling essential products with high barriers to entry seems an attractive business model to me and today’s results suggest to me that the group’s quality metrics remain strong:
Trailing 12-month operating margin: 12.3%
Trailing 12-month ROCE: 16.6%
Today’s upgrade to earnings also confirms continued momentum in the valuable (and huge) US market.
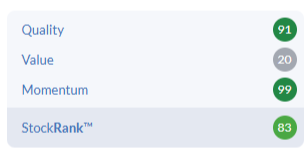
On balance, I think the StockRanks capture the situation nicely, with High Flyer status flagging strong Quality and Momentum scores, with weaker value:
The long-term share price chart here suggests that patient investors may be able to take advantage of period dips to capture a more attractive entry valuation.
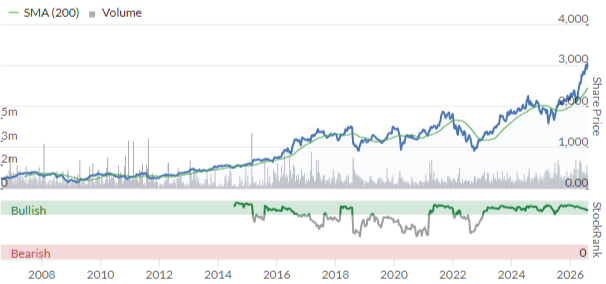
I don’t think the shares are cheap enough to justify a positive view today, but I am confident enough in the quality and long-term compounding potential of this business to leave my previous AMBER/GREEN view unchanged.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Shoe Zone rose by 11% today on no news?
Try yesterday's trading update and DMSR review.
Shoe Zone (LON:SHOE)
Especially the review :-)
All the best
Kazera Global (LON:KZG) V encouraging update from KZG with Chinese production partner SAI pencilling in 30ktpcm target from Walviskop compared to the old 6ktpcm targets mooted pre SAI. Starts to make KZG look pretty attractive even before the long anticipated 2A licence for the neighbouring 34x area plot.
Hi snowdrop
Velo3D (NAQ:VELO) up over +15% in pre market.
I do not hold.
Regards
Howard
Is there a Goodwin (gdwn) update due today.
Unlikely now. It was never confirmed today, just an algorithmic guess. Next best guess is next Tuesday
Don't Goodwin (LON:GDWN) put them out midday, sometimes?
Is "algorithmic guess" a fancy term for a PASWAG.
Pure And Simple Wild Ar*sed Guess
Results are out week commencing 24th August according to their site
this is what I see .
Yep but historically Year End update comes out approx. 15 days before Annual Report
Results and AR are confirmed directly by Goodwin (LON:GDWN) as being w/c 24th…I’d imagine the later timetable this year is to accommodate some additional newsflow..
To confirm - you’ve had this confirmed directly from Goodwin source?
I should add - I mean the date range being confirmed, not the additional news flow
Yes
Will Velo3D (NAQ:VELO) results beat feed across to Filtronic? Velo volatility is crazy but the space biz is clearly on the up!
Velo3D (NAQ:VELO) - believe this 'prints' (large-format laser powder bed fusion) complex machinery such as the SpaceX Raptor engines - freaking amazing.