Daily Stock Market Report (Tue 11th August 2026) - SPX, SHOE, BWY, CML, ATYM, RGG

Circular AI funding at Nvidia: the biggest financial news story overnight is that Nvidia is turning to major institutions for $500 billion to help fund AI infrastructure. The original statement can be read here.
Here’s the key paragraph:
Memorandums of understanding signed with six of the world’s premier financial institutions to create these partnerships aim to establish the first compute financing platforms of their kind at global scale to enable the AI infrastructure buildout across NVIDIA’s ecosystem, including leading frontier AI labs, enterprises and AI clouds. Under these strategic partnerships, NVIDIA will work with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to create dedicated pools of capital at significant scale at attractive rates for NVIDIA customers.
In other words, Nvidia is helping to arrange cheap debt for their AI industry customers, in order to further boost demand for Nvidia's processing power.
I would categorise this news story in the same way that I categorise the forthcoming AI IPOs, expected to be at eye-watering valuations, and the other very large fundraising deals we’ve seen this year, such as the $80 billion equity raise carried out by Alphabet recently. These are all signs of the financial industry treating the AI trade as a one-way bet, and therefore allocating vast sums of capital to it on extremely generous terms.
Overnight market movements:
The FTSE is unchanged at 10,860
S&P 500 is flat at 7,758
Brent crude (November) is up 0.3% $85.95/bbl
Gold is down 0.4% at $4,370/oz
Bitcoin is down 0.3% at $64,000
Wrapping it up there, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Intercontinental Hotels (LON:IHG) (£17bn | SR72) | H1 Global RevPAR +4.1%. Underlying revenue +6%. Adjusted EPS +13% (274.7 cents). “We remain on track to meet full year consensus profit and earnings expectations. We are also confident in the successful delivery of our growth algorithm…” | ||
Spirax (LON:SPX) (£5.7bn | SR80) | Revenue +5% (and +5% organically). Adjusted operating profit +8% (+6% organically) to £171.1m. On track to deliver full year guidance: mid-single-digit organic revenue growth and organic margin progress. | AMBER/GREEN = (Roland) These half-year figures look solid enough to me, with sales growth ahead of global industrial production and improving profitability. Management guidance reiterates expectations for a stronger H2 as the orderbook converts to deliveries and industrial activity strengthens (modestly). The market appears to be disappointed by the lack of an upgrade today, but I wouldn’t be too concerned if Spirax can continue to deliver on current expectations. The only question mark for me is on valuation. While this is a quality business, it’s not cheap enough to persuade me to turn positive, so I’m leaving my view from March unchanged today. | |
Lion Finance (LON:BGEO) (£5.4bn | SR79) | Operating income before cost of risk +19.6% y/y. Profit +17.3% to GEL 1203.8m. ROAE of 27.2%. Key targets for the medium term remain c.15% annual growth of the loan book, 20%+ return on average equity, and 30-50% payout ratio. | ||
Bellway (LON:BWY) (£2.36bn | SR47) | FY July 2026: Completions +10.8%, adjusted operating profit around £320m (2025 - £303.5m). Net cash £157.7m. Outlook: Our industry continues to face challenging headwinds, increasing the risk of a more prolonged period of softer customer demand alongside renewed inflationary pressure on build costs. | AMBER = (Roland) [no section below] Comparing today’s FY update with Bellway’s previous update on 9 June highlights a couple of points I think are worth flagging up. Total completions of 9,695 homes is 11% higher than last year and is also ahead of June’s guidance of 9,300-9,500. However, guidance for underlying operating profit of c.£320m is at the bottom end of the £320-330m guidance range provided in June. I think the factor that connects these two numbers is “a strong conversion from our bulk sales pipeline”. Big housebuilders rely on volume. To me, it looks like Bellway may have pushed a fairly large number of homes out through lower-margin bulk sales in June and July in order to offset weak private sales and avoid another profit warning. I don’t know when the market will turn, but I view the 30%+ discount to NAV as a value signal that should eventually deliver a return when higher-margin private market demand improves. In the meantime, year-end net cash and ongoing share buybacks (below NAV) are a further attraction. However, Bellway’s Contrarian styling and low MomentumRank are a reminder that patience may be required. I’m staying neutral for now. | |
International Workplace (LON:IWG) (£1.77bn | SR25) | H1 revenue +6%. Overheads expected to reduce significantly in H2. Overheads expected to reduce significantly in H2. | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.53bn | SR86) | Copper production of 13.5 kt in Q2 2026 and 23.4 kt in H1 2026. FY2026 guidance is maintained for production, Cash Costs and AISC. | AMBER = (Roland) [no section below] I moved our view on this Spanish copper miner to neutral in April after ATYM reported weather-related disruption to production. I speculated that there was an increased risk of disappointment if either production or the price of copper weakened further. So far, it seems my caution may have been overstated. Today’s update leaves FY26 production guidance unchanged and the copper price has risen by c.10% since April. Looking at today’s results, earnings of €0.554 per share suggest a modest H2 weighting will be needed to hit consensus of €1.20, but this seems achievable enough to me if the price of copper remains stable. However, I’d note that the mid-point of production guidance is only 2% higher than 2025 production. With the stock not obviously cheap, in my view, I’d argue that further upside is dependent on future growth or higher copper prices. This increase speculative element means I’m going to stay neutral today. The StockRank’s HighFlyer styling and MomentumRank of 99 also highlight the importance of continued momentum. | |
Genuit (LON:GEN) (£770m | SR55) | Revenue +3.4%. Underlying operating profit down 1.6% (£43.9m). Statutory operating profit down 30.1% (£26.2m). “Genuit took decisive and responsible action in the first half of the year in the face of challenging market conditions… Our expectations for the full year remain unchanged.” | ||
Thor Explorations (LON:THX) (£395m | SR94) | 17,050 ounces of gold sold in Q2 2026 with an average gold price of US$4,554 per oz. FY2026 production guidance of 75,000 to 85,000 oz maintained, while AISC guidance remains at US$1,000 to US$1,200 per oz. | ||
Altyngold (LON:ALTN) (£287m | SR64) | 15.6Koz of gold produced, up 23.3% from Q1. Remains on track to meet market guidance of 52-55Koz for the full year. | ||
Public Policy Holding (LON:PPHC) (£248m | SR18) | Revenue +7.3% over Q2 2025. Organic growth 3.9%. GAAP net loss of $3.7m. Adjusted EBITDA of $12.3 million, down 4.4% over Q2 2025. Outlook: For full year 2026, PPHC is raising its guidance to reflect the expected in-year contribution of the acquisitions completed and announced in YTD 2026. Organic growth guidance unchanged at c. 5%. | ||
Seeing Machines (LON:SEE) (£233m | SR21) | FY26 adj revenue +45% to $76.3m, in line with exps. H2 adj revenue of $52.9m vs $23.4m in H1. Positive adj EBITDA for H2, although FY26 adj EBITDA is still expected to be -$2m to -$3m. | ||
Afentra (LON:AET) (£175m | SR38) | Successful oil discovery at Pacassa SW, with net pay of 136m and reservoir quality supporting the pre-drill estimate of 5,000 bopd (gross). Production re-established at Impala-1 at c.3,000 bopd (gross) following “light well intervention”. | ||
Aptitude Software (LON:APTD) (£108m | SR42) | Kenneth Paqvalén will join as CFO from 21 September 2026. He was previously CFO at Napier AI, R3 and Matillion. | ||
Rentguarantor Holdings (LON:RGG) (£80m | SR36) | Revenue +250% to £3.39m with positive adj EBITDA of c.£110k and adj operating loss of c.£11k. Contracts completed +179% to 3,703 with average contract price of £915 (H1 25: £731). | AMBER/GREEN = (Graham)
This is one of the most exciting growth stories I cover in this report. If you judge it purely on the current numbers, the valuation is bonkers. The ValueRank is only 4, with a market cap of 10x current-year sales. However, if you’re willing to look further ahead, the valuation is much less extreme. For me, the bottom line is that I wouldn’t want to bet against a business that’s growing like RGG is, and that is doing so from a position of strength. It’s well-capitalised and its founder-CEO, who has decades of property investment experience, is also the largest shareholder. | |
CML Microsystems (LON:CML) (£46m | SR52) | CML has started FY27 with “encouraging momentum” following a positive Q4. Revenue so far this year has been in line with expectations, while order intake has been ahead of expectations. A return to operational profitability now looks likely to be achieved earlier than previously expected. | AMBER ↑ (Roland) Today’s update is brief and broker forecasts suggest CML will still report a full-year loss this year. However, the company’s commentary on improving demand and stronger-than-expected order intake seem positive. A return to profitability could lead to a much stronger performance in FY28. Although broker forecasts for the current year are unchanged today, I don’t see any reason to maintain our previous AMBER/RED view, so am up one notch to neutral today. CML doesn’t have wide coverage and is quite closely held, but I think it could be an interesting situation to research in more detail. | |
Hemogenyx Pharmaceuticals (LON:HEMO) (£44m | SR2) | Hemogenyx Pharmaceuticals has entered into an agreement with Cellin Technologies for Cellin to become the company’s exclusive manufacturing and operational partner for HG-CT-1 in Estonia for five years. The technology transfer is anticipated to take approximately four months, followed by an approximately 90-day regulatory review of the Hospital Exemption dossier. | ||
Shoe Zone (LON:SHOE) (£28m | SR88) | Trading was positive in July. As a result, cash at 25 July was c.£7m ahead of budget. FY26 expectations are unchanged for an adjusted pre-tax loss of no greater than £1m. Company intends to carry out a share buyback for up to £3.47m, to be completed by 26 October 2026. | AMBER/RED ↑ (Graham) | |
Sealand Capital Galaxy (LON:SCGL) (£28m | SR9) | Sealand has acquired a c.2% interest in Wanel Capital Limited for £450k in cash. Wanel is a regulated Web3 digital financial infrastructure business with operations in Hong Kong and Europe. | ||
Harena Rare Earths (LON:HREE) (£19m | SR14) | The Company has signed the Cahier des Charges Minières (CCM) with Madagascar's Ministry of Mines. The CCM framework unlocks the next development phase, including the Proof of Concept pilot plant and an onsite laboratory, alongside continued technical studies and project development activities. | ||
Genedrive (LON:GDR) (£18m | SR14) | Neonatal Intensive Care Unit patient recruitment in the PALOH-UK programme has been completed, with nearly 6,000 babies in neonatal care receiving the Genedrive MT-RNR1 ID test. Clinical cohort analysis is underway with publication expected in scientific literature around October 2026. | ||
Oriole Resources (LON:ORR) (£16m | SR29) | Further results from early-stage exploration have been received for the Niambaram and Ndom licences. Regolith mapping and rock-chip sampling over 2021 anomalous gold-in-soil samples at Niambaram has identified three main mineralised areas of multi-gramme gold anomalism, with results up to 28.40g/t Au. | ||
Cellbxhealth (LON:CLBX)(£15m | SR16) | Independent peer-reviewed study supports Parsortix use in GBM. CTC-enriched GBM samples reflect matched tumour genomics. Findings suggest potential in GBM diagnosis and monitoring. Study aligned with CelLBxHealth own research data on GBM patient samples. |
Graham's Section
Shoe Zone (LON:SHOE)
Up 21% at 74p (£34m) - Trading Update & Share Buyback Programme - Graham - AMBER/RED ↑
A tiny but powerful trading update:
Shoe Zone is pleased to announce that trading has continued positively throughout July and as a result of this, cash and equivalents as at 25 July 2026 stood at approximately £7.0m ahead of original budget. The Board continues to expect an adjusted loss before tax* of no greater than £1.0m for the financial year ending 3 October 2026.
With a market cap as low as Shoe Zone’s, a £7m cash swing is a very big deal.
There is a second RNS:
Following its trading update released earlier today, Shoe Zone announces that it intends to conduct a share buyback programme of ordinary shares of £0.01 each in the capital of the Company… up to a maximum aggregate consideration of approximately £3.47 million.
Shares bought back “will be initially held in treasury and then cancelled periodically.”
Estimates: many thanks to house broker Zeus for publishing on this today. They have left adj. PBT forecasts unchanged at minus £0.5m (FY September 2026) and then +£0.5m (FY September 2026).
In terms of cash, Zeus already raised their net cash estimate for SHOE by £6.1m, after the July trading update. They raise their estimate by a further £1.7m today, getting an FY 2026 net cash estimate of £11.4m, and this is after the buyback. Without the buyback, they’d get a net cash position of £14.8m. That's more than half of last night's market cap.
Graham’s view
With the company’s profit/loss guidance and forecasts unchanged, the unexpected additional cash appears to be coming primarily from inventory control.
Checking the July trading update, I see that the company’s sales received a boost from their “warehouse closing down sale”, along with favourable weather. These sales appear to have very successfully cleared out inventory, resulting in a big cash boost.
Going further back, I see that the cash performance of the business has been improving. At the most recent interim results (H1 to March 2026), there was an inventory position of £28m (down from £34.5m a year earlier). Inventories had been as high as £38m in September 2024.
So the inventory movement alone had already freed up £10m. Taking any seasonality out of the picture, since March and September will have different requirements, the year-on-year benefit of lower inventory was £6.5m between March 2025 and March 2026, and that was before the warehouse closing down sale and the sales boost from stronger weather.
But I think there are a few things to highlight, before we get too excited.
Firstly, the overall revenue growth here is not amazing. Sales were £149m in 2025. Sales are expected to come in at £143m in the current year, and then £143m again in FY 2027 (Zeus have revised down their sales forecast for FY 2027 today, as it’s one week shorter than FY 2026).
The July trading update did see revenue forecasts increased, but only by a couple of percentage points. And there is no increase to revenue forecasts arising from today's update.
Secondly, the P&L situation remains unexciting. The company is now trading around breakeven, and is expected to remain around breakeven next year. A better cash position doesn’t mean that the company is suddenly profitable - it’s simply holding less stock than it did before.
The decision to send this cash boost directly to shareholders in the form of a buyback is a bold move, and it’s not one that I’d typically recommend for a loss-making company that isn’t planning to liquidate.
However, it’s worth mentioning that Shoe Zone is a family business run by two brothers (the CEO and Chairman) who together own the majority of the shares. They have both been involved in the business for decades.
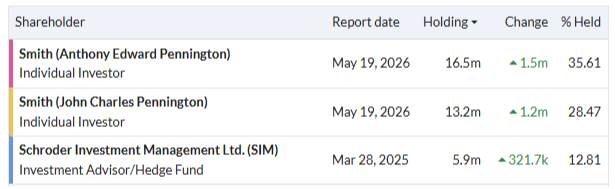
In that context, the share buyback becomes more interesting - if we can trust the judgement of the Smith brothers and the Board, then perhaps the buyback is reasonable and is a good sign that the shares are undervalued? They wouldn’t recklessly endanger the financial security of the business they’ve been managing for so long, would they?
This buyback for c. £3.5m will spend only about a quarter of the company’s expected year-end net cash position (prior to the effect of the buyback), while potentially reducing the share count by about 10%, depending on the price achieved. Putting it that way, it sounds like a smart move.
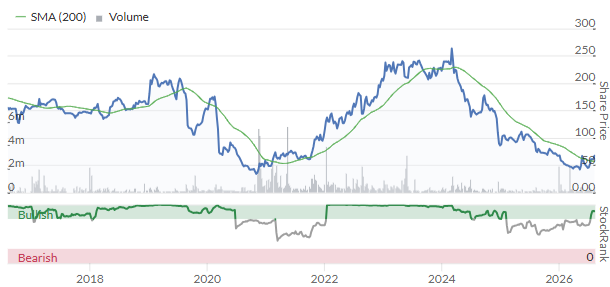
The SHOE chart is interesting. These shares traded over 250p as recently as March 2024:
Putting it all together, I’m inclined to raise our stance on this by one notch, to AMBER/RED.
My reasons are:
The positive July trading update did boost forecasts, and we haven’t accounted for that yet.
The strong cash position covers a large percentage of the market cap.
The Smith brothers are both highly aligned and highly experienced managers of the business.
My reasons for not going any further than AMBER/RED are:
It's obviously still loss-making. It’s still operating in a highly competitive, commoditised industry with zero barriers to entry. It’s not what we might call a “high-quality” business, and its overall financial performance leaves a lot to be desired right now.
The recent cash boost arises from inventory control. That’s not a bad thing, but it is difficult to repeat.
While I’m inclined to trust the decision-making of the managers here, this is a retailer with plenty of lease liabilities (£34m at last count) and so having lots of cash on hand is not really a luxury, but a cushion against hard times.
So in summary: SHOE has issued some really encouraging news in the last few months, and I’m happy to upgrade our stance, but only by one notch at this stage.
Rentguarantor Holdings (LON:RGG)
Up 4% at 54.9p (£83m) - Unaudited interim results - Graham - AMBER/GREEN =
RentGuarantor (AIM: RGG), a leading provider of rent guarantee services, which includes property protection, to tenants and landlords in the UK private rental sector, is pleased to announce its unaudited interim results for the six months ended 30 June 2026 ("H1 2026" or the "Period").
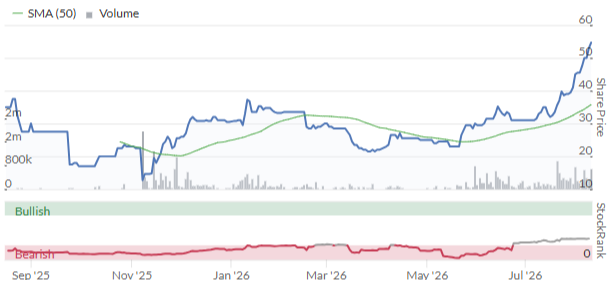
I tentatively turned AMBER/GREEN on this in June and the share price is up by over 70% since then.
It has doubled in just a few months:
Today’s results are pretty exciting, as you might expect, as it grows from a small base:
H1 revenue +250% to £3.4m. Applications more than doubled and the average size of each contract increased from £731 to £915.
Adj. EBITDA improves from a £124k loss to a £110k profit.
The H1 operating loss improves from £440k last year to only £10k, effectively at breakeven.
I think this bit might be key: “Signed a total of 367 partnership agreements with letting agent entities or letting agent groups (H1 2025: 224).”
The relationship between RGG and letting agents puts RGG right in front of landlords and tenants, as a solution to the new environment where evictions, including in cases where there are rent arrears, has become more complex. Note this, too:
We also announced a strategic partnership with the National Residential Landlords Association, or NRLA, affording RentGuarantor visibility to its 111,000-strong membership as we jointly create a co-supported education and training programme, aimed at helping landlords to manage risk and protect their rental income.
High visibility among their target audience, combined with the fact that RGG are solving new, serious challenges in the rental market, helps to explain the rapid growth they are experiencing.
Fundraising: £1m raised in June 2026, and another £2.15m received from warrant holders since then. Bank balance now c. £10m, a very healthy warchest for a company of this size.
AI: it’s obligatory for companies to explain their AI strategy in the current environment. RG say they are developing AI tools that “could illustratively have the potential to increase capacity for processing tenant documents to approximately 100,000 contracts per year by 2029”. (Context:3,700 contracts were completed in H1.)
Outlook: “The results have given the Board confidence in the Company's ability to meet market expectations on the financial performance for the year.”
Dividend: considering the growth opportunity and the fact that RGG has recently been fundraising, I don’t think a dividend makes a lot of sense here, but they say they “will consider the introduction of a dividend policy as part of its assessment of the Group's full-year results and future capital requirements.”
Graham’s view
This is one of the most exciting growth stories I cover in this report.
I’ve been AMBER/GREEN (moderately positive) on it, and I’m inclined to leave that stance unchanged after today’s in-line outlook statement.
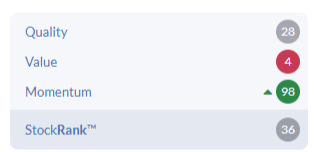
If you judge it purely on the current numbers, the valuation is bonkers. The ValueRank is only 4, with a market cap of 10x current-year sales. The StockRanks take a fairly dim of view this:
However, if you’re willing to look further ahead, the valuation is much less extreme.
Estimates: For FY June 2027, Cavendish are forecasting PBT of £4.6m, rising to £8.5m in FY 2028. The valuation multiples would start to look very attractive, if these numbers materialised.
These estimates should of course be taken with a barrel of salt, as it’s impossible to predict the growth of early-stage businesses with such precision.
For me, the bottom line is that I wouldn’t want to bet against a business that’s growing like RGG is, and that is doing so from a position of strength. It’s well-capitalised and its founder-CEO, who has decades of property investment experience, is also the largest shareholder.
I’m not going fully GREEN because clearly it has a lot of work to do, if it’s going to grow into this valuation. But a moderately positive stance continues to make sense to me. It's worthy of further research, for growth-oriented investors.
Roland's Section
Spirax (LON:SPX)
Down 8.5% at 7,000p (£5.1bn) - Half Year Results - Roland - AMBER/GREEN =
In March this year, I upgraded our view on this industrial group to be moderately positive. That view hasn’t yet been reflected in share price action, but I’m interested to see if the latest results from this group – a global leader in steam management solutions – justify my confidence.
Half-year results: “first half in line”
Today’s half-year numbers haven’t received a very warm welcome from the market, but my initial impression is that they are relatively positive and suggest the business may be regaining some momentum:
Revenue up 5% to £863.8m
Adjusted pre-tax profit up 9% £152.3m
Reported pre-tax profit up 54% to £135.4m
Adjusted EPS up 9% to 150.0p
Interim dividend up 3% to 50.4p per share
Net debt down 6% to £618.2m (1.6x leverage)
Revenue growth of 5% is consistent with the 5% organic growth rate reported last year and is ahead of global industrial production (IP) growth of 1.8%.
Trading commentary: “strong orderbooks”
All three of the group’s divisions saw sales growth during the first half:
Steam Thermal Solutions (STS): revenue up +1% to £419.8m
Electric Thermal Solutions (ETS): revenue up 10% to £232.9m
Watson-Marlow Fluid Technology Solutions: revenue up 8% to £211.1m
This doesn’t seem a bad result to me against a backdrop of rather weak global industrial growth:
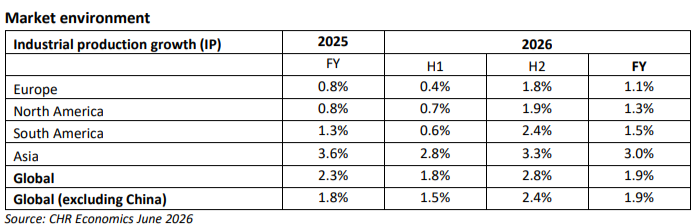
Source: Spirax H1 2026 results
The table above suggests that IP growth is expected to improve in H2 this year. This is reflected in the company’s expectations for H2-weighted profits and higher margins in H2, driven by the core STS business, where headwinds in China are easing:
In STS, the unwind of the strong orderbook at the end of the first half is driving sales as anticipated and we expect second half sales growth to be ahead of the first half. We also expect margin to be higher than the first half, consistent with our typical 45%:55% weighting of operating profit. This reflects operating leverage from higher second half shipments driving a full year margin broadly in line with that of 2025.
Strong sales growth in ETS benefited from exposure to the (booming) semiconductor sector, which contributed a higher proportion of sales in H1 than during the same period last year (2025: 13%).
Performance in the Watson-Marlow business also sounds promising. This division has exposure to the biotech and pharmaceutical sector, which is driving growth:
WMFTS organic sales growth was 7%. In Biopharm, new order intake remained ahead of sales, with Q2 orders reaching the highest level of any quarter since the COVID-related peak of 2021 and ahead of pre-COVID levels, underpinning continuing sales growth
WMFTS is also the most profitable division, with an impressive 25%+ operating margin. However, all three parts of the business enjoy (adjusted) margins that I see as suggesting strong market share and durable competitive advantages:
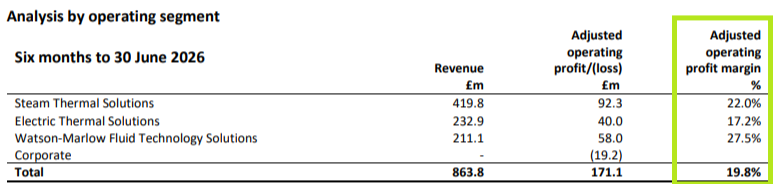
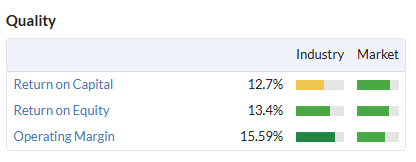
Profitability is recovering: these results show a welcome improvement in group-level profitability, after a period of cost-cutting and restructuring. On a statutory basis my sums suggest the Spirax’s H1 operating margin improved to 17.9%, compared to 15.6% for FY25.
More importantly, perhaps, I estimate return on capital employed of 14.2% for the 12 months to 30 June, with a return on equity of 15.9%. These figures are all comfortably ahead of the 2025 numbers:
Why I’m not adjusting ROCE: I should say that Spirax provides its own adjusted measure of return on capital employed, which it reports at 35% for H1 2026. This relies on using adjusted operating profit together paired a narrower “more operational” definition of capital employed than the standard calculation I use. Notably, it excludes the impact of past acquisitions (e.g. goodwill).
Calculating ROCE based on an idealised alternative reality doesn’t seem that helpful to me as a potential investor.
Fortunately, Spirax also reports return on invested capital (ROIC), which includes the impact of acquisitions and disposals. ROIC was 13.3% in H1 – much more closely aligned with my view on ROCE. In my view, this is a more useful metric for investors to follow.
Creating value for shareholders: despite my comments above, I see Spirax as having an attractive level of profitability, with a track record of creating value for shareholders over time. The stock’s book value has risen at a compound average rate of 10% annually since 2016 despite a slowdown since 2022:
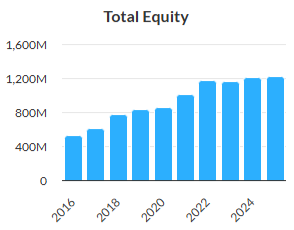
Building book value while maintaining attractive returns on equity is the core mechanism behind compound returns – mathematically, profits must rise over time.
Outlook
Commentary from CEO Nimesh Patel today sounds confident to me (my emphasis):
Continuing momentum in end markets such as Semicon and Biopharm as well as strong orderbooks, underpin our expectations for second half revenue and profit growth and we are reiterating our full year guidance.
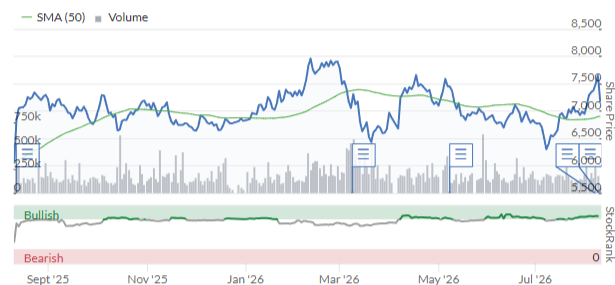
A c.9% share price fall on the back of in-line guidance seems a little harsh to me for a business of this quality, but perhaps the market was pricing in an upgrade after a long period of in-line guidance:
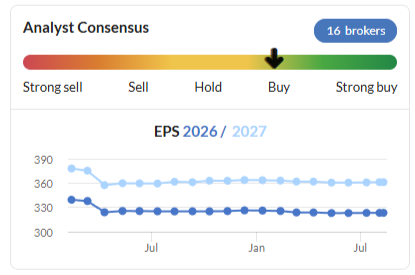
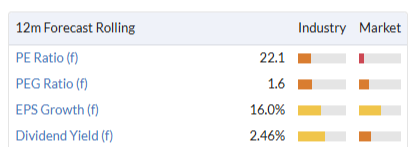
It’s probably fair to say that Spirax does not look especially cheap, despite its above-average quality:
Roland’s view
This is a business I’ve often admired and considered as a possible long-term investment. Long-term shareholder returns have been excellent, but this was also an example of a quality mid-cap that became priced to perfection at the end of the zero interest rate era:
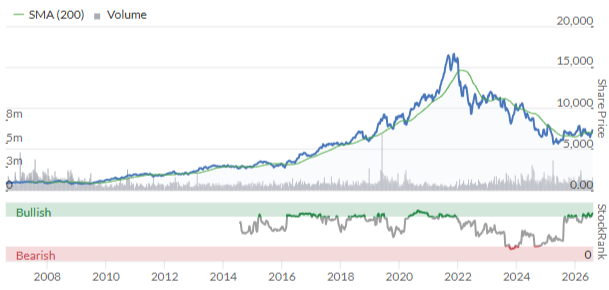
Rising interest rates combined with a slowdown in demand to trigger a brutal de-rating. Spirax is still down by more than 50% from its 2021 highs.
I haven’t done the research needed to gain an in-depth understanding of this business and its end markets. But today’s results show positive sales growth at improved margins and flag up the expectation of a stronger H2.
On balance, my view that the outlook is improving here is unchanged. The only question mark for me is whether growth will be strong enough to support and extend the current valuation.
The StockRanks suggest a similar view, with High Flyer styling reflecting strong quality and momentum but a weak value score:
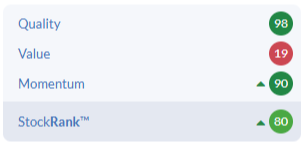
Spirax isn’t cheap enough for me to turn fully positive, but I’m comfortable leaving my AMBER/GREEN view unchanged today.
CML Microsystems (LON:CML)
Up 5.5% at 290p (£48m) - AGM Statement - Roland - AMBER ↑
We haven’t looked at this radio frequency electronics firm for a year, since it reported a £7m sale of surplus land.
The shares have gone nowhere since then and the business has remained loss-making. But today’s AGM Statement suggests a return to profitability may now happen sooner than expected.
AGM update: “encouraging momentum”
CML’s financial year ends on 31 March, so today’s FY27 commentary relates to the period from 1 April onwards:
CML has entered FY27 “with encouraging momentum following a positive final quarter [to FY26]”
The company is seeing “firmer demand across all key market verticals”
Year-to-date revenue is in line with expectations, but order intake is ahead of expectations.
The Board remains confident in its growth strategy and a return to operational profitability now looks likely to be achieved earlier in the current financial year than previously expected.
For some more clarity on the exact meaning of this statement, I checked for any updated broker notes.
Outlook & Updated forecasts: Broker coverage for CML is limited – the company qualifies for our Neglected Firms Screen, which flags up under-researched stocks.
However, CML’s house broker Shore Capital does maintain forecasts and has kindly made its latest note available on Research Tree today.
Shore appears to be responsible for the forecast shown on the StockReport and its estimates are unchanged today:
FY27E revenue: £23.9m
FY27E adj EBITDA £4.0m
FY27E adj pre-tax profit: £(0.1)m
FY27E adj EPS: (0.2)p
My conclusion is that today's AGM statement is guiding for a return to run-rate profitability at some point in the current year, but is not indicating a return to full-year profitability in FY27.
Roland’s view
CML is quite closely held and fairly illiquid. I note that MD Chris Gurry and another family member appear to control c.15% of the stock. There are also a couple of other named individual investors with big holdings.
A look at the long-term chart suggests this business is somewhat cyclical:
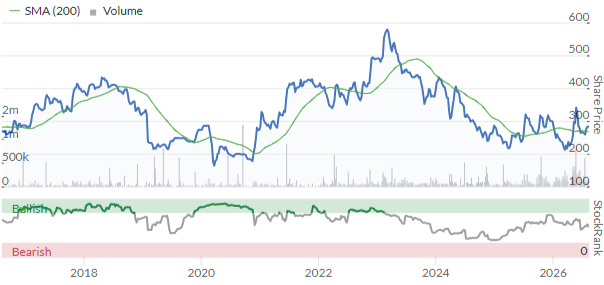
owever, CML had a c.£13m net cash position at the end of last year and has paid an 11p dividend for a number of years, providing a c.4% yield. While uncovered by earnings, this payout (c.£1.8m/yr) does look affordable against net cash.
I suspect that this stable dividend reflects the heavy insider ownership – not necessarily a bad thing, in my view.
One point that could be worth noting is that Gurry added to his shareholding in March, spending c.£52k on stock at 210p. Based on our records, it’s the first time he has purchased shares since August 2012. Make of this what you will.
Shore Capital’s latest note comments that CML has exposure to “attractive structural growth markets” that include 5G, Industrial IoT, satellite communications and defence.
I haven’t done the research needed to understand this business. I don’t know, for example, if there are any similar areas of exposure to Filtronic.
However, the positive tone of today’s update and the prospect of revenue growth and a return to profitability suggests to me that this situation could be worth further research.
I certainly don’t see any reason for us to maintain a negative view any longer, so I’m going to move CML up to neutral today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
a little nerdy side fact…. John Baron was one of Trumps pseudonyms back in the day…..
I wonder if Circular Funding has any parallel with a Circular firing squad.
People keep saying bull market, FTSE AIM 36% down last 5 years, FTSE250 4% gain last 5 years...
Shoe Zone (LON:SHOE) just my kind of investment (I hold). A previous market darling now down on its knees (or soles) but with canny operators at the helm who have just bought a big chunk of shares around 50p. The bad news is all in and from here things should start to improve for this cyclical retailer.
Careful DD
You will upset Graham
He thinks it’s a near red???!!!
All the best
Shoe Zone (LON:SHOE) is a good example of my tactic of selling on the first profit warning and then monitoring for a buy opportunity on the first signs of a turnaround working very well.. That tactic missed the subsequent near 70% share price fall after further profits warnings.
The update today, and from memory the previous one, hints at better times ahead. Far better surely, if chancing a buy now, to be doing so after saving ourselves from that 70% share price fall, than if still holding at a big loss and wondering whether buying now risks throwing good money after bad?
I realised the folly of holding on to shares that disappoint when doing that with Taylor Wimpey (LON:TW.) (and others) all the way down to 2p after the banking crisis in 2008. I nearly bought more Taylor Wimpey (LON:TW.) then, but thought why take the risk and decided against. I wouldn’t have hesitated if I had sold before losing almost all my stake. Taylor Wimpey (LON:TW.) went on to multi bag from 2p in no time.
After rising 38% yesterday and another 44% today Thruvision (LON:THRU) is still not at a £10mm MCap which would get it into discussion here, but you may want to keep an eye on it.
Not for nothing is it a long term resident of my Serial Disappointers folio, but there recently have been several distinguished alumni (Hardide, Tekmar, Ensilica, and of course SRT) that have moved up to greater things, so a flowering here cannot be dismissed as a possibility.
A Stockrank of 17 tells you where things are now but still……interesting.
Well John Baron tells Twitter he bought 100ks worth this morning which has caused a bit of a flap on the bulletin boards and had no doubt created extra demand today.
And according to Stocko - Major shareholders - Schroders have a big interest - I cannot imagine there are many stocks below £5m value with such institutional holders.
Tpximpact Holdings (LON:TPX)
The RNS was a response to this link which is open for all to see being posted on ADVFN on 7/8 by spdevjani.
The contract is awarded but not yet signed.
The huge NVIDIA (NSQ:NVDA) financial action reported today may be increasing the risk of contagion from any slowdown in AI growth rates. It's obvious that growth has to slow down sometime!
I'd welcome others' views. I wonder whether Ed's calculations about StockRanks considers second derivatives.
Thanks for the link. Great article … as it backs up my pre-existing biases! Just think this must be a bubble, but I didn’t realise it's a real estate bubble pretending to be a tech one. It seems that OpenAI and Oracle may be the canaries in the coalmine as the rate of fundraising increase goes negative whilst the amount being raised still increases.
The 2008 sub-prime mortgage bubble was financed against houses which have a long lifespan and can be used again after the previous owners defaulted. This speculative property bubble is financed against microprocessors, which are quickly obsolete, and enormous sheds with no obvious secondary use.
The NVIDIA financing announcement looks like a desperate attempt to keep the merry-go-round spinning for a little while longer. Trump may take a stake in OpenAI to keep everything afloat until after the mid terms.
It seems that Wiley Coyote is still not looking down. When he starts to fall and he pulls the ripcord maybe a massive server rack will pop out of his parachute pack.
I’ll definitely be looking at what stocks did well after 2008, not 2000.
What you have to factor in the huge future need for AI and processing power - yes at some stage supply and demand mismatch may moderate and go into reverse - but i would be surprised if there isnt a real need for all these data centres that are being built - AI is going to be front and centre of everything - so to me if its costs ref building data centre - that kinda akin to setting up the infrastructure for everything so that loads of users can pay to hook up to the grid data. I would worry more about the commodity manufacturers rather than the companies running the data centres - albeit i suspect the big boys like nvidia can look after themselves.
Greggs (LON:GRG) Not in the news today but was interested to look them up after returning from a few days travel, and seeing the numbers of people queuing for Greggs at motorway services. The SP has been falling since the beginning of the month - not so long but it's now 11 days yet the Momentum rank is still showing 92 and rising. Surely the stock ranks should be more responsive - not just on this, but all stocks ?
CML Microsystems (LON:CML) A positive AGM statement. They have had a flat period post-COVID, while they sold off the memory side of the business, and pumped money into new products on the comms side of the business. This is a small "fabless" business, with leverage to match. I hold.
Hi SundayTrader,
I've just been taking a look CML Microsystems (LON:CML) - update will be posted shortly.
Roland
"Circular AI funding at Nvidia: the biggest financial news story overnight is that Nvidia is turning to major institutions for $500 billion to help fund AI infrastructure"
Yes - this is a big story. Also reported in the press today.
"OpenAI will pause some of its work on a planned update to ChatGPT amid fears it could be too dangerous."
The Independent reports that some work on the new model "Astra" has been paused after testing showed that it might be too powerful. Link to original article below.
https://www.independent.co.uk/...
Thanks for the link here, very interesting....as both Anthropic and OpenAI are both planning their "trillion dollar" IPOs to raise more capital later this year, I find it entertaining that the PR coming out of both companies these last few weeks is about the "risks" associated with both of their most recent releases, with both stating how powerful and dangerous their new variants are -kind of trying to out-do each other on that front. So a negative message but their aim clearly to boost visibility before their respective IPOs.......A lot of PR hot-air and this will all come to a very nasty end in 2027 methinks ...just a thought.
The Independent reports that some work on the new model "Astra" has been paused after testing showed that it might be too powerful.
Since when in the history of capitalism does someone say that their product is too good?
I thought that there was some irony in the story in that AI was attracting huge funds for development yet on the other hand was having to pause development.
I don't think anyone yet is assessing AI as being good or bad - rather something that might be useful but has got ( just ) beyond the point of human control and intervention.
I know very little about AI other what I read. I suspect its main use will be in warfare and that Sovereign countries will have to develop to protect themselves.
I suppose that it is also possible that AI , depending on what it becomes might decide that capitalism is not a good thing. Who knows?
Or another great quote I heard in relation to AI "The robots will probably end up destroying us but it will still happen anyway as trillions of dollars will be made in the lead up"
In other words, Nvidia is helping to arrange cheap debt for their AI industry customers, in order to further boost demand for Nvidia's processing power.
Isn't this a bit like what GE Capital did? It didn't end well.
I can only presume that these mega players know what they're doing. Plenty of brains, and all that. They wouldn't be pumping all this money into AI if they didn't think there would be a payoff, right? Right?
Just for clarification, I'm not invested, I think the whole thing could go horribly wrong. But as the saying goes, a cynical knows the price of everything and the value of nothing. It will be interesting to see how this all plays out. I'm on the sidelines. Me personally, I'm following Peter Lynch's advice: avoid the hottest stocks in the hottest industries.
Interesting StockRank movement in tinyBuild (LON:TBLD) which I hold. -3 in 30 days, +13 in one week, +3 in one day. TortoiseInvestor has been commenting on recent interest on online gaming websites in TBLD's games.
Review and thoughts on Altyngold would be good
I would appreciate your opinion on Thor Exp results
Could you look at Spirax (LON:SPX) and Lion Finance (LON:BGEO) please. Recent add on lion finance as a momentum play, but spirax has been in my portfolio for two years now, was quality, any chance it goes the same way as rotork, as it's specialist and industrial?
We got one of them covered, Eric! Sorry we didn't get around to BGEO. It is a little bit too exotic for my taste, if I'm being honest. Not sure I'd be able to add much value. G
No worries and thanks for all the commentary regardless. Spirax I feel moved like PZ Cussons (LON:PZC) did. Decent results with a drop, it the. Recovered well. See what the rest of the week brings. Lion Finance (LON:BGEO) is spicy, but came up on my momentum screen and is a small position
New Tpximpact Holdings (LON:TPX) £25M "provisional" Ministry of Justice contract disclosed after hours yesterday. Combined MoJ exposure deepened and is now ~£41m TCV across 2 awards.
Yes, I have a small holding of Tpximpact Holdings (LON:TPX) and looks like another significant win. Shares look attractive - Graham and Team if you have time, i would appreciate your views? Thanks.
I'll make a note that we should try to look into TPX in the next couple of days, thanks Murray.
Appreciated Graham.
IG group (LON:IGG)
Decent 500k buy by the ned here - lots of question marks over the recent acquisition - with pe of 10 though with company with very decent long history of executing I have been tempted in here - I bought yesterday nice to know directors following suit - I would say what is cheap can get cheaper the chart most certainly doesn’t look great and I suspect many will not be liking the big acquisition
The recent fall in the IG market cap exceeds what they're paying for Underdog, so the sell-off probably looks a bit excessive.
Plus500. (LON:PLUS) similar in market not liking the betting markets thing. Interactive Brokers (NSQ:IBKR) is down $7 and keeping to their knitting I think - great liquidity and cheap (for US, and has a UK ISA which have just got into and seeing how it goes).
I looked at Underdog website to understand what is on offer. This semingly is gambling pure and simple basically on NFL and Baseball teams where odds are set at a favourable level to attract bets. The best odds being on the ' underdog' Not being a gambler in particular ( and I see Plus 500 are moving into the same) I am struggling a bit with the concept. Of course this maybe just the type of area that Generation Z finds irresistible and I am sure captured in someway by our ever present friend Social Media. No doubt there are other areas of US life that could be captured by the concept. I can think of Golf pairings for example and match ups on tennis grand slams... Those were just from my slow brain...... Perhaps estimate the remaining life of the president of FIFA etc
£IG
i have to presume its all about cross selling opportunities
the market segment that will be playing fantasy sport for free - or fantasy sport - or prediction marekets - and sports gambling - is deffo the market segment that will want to be doing spreadbetting - buying shares - buying crypto and the like. Your average educated us young un is much more likley to be active in all those fields than your typical brit. Bit of predictioon gamling is a nioce in to pimp out a customer for life.
so to me Its it a simple grab for us customers to expand us presence like tastytrade -- it does seem like they think underdog will be making decent ebitda sooner rather than later so it does seem that they are getting a decent potential business here ref where it is trending - stuff like that can be very fickle at regualtory level tho lets be crystal clear on that subject.
Note no reason why they can cross sell underdog into uk too.
So i see it as simple us expansion - whilst no certainty it will pay dividends - looks pretty simple plan to me - and there is perhaps more scope for revenues here to exceed on the upsdie than tastytrade - dont know exact stats for tastyrade but i think it brings in decent revenues.
Note there may be an element of them needing to have stuff like this to stop drift away from customers going to other platforms like trading 212 robinhood etc ot other platforms we have never hear of.
Overall its tricky to see if this will pay dividends - but i dont think they can have enough diversification - if you dont offer your customer the works - well they may go to competitor who does.
as with any company that morphs from handing back back profits earned to shareholders - to spending that cash in the hope that will do better in the future - well you gotta hope the acquisition mostly arent total bombs there is perhaps scope for one total bomb though when dilution aint too much. They might very well know though that they have no choice - if sticking to their core would see customers drift off to more flexible competitors - it may be that they ned to splash the cash to stop slow decline in business. I dont really have much of handle on how secure their core stuff is - i wouldnt be over worried but we cant ignore the fact that the big uns probbaly need to do it all to stop all their core customers driftinmg off somewhere where they prefer as thats where they have being doing their other similar activities. The danger is alwasy that management may be to cock sure that this company is worth what they are paying - it might very well not be if regulators cause grief - or customers turn out to be fickle ref being sticky.
Note this acquisition should not be a huge surprise based on the prior tastytrade acquisition - imho its very much more of the same perhaps slightly bolder - but they are a bigger market cap company than they were when they acquired tastytrade.
Hi RM
thanks for that, your comments make sense. I was an advocate of the Tasty Trade acquisition despite nearly every one else saying it was far too costly. I agree there is some merit in the ' keeping up with the Joneses ' if the company sees this as an adjunct to retaining customers it may well be a risk worth taking. Whilst DT and his free loading bunch of advocates are around this type of seemingly ' wild west' business has a better chance of being licensed. Given we hardly know if other platforms offer better odds ( sorry more attractive ' event contract terms') for the same it must be hoped fingers do not get burned on something so esoteric
it must be hoped fingers do not get burned on something so esoteric
well thats what hapened back in the day when the us shut down all the poker sights over night and confiscated all the funds that were hundreds of millions - all these directors would sign away their company for nothing if they have been arrested returning from their us holiday for a potentail wire fraud type stuff with the threat if you dont do this you wont go home for the next 15 years. i think that did happen to one or two of the guys from betonsposrts which was a uk listed company i think - us arent afraid to flex their muscle - note i have to believe that decent due diligence would have been done here - so dont take my concerns as being actual worries - just a flavour of how murky it can get.
This semingly is gambling pure and simple
Arrgh, don't use that word! Part of the recent legal challenge against competitor Kalshi relates to whether sites like Underdog are gambling, or not.
Per Grok: Kalshi argues its contracts are federally regulated derivatives (swaps or futures under the Commodity Exchange Act), so the CFTC has exclusive jurisdiction and state gambling laws are preempted. States counter that these contracts function as sports betting/wagering (uncertain outcomes outside the bettor’s control), require state gaming licenses, and that federal law does not fully displace traditional state authority over gambling. Courts are split.
Litigation is active and fragmented across federal and state courts, with appeals pending in multiple circuits. Outcomes vary by jurisdiction and specific contract type (sports vs. other events).
So remember, it's not gambling, it's ,um, an "event contract".
i doubt at basic level that anyone could argue this isnt gambling if it went to an argument right at the top - lets be clear here. They may perhaps be the right side of then line on technical matters as things stand - but its plain and simple gambling.
US seems to have a very strange lover hate relationship with stuff like this - note it may very well be that IG group (LON:IGG) may be happy with top level regulation to be endpoint - eg draftkings seems to exist ok withn gambling rules as they are - there is a danger though use may tail of if taxes raised are to high - alot of styff like this is done on basis you dont have to pay excessive taxes every time you bet - if you have two bets at evens each for £50 and you win one out of the two - you dont want to have £80 in your pocket having paid £20 tax - thats so much it just makes the game non worthwhile - you want to tax the operator on their net win .
its clearly high risk stuff
Hi Mark
thanks for the additional info. This seems like a guaranteed win only for US lawyers. I am not one and do not pretend to see how this is an ' event contract' not sure I see how £5 on the favourite at Newmarket is much different but there you go.....
IG group (LON:IGG) My experience of companies who make big acquisitions outside of their area of expertise has been poor. So I find myself a reluctant holder here, but reluctant to sell as well, given the fairly modest PE. I suspect there are a lot more like me.
Count me as one of them, too.
The CEO of IG Group led Paddy Power Betfair (now Flutter Entertainment) for a couple of years so gambling is not outside his area of expertise.