Daily Stock Market Report (Tue 9th June 2026) - BWY, GLE, FEVR, SSIT, TIME, COST, LBG

OpenAI has filed its initial registration statement (the S-1 form) with the SEC. On their blog, they wrote:
We expect it to leak so we’re just announcing it. We have not decided on timing yet; it may be a while because there are things we want to do that are likely easier as a private company.
This catches up OpenAI with its rival Anthropic, which also recently filed its S-1.
Meanwhile, the SpaceX IPO is happening on Friday:
Ticker code SPCX.
IPO price: $135 per share
Market cap: $1.77 trillion (the biggest IPO ever)
At this market cap, the valuation of SpaceX is over 90 times last year’s revenues, although that is measured prior to the acquisition by SpaceX of xAI. Based on 2026 forecasts, the price to sales multiple is a more modest 70x.
As an aside, I note that the FTSE finished flat yesterday, compared to Friday’s close, entirely unaffected by the weakness in AI shares. It’s up slightly over the past week, while the S&P 500 is down 2.5% and the NASDAQ is down 4%.
Overnight market movements:
The FTSE is set to open unchanged at 10,370
S&P 500 is up 0.3% at 7,430
Brent crude is down 1% at $93.20
Gold is up .4% at $4,350
Bitcoin is unchanged at $63,400
Finishing there, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£77.5bn | SR94) | Agrees to buy Nuvalent, a Boston-based clinical-stage biopharmaceutical company focused on creating precisely targeted oncology therapies, for $10.6 billion. Net of cash acquired, aggregate investment estimated to be $9.4 billion (£7.1 billion). No change to GSK's 2026 full-year guidance range of 7-9% core operating profit and core EPS growth. | ||
Bellway (LON:BWY) (£2.0bn | SR57) | “...an increasingly challenging market, with customer demand having moderated in recent weeks… Notwithstanding this, and supported by our forward order book, we are on track to deliver FY26 underlying operating profit within the previously guided range of £320m - £330m.” Reiterates volume output of 9,300 to 9,500 homes. | AMBER = (Roland) [no section below] Trading improved in the early part of the spring, but has since moderated. Cost inflation on materials also remains an issue. Bellway says reservation rates remain higher than in H1, but are lower than during the comparative period last year, despite “a good contribution” from bulk sales. Land purchases remain selective and the balance sheet remains in good health. More broadly, I share the StockRanks’ view of this stock as a potential Contrarian play. As I discussed in March, Bellway’s c.40% discount to NAV is wide by historic standards and I view this as a well-run, good quality builder with very experienced management. The issue is the timing of any recovery, as highlighted by the MomentumRank of 1. This combination of in-line guidance but an uncertain outlook means I’m leaving my neutral view unchanged today. | |
Keller (LON:KLR) (£1.72bn | SR97) | Awarded a contract variation order of $207m in relation to the reconstruction of the I-40 highway in the US. Supports longer-term revenue visibility. KLR remains confident of delivering 2026 full year results in line with expectations. | ||
Oxford Instruments (LON:OXIG) (£1.70bn | SR70) | Full-year performance slightly ahead of expectations.Order intake +8% LfL, revenue down 3% LfL, adjusted operating profit down 1.6% LfL. Book-to-bill of 1.06x. “...we are confident in our ability to deliver attractive sustainable growth and value for all our stakeholders in the new financial year and beyond.”. | ||
Breedon (LON:BREE) (£956m | SR62) | Buys Falling Springs Quarry for an enterprise value of $120m (£90m). Falling Springs is “a well-invested, highly automated quarry with 185 million tonnes of limestone reserves strategically located approximately 15 minutes from downtown St Louis, Missouri”. | ||
Molten Ventures (LON:GROW) (£936m | SR88) | Portfolio company ICEYE Oy has raised approximately €450 million. Total transaction size >€1 billion. Valuation >€10 billion. Molten has sold c. £22m but the valuation of its ICEYE holding increases by £238m to £317m vs. March 2026 balance sheet value. This would increase Molten’s NAV per share by 117p to 877p. | ||
Fevertree Drinks (LON:FEVR) (£865m | SR45) | “The Group has made a solid start to the year and remains confident of achieving full-year market expectations.” £30m extension to the buyback programme. | AMBER ↑ (Roland) [no section below] Today’s in line statement suggests we could see modest revenue growth and a stronger recovery in earnings this year, noting that the correct comparator for consensus revenue forecasts of £386m is £375.3m. This adjusted figure is used for comparability as it includes invoiced revenue in the US, not just the royalties Fevertree actually earns through its recent partnership with Molson Coors Beverage Co (NYQ:TAP). The upshot of this is that expected sales growth in 2026 is just 2.8%. As Mark has highlighted previously, this level of top line growth is probably lower than we’d want to see from a successful, branded consumer goods business. For me, the acid test will be whether Fevertree’s margins can recover towards the above-average levels seen historically. As things stand, the stock looks expensive, but consensus forecasts suggest double-digit earnings growth in both 2026 and 2027. That could repair margins and bring the valuation to a more reasonable level. With net cash and no particular problems evident, I think a neutral view is fair here. | |
Costain (LON:COST) (£514m | SR95) | SP +1% Selected by TfL as one of three contractors on its Infrastructure Improvement Framework, which carries a total value of approximately £700m. Projects to be awarded over a two-year term, with an option of a two-year extension. No reference to expectations. | GREEN = (Graham) [no section below] This update contains no reference to any change in earnings expectations; Costain’s selection by TfL for this framework will surely have been baked into existing forecasts. In valuation terms I’m not sure how much upside is left on the table with the shares already trading at 12x earnings. More positively, the recent AGM update confirmed that the company expects its net cash position to be approx. £175m at the end of the current financial year, despite a £20m share buyback programme and a near-3% dividend yield. Cash flows can be volatile and as such, we’ll watch the interim results carefully. But given the strong balance sheet and continued healthy trading, I’m ok with us staying positive on Costain for the time being. | |
| Seraphim Space Investment Trust (LON:SSIT) (£444m | SR93) | ICEYE Financing Round | SP +14% ICEYE is currently SSIT’s largest portfolio holding. “Based on the announced valuation, the implied uplift in the fair value of the Company's holding would be approximately £202 million, which would represent a 102% increase in fair value and would be equivalent to an increase in NAV per ordinary share of approximately 73p.” | AMBER = (Graham) I would have to say that the €10 billion valuation of ICEYE is highly speculative. At a forward price/sales multiple of 20x, there is no other conclusion I can draw. The 73p increase in NAV arising from ICEYE’s new valuation leads to a new NAV per share for SSIT of over 250p. SSIT has enjoyed a c. 41% increase in its total NAV from this single event. These back-of-the-envelope calculations suggest that SSIT is currently (at 212.5p) trading at a c. 15% discount to NAV. But there are some good reasons for caution. |
VAALCO Energy (LON:EGY) (£432m | SR50) | The Baobab field on CI-40 block, offshore Côte d'Ivoire is back online following the successful Baobab Ivoirien FPSO vessel refurbishment. | ||
MJ GLEESON (LON:GLE) (£142m | SR45) | Gleeson Land has been extensively engaged in the sale of a site which would account for c. 50% of the total plots to be sold in FY2026. The transaction is now unlikely to complete in the current financial year. Also two smaller transactions, originally expected to complete in FY26, are now expected to conclude in H1 FY27. Adjusted PBT for FY26 to be £7.5m lower than current market expectations. | BLACK (AMBER =) (Roland) This is a big profit warning, with pre-tax profit guidance for the year ending 30 June cut by c.40%. However, Gleeson’s share price has already fallen by a similar amount since February and I would argue the risk of a warning – previously well flagged – was already priced in. Based on the company’s H1 NAV of 522p per share, Gleeson now trades at a discount of more than 50% to its book value. While there’s some debt, I don’t think it should become problematic and would view this stock as a potential value play. The problem is that there’s currently no sign of any catalyst for a recovery and market conditions could still worsen. For these reasons, I’ve left my previous neutral view unchanged today. | |
Jubilee Metals (LON:JLP) (£86m | SR24) | Run-of-mine (ROM) deliveries to Sable refinery and refining activities recommenced following the successful expansion of Pit 2 as part of the pre-stripping under the updated mine plan to combine Pits 2 and 3. Targeting 6,000tpm for June, rising to 10,000tpm by October 2026. | ||
Andrada Mining (LON:ATM) (£80 million | SR20) | High-grade lithium mineralisation confirmed across multiple drill holes, with consistent associated tin and tantalum mineralisation confirmed across all holes. Has now completed Stage 1 drilling campaign of 143 holes. | ||
Orosur Mining (LON:OMI) (£80 million | SR11) | First new hole at APTA (MAP-106) returns 229.7m @ 0.88g/t Au with “numerous higher-grade intervals”. Results are said to have “substantially enhanced the prospectivity of APTA with three areas of potential requiring follow up”. | ||
LBG Media (LON:LBG) (£73m | SR78) | SP -24% Revenue +19%, pre-tax profit down 79% to £1.8m. Lower margins driven by “planned investment in our Direct sales and operations”, as well as an adverse revenue mix. Outlook: now expects FY26 revenue of £100-107m and adj EBITDA of £15-20m (prev. £110m and £22m). Zeus updated broker estimates: - FY26E adj EPS 4.7p (prev. 6.2p) - FY27E adj EPS 5.9p (prev. 7.2p) | BLACK (AMBER/GREEN ↑) (Roland) Today’s profit warning translates to a large reduction in expected earnings over the next three years. While revenue growth in the Direct business seems impressive, it carries higher costs and today’s results do not provide a clear view of margins in this business. The old Indirect business – formerly a high-margin cash cow – is suffering a decline that I suspect could be longer and deeper than previously expected. Notwithstanding these risks, I do think there’s some potential value here. Net cash covers c.50% of the current market cap and the stock now trades on a forward P/E of 5x, including net cash. To reflect the change in valuation since our last view (in Jan 25), I’ve moved our view up by one notch today, with the caveat that I see this as a somewhat speculative situation. | |
Time Finance (LON:TIME) (£42m | SR70) | Strong performance has continued. Year-end (31 May) gross lending reached £217m and is currently at £250m, an all-time high. Q4 TU scheduled for 25 June. | GREEN = (Graham) [no section below] I’ve been a fan of this one for a while and it’s easy for me to stay positive on it after this slightly triumphant update. Q4 ended in May and TIME announces that its lending book has now reached £250m, up 15% compared to May 2025. While we don’t yet have the Q4 trading update proper, they do say today that “the Group's previously announced robust performance in the first three quarters of the current financial year has been maintained throughout the quarter ending 31 May 2026”, and this should reduce the probability of any nasty surprise in this update. At the Q3 update, Cavendish forecast we’d see adj. EPS of 7p in FY26, rising to 7.7p in FY27. At a share price of 46p and with net tangible assets per share of c. 54p, I continue to think that this one warrants attention. | |
Rome Resources (LON:RMR) (£27m | SR24) | 2026 field programme starting at three priority targets in New Brunswick, targeting tin and tungsten. | ||
Vianet (LON:VNET) (£20m | SR93) | Revenue +1.5%, adj operating profit -7.6% to £3.1m. EPS -51% to 1.43p. Hospitality business gaining traction with expanded offering. Outlook: well-positioned for sustainable medium-term growth. | ||
FIRST CLASS METALS (LON:FCM) (£17m | SR15) | Has raised £1m before costs through a placing of 26.3m new shares at 3.8p per share, a 9.5% discount to the closing price on 8 June 2026. | ||
Alien Metals (LON:UFO) (£13m | SR17) | Execution of joint ventures at Elizabeth Hill Silver and Munni Munni PGM projects has reduced funding requirements. Net loss of $0.7m in 2025, with year-end net cash of $1.5m. Raised £2.8m in placings last year. Going concern warning: current resources are not sufficient to cover projected expenditure over the coming year. | ||
Thor Energy (LON:THR) (£12m | SR29) | Phase-2 soil air geochemistry survey at the HY-Range project has recorded natural hydrogen readings of up to 3% (30,000 ppm) on licence, while validating three of Thor’s highest-priority exploration focus areas. |
Graham's Section
Seraphim Space Investment Trust (LON:SSIT)
Up 14% at 212.5p (£664m) - ICEYE Financing Round - Graham - AMBER =
We haven’t covered this much but I understand that it's a popular and interesting story, often featuring in our list of “Most Viewed” stocks.
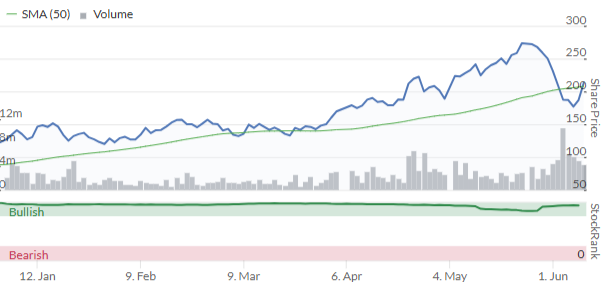
I initially took a look at it in April at a share price of 180p.
It has been as high as 270p, before dropping back:
Today’s update relates to a satellite company originally from Finland, ICEYE, in which both Seraphim Space Investment Trust (LON:SSIT) and Molten Ventures (LON:GROW) are invested.
A description of ICEYE, from its own website:
ICEYE owns the world's largest and most advanced SAR (synthetic aperture radar) satellite constellation. We deliver persistent monitoring capabilities to detect and respond to changes in any location on Earth.
Key points:
ICEYE is privately raising €450m at a valuation of over €10 billion
At March 2026, ICEYE was 47.1% of SSIT’s NAV.
The new valuation would increase SSIT’s NAV by 73p
The Chief Investment Officer at SSIT’s manager says:
"For SSIT shareholders, this financing round demonstrates the Company's ability to provide access to category-leading SpaceTech companies at the forefront of some of the most important technological and geopolitical trends shaping the global economy."
Graham’s view
Before checking SSIT as a whole, I’d like to briefly look at some of ICEYE’s financials.
It posted its 2025 results as follows:
Revenue >€250m
EBITDA >€100m
Cash >€350m
Cash from operations >€130m
Contracted backlog €1.5 billion
They launched six new satellites, bringing their total number of launched satellites to 70.
They said that ICEYE “doubled in 2025 and is set to grow at a similar rate in 2026”.
Now let’s suppose that ICEYE’s revenue reaches €500m this year.
At a €10 billion valuation, that’s a price to sales multiplier of 20x. Great value compared to SpaceX, at least!
All references to EBITDA and cash from operations are irrelevant as the tooth fairy doesn’t pay for capex, not even in space.
To my eyes, therefore, I would have to say that the €10 billion valuation of ICEYE is highly speculative. At a forward price/sales multiple of 20x, there is no other conclusion I can draw.
Seraphim Space Investment Trust (LON:SSIT)
Turning away from ICEYE to look at SSIT, this is now a FTSE-250 component.
Q3 results were published last week with the following info:
NAV £421m as of March 2026
NAV per share 177.6p, up 24.8% quarter-on-quarter
Shares in issue 237m
This was a tremendous quarterly gain, “largely due to continued strong performance of ICEYE, funding rounds at Xona Space Systems and Tomorrow.io and the HawkEye 360 indicative IPO pricing…”
Their portfolio was made up as follows:
ICEYE 47.1%
ALL SPACE 13.6%
HawkEye 360 9.8% (Stockreport: HawkEye 360 (NYQ:HAWK))
Xona Space Systems 6.7%
…and various smaller positions.
The 73p increase in NAV arising from ICEYE’s new valuation leads to a new NAV per share for SSIT of over 250p. SSIT has enjoyed a c. 41% increase in its total NAV from this single event.
These back-of-the-envelope calculations suggest that SSIT is currently (at 212.5p) trading at a c. 15% discount to NAV.
But there are some good reasons for caution:
A highly concentrated portfolio with ICEYE being responsible for the vast majority of value means that NAV becomes less useful as a metric.
ICEYE’s valuation is itself open for debate and in my view should be controversial. Over what timeframe will it conceivably generate €10 billion of value for its investors, when its total revenue backlog is currently about one seventh of this?
SSIT itself is involved in heavy fundraising activity. 137m new C-shares have already been issued. While the dilutive effect of these shares is being mitigated in the short-term by keeping them distinct from SSIT’s ordinary shares, there could be complications arising from managing two separate pools of capital and attempting to merge them over time.
I’m going to stay neutral on SSIT. To be clear: I do not understand the value of ICEYE. And SSIT itself is now largely being driven by ICEYE’s valuation. But if I view SSIT purely as a vehicle with which to own space-related investments, and considering that the valuation of these investments is only going upwards for the time being, I can remain neutral.
If the space theme turns out to be a bubble (which I strongly suspect that it is), and it pops, I’ll want to have a negative stance on SSIT then. But for now, it seems that we are go for launch.
Roland's Section
MJ GLEESON (LON:GLE)
Down 4% at 238p (£139m) - Update on Gleeson Land - Roland - BLACK (AMBER =)
In February, I highlighted housebuilder Gleeson’s dependency on a big contribution from Land sales in H2 to meet profit expectations for the full year, which ends on 30 June 2026.
While lumpy contributions from the group’s Land business are the norm, this situation seemed more uncertain than usual, with a single site expected to account for 50% of all plot sales in FY26. The risk was that this – and other land sales – might slip into FY27, triggering a profit warning.
Today we have confirmation that this is what’s happened:
The majority of conditions required to achieve formal technical approval have been agreed, and the Group expects to conclude the remaining conditions soon. Completion of the transaction is now anticipated during the first half of the new financial year.Two additional, smaller land sales are also now expected to slip into FY27. This is said to be due to delayed decisions by major housebuilders, reflecting the current market environment.
Gleeson Homes: the good news is that trading at the group’s homebuilding business is in line with full-year expectations.
Revised outlook: the delayed land sales mean that MJ Gleeson’s adjusted pre-tax profit for the year is expected to be c.£7.5m below expectations.
Previous market expectations for pre-tax profit are given as being £16.4m to £18.5m, with a consensus of £17.8m.
That means this is a big miss – today’s revised guidance suggests pre-tax profit could be c.£10m, or around 40% below previous consensus.
Roland’s view
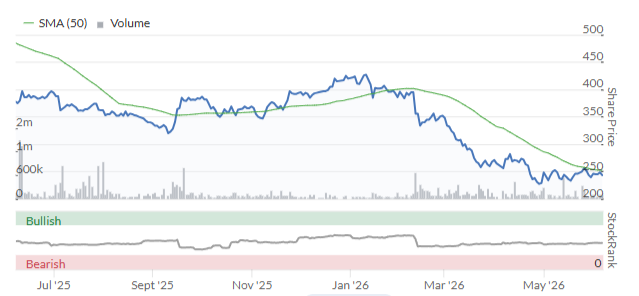
The market reaction to today’s profit warning has been muted, with the shares down by just 4% as I write, One reason for this may be that today’s warning was widely expected – the shares have already fallen by c.35% since February’s interim results:
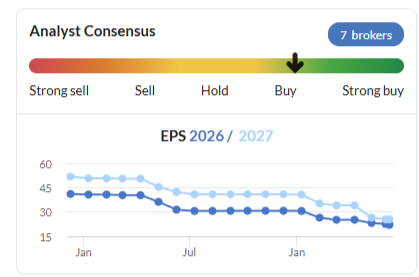
Broker consensus has also continued to decline since February, most recently following the trading update on 1 May:
I don’t see any particular reason to doubt that the delayed land sales will complete in FY27, so this potentially helps to underpin forecasts for the year ahead.
Deep value? Gleeson’s valuation is already deeply discounted, with the shares trading at a discount of more than 50% to the group’s last-reported book value of 522p per share, or £305m.
The majority of this is accounted for by inventories of land and homes under construction which were valued at £417m at the end of 2025. Barring a housing market meltdown, I’d expect these assets to maintain most or all of their value when eventually sold.
One risk is that net debt will have risen further since the half-year mark, due to the delayed completion of these land sales. While H1 net debt of £22.5m looked comfortable against previous profit forecasts, leverage is relatively higher versus today’s revised guidance.
Another potential concern is that the twin pressures on housebuilders’ margins from a lack of pricing power and materials cost inflation will persist for some time, leaving them generating very low returns on equity and thus justifying discounted valuations.
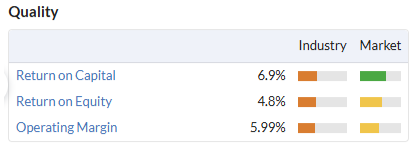
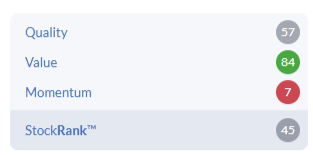
However, on balance I think Gleeson shares are cheap enough to be of interest as a value or Contrarian investment – a view reflected in the StockRanks:
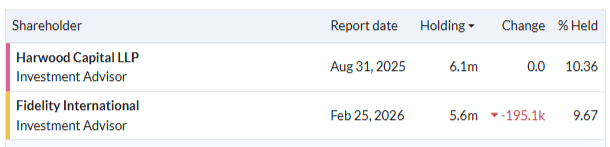
I note that Harwood Capital has become Gleeson’s largest shareholder, suggesting others see value here too:
As with Bellway above, the main risk I can see lies in the uncertain timing of any improvement in market conditions. I was neutral on Gleeson in February and don’t see any reason to change that view today. AMBER =
LBG Media (LON:LBG)
Down 24% at 27p (£56m) - Half-year Results - Roland - AMBER/GREEN ↑
LBG Media is “a social entertainment powerhouse with a focus on young adults” that’s home to a number of online publications and content marketing activities. Unfortunately the group’s core web properties aren’t as profitable as they used to be due to changes to Facebook advertising algorithms.
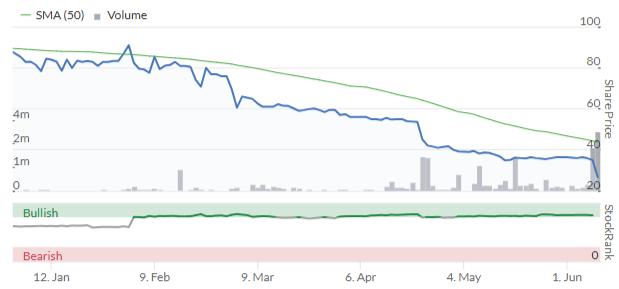
Today’s profit warning – the second in three months – and the shares have now fallen by nearly 70% so far this year:
Half-year results: key points
The combination of rising revenue and plummeting profits tells us that something is amiss here:
Revenue up 19% to £52.4m
Adjusted EBITDA down 34% to £8.0m
Pre-tax profit down 79% to £1.8m
Net cash down 14% to £28.4m
This situation is explained by the changing split between Direct and Indirect revenue:
Direct revenue up 95% to £37.6m
Indirect revenue down 41% to £14.5m
Direct revenue is generated from content marketing partnerships with brands – in essence, paid content and marketing efforts.
Indirect revenue is generated mainly from Facebook adverts placed alongside content on LBG websites, such as LADbible.
Indirect revenue is falling fast “due to previously announced changes to Meta’s Facebook algorithm in line with trends outlined in 2H25”, as well as lower search traffic due to AI Overviews (which discourage people from clicking through to search results).
Direct revenue is growing fast. But as broker Zeus highlights in an updated note today, there’s a problem:
Direct has mid-20% margins before central costs, while Indirect is >40%
In other words, Direct revenue is much less profitable than Indirect revenue, so the decline in Indirect has an outsized impact on profits.
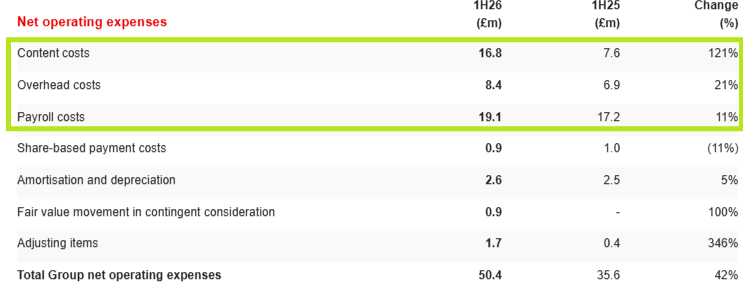
Margins were also affected last year by “planned investment in our Direct markets”. This is evident in the breakdown of operating expenses, with content costs more than doubling relative to the same period last year.
I would hazard a guess that producing good quality content for brand partners is more expensive than the kind of lower quality (in my opinion) material published on the company’s own websites:
Trading commentary: LBG is naturally keen to talk up growth in the Direct business, especially in the US, where Direct revenue rose by 154% to £16.1m last year.
For contrast, Direct UK revenue rose by 64% to £20.6m.
If these growth rates can be maintained at stable margins then it certainly seems like the Direct business could help LBG to gradually eliminate its dependency on Indirect profits.
The US market is described as becoming “materially more important” and is clearly the big hope for growth. Management describes the US opportunity as “a multiplier for LBG Media”, potentially allowing the company to replicate its UK model at scale.
I note that LBG is willing to sacrifice margin in order to try and win market share in the US:
Within 1H26, two large client deals were offered at lower than usual margins in the U.S. business, to incentivise higher levels of spend and build the client relationships.
Time will tell whether LBG’s Direct content is sufficiently distinctive and commercial to provide it with the pricing power needed for this strategy to succeed.
As things stand, Direct performance metrics in the US remain lower than in the UK. This could suggest an opportunity – although I imagine competition is tough in the US market:
# clients generating campaign spend >$1m:
UK: 16
US: 7
Repeat client revenue:
UK: 89%
US: 62%
Revised outlook & Estimates
In April, LBG raised revenue guidance to £110m and cut adjusted EBITDA guidance to £22m.
Unfortunately today sees a cut to both revenue and EBITDA guidance due to the continuing weakness in the Indirect business:
While Direct continues to see a healthy pipeline and improving deal margins, the trends in Indirect have not stabilised as quickly as anticipated. As a result, the Board now expects FY26 revenue of £100m to £107m and Adjusted EBITDA in a range of £15m to £20m.
I think the risk is that Indirect revenue and profit could fall further, faster, before reaching a sustainable baseline.
Today’s revised forecasts from house broker Zeus tend to confirm this view, in my opinion, with cuts all the way out to FY28:
FY26E adj EPS: 4.7p (-24% versus 6.2p previously)
FY27E adj EPS: 5.9p (-18% versus 7.2p previously)
FY28E adj EPS: 7.0p (-20% versus 8.7p previously)
In addition to higher costs, Zeus also expects revenue growth to be lower than previously expected – revenue forecasts have been cut by c.7% per year for FY26 through FY28.
Today’s cuts continue a downward trend for forecasts:
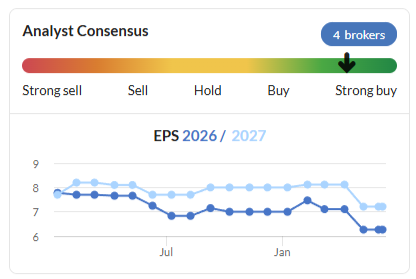
Questions over the sustainability of the company’s earnings may explain why LBG is trading on a FY26E P/E of 5x, falling to even lower levels for outer years.
Roland’s view
So far, I’ve focused on the performance of LBG’s operating business. My view is that the quality of earnings in the Indirect business is extremely low. The Direct business appears to be enjoying impressive revenue growth and could become a material business regardless of Indirect.
The concern I have regarding the Direct business is over its pricing power and sustainable level of margin. It operates in competitive markets with many competitors, some of whom are much larger.
Unfortunately, LBG doesn’t report the profit split between Indirect and Direct. This makes it hard for us to gauge the true value of the rapid revenue growth being seen in Direct.
However, there’s also another angle to this situation.
LBG Media’s market cap has fallen from £193m to £54m over the last year, but the group’s net cash position has remained relatively stable.
Today’s balance sheet shows net cash of £28.4m at the end of March, excluding leases (c.£14m) and contingent acquisition consideration (£8.6m). Even if we strip out the potential acquisition liability, that’s still c.£20m of net cash.
In other words, net cash now covers nearly half LBG’s market cap. This puts the stock on a cash-adjusted forward P/E of perhaps 3x. That prices in a lot of future weakness.
Another point worth noting is that CEO Solly Solomou remains the company’s largest shareholder, with a near-42% holding according to our data:
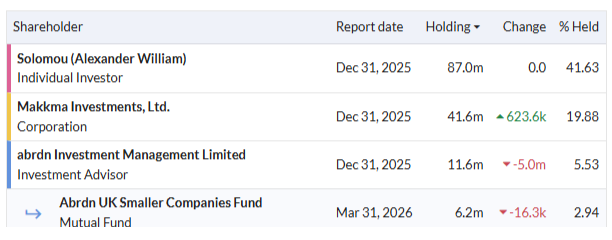
Mr Solomou has seen the value of his holding fall from c.£78m to around £22m over the last year. Presumably he is well incentivised to recover some of this lost value.
If the Direct business does have the quality the company would have us believe, then I wouldn’t be completely surprised to see LBG attract interest from trade buyers at current levels. Potentially, of course, Solomou might also engineer a bid to take LBG private at a low valuation…
Graham was neutral on LBG when it had a market cap of £261m in January 2025 (the shares were trading on a forward P/E of 16). While I think that was probably too expensive, I am inclined to think the current valuation may be too low.
The StockRanks view LBG Media as a Contrarian stock with strong Quality and Value scores, but a weak MomentumRank:
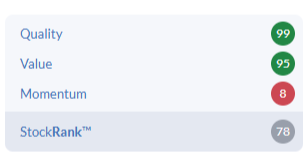
This largely mirrors my view, albeit I have some concerns about the underlying quality of the business.
Even so, I think the mix of value, risk and growth potential here could be worth further research.
I am going to move our view up by one notch to AMBER/GREEN, with the caveat that I view this as a speculative situation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Having sold out last year at Time Finance (LON:TIME), I watched a very assured presentation at Mello and bought back in.
Toda's trading update confirms for me that is growing their loan book at 15% a year. They've done similar for the last few years.
Yet, it's trading at a 6.5x PE for FY May26 that just ended. Which management have also just confirmed Q4 had done well.
There are the usual hazards with this type of business. It lends to SMEs. It is reliant on external funding for its loan book growth.
My view here.. Let's say a top quality lending business can command a PE of 10x. Time Finance is not top tier, so you take 30% discount. So 7x.
PE is on course to grow 15% next year (as opening loan book already that). It is easily at least 20% undervalued at this point and I suspect this is an easy rerating once the Q4/FY trading update comes out.
(I hold in the Boon Fund)
Time Finance (LON:TIME)
cheers boon - this one looks to be one consistent perfomer - increase in eps every year since 2022 - shares in issue hasnt budged since 2022 - and book value up to 81p per share well above shareprice - looks solid little performer. As you say monemy lending aint without risks - particularly regulatory.
Not sure how well funded they are ? with money lenders you need to know their sources of funding arent going to dry up anytime soon - not sure how rock solid their funding sources are ?
That is one of their risks. On the Asset Financing side, they use what they call "block funding" from over 8 unnamed institutions as well as the British Business Bank... I'm guessing they just pledge the Asset Financing loans they have made as collateral/assets to get new funding to lend out.
On the Invoice Financing side, they state "corporate banker back to back facility". I have in my notes (from the last few years) the name Natwest, but not sure where I got it from. So seems like a single name risk to be aware of.
Key risk is ofc that the credit markets seize up, and they can't get access to new credit to make new loans. And they just enter run-off, decreasing revenues, etc. But the high NTAV then protects the SP downside, as TIME increases its cash balances and the cash makes up more and more of the NTAV.
Time Finance (LON:TIME)
thanks for that
Note i see graham above has stated tangible book value is 54p a share thats a bit less than the 81p i quoted which was taken from stocky and perhaps may include intangibles? - either way tangible assets is higher than shareprice so as you say not a bad position to be in for company increasing profits.
Since AI has been mentioned ... I heard that Terry Smith has halved his positions in MSFT, META and GOOG on AI expenditure concerns.
There are concerns about overbuild collectively and an inability to spot who the is ultimately going to be.
Is he too negative? I can see where he's coming from, but these companies are on high rather than stratospheric valuations. It could be a mistake that he made like AMZN, where he sold because he thought that their forays into groceries wouldn't pan out.
I guess one way of playing it is to sit on the sidelines and see if any of them crash and burn as a result of their AI expenditure. That'll probably present a good time to buy in, like when META sunk all that dough into the ill-fated Metaverse. The market reacted badly and they pulled the plug. This turned out to be the perfect time to buy.
I think it likely that if one mega-cap pulls out then the rest will follow. Businesses have a habit of copying each others' behaviour.
Well, the US has pit its shants
Everything in context… still up 20%+ over last year! Can’t only go up forever.
Well yes, of course. Dow may finish blue. Remarkable.
Thoughts on the big IPOs happening this year? Minimal thoughts based on no research, but curious what others who are more knowledgable & researching it more think:
- SpaceX not buying into IPO, mostly out of an intense dislike for the CEO but also on extreme valuation / free float / governance grounds. Expecting it will still go to the moon for years as Musk's ventures usually do but still can't bring myself to get involved.
- OpenAI, for similar simple reasons, I wont be investing as I'm a huge Anthropic fanboy
- Anthropic, I use this daily both personally and at work, where we heavily use Claude Code amongst other things. Love the product and the overall experience as a consumer. Might invest a small amount into IPO purely as a fan boy, but would probably rather wait and watch for a while for any kind of serious investment.
Tomorrow CPI data is out in the US and pretty much sets the scene for rate prospects. Data so far this year has been high capturing mainly the rise in Oil prices that has increased data by c1.5%. Naturally this makes hitting 2% very difficult but the open question remains should the Fed even try. It is interesting to look at US Tips that are "supposed" to capture the higher inflation expectations. Interestingly they do not.... in fact the difference in TIP yields from conventional Treasury yields are pretty much the same they have been for a year or two. Inflation expectations remain anchored at 2.2-2.3% so investors in this liquid asset demand no more return now since the Iran War started. All very interesting since the market thinks the Fed will raise rates now....buy one could be forgiven for asking why? The conclusion TIPS market prices push you toward are that CPI data will not follow the strong PPI data we have already seen....and we only have a day to wait. As usual I would watch the MoM number not the full year and expect a drift back towards 0.2-0.3% and not remain higher than this. We see tomorrow but rate expectations may well fall which would hurt the Dollar.
I appreciate that it was a week ago now (2 June) but the proposed acquisition by Central Asia Metals (LON:CAML) of Cygnus Metals (ASX:CY5) for A$232m (£122.6m) didn't seem to be covered (unless I missed it). Given that this is one of the NAPs selection for this year and it has fallen dramatically from its peak of c. 241p end February to the current level of 132p I would have thought it merited some analysis (perhaps from Mark the mining 'expert'). Given Central Asia Metals (LON:CAML) market cap of £240m this would seem to be a biggish deal and the market certainly doesn't seem to like it as the share price fell even further following the announcement.
stats for Planet Labs (Planet Labs PBC (NYQ:PL)
mcap $11.69B (after recent 39% drop)
TTM sales $335.6m multiple x34
EBITDATTM $13.26 multiple x880
Cash from Ops TTM 132.5m multiple x88
looks more expensive than ICEye
I wonder how many UK investors are taking part in the SpaceX IPO? I'm not as its valuation is crazy and its just speculation. I am very surprised as to how open it is to UK retail investors. A warning sign, if ever there was one! All credit to Elon Musk though for getting this away. He can walk on water!
I've taken a punt on SpaceX but not on valuation grounds! I'm expecting that there will be forced buyers who may drive the price up, but I agree its highly speculative and very expensive.
I have applied as well (the maximum I had available).
There are so many different ways you can hedge this IPO, making it the easiest and quickest 10%-15% profit in the last decade.
All the best
Dear Graham,
I expected the DSMR this morning to confirm that the KOSPI had fully recovered yesterday’s losses, as yesterday’s crash was mentioned in your report. Worth mentioning that this index has almost DOUBLED YTD so a correction is obviously possible.
Comparing the FTSE 100, S&P 500, and Nasdaq over just one week is misleading. Short-term data captures momentary noise, not actual market health. A two year comparison (or more) shows the true picture.
Also, polymarket and other prediction markets heavily favour that SpaceX IPO will be a major success. SpaceX TAM is still bonkers though (about 25% of global GDP), but markets do not work like this!
All the best
The KOSPI is still down 9% over the past week. It's very very heavily concentrated in Samsung and Hynix. 50% of a national index in two AI-related stocks. Wouldn't that make you nervous? G
I don’t invest in the KOSPI (wish I did!) and it’s irrelevant to what I have written. When you mention a crash on Monday, then the correct thing is to mention that the losses incurred have been recovered on Tuesday.
Yes the KOSPI is up 184%! over the last year and a crash is not out of the question. It will happen.
I do like and respect your opinions, style and attitude on your UK analysis. It’s honest and transparent. I would love to see you analyse a US company.
I made my first investment in 1988 in the UK and my first in 1996-1997 in the US and worked in the industry till 2012-2013. How do you expect a market with growing EPS of 25% in 2026 to crash? Have you ever wondered why the US market makes new highs every single time there is a correction?
The US market always comes back stronger because of innovation, growth and liquidity.
At the end of the day it is damaging to not include the US in your subscribers portfolio.
All the best
I read on Twitter (make of that what you will) that S Koreans are cashing out their insurance policies and savings to pile into the local stock rally. Danger Will Robinson, danger.
"Also, polymarket and other prediction markets heavily favour that SpaceX IPO will be a major success."
Will be interesting to see how that plays out. I suspect they're right. SPCX is heavily oversubscribed, I hear. So it'll probably do OK, at least initially.
Remember, too, that Goldman Sachs is leading the IPO of Anthropic, so they'll definitely want SPCX to be a success.
All valid points Mark.
All the best
There has been some positive government policy too which has helped. South Koreans get capital gains relief from selling foreign stocks and reinvesting into national stocks (need to keep invested for 12 months). Presumably the move from foreign stocks has a limited duration on its impact i.e. once the majority has been transferred.
WH Smith (LON:SMWH) Financial Reporting Council displaying their usual relaxed approach, in only today announcing a review of Smith's external auditor, some 6 months after the accounting issue was identified.
Keller (LON:KLR) seems like a quality compounder (which is why I bought last month). It has returns on equity of 18%, decent interest cover of 11. Revenues have been growing at around 8% pa over the last 5 years. PE is 10 and P/FCF is 10, too.
Seems like June so far, nothing is allowed to rise!!
Fonix (LON:FNX) 3 year low, frustrating
Sell in May .... :)
Sell in June ha ha
Linked to redemption perhaps as it’s an aim listed share?
Could well be, a few suffering like that
Bellway (LON:BWY) looks cheap but for a reason. Incentives up, raw materials up, interest rates up (?), will all squeeze margins. Housebuilders are probably not the right place to invest at the moment.
But when it is will you be buying at such deep discounts to equity?
The chart looks bad and the stock is in a downward trend line. If that can reverse then will buy. I gave learnt from bitter experience that discounts can widen as well as shrink.
Nanoco - LON: NANO have the cheek to publish a
Nanoco Group PLC Glass Lewis recommendation
to recommend delisting of their shares and for retail to vote for delisting.
Nanoco shareholders - vote NO to delisting
Nanoco has announced that Glass Lewis recommends voting FOR the delisting resolution. That does not change the reality for ordinary shareholders. The stock is now trading at approximately half the cash balance they have!
This is still your company. The board only owns around 1.36% of the shares, yet it is asking shareholders to remove Nanoco from the public market. The delisting and re-registration need at least 75% of the votes cast, so retail shareholders can stop this if they actually vote.
Do not be passive. If you oppose delisting, vote AGAINST both resolutions immediately.
If you hold through Hargreaves Lansdown, Interactive Investor, AJ Bell, Barclays, Halifax, ii, Freetrade or another nominee platform, check your voting deadline now. Nanoco itself says platform deadlines are likely to be significantly earlier than the official proxy deadline of 10.30 a.m. on 17 June 2026.
Important: if you are buying Nanoco shares because you believe the delisting should be defeated, do not assume your vote will automatically count. Nanoco’s circular says shareholders must be on the company’s register at 6.00 p.m. on 17 June 2026 to vote, and platform deadlines may be earlier. Buy only if you understand the risks, then contact your broker/platform immediately and ask how to vote AGAINST the delisting.
The board wants to remove the public listing and leave shareholders relying on a matched bargain facility. That is not the same as a proper public market. Liquidity may be far worse. Once delisted, retail shareholders could be trapped in an illiquid private company.
This is not about Glass Lewis. This is about whether ordinary shareholders want to keep the right to trade Nanoco shares on the London Stock Exchange.
Vote NO.
Tell other shareholders.
Do not let apathy hand the board a 75% vote.
As a holder of Seraphim Space Investment Trust (LON:SSIT) the following RNS was of particular interest .
Summary by AI BETAClose X
Seraphim Space Investment Trust plc notes that its largest portfolio holding, ICEYE, is raising €450 million in a Series F financing round at a valuation exceeding €10 billion, with an expected closing in Q3 2026. This valuation implies an uplift of approximately £202 million in the fair value of SSIT's holding, representing a 102% increase and an estimated 73p increase in NAV per ordinary share. SSIT expects to reflect this uplift in its results for the year ended 30 June 2026, to be announced in October 2026
Entry to the FTSE250 the icing on the cake.
One of their other portfolio companies HawkEye 360 (NYQ:HAWK) recently listed on Nasdaq - it is classed as a Sucker Stock with a Stock Rank of 3!
Is this because it is newly listed and not had time to prove itself or is it because of its short financial history going back only to 2024?
Can anybody shed additional light on this?
(I hold SSIT and SSIC)
Not a share guidance outfit i admire but this is their take.
I have used it but with mixed results, what don't you like?
It was my first stock advisor app and I did not feel wellserved. The graphics made me feel empowered with no grasp of real fundamentals. VectorVest was my real education closely followed by stockopedia. ( But I have done better with stockopedia alone not combin
Mega news for Seraphim Space Investment Trust (LON:SSIT) this morning