Daily Stock Market Report (Wed 15th July 2026) - BKS, HTG, DOCS, AT.

The 20% Hormuz “reimbursement fee” for the United States, mooted by President Trump, has been rapidly dropped:
I have decided to replace the 20% United States Reimbursement Fee with Trade and Investment Deals that the various Gulf States will be making into the United States...
Trump said that leaders from Saudi Arabia, Qatar, Bahrain, Kuwait and the United Arab Emirates had all urged him to change the plan.
In other news, US CPI fell 0.4% month-on-month in June, according to data released yesterday.
It was a larger fall than the 0.1% decline that markets had expected, and it resulted in a year-on-year inflation rate of 3.5% (vs. 3.8% expected). This is still much higher than the Fed’s official 2% target (although the Fed prefers to use Core PCE, rather than CPI).
Overnight market movements:
The FTSE is down 0.25% at 10,490
S&P 500 is up 0.25% at 7,565
Brent crude (September) is up 0.65% at $85.40/bbl
Gold is down 0.5% at $4,035/oz
Bitcoin is up 0.5% at $64,900
Mark Simpson joins me today.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£113bn | SR66) | 3% YoY increase in copper equivalent production for the first half. Production/sales guidance is unchanged. Mid East conflict: Operational impacts to Rio Tinto remain limited. | ||
Antofagasta (LON:ANTO) (£37.9bn | SR72) | “We delivered another consistent performance in Q2, with copper production in line with the previous quarter and continued cash cost discipline across the business. Full-year guidance remains unchanged…” | ||
ICG (LON:ICG) (£5bn | SR80) | Fee earning AUM of $88bn, up 3% in the quarter and up 10% year-on-year. $2.4bn net additions to fee-earning AUM. Dry powder of $36bn, of which $18bn is not yet earning fees. | ||
ConvaTec (LON:CTEC) (£4.12bn | SR35) | CFO to stand down when a successor has been appointed. She is sincerely thanked. H1 results will be in line with expectations. Convatec expected “to deliver another year of double-digit adjusted EPS growth in 2026, driven by 5-7% organic revenue growth and adjusted operating margin of ≥23”. | ||
Barratt Redrow (LON:BTRW) (£3.92bn | SR48) | "...a solid performance in a challenging market, completing 17,6671 homes and generating adjusted profit before tax in line with market expectations.” Returning £400m to shareholders, primarily through a share buyback. | ||
Zegona Communications (LON:ZEG) (£3.48bn | SR95) | Revenues +2%, EBITDA +5%. Net debt reduced by 11% to €3.2bn, leverage multiple 2.33x. | ||
B&M European Value Retail (LON:BME) (£2.05bn | SR60) | UK LfL revenue down 2.3%. Total revenue up 2%. Slower start to garden season against very strong comparable. “Our B&M UK general merchandise trading margin continued the upward trend we communicated with FY26 results, which together with our ongoing focus on cost mitigation underscore our confidence in rebuilding Group profitability over time." | ||
Yellow Cake (LON:YCA) (£1.34bn | SR51) | Spot U3O8 price increased by 30% to USD83.95/lb on 31 March 2026, compared 31 March 2025. 39% increase in the value of the Group's holdings of U3O8 during the financial year to USD1,940.4 million. | ||
Supermarket Income REIT (LON:SUPR) (£1.11bn | SR65) | £100m proposed equity raise to fund acquisitions. Wants to buy nine grocery assets for £216m. | ||
Dr Martens (LON:DOCS) (£704m | SR92) | “Trading since the start of this financial year has been in line with expectations and our outlook and guidance for FY27 are unchanged.” | AMBER/GREEN ↑ (Graham)
After only recently switching from negative to neutral, I’m inclined to further upgrade our stance on this one today. It now qualifies as a Super Stock, as momentum has been improving. Today’s “in line” update gives us some hope that EPS forecasts might have stabilised, that the company’s attempts to “unlock” its operating model are working, and that this 50p-100p range for the share price might be the bottom. I always appreciate a well-known and popular brand, and Dr. Martens qualifies as top-tier in that regard. | |
Hunting (LON:HTG) (£686m | SR90) | “Solid Group performance during the period, with EBITDA in line with guidance.” “H1 2026 EBITDA of c.$62 million, consistent with the 40:60 phasing of full-year earnings guidance issued in March 2026.” 2026 full year EBITDA guidance of between $145-$155 million is maintained. | AMBER = (Mark) | |
Workspace (LON:WKP) (£661m | SR38) | “We saw a modest increase in stabilised occupancy and rent roll in Q1.” Considering an additional £100m+ of disposals above original target, with £200m of assets currently being marketed for sale. | ||
Cohort (LON:CHRT) (£609m | SR38) | Revenue +13%. Adj. operating profit +32%. Record closing order book underpins 83% of current market revenue expectations for 2026/27. Following contract wins since the year end, this now stands at 88%. Continuing to target double-digit earnings growth in each of 2026/27 and the subsequent two years. | ||
Costain (LON:COST) (£549m | SR92) | Awarded an 3 year extension to its existing Managed Service Provider contract with United Utilities. | ||
Galliford Try Holdings (LON:GFRD) (£545m | SR85) | Revenue +3%. Adjusted profit before tax at the top end of analysts' current forecasts (51.4m to £53.4m). Average month-end cash was up 21.0% at £216.2m. Robust order book of £4.3bn at 30 June 2026 (2025: £4.1bn). | ||
Bloomsbury Publishing (LON:BMY) (£526m | SR89) | The Board remains confident in delivering Adjusted Profit in line with expectations for the full year. | ||
XP Power (LON:XPP) (£515m | SR62) | The Court of Appeals has reversed the earlier 2022 judgment of the District Court and remanded the case for a new trial. As a result, the previous award of approximately US$40m in compensatory and punitive damages, together with over US$17m in attorney fees, and the permanent injunction, have been vacated. | ||
Anglo Asian Mining (LON:AAZ) (£469m | SR55) | H1 Production: Copper 8,840 tonnes (H1 2025: 1,188 tonnes). Gold 12,329 ounces (H1 2025: 12,114 ounces). Silver 92,855 ounces (H1 2025: 62,348 ounces). Net cash of $57.6m (31 Mar 26: $17.7m) The Board therefore remains confident in meeting 2026 guidance. | ||
Ashtead Technology Holdings (LON:AT.). (£332m | SR59) | H1 Revenue +1% to £100.2m, Adj. EBITDA margin 37.8% marginally lower than 25H1. The Board is comfortable with full year market expectations. | AMBER/GREEN = (Mark) | |
NextEnergy Solar Fund (LON:NESF) (£275m | SR48) | The Board has continued to engage with major stakeholders to understand their views on the Company's future strategic options. Having evaluated this feedback and numerous alternatives to maximise value for shareholders, the Board believes that it would be in shareholders' interest to investigate the sale of NESF. | ||
Petrotal (LON:PTAL) (£235m | SR99) | Group production averaged 12,557 bobp in Q2 2026, and 13,726 bopd in H1 2026;. Total cash of $136.8m on June 30, 2026 ($105.3m unrestricted), compared to $128.1m at the end of Q1 2026. | ||
Ferrexpo (LON:FXPO) (£171m | SR-) | 963kt. H1 production -54% on 25H1 to 1.56mt. The Group had an accessible cash balance of approximately US$27 million as at 30 June 2026. "In light of the actions taken by the Group, and based on current production rates, current and forecast energy prices over the next quarter, and an optimised sales mix, the Group now forecasts that it has sufficient net accessible cash less lease obligations and funds blocked at MBaer to operate in this current constrained environment until early Q4 2026." Remains suspended. | Suspended. | |
Beeks Financial Cloud (LON:BKS) (£147m | SR26) | FY26 Revenue +11% to £40.0m, U/L EBITDA +18% to £16.0m, U/L PBT +13% to £6.2m. Net Cash £0.63m (30 Jun 25: £6.96m). “The Group enters FY27 with encouraging momentum…” | BLACK (AMBER/RED ↓) (Mark) | |
Iofina (LON:IOF) (£107m | SR82) | H1 production +29% to 393.3MT of crystalline iodine. Spot iodine prices continue to trade in the mid-US$70/kg range. Currently anticipates H2 2026 production in the range of 460-485MT of crystalline iodine. | ||
Audioboom (LON:BOOM) (£90.6m | SR16) | H1 Revenue +30% to $45.7m, H1 Adj. EBITDA +80% to $3.2m. H1 PBT +248% to $3.1m. Casg $5.4m (30 Jun 25: $2.5m). “The momentum we have built during the first half of 2026 provides us with confidence for the remainder of the year, and with more than US$81.0 million of revenue booked for 2026 we are already ahead of last year's total revenue and are fully focused on maximising growth through the second half of the year.” | ||
Topps Tiles (LON:TPT) (£66.6m | SR56) | H1 Revenue +30% to $45.7m, H1 Adj. EBITDA +80% to $3.2m. H1 PBT +248% to $3.1m. Casg $5.4m (30 Jun 25: $2.5m). “The momentum we have built during the first half of 2026 provides us with confidence for the remainder of the year, and with more than US$81.0 million of revenue booked for 2026 we are already ahead of last year's total revenue and are fully focused on maximising growth through the second half of the year.” | ||
ECO Animal Health (LON:EAH) (£58.3m | SR85) | Revenue 10% to £87.5m, Adj. EBITDA +16% to £8.5m (5% ahead of consensus), PBT +35% to £5.4m. Net cash £25.4m (FY25: £25.0m) (39% outside China). Outlook: US revenue outperformance offsetting reduced revenue in China. Gross margins strengthening. | ||
James Cropper (LON:CRPR) (£36.3m | SR93) | Revenue +3.6%, Adj. EBITDA +33% to £8.9m, Adj. PBT +360% to £4.7m,Net debt £8.1m (FY25: £12.9m). “Trading momentum into FY27 has been positive with a strong start in the first quarter underpinning the Board's expectations for the full year.” | ||
Lendinvest (LON:LINV) (£36m | SR34) | Originations +17% to £1.44bn, NOI +12% to £43.2m, u/l PBT £4.0m (FY25: £1.3m LBT), EPS 1.6p (FY25: -1.2p). Impaired balanced -30% to £63.1m. Group entered FY27 with its largest lending pipeline to date. | ||
Kendrick Resources (LON:KEN) (£25.3m | SR15) | Channel TKCH004 delivered the strongest headline grade, returning 2.94 wt% LREO over 53.5m | ||
Wynnstay Properties (LON:WSP) (£23.1m | SR57) | FY27 has started well with operations in line with expectations. 99% of the rent due for Q1 has been collected. | ||
Great Southern Copper (LON:GSCU) (£22.4m | SR3) | 223 rock and channel chip samples define Au-Ag-Cu mineralisation at Viuda Negra | ||
Kropz (LON:KRPZ) (£19.8m | SR61) | Operational issues, combined with the market factors required a new US$ 12.3m loan from a related party at SA Prime +6%. Elandsfontein produced 95.956kt of phosphate concentrate in the quarter, -17% on previous quarter. Sales for the period totalled 183.714kt and stock at the quarter end was higher than anticipated being approximately 94kt. | ||
Artisanal Spirits (LON:ART) (£16.6m | SR15) | Group revenue broadly in line with 25H1.Cash generation in 26H1 £1.5m up on 25H1. Remains confident in delivering its expectations for FY26. | ||
Cellbxhealth (LON:CLBX) (£16m | SR13) | Q2 revenue +100% to £0.4m, H1 Op loss £2.7m, (25H1: £9.7m loss), cash £2.9m with average monthly cash burn £0.3-£0.4m. Outlook: FY26 revenues at least £2.1m, EBITDA positive in 2028. | ||
Angus Energy (LON:ANGS) (£14.4m | SR38) | Q2 Production from the Saltfleetby Field: 530 mscf natural gas and 3,365 boe gas condensate. Estimated Q2 revenue +37% on Q1 to £7.16m, driven primarily by higher realised gas prices, increased production volumes and improved hedging position. 30 June 2026, outstanding borrowings £24.7m. | ||
Tern (LON:TERN) (£11.1m | SR39) | 50m shares issued at 0.9p, a 31% discount to last night’s close, to raise £450k |
Graham's Section
Dr Martens (LON:DOCS)
Up 1% at 73.5p (£711m) - AGM Trading Update - Graham - AMBER/GREEN ↑
I’ve been growing increasingly curious about this one, a 2021 float that bombed:
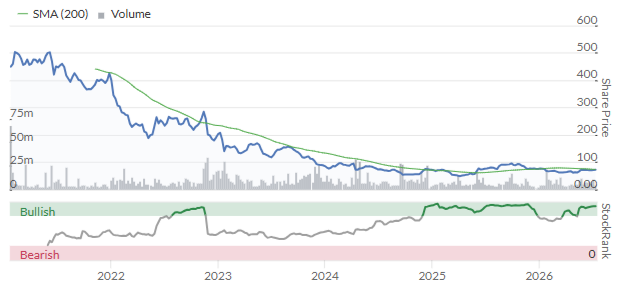
I upgraded us to a neutral stance in May at the full-year results.
Under a new CEO (since January 2025), there have been signs of improved financial performance, and promises of future operational leverage. Net debt has been on the decline, and there’s a yield of c. 3.5%.
Today’s update (emphasis added):
Trading since the start of this financial year has been in line with expectations and our outlook and guidance for FY27 are unchanged. We are focused on our ambition to become the world's most-desired premium footwear brand and are on track with our strategic objectives for FY27, as shared in our results on 19th May, which are:
- Consumer: Drive full price revenue mix in UK and DACH
- Product: Successfully introduce an innovative new sandals range
- Markets: Launch new retail concepts in key cities globally
- Organisation: Unlock operating model and technology benefits
The company’s largest market is the US (about 40% of revenues, I think). It “continues to grow, with wholesale particularly encouraging”.
Graham’s view
After only recently switching from negative to neutral, I’m inclined to further upgrade our stance on this one today.
It now qualifies as a Super Stock:
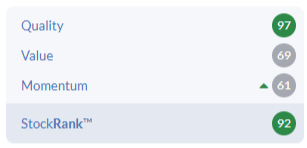
The last time I checked, it was merely Contrarian. But momentum has been improving.
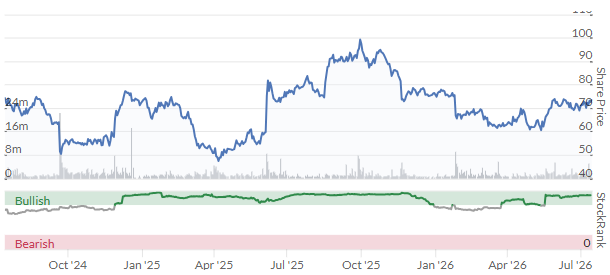
Technically, it’s still within the 50p-100p range:
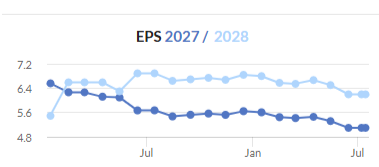
Earnings forecasts have been fluctuating:
The P/E multiple is about 13-14x:
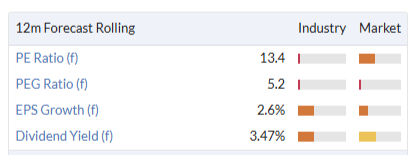
I’m going to resist the temptation to go fully GREEN on this today, as that might be premature. But I have no issue at all going AMBER/GREEN.
Today’s “in line” update gives us some hope that EPS forecasts might have stabilised, that the company’s attempts to “unlock” its operating model are working, and that this 50p-100p range for the share price might be the bottom.
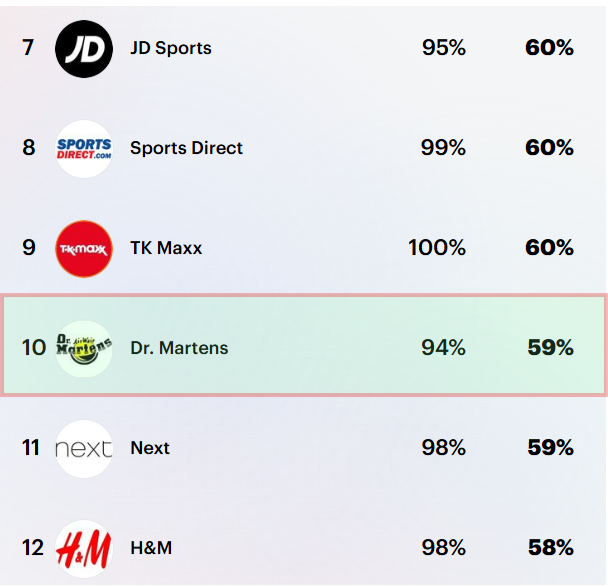
As a reminder, this is a brand owner that enjoys extremely high public recognition: here are YouGov’s fashion & clothing rankings sorted by “popularity” (right-hand side, 59% score) rather than “fame” (left-hand side, 94% score).
(Disclosure: I’m long NXT)
I always appreciate a well-known and popular brand, and Dr. Martens qualifies as top-tier in that regard.
Of course, that was true at its IPO, too. The difference now, compared to then, is that the share price is 80% lower. This has got my attention!
Mark's Section
Beeks Financial Cloud (LON:BKS)
Down 7% at 200p (£147m) - FY26 Trading Update - Mark - BLACK (AMBER/RED ↓)
Roland had previously commented on the race for Beeks to book enough revenue to meet expectations. In March, he estimated there was a £4.5m shortfall in revenue visibility needed to meet full-year forecasts.
However, in June there was a flurry of contract announcements. With revenue recognition on these often having a significant proportion being able to be booked on signing, these may have saved the day:
North American Exchange Operator ($3.0M): A 5-year software contract for Beeks Analytics and Market Edge Intelligence in New York, which expanded an existing deployment
Global Tier 1 Investment Bank ($4.8M): A 5-year agreement for their Market Edge Intelligence platform, marking the first deployment of the AI solution at Tier 1 bank scale.
Global Tech Customer & Strategic Partner (£1.7M): Three separate contracts including a 34-month software deal, a £0.6m Proximity Cloud contract, and a US$0.8m Private Cloud expansion with a strategic partner.
So the big question is, did they? The answer is not quite:
FY26 Revenue is expected to increase by 11% to approximately £40.0m (FY25: £35.9m)
Their broker, Canaccord had previously forecast £41m in revenue, so this is a miss but not a catastrophic one. This is what the company says on profitability:
…with underlying EBITDA growth of 18% to approximately £16.0m (FY25: £13.6m) and underlying profit before tax growth of 13% to approximately £6.2m (FY25: £5.5m). On a constant currency basis, Beeks has achieved revenue growth of 12% (£40.7m) and underlying profit before tax growth of 18% to £6.5m.
EBITDA is not a good measure for a business that capitalises development costs and, following their transition to a Revenue-Sharing Pricing Model, is increasingly absorbing the upfront capital costs to build and deploy the trading infrastructure. Clients "rent" the cloud environment, reducing their initial technology investment. Depreciation is now a real cost for Beeks, especially in an environment where latency matters and hence infrastructure lifespan is limited.
Underlying PBT of £6.5m is a 7% miss on Canaccord’s previous estimate. Enough for me to rate this as a sort of soft BLACK today. However, again this is a relatively minor miss and this is a company with a long history of not quite hitting expectations but still growing strongly. Canaccord also suggests that currency moves played a part in this miss. However, I am a little sceptical. The pound-dollar rate has to be the key one here, and while this has been volatile, there has been no defined trend over the last six months and today’s rate is around the average for the period. They would appear to have been quite unlucky with the timing of contracts or costs for FX to be the main reason for this miss.
Perhaps more worrying is this:
Gross cash at year end was £5.37m (FY25: gross cash £7.36m), with net cash of approximately £0.63m (30 June 2025: £6.96m).
Net cash was £3.29m at 31 December, so the cash outflow was £2.66m for the period. While Canaccord consider the rest of the figures broadly in line, the cash here is definitely a miss:
Net cash of £0.6m is shy of our £3.7m forecast, implying FCF of c.-£3.5m due to 2H capex for Proximity & Exchange Cloud deployments ramping in FY27 as well as collections for software deals signed late in the year falling into FY27+.
There is presumably a working capital aspect to this, with deals signed late in the period. However, assuming these deals were signed under the now-typical revenue-sharing pricing model, the capex associated with them will hit Beeks in FY27 as well. Both the “Major FX Broker Proximity Cloud Expansion” announced in April and the “Major FX Global Technology Customer Proximity & Private Cloud Wins” in June will have significant hardware components.
These contracts come at a time when the global tech sector is experiencing massive "chipflation," with DRAM prices up 171% year-over-year and server memory costs soaring. To help support these exact infrastructure rollouts amid rising chip prices, Beeks launched “Theia” in May 2026. This is a high-performance, GPU-accelerated dedicated server line built specifically for capital markets, and it will mitigate these effects somewhat.
Canaccord don't appear to have updated the table in their note in response to this trading update, and says they will review forecasts with the FY26 results, which are released in October, so we don’t really have an up-to-date view of near-term cash flow expectations. Their committed facilities provide them with £5.4m of gross cash to meet these capex requirements. However, another period of £3-4m cash outflow could leave them a bit too close for comfort.
Given that this cash outflow is funding capex, the banks may be happy to lend more. However, with the market having been relatively kind to the company lately, and a £147m market cap, they may see a small equity raise as the easy way to ensure they retain a robust cash position.
Mark’s view
I’ve always been a little sceptical of Beeks. I’ve never doubted their ability to grow their revenue. But they have always been a relatively capital intensive business, as contract wins often require them to fund the up front IT infrastructure. As such, I’m not sure I’d be willing to pay a particularly high multiple for that growth. However, many others take the opposite view.
I view Beeks very similar to Ocado. Where shareholders willingness to fund customer capex at high multiples gives a long runway for growth. It is just really hard to tell if the biggest attraction for customers is the technology product, or the upfront capex being funded.
For both companies, this dynamic gives them scale and the ability to develop long-term high margin recurring revenue streams, with the hope that in time they can transition to a more capex light model. Beeks certainly seem further on in this journey, as unlike Ocado, they do manage to be consistently profitable. However, generating free cash flow has been more of a challenge.
The big miss on net cash together with what I consider very small misses on revenue and profits, mean I am willing to call this BLACK today.
Despite a Stock Rank that was 17, Roland was willing to increase his view here to AMBER in early June due to its mid-teens forward rating and in line trading statement.
With today’s slight miss, the chance of an equity raise perhaps increasing, and a 20+ forward multiple, I think we should probably revert back to our previously more cautious view of AMBER/RED.
Hunting (LON:HTG)
Up 5% at 473p (£686m) - H1 2026 Trading Update - Mark - AMBER =
Recent history:
Hunting has confused me of late. A year or so ago, the company's outlook appeared to be improving. The share price had bottomed around £2.50 and was still trading at a significant discount to tangible book value, plus there were indications that they would implement a relatively large share buyback. Thankfully, Graham recognised the opportunity and gave the company a GREEN view.
However, when the company reported results at the end of August, I was more cautious, even though I held the shares at the time. The share price had risen to £3.27, but I commented that the rise was not backed by fundamentals as the EPS trend was backwards:
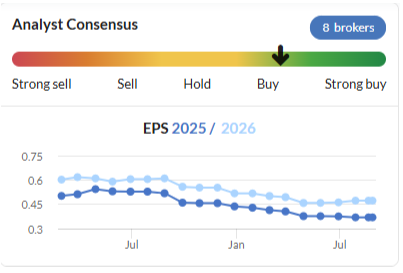
Fast forward to today, and the trend of downgrades has continued:
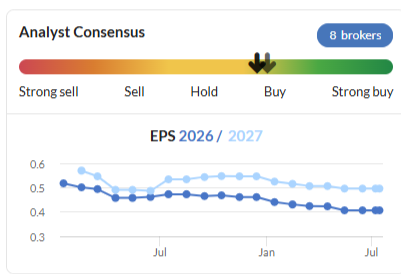
Yet the share price had doubled off the lows. What appeared to be a sensible move to start a buyback when the stock looked relatively cheap, now looks suboptimal as the valuation metrics no longer look particularly favourable:
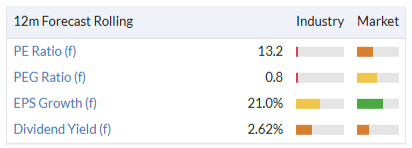
When we last looked at the company on the DSMR, Graham reflected this with a more measured AMBER view.
Today’s update:
These are the key points:
H1 2026 EBITDA of c.$62 million, consistent with the 40:60 phasing of full-year earnings guidance issued in March 2026.
H1 2026 EBITDA margin of c.12%, reflecting the continued rebalancing of the earnings profile of the Group towards higher growth segments of the global oil and gas market.
These are said to be in line with expectations:
2026 full year EBITDA guidance of between $145-$155 million is maintained, with EBITDA margin guidance unchanged at c.13%-14%.
Some quick maths shows that an exact 60/40 split would see them hit the upper end of $155m EBITDA. However, this requires some margin improvement to get there.
Last year, they reported that EBITDA increased by 7%, to $135.7m on a 13% margin. The mid-point of the current range would be a 10.5% increase, a reasonable but not outstanding result for a company trading on around 7x EV/EBITDA.
Organic Oil Recovery:
This is an exciting growth area, which I gave a summary of in February, and today they tell us that:
Hunting now has more than 30 active clients who are either sampling or field testing the OOR technology…Hunting continues to expect the business unit to generate revenue of c.$10-$15 million in 2026…Management remains confident that it can grow into a $100 million per annum business by 2030.
However, as I also pointed out in March, this was bought relatively recently (they acquired the global rights to this technology for $17.5m in early 2025), and presumably, in a competitive environment, that means they paid what the sellers thought it was worth at the time. Progress here is good, but it's not the sole reason the business's valuation has increased as much as it has.
Mark’s view
Today’s update gives confidence that the company is trading in line with expectations. However, the valuation anomaly has now closed, and the stock looks to be priced about right for a capex-heavy cyclical business. It remains a highly ranked company:
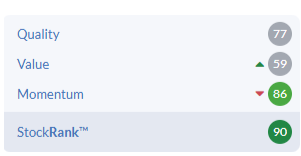
However, with the Momentum Rank declining and recent price strength not being backed by the broker consensus trend, it remains best to keep our previously neutral view. AMBER
Ashtead Technology Holdings (LON:AT.).
Flat at 411p (£332m) - Half Year Trading Statement - Mark - AMBER/GREEN =
Staying with oil field services, Ashtead Technology Holdings (LON:AT.). is another company I’ve found particularly interesting not due to the company itself but the behaviour of other investors.
For a while, it was one of the most shorted stocks on the UK market:
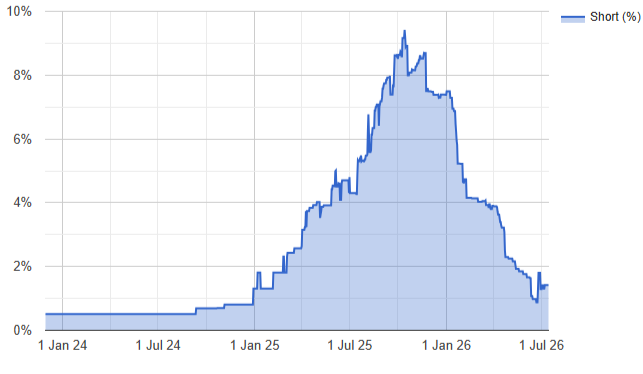
However, whatever the shorters expected to happen appears to have been avoided as the shorts have largely closed and the share price has been relatively strong since the start of the year:
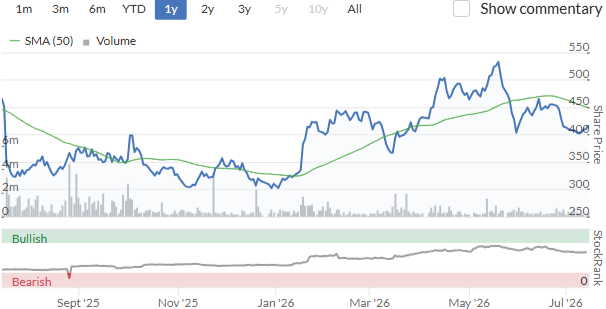
This was aided by an “ahead of expectations” announcement in January for FY25, which led Roland to increase our view to AMBER/GREEN. A view he reaffirmed when he got to see the results, saying, “Current consensus suggests further modest growth in 2026. With Ashtead shares trading on eight times forecast earnings, my view remains broadly positive.”
Guidance:
In this context, and given what has happened so far this year in the Middle East, an in-line statement looks good news:
Assuming that the disruption associated with the Middle East conflict eases through the second half, and there are no major changes to project scheduling, the Board is comfortable with full year market expectations.
They give us guidance on margins:
Adjusted EBITDA margin for the period is expected to be c.37.8% (H1 2025: 38.7%) with resultant EBITA margin of c.25.0% (H1 2025: 27.3%), marginally lower than prior year due to the revenue impact from lower rental activity in the Middle East and Asia, and an overall higher proportion of lower margin, non-rental revenues, linked to project scheduling. Margins are anticipated to strengthen during the seasonally stronger second half, with full year EBITA margin percentage target remaining in the high twenties.
However, surely it would have been better to give us the actual numbers. Thankfully Zeus save me from having to get my calculator out as their table shows EBITDA rising from £82.4m last year to £84.0m in 2026.
Valuation:
Given that the company funds their equipment hire business partially with modest debt, it makes sense to use EV measures. They give an update on leverage today, saying:
After the acquisition of Seadraulics and net capex spend of £24m in the first half, the Group expects to report leverage2 as of 30 June 2026 of 1.4x, and year end leverage is expected to be <1.0x.
Zeus calculates a forward EV/EBITDA of 5.2x falling to 4.7x for FY27. This looks good value. There is an argument that this should never be particularly highly rated as equipment rental can be a capital-intensive business. However, Ashtead’s specialism and ability to secure debt at reasonable rates against its equipment means that they generate excellent Returns on Equity:
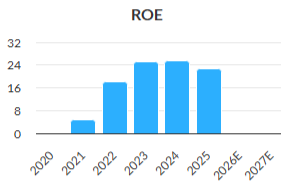
In light of this, any growth is likely to create shareholder value.
Mark’s view
I would love to know why this suddenly became one of the most shorted stocks in the UK. However, with whatever those fears were largely gone and today’s in line update confirming that they are trading at a relatively low multiple, I am happy to keep our positive view. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Site down
Beeks Financial Cloud (LON:BKS)
Excellent analysis today!
All the best
SK Hynix (NSQ:SKHY) down 10% today after jumping up 23% yesterday, SanDisk (NSQ:SNDK) down 13%...
Semis are a roller coaster it seems. Hard to comprehend what is going on with such giant cap businesses day to day, how they can fluctuate by so many billions of dollars in market cap from one day to the next. Are people leveraged to the tits to be causing this or what?
Is anyone buying the dip?
Perhaps $DRAM ETF around $50 will be a good re-entry starting position covering the whole sector.
This covers about 75% in Micron Technology (NSQ:MU) SK Hynix (NSQ:SKHY) and Samsung. Another 15% is allocated on SanDisk (NSQ:SNDK) Western Digital (NSQ:WDC) and Seagate Technology Holdings (NSQ:STX).
We have alerted our members on 02/JULY/2026 about the imminent selling of the whole memory sector.
I have sent you a more detailed DM on X.
All the best
Yiannos , Sk Hynix ADR trading at a big premium to Korean shares is it betters to buy the shares ?
Maybe its the heat, but I'm about to put my 'grumpy pants' back on! Up until this morning I was a relatively sanguine holder of Barratt Redrow (LON:BTRW). A company doing OK with a difficult, but just about manageable, housing market backdrop. Whilst waiting for the next cyclical upturn I was happy enough to take the 5% dividend income. However, all of a sudden today we have a complete shift of capital allocation. A nice headline grabbing £400m share buyback but, by the way, we aren't going to pay you a dividend any more (unless you call 1p a share a dividend). Incidentally this will save the company c£244m per year.
Since when was it OK to pull the rug on income investors, just because the current vogue is buybacks?
Sparkler, it is an annoyance. I bought BTRW because it looked cheap compared to Asset value and the yield was OK.Not sure a £400m buyback will make much difference to reducing the discount in a £3.92BN company. Boards don't seem to get this but great business for the broker who advises them-lots of fees on the buy side. Broker's earn nothing from dividends. I am sort of waiting for some-one to come along and bid for the company. Unlike many I accept bids- it is a sign of market inefficiency- which the blame has to be attached to institutions .
But on the buyback/dividend they may find they have shot them selves in the foot. Not sure what funds Fidelity hold it in, for example, but if they needed the dividend they will be selling.
The directors hardly have meaningful holdings-about time they were all made to take a % of fees in shares, or use the fees to buy shares. All they do is get paid well and make poor calls on issues like this.
Thanks Mark on your analysis on Beeks Financial Cloud (LON:BKS)
One of the big questions that any investor will need to figure out for the investment case, is how profitable Exchange Cloud will be. As they moved to a rev-share model, with the upfront capex (and getting more expensive now), the company is taking on extra commercial risk.
It is interesting that they state that Kraken and ASX have moved into positive profit monthly now. Kraken was deployed near Jun25, and ASX between Jun-Dec25 from my notes?
So that means, on an EBITDA profit level it takes Exchange Cloud deployments 6-12 months to get to monthly profitability. Not too bad. The key omission which the company has never guided yet, is when Exchange Cloud sites get to EBIT site level or even PBT site level profitability, and how long it takes to payback the initial cash investment. I guess it is still too soon to tell, as Kraken and ASX were the first exchanges under the new rev-share model.
This has implications for the net cash/net debt as Mark highlights, as they roll out more and more rev-share Exchange Cloud contracts. Also with the increase with hardware costs now, the timeframe to recoup the initial investment gets longer.
i hold shares in NextEnergy Solar Fund (LON:NESF) and take note that an RNS of today states that NESF is up for sale now. The company created a strategic seminar in March this year which can be found on the company website. Below is the list of options under consideration at the time.
I hold at a loss. Hopefully some-one will make a bid near my buy price. Infrastructure funds have not been great for me.
Anything renewables infrastructure related has also be pretty disastrous for me too. Only have left Bluefield Solar Income Fund (LON:BSIF) which Drax is in the process of acquiring. I just hope someone comes in with a bid for Gore Street Energy Storage Fund (LON:GSF) which is down c. 7% today. When I am rid of these two I won't be going near any renewable infrastructure investment trusts - too many moving parts for me to understand!
Too many poor boards as well- hoodwinked by the well paid managers.
Re Ed Miliband potentially allowing North Sea oil and gas drilling. It would be good to have some analysis on which companies would benefit from that.
Serica Energy (LON:SQZ)
Ithaca Energy (LON:ITH)
Enquest (LON:ENQ)
Harbour Energy (LON:HBR)
All the best
My good friend Gemini states the following top 4 (of which Yiannos1 has already highlighted, is he a real person or AI?)
If the UK’s ban on new North Sea oil and gas exploration licensing were rescinded, independent UK independent exploration and production (E&P) companies would gain the most, followed by select UK supermajors and US oilfield service giants.
While large US producers have mostly divested from the aging North Sea basin to focus on US Permian shale, specific publicly listed corporations across both nations stand to capture significant value:
1. UK Independent E&Ps (The Direct Winners)These pure-play upstream operators have their valuations heavily tied to North Sea volumes and regulatory approvals. Lifting the ban would immediately revitalize their project pipelines.
2. UK Supermajors (Diversified Winners)For the largest oil companies, the North Sea is just one part of a global portfolio, but a policy reversal would remove immense regulatory and legal friction. [1]
3. US Listed Companies (Infrastructure & Services)US supermajors (like ExxonMobil and Chevron) have largely exited UK waters. However, US companies would win heavily on the oilfield services and technology side
Crucial Strategic Considerations
The Lowest Production Cost Winner: Harbour Energy (LON: HBR)
The Highest Dividend Yield Winner: Ithaca Energy (LON: ITH)
The Mid-Cap and Outlier Plays
I already own Harbour Energy (LON:HBR) and Serica Energy (LON:SQZ) so do I want another energy company but that 10% yield on Ithaca Energy (LON:ITH) looks appertising.
I am a RI.
Real investor!
All the best
Given the nature of your posts, which I thoroughly enjoy even where I differ, I have never doubted the 'reality' of yiannos1.
“If the UK’s ban on new North Sea oil and gas exploration licensing were rescinded.”
This is not on the cards under red Ed. The only reason Jackdaw and possibly Rosebank are being considered is because they were approved before the ban (is my understanding).
I think the rumour being referred to is that if Ed were appointed Chancellor he's willing to backtrack on north sea to show pragmatism and please the markets
I am not wasting time thinking about it all though, we'll see what happens and then react when we know.
I sold Serica and Ithaca during the massive oil prices of the Iran conflict and not tempted back in as of yet, long term oil prices should be falling and the best days of the North Sea are behind it. Serica is also super crash prone due to running ancient rigs. There may yet be a time to buy but imo now is not it.
Yes agreed it is a very cynical ploy to get the no.2 job. However, can he be trusted as he is an ideologue. But if it were to happen there may be some good investment opportunities.
Thank you for this very detailed analysis!
excellent analysis thank for sharing, also think Hunting with its oil recovery project would benefit from change in regulatory requirements
Oil picks and shovels play Ashtead Technology Holdings (LON:AT.)
Would appreciate it if you could do even a brief note on Zegona Graham as I can see no reason from the Q1 results for a 6% fall. Many thanks
Anglo Asian Mining (LON:AAZ) My appreciation to Donald Pond the man who understands mining!
Appreciated. Anglo Asian Mining (LON:AAZ) is a rare example of an AIM company that never issues new shares, avoids debt where possible, and is capable of bringing major projects into production (2 new mines in the last 12 months). They also have a lot of projects that arguably aren't included in the share price: when the company IPOd, it was all about Ordubad, a site that has yet to be progressed (it's in a landlocked province of Azerbaijan but as tensions with Armenia reduce it will become easier to progress). And with Xarxar and Garadagh due to come into production in 2028, the route to increased production is clear.
It is simply a great example of a company with excellent management and superb engineering. Also, with 40% of the shares owned by the board, a testament to the value of companies that are, in practice, run like family businesses. That can be frustrating with the lack of promotion at times, but over the long-term it creates huge value.
Would appreciate your thoughts on Beeks Financial Cloud (LON:BKS) trading update
Audioboom (LON:BOOM) looks as if the summary relates to another company.
that's fixed, Chris!
Yes, I'm having a bit of trouble with news links today - I'm able to access them from the StockReport, not from the table. Hopefully it can be fixed soon. G
Great RNS from Tufton Assets (LON:SHIP) this morning. A record quarter, increasing NAV and a 10% increase in the quarterly dividend to boot (geddit?). Certainly won’t do the share price any harm at all.
It’s an ill wind that blows nobody any good. (I hold)
Anyone else having problems accessing links?
Barratt Redrow (LON:BTRW) in line update, expect to return £400m to shareholders.
Good morning Graham,
Any chance you could add Ashtead Technology Holdings (LON:AT.) and Bloomsbury Publishing (LON:BMY) to your deep dives today?
that's been noted, Felix!
site down again!!!!! will leave if this continues not good enough
But go where? I cannot think of another place with the screener and QVM stock ranks system. I’ve built out my own screener so I can fully automate trades off it but what you get here is fab and very comprehensive by the standards of the investment industry the quality of the data is strong as well. A major data provider I use provides garbage for bank revenues as their reporting is different. Stocko is generally better.
Outages can be frustrating what would help is improved comms. Most stuff on here isn’t super time sensitive but I do like the RNS scanner at 0700.
Toys out of the pram stuff tends in my experience cause technical people to go into there shells and hide. You win more friends with honey than vinegar.
The last one to switch off the lights please!
It’s worrying that there is no mention of SK Hynix (NSQ:SKHY) today (in the introduction of the DSMR) about yesterday’s performance on Wall Street. Not that anyone cares but since the KOSPI is mentioned continuously when it’s down, then the correct thing is to update on any changes or stop mentioning it.
All the best