Daily Stock Market Report (Wed 15th October 2025) - OMG, HERC, JUP, RNK, SDG, AOM, THX

Good morning!
All done for today, thanks everyone.
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Entain (LON:ENT) (£5.37bn) | FY25 guidance reiterated: c. 7% online NGR growth (constant FX), EBITDA £1,100m to £1,150m. | ||
Rathbones (LON:RAT) (£2.08bn) | FUMA up 3.7% (to £113bn), net outflows £0.6bn. Operating income up 7.2% year-on-year to £236m. | ||
| CVS (LON:CVSG) (£1.0bn) | Response to CMA provisional decision announcement | Continues to expect to trade in line. Welcomes additional certainty, pleased to see CMA considered CVS’ and veterinary profession's feedback. | |
Jupiter Fund Management (LON:JUP) (£799m) | Q3 net inflows £0.3bn, AUM up 7% over the quarter to £50.4bn. Acquiring CCLA in Q1 2026. | GREEN (Graham) [no section below] It’s wonderful to see some inflows in this embattled sector, even if they are modest. Jupiter are quick to point out that it’s not a blip: with three quarters done, they are marginally positive year-to-date when it comes to flows. AUM grew by an impressive 7% in the quarter thanks to strong underlying market movements: with AUM now at £50.4bn, the shares currently offer £63 of AUM for every £1 invested. Much of the value has been squeezed out by the share price having more than doubled over the past six months: it took a long time, but my faith in this stock has been justified at last! Looking forward, the StockRank is now 98 (it’s a Super Stock) and investors can look forward to the CCLA acquisition booting AUM by c. £15 billion - funded from existing cash resources, with no dilution. Taking that account, value will rise to c. £82 of AUM for every £1 invested in the shares at the current level. To me, that’s still a very interesting valuation. It’s a little pro-cyclical of me, but I’m willing to stick my neck out by upgrading this by one notch to fully GREEN. Retail flows - not institutional - have driven the recent flow performance, which I think is a very positive sign of renewed sentiment and interest in the Jupiter fund range - long may it continue. | |
Pagegroup (LON:PAGE) (£768m) | 2025 operating profit to be broadly in line with current market consensus of £21.5m. Q3 gross profit down 6.7%. | ||
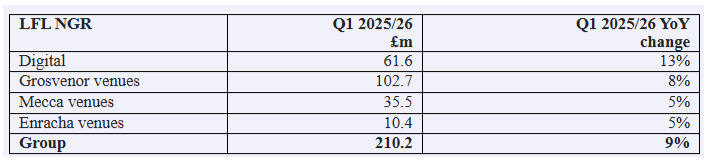
Rank (LON:RNK) (£607m) | Q1 like-for-like NGR up 9% to £210.2m. Confident of delivering like-for-like operating profit in line with expectations. | AMBER/GREEN (Graham) It's a nice update and I'm tempted to raise my stance on this back to fully GREEN. In StockRank terms, this is a Super Stock with improving Value as optimistic FY26/FY27 earnings forecasts come into view. However, the CEO notes the risk of increased taxes in the forthcoming UK budget. Having looked into the proposals (from 101 government backbenchers), I think I'd prefer to retain my moderately positive stance here, pending clarity. | |
Thor Explorations (LON:THX) (£491m) | Q3 gold poured 22,617 oz. Production guidance maintained at 85k-95k oz. AISC guidance maintained at $800- $1,000. | AMBER/GREEN (Mark) [no section below] | |
Brooks Macdonald (LON:BRK) (£276m) | FUMA up 3% in Q1 to £19.7 billion. Q1 net outflows £49m. | ||
Midwich (LON:MIDW) (£193m) | Group FD leaves to become CFO of RWS, is thanked. Will remain to ensure a smooth transition. Search process initiated. | ||
Activeops (LON:AOM) (£121m) | SP +27% Double digit revenue growth, anticipates full year revenues will now be comfortably ahead of consensus expectations (exps: rev £40.3m, PBT £1.7m). Cash of £13.3 after £5m acquisition of Enlighten, a “workforce optimisation software and services provider with a strong footprint in North America and Asia Pacific“. | AMBER/GREEN (Graham) [no section below] I’m compelled to upgrade our stance on this by one notch after this exciting update. But when I check the new estimates at Canaccord Genuity (many thanks), I see that their revenue estimates are raised at a more modest pace (4%) than today’s share price reaction would have suggested. I also note that there is no change to EPS or adjusted PBT estimates, save for a slight decrease in this year’s EPS estimate. It might well be conservative, but I find it striking that an additional £2m added to the revenue forecast for each future financial year leads to no change in the profitability estimate. This year’s 34% organic revenue growth will be very much a one-shot success, to be followed by periods of much more modest growth, if these estimates turn out to be accurate. At least the company does already have a healthy cash position, and so it should not be reliant on cash profits to fund growth. In the SaaS sector, annual recurring revenue can easily be valued at a multiple of more than 3-4x, so I don’t think that today’s market cap of £150m is particularly expensive given ARR of £40.6m (with organic growth just seen of 27%). Therefore, while this will continue to look very expensive against EPS for the foreseeable future, the valuation does arguably make sense - and is even cheap - in a software context. | |
Audioboom (LON:BOOM) (£111m) | Q3 Revenue +9% to $20.4m, Adj. EBITDA +18% to $1.2m, cash $2.9m (30 Jun: $2.5m). $79m revenue booked for FY25. | ||
Oxford Metrics (LON:OMG) (£45m) | Group revenue broadly in line with market expectations. Headwinds around US academic funding. Adjusted EBIT in line with market expectations for the FY of £2.3m. Cash £37m (FY24: £50.7m) after £5.4m spent on acquisitions and £12.5m of dividends & buybacks. | AMBER (Mark - I hold) [No section below] | |
Getbusy (LON:GETB) (£42.3m) | SmartVault now integrated with Intuit ProConnect Tax, Intuit's flagship cloud-based tax preparation and advisory platform. | ||
PROCOOK (LON:PROC) (£37.6m) | Q2 revenue +25% to 21.3m (12% LFL), gross profit margin and costs in line with expectations. Net debt £4.1m (25H1: £4.2m). Confident in delivering full year performance in line with market expectations. | ||
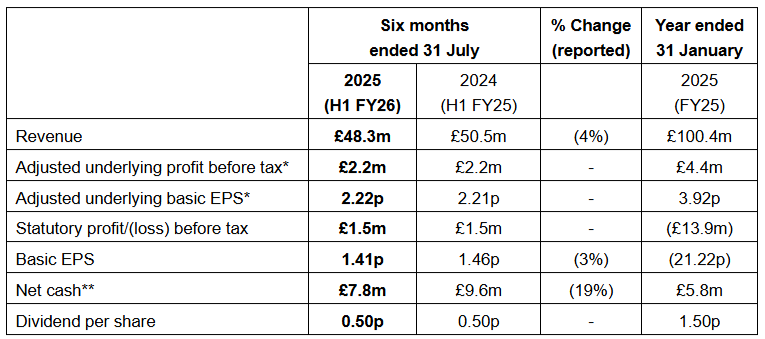
Sanderson Design (LON:SDG) (£34.3m) | H1 Revenue -4% to £48.3m, licensing +6% to £4.4m, Adj PBT flat at £2.3m Adj EPS flat at 2.22p, Net cash £7.8m (25H1: £9.6m, FY25: £5.8m), dividend held at 0.5p.Cost cutting complete. Brand sales +5% CCY so far in H2, confident of meeting FY expectations. | AMBER/GREEN (Mark - I hold) | |
Hercules (LON:HERC) (£27.3m) | Acquired a 70% shareholding in Warrington-based Lyons Power Services for £703k (£351k cash, £351k shares at 5-day VWAP). Lyons Power FY25 revenue £1.39m, PBT £0.29m. | AMBER/GREEN (Mark) [No section below] | |
Alkemy Capital Investments (LON:ALK) (£24.9m) | H1 LBT £1.13m (24H1: £0.68m), Net debt £0.48m (24H1: £0.4m) after raising £0.71m during the period. Focused on advancing TVL through the FEED study to FID. | ||
Tap Global (LON:TAP) (£13.9m) | Launch of corporate customer programme with 25 business customers, worth £75k. | ||
Light Science Technologies Holdings (LON:LST) (£13.2m) | AgTech division extended its distribution framework agreement to distribute products developed by Gavita for a further 12 months. £24m sales pipeline. | ||
IXICO (LON:IXI) (£11.1m) | New 3-yr contract to assist in the validation of a diagnostic blood test and contract extension on an existing Alzheimer's Disease clinical trial worth £1.2 million combined. |
Graham's Section
Rank (LON:RNK)
Down 1% to 128.24p (£601m) - Trading Statement - Graham - AMBER/GREEN
Pleasant news from this casino/bingo group: all businesses growing in line with expectations.
I’ve been GREEN and AMBER/GREEN on this, most recently taking the slightly more cautious stance in August on publication of its full-year results for last year.
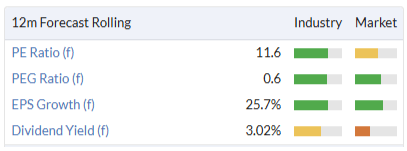
However, as the positive estimates for FY26 and FY27 start to come into view, perhaps there is still good value to be had here?
Even with a 60% share price gain over the last six months, the forward P/E is not prohibitive:
Let’s dig into today’s Q1 update a little:
Digital - Rank is keen to highlight its online presence, and it has been a nice source of growth. Grosvenor Casinos are the main driver here, with their digital UK revenues up 31% year-on-year.
Grosvenor - a nice spread of increased visits (5%) and higher spend per visit (3%). New regulations on land-based casinos have enabled the installation of hundreds of new gaming machines. In total 850 new machines will be added.
Mecca (bingo) - steady revenue growth but visitor numbers slightly down.
Enracha (Spanish casinos) - steady revenue growth.
CEO comment:
We have started the year strongly and are confident of delivering Group like-for-like operating profit in line with expectations, notwithstanding the significant cost increases we have incurred in employer national insurance contributions, the national living wage and the new statutory levy.
There’s also a comment on tax:
Speculation regarding tax changes in the upcoming Budget is, inevitably, hanging over the business. We are engaged with the Treasury on the implications of tax changes on the viability of our venues, employment levels, future investment and the customer. Last year the Group generated £44.6m in profit after tax, having paid HMRC and local authorities £188.0m in taxes. The Rank Group, with its strong UK focus, is certainly paying its fair share.
I note that over 100 Labour backbenchers have called for an increase in Remote Gaming Duty, amplifying calls from the Institute for Public Policy Research to increase it from 21% to 50% of the operator’s “gross gambling yield”.
Graham’s view
I was tempted to raise my view on this back to GREEN, as I do greatly admire the company (and its venues!). However, as there is a real and imminent threat of tax increases, I’ll hold my existing stance.
One thing that Rank followers know well is that the company’s profits can easily evaporate due to its heavy fixed costs - and the emphasis on Digital was presumably supposed to offset this. But if rising fixed costs aren’t offset by higher revenues in a timely manner, or if revenues take an unexpected hit, then the income statement gets ugly - this happened during Covid of course, but also in the inflationary period that followed. Perhaps tax rises on Digital could be the third time in less than a decade that the company’s profits are hobbled? I hope not, and I’ll keep my moderately positive stance, but it’s something to keep an eye out for. This year’s budget is on November 26th.
Mark's Section
Sanderson Design (LON:SDG)
Up 6% at 50p - Half Year Results - Mark (I hold) - AMBER/GREEN
On the surface, this is a relatively uninspiring half for the company, with revenue down slightly and most other figures flat on the previous year:
Cost savings:
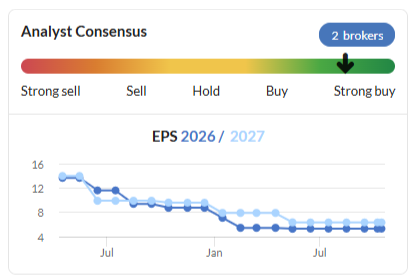
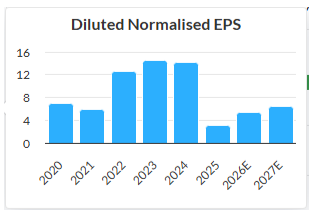
The narrative is one of cost savings to protect margins and they have now delivered cumulative annualised cost reductions of £4.8m over three years and £2.5m in the latest programme. I have a theory that they were caught out by the severity of the downturn in revenue in their key markets and were slow to cut costs. This is why the medium-term EPS trend looks like this:
My other theory is that the strength of the licensing revenue meant that they were initially reluctant to cut costs. However, the nettle has been grasped, especially in manufacturing:
The factory restructuring completed in the first half of this year has reduced costs, increased efficiency and delivered a much more flexible workforce able to respond to market demand and to the requirements of digital printing. There is positive momentum in our current manufacturing order books, with a better mix of new collections and repeat orders compared with the same time last year. We continue to expect the manufacturing segment to achieve break-even, or slightly better, for the current financial year.
There are some other low-hanging fruit that appear to have been picked, too:
Our approach to issuing these pattern books has changed compared with the prior year. Under the old "book scheme" members paid a monthly fee to receive a pattern book for all new collections. Under the new loyalty scheme, members pay for each pattern book on an individual basis. This change has seen a reduction in both Other operating income and Distribution and selling expenses, and a net saving to the Group of £0.7m compared with H1 FY25.
Licensing:
In terms of licensing revenue, this is another bright spot, with the company saying:
Licensing revenue, an important strategic focus for the Group and a key profit driver, continued to perform well in the first half with revenue up 6% at £4.4m. Importantly, there was strong growth of 22% in licensing's underlying performance (licensing revenue excluding accelerated income under IFRS15) reflecting both new agreements from last year which have moved to product launch and increased on-going sales from existing licensees.
However, this increase comes off a recent low for underlying licensing revenue, and is perhaps less impressive with a historical context:
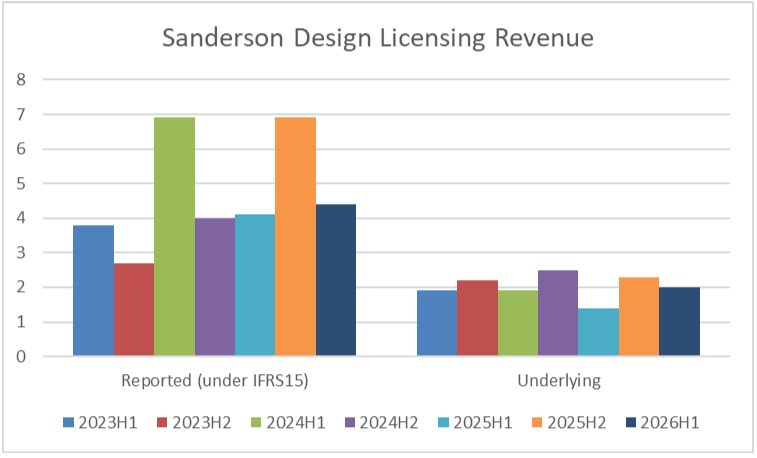
Over time, I would expect underlying licensing to track closer to the reported licensing, but it shows there is still some way to go before this is a significant contributor to cash flow.
Brand sales:
In terms of brand sales, Europe and the ROW seem to have bottomed out, but the UK sales continue their downward trajectory:
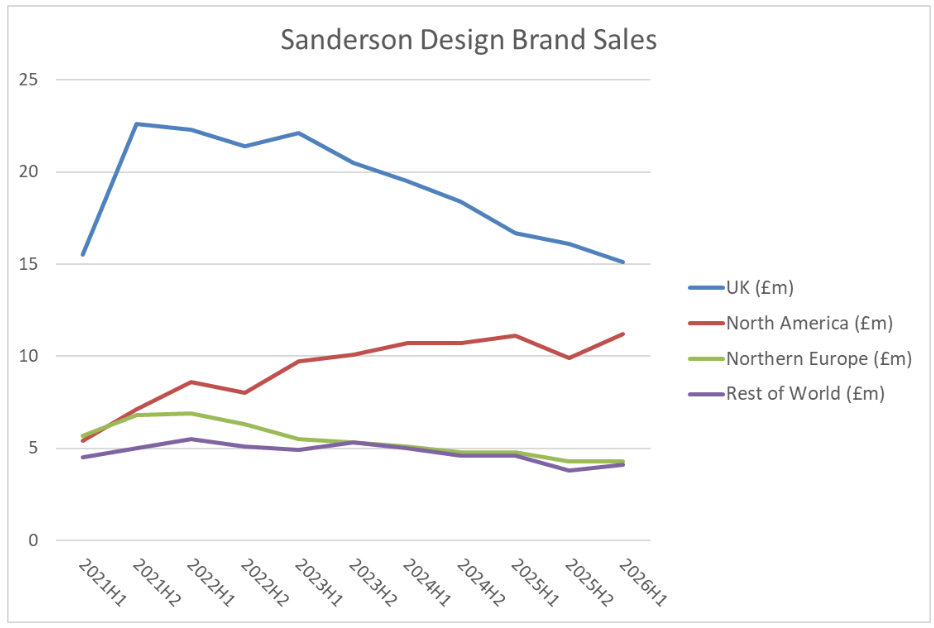
North America continues its medium-term growth trajectory, but there are some risks here:
From 29 August 2025, the US government removed the $800 de minimis threshold for commercial shipments into the USA. The majority of our US shipments fell below this threshold and so recently we have begun to incur tariffs and administrative charges. We have moved swiftly to recover the additional costs from customers via a surcharge on invoices whilst the tariff situation, which continues to evolve, becomes clearer.
Unlike Colefax, who sell through distributors, it seems the vast majority of Sanderson’s NA sales are made direct to interior designers or similar and shipped from the UK. This means that they haven’t benefited from the big push to source product into stock before tariffs came into force. Presumably, they will face less of a reduction in demand post-tariffs, although the impact of the associated price rises is yet to really hit.
In terms of brands themselves, most follow similar trends, although there is a notable uptick in sales for Morris & Co. in H1:
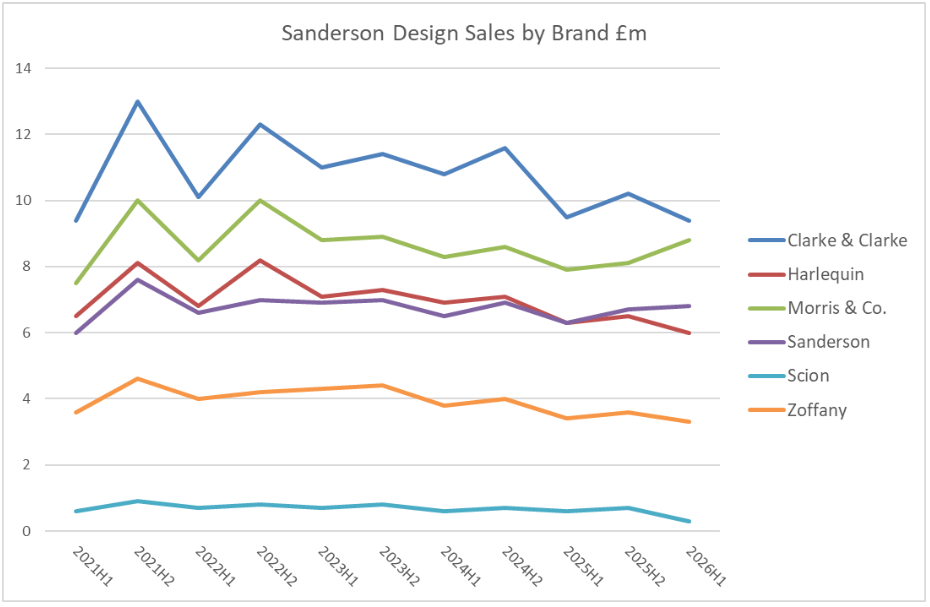
Scion is struggling. Although this brand is far more important in terms of licensing deals than direct sales.
The trends for brand sales are encouraging with a 5% rise in CCY sales in H2 so far:
As noted in the Half Year Trading Update issued on 7 August 2025, brand sales in the nine-week period of June and July 2025, although slightly below the same time period last year, were on an improving trend compared with the full six months ended 31 July 2025. This momentum has continued into the current half year, and brand sales in the first 9 weeks of the second half are up 5% at constant exchange rates compared with the same time last year.
It would be nice to have got some regional breakdown, though.
Manufacturing:
External manufacturing sales appear to have bottomed and look to be starting a modest recovery:
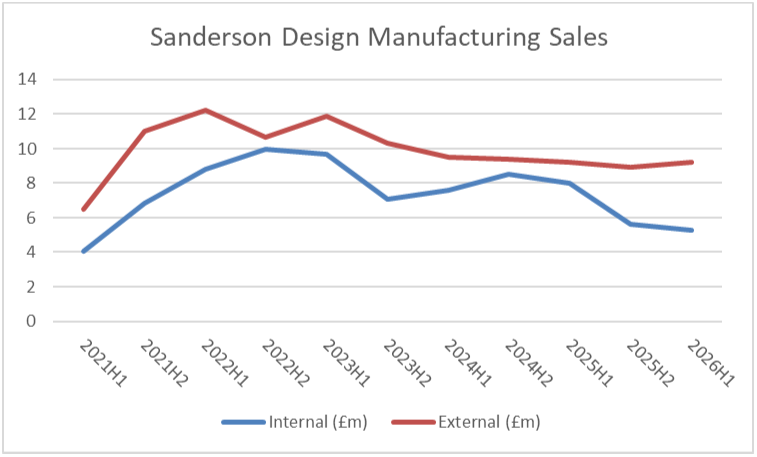
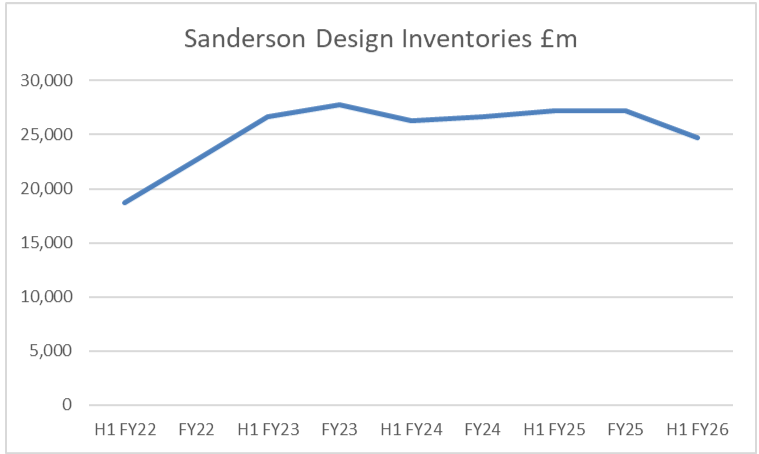
Internal sales are lower, presumably as the company chose to sell from inventory. This has led to inventories declining to £24.7m from £27.2m the year before and the flag scope for further reductions in the future.
Cashflow & Balance sheet:
As well as the decline in inventories, the company has spent very little capex during the period. Payables have remained static, but receivables increased by around £1m. This meant that cash increased by around £2m. The current ratio is over 3, meaning that the balance sheet is very strong.
Total equity increased slightly to £69.2m from £68.7m, although £10.7m of that is Intangibles, and £2.2m is a pension surplus which is largely an accounting fiction as they continue to make payments to the scheme in excess of the pension charge. This gives £56.3m tangible book value if we assume the pension scheme deficit is zero, or £51.3m if we take my guess of £5m for the buyout costs of the remaining scheme. This compares favourably to the c.£37m market cap today.
While value investors, such as myself, tend to focus on tangible assets, I don’t think the intangible assets here are worthless. After all, intangibles are generating something in the region of £10m high-margin revenues each year. The big question is how soon can the tangible assets be made productive again?
Forecasts:
The company say that “We remain on track to deliver results in line with the Board's expectations for the full year." However, £102m revenue consensus with £48.3m in H1 leaves £53.7m to do in H2. That’s 8.5% higher than 25H2 and 11.1% higher than 26H1. It is clear that they will need sales to accelerate beyond the 5% CCY so far in H2 if they want to reach that figure. So its is perhaps unsurprising that research provider Progressive say they have “trimmed back top-line forecasts”. They now have £101.2m, for a perhaps more reasonable 6.9% H2 growth in sales. Perhaps more importantly they say:
Our FY26E and FY27E underlying adjusted PBT forecasts remain unchanged following these interim results, at £5.0m and £5.7m, respectively. Likewise, our year-end net cash forecasts remain unchanged at £8.5m and £11.8m, respectively.
This means that these valuation figures remain valid:
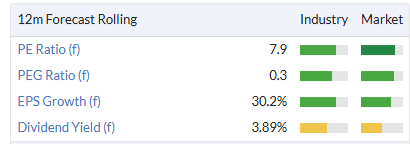
Which makes them look good value. Especially as I don’t see why they won’t return to double-figure EPS in better market conditions:
Mark’s view
Having gone through all of the aspects of the business, these results seem in line with recent trends. Strong licensing and US sales offset weakness elsewhere, but the real financial recovery comes from cost-cutting. While cost-cutting can only get a company so far, it does place them in a good position when sales recover. Ultimately I don’t see anything to change my view that this is exposed to the housing market cycle, and when general market conditions improve, so will their financial results. In the meantime they have a strong balance sheet and are generating cash, so have time on their side. A slight downgrade in revenue forecasts is disappointing, but understandable. However, it is profitability that matters and even on depressed sales this looks cheap. Partly this is due to continued strong high-margin licensing sales, but I continue to believe that the licensing side alone is probably worth more than the current market cap. I keep our AMBER/GREEN view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
I'd like to flag up some really bad behaviour of management in writing a HY results statement...
My comment is 8 days late on Sanderson Design (LON:SDG). But I felt so strongly I need to share.
HY results statement.
You would expect, if the biggest division responsible for 72% of revenues, had a -7% drop YoY causing the overall -4% drop YoY in revenues....
That this would at least be mentioned in the top highlight bullets, with an explanation.
No.... management only give all the positive news there, and you have to go way into the details to find that out....
Technically, not a crime, right? As long as all the information is presented in the looooong document.
But as a shareholder, why would you invest in a company that cannot be upfront transparent with its owners?
And this isn't the only trickery I have found in the HY results. Plenty of other things - like not consistently reporting recurring/repeat/underlying licensing income, across all the HY and FY results. Unless it paints a positive narrative, then it comes out.
Despite what I think may be a good price to buy, Sanderson now goes on my bargepole list.
Just to back up Ed's comments re Jupiter Fund Management (LON:JUP) a lot of the flows will be going into their gold & silver fund Ned Naylor-Leyland is the fund manager and he is excellent in this area.
He's also a great speaker on the subject would be worth Ed and the team seeing if they could get him on the Stocko channel to do a podcast as you could listen to him for hours.
Ceres Power Holdings (LON:CWR) The multi bagger bought at the right price. I'm in danger of returning to profit after a very long time. My Hydrogen related ETF L&G Hydrogen Economy UCITS ETF USD Acc (LON:HTWG) also has a rocket under it. I suspect AI power requirement related.
Re Hydrogen
Its only a guess - but there have been trials recently reported where 3% Green Hydrogen has been added to conventional gas supply in UK.
Reported that ultimate objective would be to add 5%. This news might have been the catalyst for price rises.
I was given a tour of a University facility yesterday, very interesting even if I didn't know the difference between Green, Blue and Grey Hydrogen to start with.
Yes, one of the statements about where is the product demand for Hydrogen is the testing to date has proven a level of Hydrogen can be mixed/added to natural gas and still burn safely and efficiently on all currently installed gas burners (e.g. boilers, gas rings, front room fires etcetera), so therefore we can carry on with the existing usage but decarbonise a portion through doing this with hydrogen hence achieving part of the step target.
Caution required on potential for leaks when looking at residential and distribution network due to molecule size and other issues. (UK boilers have been spec'd for up to 20% H2 mix for about 5 years.)
https://ecostandard.org/news_e...
I see initial usage focussed on commercial large operations such as fertiliser Atome (LON:ATOM) , Power ITM Power (LON:ITM) and AFC Energy (LON:AFC) , as well as use of technology, such as Ceres Power Holdings (LON:CWR) to use cheap electricity to create the hydrogen as an energy store.
I hold all
If into gold or silver stocks subscribe to the Daily Gold. Mostly Canadian stocks though. Lots of knowledge in it.
The Skier......thank you.
I see LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) update has lifted a few HK stocks such as Burberry (LON:BRBY) and Watches of Switzerland (LON:WOSG).
Graham - I read the Jupiter release with interest this am. You said above:
"Retail flows - not institutional - have driven the recent flow performance, which I think is a very positive sign of renewed sentiment and interest in the Jupiter fund range - long may it continue."
This is very much the theme that we opened our webinar with... the Peel Hunt trading statement recently was ahead of expectations on increased equity capital markets activity. I note they are involved in the Princes IPO which also is going to be offered on Retail Book - so private investors might be able to access too.
While JUP mentioned the gold & silver fund flows are strong... my thesis is that after a year of stronger UK markets, we'll start seeing more domestic fund flow improvements - there's always a lag.
I'm still optimistic in spite of the worries all over the press about crashes, gold going vertical and so on. I note that Rachel Reeves is going to be changing ISAs to encourage more stocks and shares investment - good FT piece on this today. Pensions after that?
Will Kenmare Resources (LON:KMR) be covered today?
The update today is disappointing but inevitable they will suffer ups and downs. What is more disappointing is that one of their clients is in difficulty and withdrawn from the Mkt. Suppose we should be thankful they did not actually default on payment. Meanwhile the stock is paying a good divi - one for the patient holder
I also would be interested in any coverage on this. Interesting company to analyse imo.
I also hold Oxford Metrics (LON:OMG) , Mark, and I share your relief that numbers are going to be broadly in line for the full year. If the Vicon business ever delivers consistently on its significant potential (maybe with 'markerless' as the catalyst) then this is a very cheap entry point for the shares.
I think the rise in pet insurance has to carry a lot of blame for increased prices.
Once it's an insurance job there's no incentive to keep prices down or moderate the number of tests etc. Sure it causes insurance to rise and premiums to go up but that's somewhat hidden compared to a bill.
There is that, think how often when you report a loss to the police they say " you are insured, aren't you?".
Just seen on Citywire that Nick Train has bought into Games Workshop (LON:GAW) for his £FGT. Oh dear - hope its not time for me to sell up and move on
Games Workshop (LON:GAW)
maybe he is a stocky subscriber and has realised its got the rare "100" score ref "quality" - i dont remember having seen many "100" quality ratings for companies - oopo i think it might be in a club of one in thar regard.
I have alwasy been reluctant to pay the top dollar price here - trending earnings looks fine though and i would say p/e of 25 for sucha quality company doesnt seem ott - if one is confident of long term propsects. I have always been slightly worried it might be slighlky faddy what they do - i think that viewpoint is probably wrong and they should possibly be compared to lego which is an enduring classic brand. Notr sure what other people think.
looks like they are having slight blip ref forecasts this year albeit looks like thats been flagged up for some time - is that due to increased corp tax and extra NI etc ? or other one of reasons ? perhaps prior year profits benefitted from one of gains ? that might make more sense.
so not being a chartist i can see why one might be adding now as pes forecasts are trening nicely anbd price has droped back from mid summer peak. Not sure what charists would make of this one momentum numbers looked mixed at best - so perhaps looking for some positive trend before adding for tose that want to add mighbt be the way to go - by thne though price might be back at 1600p :)
looks like they are having slight blip ref forecasts this year albeit looks like thats been flagged up for some time
Before you pay any attention to the forecasts for Games Workshop (LON:GAW) I would encourage you to go back 5 or 6 years and see how actual performance compares to the forecasts. Spoiler - they are usually way too conservative.
Feels like something you should have been buying 5 years ago - feels a bit late for any further major upside, but no doubt a very high quality company.
I'd appreciate comments from any holders of Ninety One on their increased AUM announcement yesterday. Roland covered it at Amber/Green moderately positive on June 14th. It's rallied 30% since then and I'm sorely tempted to take the profit on our medium size holding. We're also long term Sanderson Design holders, breathing a sigh of relief with today's results and held dividend, the increasing licensing profit keeps me in there.
Not on your list but you might want to have a look at Activeops (LON:AOM) which is up about 16% as I write after very strong trading update this morning with organic revenue growth of 34% and inorganic of 43%.
ARR is actually up 50% and they managed to pay for an acquisition during the period with the FCF from that period. They have a software for operations allowing companies to both monitor activity of their teams but also help predict and improve processes going forward (I hold)
CMA vets preliminary report out today (finally): https://www.londonstockexchang...
The remedies proposed aren't insignificant but are mainly about providing better information. Smaller vets have longer to implement but I'd guess will find it harder to absorb the costs. There's nothing about divestment or limiting further expansion.
Too complex to know how it'll pan out but I'd guess this will lead to more market concentration but reduced margins. Will be interesting to see how Pets at Home (LON:PETS) and CVS (LON:CVSG) react today.
Still only provisional - final report not due until next year.
timarr
Just gave it all a quick skim read. All seems fairly basic stuff that they are recommending (subject to consultation). I would guess Pets at Home (LON:PETS) and CVS (LON:CVSG) could do 10% today.
Having just spent £943 at a large multi practice vet for a cat with constipation, I don’t think this report goes anywhere far enough. The whole industry is a complete rip-off and whilst CVS might be a money-spinner, on moral grounds, I could not, EVER, invest in this company.
Definitely feels like they are one of the sectors that used Covid as an excuse to raise prices far above their increased costs, with the feeling they could get away with it because everyone was doing it together and in the end if you need to use a vet, you need to use a vet.
Yet the average operating margin for CVS (LON:CVSG) works out at 7.73% and the ROCE a measly 9.58% .... they make about 2% over their weighted cost of capital. This does not speak to either price gouging or a particularly attractive business.
The fact is there is a shortage of vets - a clinical director of a corporately owned local practice will be on circa £88,000 to £100,000; yet there is a constant battle to retain staff. The corporate chains are now squeezed between ever rising staff costs and the CMA.
We keep 30 horses and our veterinary bills over the past 30 years are in excess of £250,000. (less than £300 per horse per annum as we do what we can legally ourselves). We self-insure ... insurance would have been about £750,000 over the 30 years. We recognise the costs of the equipment, which runs into millions for equine care, scanning and surgery and the costs of recruiting highly qualified and motivated young vets. This is not an expensive hobby but a business and, like the farm, we look at equines through business eyes.
I think, because most of us are insulated from the direct costs of human medicine, we have a poor understanding of the true costs of delivering clinical care. Consequently, we are shocked at the size of our veterinary bills. As our vet says, keeping a pet is not a human right and many people should not be allowed to keep pets given the level of ignorance.
We are left with the question as to whether or not CVS (LON:CVSG) is a good business or not. I owned it briefly to trade it through the CMS decision as I was sure the CMS report would be less onerous that the market thought. I sold before the final report was published, confident I had extracted what value there was. I do not consider a business making such paltry ROCE, a good long-term investment. There is a runway for CVS (LON:CVSG) in the Australian market where vets are cheaper and margins higher and CVS are allocating capital to that market. Although, margins and ROCE should improve as the geographical mix changes, I am not enticed. Good luck to those who are.
Is there any correlation between the well-equipped pet surgeries (many better than hospitals) and the seemingly well-padded charges applied? I don't hold any shares in listed vetinary companies.
As a counterweight to your comment, I have a friend who works for CVSG and another who owns a veterinary practice. Both point out that a population accustomed to free healthcare at the point of use is poorly educated as to the true cost of medical services, whether they be for human or animal. Do you expect vets to be paid like shop assistants while they perform life-saving surgery in expensive to maintain facilities? Do they have the purchasing power of the NHS when stocking their drugs?
Margins are lower than for other professional services requiring the highest academic standards and professional qualifications. I pay £300 for a 15 minute chat every few months with my consultant, involving no treatment costs. Why should it be lower for a vet?
Sorry BnB .... just posted a similar comment above: I did not see this until I scrolled down. Totally agree BTW.
Your comment was more detailed and based on personal experience, so well worth adding your superior knowledge.
There are a couple of private equity groups who have been buying up independent vets practice over the last decade or so. They probably centralise buying to reduce their costs and raise prices to the pet owners who have little to no choice of vet and also seem to advise doing more tests and procedures than they used to.
Vets are a lot cheaper in france. Ofc this is all subjective evidence sample size 1.
Human care is cheaper in France and at the same time people are treated better too.
Taxes are a lot higher in France, so I'm not sure about care is cheaper.
Friend of mine lived in France for many years said the overall tax levels make the UK look like Jersey/Isle of Man but the flip side is health care, roads , public services are excellent compared to UK.
I remember well when my parents had my five year old pet dog put down because they couldn't afford the treatment costs. It may be a harsh view but no vet treatment cost is mandatory, it's the owners' choice.
While I don't doubt that the bigger chains are making bigger profits it gives them the opportunity to invest in equipment and training smaller practices can't compete with. If people want to treat their pets as indispensable family members then treatment costs will continue to rise. There's nothing in the CMA remedies that will prevent that, and probably nothing can.
timarr
Thats not actually correct, Timarr. It isn’t actually a choice if you are a pet owner; you have an obligation, as you would if a child was ill, for example. Perhaps to have to be a pet owner to understand that view. Large chains are purely driven for mega profit. There is no benevolence about being a vet. Im not saying they shouldn’t operate that way, I am saying I would never invest in such a business regardless of the potential profit. Its just a personal view, clearly not one shared by you.