Daily Stock Market Report (Wed 16 April 2025) - JIM, MERC, OXIG, BNZL, JNEO, SOS, SMWH, XPS, RIO, PMI, G4M

Good morning! It's another busy day for updates.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£70.8bn) | Production/costs for the year on track. Pilbara iron ore at lower end of guidance due to cyclones. Rio highlights “an uncertain future impact from tariffs on the commodity markets”. | AMBER/GREEN (Roland) [no section below] Today’s update doesn’t highlight any serious operational concerns and expectations are unchanged. Of course, the real story with commodity producers is always about prices and demand. Potential disruption from tariffs and a possible US economic slowdown inject some uncertainty into the outlook. | |
Antofagasta (LON:ANTO) (£15.1bn) | Copper production up 20%. Full year guidance maintained. 660-700,000 tonnes. | ||
Bunzl (LON:BNZL) (£10.1bn) |
PW. Operational challenges in North America, where falling volumes and deflation have combined with execution problems delivering an expanded own brand offering. FY25 op margin now exp <8% (2024: 8.3%). Buyback paused. | BLACK (AMBER/RED) (Roland) Today’s downgrade seems quite modest, but the issues described by the company suggest a difficult combination of internal missteps and macroeconomic headwinds. While I respect the track record of this long-term compounder, I think there’s a material risk of further downgrades, so have taken a moderately negative view today. | |
Barratt Redrow (LON:BTRW) (£6.2bn) | Well placed to deliver housing volumes in line. Cost inflation to be broadly flat. £508m net cash. | ||
Tritax Big Box REIT (LON:BBOX) (£3.4bn) | £235.7m of sales. 50% of UK Commercial Property REIT portfolio. 2.9% premium to book. | ||
MITIE (LON:MTO) (£1.5bn) | FY25 revenue +13%. Op profit guidance upgraded to c. £230m. New £125m buyback launched. | ||
WH Smith (LON:SMWH) (£1.2bn) | Revenue in the remaining travel business +6%, “trading profit” +12% to £56m. Group PBT flat at £45m, in line with expectations. Leverage at 1.7x after successful debt refinancing, with more cash due to come in from the sale of the high street business. | AMBER/GREEN (Megan) [No section below] | |
Hays (LON:HAS) (£1.1bn) | Q3 net fees down 9% LfL (temp down 6%, perm down 14%). FY25 op profit to be in line (£56.9m). | ||
Oxford Instruments (LON:OXIG) (£946m) | Revenues for the year to March 2025 +9% at constant FX, in line with expectations. Adj. op profit +13% at constant FX, but just +3% at actual FX. Ad. op margins improved to 17.8% (from 16.5% last year). | AMBER/GREEN (Megan) | |
XPS Pensions (LON:XPS) (£818m) | Rev +18%. Confident full year results in line with previously upgraded expectations. | AMBER/GREEN (Graham) [no section below] We tend to like this fast-growing pensions consultancy that enjoys various tailwinds including “ongoing regulatory change” and, recently, projects to fix some public service pension schemes following the “McCloud Judgement”. Year-on-year growth rates are expected to decline in FY26 and the PEG ratio is now over 3x. At 19x earnings it’s not cheap. But it has delivered. I’ll stay consistent with the trend and leave our mildly positive position unchanged. | |
Discoverie (LON:DSCV) (£522m) | Underlying earnings to be slightly ahead of expectations. Sales for the year down 2% at constant FX. | ||
Hunting (LON:HTG) (£430m) | Q1 trading in line. EBITDA $38.7m. Suggests minimal/no impact from tariffs. | ||
Brooks Macdonald (LON:BRK) (£230m) | Funds under management and advice +7% to £18.6bn. Q3 net outflows £129m.Outlook in line. | ||
Life Science Reit (LON:LABS) (£155m) | NAV 74.4p (2023: 79.9p). Adj EPS -10% to 1.7p. Strategic review ongoing. No dividend. | ||
Mercia Asset Management (LON:MERC) (£110m) | FY25 EBITDA exp materially ahead of exps. Inflows totalling £250m in Q1. No redemptions. | GREEN (Graham) | |
Jubilee Metals (LON:JLP) (£95m) | Updated FY25 prod guidance: Chrome +12% to 1.85Mt, PGM +6% to 38kOz. | ||
Speedy Hire (LON:SDY) (£89m) | FY25 (y/e 31 Mar) to be in line with exps. Mixed trading, higher debt. Refinanced successfully. | ||
DP Poland (LON:DPP) (£83m) | FY24 results in line. Q1 FY25: PL sales +6.5%, orders -0.1%. Croatia +12.5%, orders +1.1%. | ||
Premier Miton (LON:PMI) (£75m) | £10.2bn AUM at 31 March, £221m net outflows during the quarter. £3m of cost savings by Sept 25. The company emphasises that most of the outflows were driven by flows from a single fund that has had shorter term relative underperformance. | AMBER/GREEN (Graham) [no section below] | |
Journeo (LON:JNEO) (£41m) | Order from Outfront Media (NYQ:OUT) for 600 displays for New York Subway Cars, delivery this year. | GREEN (Roland) [no section below] | |
PROCOOK (LON:PROC) (£33m) | FY rev +11%, LFL +4.9%. FY adj EBITDA to be in line. PBT “to reflect” new store costs & FX. | ||
M Winkworth (LON:WINK) (£26m) | Rev +17%, PBT up 10% to £2.3m. Net cash £4.1m. Sales rev up 18%, lettings up 6%. | ||
Gear4music (HOLDINGS) (LON:G4M) (£25m) | Spent £0.6m on £1.8m of stock & assets from a failed competitor. Confident in FY26 outlook. | AMBER (Megan) | |
Cirata (LON:CRTA) (£22m) | Q1 FY25 bookings up 330% to $3.0m YoY, but NAm below plan. Q1 cash burn $1.4m, has $8.3m. | ||
Sosandar (LON:SOS) (£17m) |
SP down 14% | BLACK (AMBER/RED) (Roland) [no section below] An updated note from broker Singer this morning confirms this result is significantly below its previous PBT forecast of £1.0m. So I think we might see this as a profit warning for FY25. Sosander’s management says the shortfall was driven by a weak February and that sales trends have been positive since then. However, with an increased cost base from six stores and only minimal profitability, I think a moderately negative view is prudent. | |
Jarvis Securities (LON:JIM) (£8m) | Jarvis plans to sell its brokerage to Interactive Investor for £11m and wind down other operations. | PINK (Graham) Selling up for a paltry sum compared to prior levels of profitability. My conclusion is to steer clear of any companies that undergo a skilled person review. | |
IXICO (LON:IXI) (£7m) | Exp H1 rev +26% to £3.2m. Order book £13.1m at 31 Mar, £5m net cash. H1 adj LBT exp £0.7m. |
Graham's Section
Jarvis Securities (LON:JIM)
Down 56% to 18.9p (£8m) - Sale of Retail Brokerage and Strategic Direction - Graham - PINK
At 3pm yesterday, Jarvis announced the sale of their main trading division to Interactive Investor for £11m, with their other services also being shut down. The sale is conditional on Jarvis keeping 90% of both their customers and their assets under administration before completion, which is anticipated in July.
Comment by the MD:
"We believe this transaction represents the best outcome for the Group and its clients given the position of Jarvis Investment Management at this time and its future viability"
It's been some time since I commented on this - see last August - but it's definitely one that I got very badly wrong, acknowledging the very high risk involved but maintaining my positive stance on it all the way down.
They are now shutting down and selling up for a paltry sum compared to their previous levels of profitability.
A particular source of frustration is the lack of public information around the findings of the FCA's skilled person review. As I concluded last August, in future instances I am going to run for the hills whenever I hear that this type of review is taking place - they are expensive, drawn-out affairs and shareholders/the investing public are the last to be told of their findings. I now believe that any company with this type of review taking place has to be avoided, sadly.
Mercia Asset Management (LON:MERC)
Up 14% to 29p (£125m) - Trading Update - Graham - GREEN
Mercia is “the regionally focused, specialist alternative asset manager with over £1.8billion of assets under management”.
Some pleasing news here: EBITDA for FY March 2025 will be materially ahead of current market expectations.
The benefits of Mercia's increasing scale are now beginning to feed their way into the Group's overall financial performance. Together with a continuing focus on efficiency, Mercia now expects its EBITDA for FY25 to be materially ahead of current market expectations.
You may recall from our previous coverage that Mercia trades cheaply against the value of its balance sheet, where it has its own longstanding portfolio of direct investments, but it also has a growing fund management business.
In Q4 it has raised an additional £250m and again saw no redemptions.
It closed the year with £40m of cash and zero debt.
Estimates: thanks to Equity Development for publishing a refreshed note this morning with a new AUM estimate for March 2025 of £2.2bn (includes £2bn of 3rd-party funds). The new EBITDA estimate is £7.7m (previously £6.2m) and the new PBT estimate is £4.8m (previously £3.3m). The company is estimated to have net assets of nearly £188m.
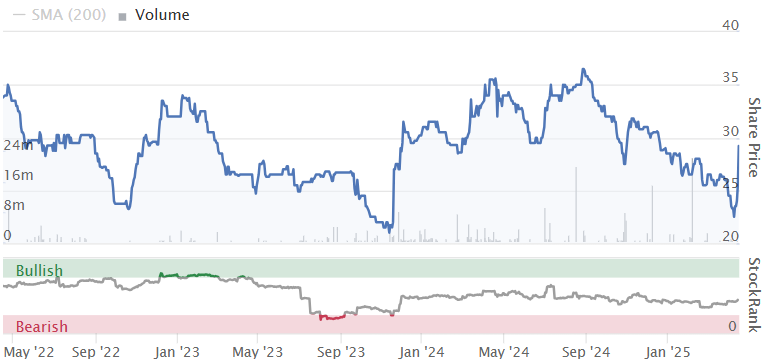
Graham’s view: I have been positive on this for a while and again put it on my 2025 watchlist. The shares are still trading around where they were at the end of 2024 (having travelled lower before recovering), and we’ve now had an “ahead of expectations” update. So there is no reason at all for me to change my positive stance.
While it’s impossible to have total conviction in the long-term success of the fund management business, the signs so far are very positive. If I was valuing it purely on current earnings and on the fund management business, perhaps I’d be less enthusiastic. It’s the very strong cash and asset position that convinces me I need to be positive on this.
Megan's Section
Oxford Instruments (LON:OXIG)
Up 6% to £17.28 (£1.0bn) - Trading Update - Megan - AMBER/GREEN
Overview:
- Revenues for the year to March 2025 +9% at constant FX, in line with expectations.
- Adj. op profit +13% at constant FX, but just +3% at actual FX.
- Adj. op margins improved to 17.8% (from 16.5% last year).
Unsurprisingly, demand for the company's semiconductor services has been especially strong, helping lift revenues in the larger Imaging and Analysis business, with margins here of 24%.
The smaller Advanced Technology business has also benefited from semiconductor demand, with an improvement in the client base helping lift the division back to profitability.
Megan's view
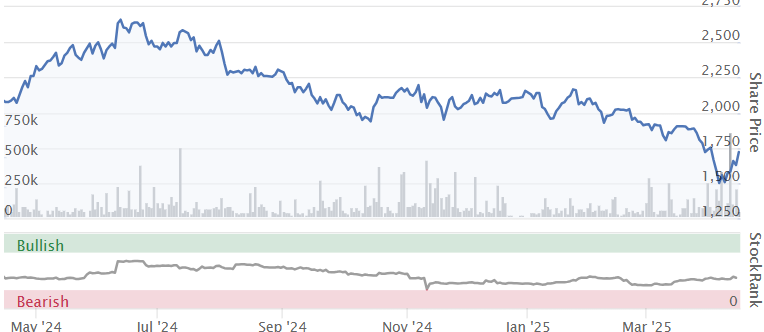
The share price slump at Oxford Instruments has continued in the last few months as broker forecasts for the 2025 and 2026 financial years (ended in March) have been cut. Today’s trading update reassures that trading has been in line with the current consensus thanks to a return to profitability of the smaller ‘Advanced Technology’ business.
At 14x forecast earrings, there is an argument to be made that the shares now present better (if not good) value.
Operating margins are improving, as the company focuses on trimming back costs. I’m not inclined to turn fully positive yet as I still think there are some unanswered questions (especially around the uninspiring pace of growth). But I think this is one to watch. AMBER/GREEN
Gear4music (HOLDINGS) (LON:G4M)
Up 15% to 135p (£28m ) - Asset purchase and trading update - Megan - AMBER
It’s been a rocky road for Gear4Music investors since the company’s IPO.
The company came to Aim in 2015 as an asset-light specialist retailer of music equipment with annual revenues of £24m. Ten years later, the annual revenues are heading towards £150m, but the company is worth less than it was when it listed.
What’s gone wrong? Gearing.
At the last count, the company was sitting on £21m of interest-bearing loans, with net debt of £14.4m, equivalent to 60% of the market value of the company. Gearing has come down from its painful peak a few years ago, but it’s still at a slightly uncomfortable 80%. And the debt doesn’t come cheap, meaning interest costs have eaten into company profits in the last couple of years.
And so today, it’s nice today to see a bit of financial wizardry going on at the company. Management has bought up a load of inventory from a company in administration at below cost price. In addition to the £1.8m of stock, the company has acquired £0.6m of commercial data and trademarks as part of the deal.
Inventory management has historically been another slightly sore spot for Gear4Music. A ridiculously high level of inventory during 2022/23 as demand began its downturn post-pandemic left the company having to hive off stock at a massively discounted rate, which hurt gross margins. At the last count, the company was sitting on over £40m of inventory, which is almost the equivalent of the company’s current enterprise value.
In addition to grabbing an opportunistic deal for cheap stock, management has also confirmed that trading remains in line with current expectations. Which is a relief considering how much stock the business had to shift in the second half of the financial year.
Megan’s view:
Gear4Music is a nice business which has paid the price for being enticed by previously cheap borrowing costs. A rise in interest rates alongside a slowdown in demand have caused the company and its investors a world of pain in the last few years.
That’s said, with debt coming down and the balance sheet seemingly being managed more effectively, there is value in the current share price. Perhaps one for deep value investors to take a bite at, but it’s not one for me. AMBER
Roland's Section
Bunzl (LON:BNZL)
Down 23% to 2,370p (£7.8bn) - Trading Update - Roland - BLACK (PW) / AMBER/RED
We reduce our 2025 guidance to reflect the operational challenges faced by our largest business in North America, and the implications on the remainder of the year from a more challenging start for the Group.
FTSE 100 distribution specialist Bunzl supplies a myriad of non-food products to a wide range of customers. It’s a long-term compounder that’s become a byword for reliable performance, so today’s profit warning is surprising, perhaps accounting for the severe de-rating the stock has suffered this morning:
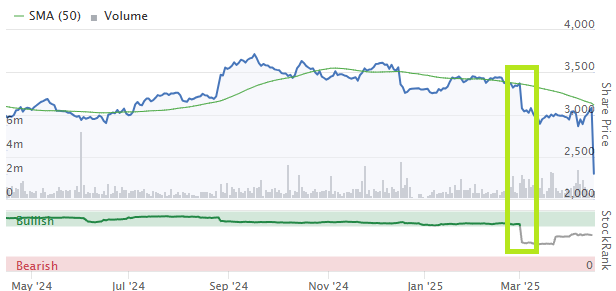
What’s interesting here is that the StockRanks (and the market) appear to have picked up warning signs from Bunzl’s 2024 results in early March. These prompted a sell-off despite 2025 guidance being left unchanged. Shareholders who noted this might have been able to avoid today’s drop.
I didn’t study those results in detail at the time. But looking back now, they did highlight warning signs in North America (the cause of today’s warning). Both sales and volumes were lower in North America last year, and management commented on persistent deflation, which can be hard for a low-margin business to deal with.
North America generates more than half the group’s revenue, so when this business catches a cold, the whole of Bunzl sneezes!
With that backdrop, let’s take a look at today’s update for more detail.
Q1 trading update: Bunzl’s underlying revenue, which is the most comparable measure of organic performance, fell by 0.9% during the first quarter. Acquisitions contributed a further 5.7% in revenue growth versus Q1 24, but of course these come with their own additional costs.
Overall profitability appears to have fallen, perhaps quite sharply:
Adjusted operating profit was down significantly year-on-year in the first quarter, reflective of an operating margin decline driven by performance in North America and Continental Europe.
North America: softer trading appears to have combined with a misfiring effort to expand Bunzl’s own-brand offering.
The company’s largest business in this region “primarily services foodservice and grocery customers” and has been trying to develop “an enhanced own brand offering” to sit alongside its core third-party product offerings.
Unfortunately, this appears to have been a more complex shift than expected:
This has required substantial investment and change in the sales and operating model, which has been more challenging to execute than expected.
Continued deflation in the first quarter has compounded these problems – Bunzl has to carry a certain amount of inventory, but if sale prices are falling then this could lead to severe (albeit temporary) pressure on margins, until pricing stabilises.
The end result makes for grim reading:
“Slower than anticipated volume improvement”
“An isolated customer category loss”
“Higher operating costs”
All of which has led to “a significant decline in adjusted operating profit”
I suspect the focus on own brand products was part of a move to try and support or improve margins, particularly after the inflationary pressure we’ve seen in recent years. However, it sounds to me like this has been poorly managed operationally and may also have faced some pushback from customers.
Bunzl confirms that management changes are being made:
We have taken a series of decisive actions to improve performance. These include leadership changes to ensure there is a renewed focus on commercial agility and operational excellence.
Continental Europe: to add to the pressure on group profits, Bunzl’s operating margin was lower during Q1 in Europe as well. However, this decline is said to have been “broadly in line with expectations” – i.e. only slightly worse than expected!
Rest of the World: strong underlying revenue growth is reported, driven by Latin America.
2025 guidance update: Bunzl now expects “moderate revenue growth” at constant FX, driven by acquisitions. Excluding acquisitions, underlying revenue is expected to be “broadly flat”.
Adjusted operating margin is expected to be “moderately below 8.0%”, compared to 8.3% in 2024. This figure will be weighted to H2 for seasonal and operational reasons – H1 operating margin is expected to be “around 7.0%”.
The company emphasises this guidance is being offered without any clarity on the potential impact of US tariffs on inflation and economic growth. I see this as a warning that further downgrades could be needed.
Previous consensus estimates on Stocko suggested reported revenue would rise by 2.7% to £12.1bn this year, so it’s not clear to me exactly how much of a downgrade this is.
However, if we assume revenue of £12bn and apply a 7.8% adjusted operating margin, the resulting profit figure of £936m would be 4% below the £976m reported last year. From what I can see, previous expectations were for an operating profit figure of c.£1bn.
Bunzl has also paused its ongoing share buyback programme to try and reduce leverage to the lower end of its 2.0x-2.5x EBITDA target range. I’m fully on board with this – I would have preferred the company to have already been focusing on debt reduction rather than pandering to the fashion for buybacks.
Roland’s view
I’m only guessing at these numbers – without access to broker notes, it’s hard to be clear on the exact impact on forecasts of today’s announcement.
However, at face value this appears to be a relatively modest downgrade. Given this, a 25% share price drop seems a harsh reaction.
My reading of this situation is that the market shares my view that further downgrades could be needed before Bunzl fixes its internal issues in North America and perhaps starts to benefit from a more stable macro environment.
Fundamentally, I think this is still a decent business, but our research has found that a company’s first profit warning is often the start of a longer period of weakness.
Personally, I don’t see any good reason to buy Bunzl just yet. Although my estimates suggest a potentially cheap EBIT/EV yield of c.9%, I think it’s probably more sensible for investors to stay on the sidelines and see what unfolds over the coming year.
I’m tempted to take a neutral view, out of respect for Bunzl’s strong track record and the seemingly modest scale of today’s downgrade. But I can’t help feeling there’s a relatively high chance of further bad news, so I’m going to go AMBER/RED until we know more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
For reasons outlined in my earlier post I have added to WH Smith (LON:SMWH) and Premier Miton (LON:PMI) . I remain adrift of my blended purchase price in both cases but am of the view that the share price of both will be substantially higher at some point, as to when that is, it is a finger in the air job.
With regard to WH Smith (LON:SMWH) I would suggest that once the sale of the high street division completes and the positive impact on margins comes through.
Premier Miton (LON:PMI) has about 40% of its market cap in cash and on current forecasts the dividend of 6p is covered by earnings, so unlike most other fund managers it appears that it will not need to deplete its cash balance. On this basis the shares yield north of 12%, which in normal markets would be unthinkable. Interest rate reductions are good for assets (shares) so fund managers are too a large extent a play on the potential for such.
It is difficult to believe that we are not close to the bottom for good quality small caps and AIM has started to tick up recently. There are some very well managed companies listed on AIM, Jet2 (LON:JET2) James Halstead (LON:JHD) Avingtrans (LON:AVG) for example, but there is also a lot of dross. Successful investing is in my view about avoiding the latter and buying fundamentally good companies when nobody wants them.
Things can always get worse, but small cap investing has been challenging for the last 2/3 years and the share prices of most UK small caps have been battered, despite in many cases performing well from an operational perspective.
To quote two of the great investors, Warren Buffet and Howard Marks 'price is what you pay value is what you get' and "investing is a popularity contest and the most dangerous thing is to buy something at the peak of its popularity".
Hopefully I have got these buy decisions right, time will tell.
I already have a full position in Journeo (LON:JNEO)
There endeth the monologue.
All the best.
More insider buying for Volex (LON:VLX)
COO picking up £150k worth, bullish! Yes I hold :)
https://www.stockopedia.com/sh...
Volex (LON:VLX)
every time i check volex the future earnings expectations seem to be lower than previously.
looking at stocky ref 2026 thats 8 consecutive ticks down when stocky updates numbers - perhaps the people that should know are going to be lucky and buy in just before the trend reverses !! - if that does happen is that luck or insider trading ?
Note i suspect here that they are actively downgrading behind then scenes to then hit on promises - the year just finished looked like stuff was downgraded so that they coudl at the end of the year say they have delivered at the top end of estimates
Make of this what you will - i would agree now the p/e is at 9 this does look like its trending more towards being nice value pick than has ben the case for some time - that will only really be the case though if we dont get another 8 consecutive downgrades over the next 6-9 months or so.
Not sure what chartist would say here - chart looks poor - but i dont think price has gone under 200p in the last 10 years - so does very low point there offer support?
Well it certainly has been below 200 in last 10 years, though i take your wider point
News from three portfolio companies this morning:
Journeo: $2.5m contract to supply high definition screens to the New York transportation system. Possibly opens up more opportunities via its relationship with the Outfront Media Group. Also the company has £14m cash on its balance sheet, which is about 33% of its market cap. I also view this as a 'new' order that is not included in current forecasts, otherwise I believe the company would have said so, as it has done previously. Plenty to for!
Premier Miton (LON:PMI) AUM of £10.2 billion at 31 March, albeit now around £10 billion strikes me as a very creditable performance for an active fund management group in the current climate. I also hold Polar Capital Holdings (LON:POLR)
WH Smith (LON:SMWH) I think Megan's summary is somewhat harsh as is the market's reaction.
Yes the high street division went for comparative buttons. I travelled to Shrewsbury last week and bought a newspaper at Smiths in the town centre; it was empty. By comparison the outlet at Birmingham International, where I changed trains was buzzing. Despite the paltry price, the sale of the high street shops was the right thing to do. Smith's has got a declining business off its back together with the impact of the recent budgetary tax rises allowing management to focus on growing the profitable travel business. For a business with decent growth prospects, a sub 10 PE falling to 9 and a dividend yield of 3.9% rising to 4.3% or thereabouts strikes me as good value.
On the subject of share buy backs, the time to buy back shares is when the price is depressed not when it is expensive.
All the best
I too was surprised when the market, after brief enthusiasm, decided to mark down WH Smith today. I’m with you, however, on the eventual benefit of concentrating on the travel shops alone. What you could also have mentioned is that the increase in profit margins should drive a higher multiple. None of that matters right now because travel stocks are off the menu for most investors while recession risks are elevated. Fair enough. Dividend is healthy enough to sit on my hands.
For my own piece of scuttlebutt I would point to the £3.99 I paid for a small bag of Revels at Southwaite services last week. The margin on that has to be huge!
Strategically, WH Smith (LON:SMWH) might have done the right thing, but I think Megan is correct to say that the price achieved on sale was underwhelming at £76m for a business that made £32m of profit last year and generated cash. Hence, why the sale has not helped the share price in the short term.
Long-term, I agree Jonno that it will remove a management distraction and improve both growth and earnings quality but the dilution is unhelpful for now. I also don't see a share buyback as sensible given the leverage here (but let's not get started on that one again!)
WH Smith (LON:SMWH) - Hi Megan, I see the market is also underwhelmed today. Perhaps I can put a different perspective on where WHS is:
The high street business has no future value and so I believe WHS has dodged a bullet by taking decisive action and getting shot of it now. They're getting something more than nothing for it which I'm impressed with because frankly, profitable though it is now, I see no long term opportunity beyond at best the status quo, and so the market should in my view have breathed a sigh of relief, and has taken too short term a view.
WHS has effectively taken out an insurance premium which even comes with a negative excess (the price they're being paid) and protects against further distraction of management, against future drag on results, and against the strong possibility the high street business will become seriously challenged (with or without current headwinds like demise of high streets, NI, min. wage, business rates, energy costs and more). In fact it probably is seriously challenged already. Frankly lesser retailers would have been looking at a corpse by now, whereas WHS going back at least to Kate Swann has defied mortality and I'm amazed anyone else even wanted the high street stores - we might hope they will will be thriving in five or ten years but would you now put money on seeing the high street business under it's new owners still trading by then?
Meanwhile WHS has cleared the decks, de-risked, and can focus on travel, not that this sector is challenge free either. I don't hold but I'm watching because this is a dramatic shift for a very old business, effectively cutting itself off from its roots. There can't be any excuses now if the slimmed down group doesn't perform but it needs to be given more than a month or two.
Buying back shares effectively with debt is another question - beyond my paygrade but a red flag.
I don't agree that WHS is cutting itself off from its roots because it grew mostly by being in railway stations when they were the biggest source of travel business. Focussing now on their travel shops is returning to their roots - the High Street turns out to be a very long-lived diversion!
https://www.whsmithplc.co.uk/a...
Perhaps we're quibling but I was talking about the origins of the business. WH Smith (LON:SMWH) started life a few years before the first ever passenger rail service and more than half a century before it first opened for business at a railway station.
My sentiments also Tein, but as a holder I am biased.
Jarvis Securities (LON:JIM)
Currently showing a 91% loss on my original investment, financially, it doesn't matter much to me what happens from now. I am not a customer but my employer has been and I have found their service first class. They also handled competently non standard instruments the larger institutions would not, possibly because the high level of automation their business model needs make it not viable.
I imagine something much more sinister has gone down than what the public have been told. If not, a once healthy business, providing a useful specialist service, has been destroyed for what?
For Andrew Grant to open his RNS yesterday stating he is "Pleased to announce...." is not classy and not how I felt reading it! I suppose that by now he is is so demoralised he probably is pleased to be shot of the s**t show.
I agree with Graham that there is a good chance we will not see much returned. The remaining assets will likely end up in the pockets of the various experts, auditors, regulators and, via them, HMRC. With that in mind we should remind ourselves of the absolutely splendid job Share Soc did when Beaufort wend down and its clients were rescued by the Share Centre. A few spotty PWC staff might have been a bit short on their Christmas bonuses but for the rest of us it was a brilliant outcome.
A sad outcome and, as nothing has actually gone into receivership, I doubt we will learn much more.
It is not the first time I have lost most of my investment in a small company - but it is for one I invested in for income!
Regarding Jarvis Securities (LON:JIM), not necssarily anything any more sinister than already announced. My reading of the situation is that they were too small to be an effective player. The skilled person review is something that is extremely onerous and expensive for a company of this size and they probably didn't have the staff, expertise and control systems to escape. What has undoubtedly been their downfall is the Model B business segment. Some of their clients may have been on the dodgy end of the spectrum, and they have been caught up with all of this. I sold a while back after concerns around who their end customers actually were. Maybe that's the learning point as I don't believe that they ever communicated their client list. I think Andrew Grant has always been very shareholder friendly, with quarterly dividends and to the point communications, but he's been badly burnt and had to throw in the towel. He's at retirement age anyway.
Journeo (LON:JNEO)
Roland says he expects todays contract win is already baked into the forecasts but I think he is wrong.
The company previously guided to the US subway contract being paused indefinitely due to a lack of passengers, so that last expected revenues from that contract were in the previous FY and were not in the current year forecasts.
Recently passengers riding the metro in the US have gone up 9% so it seems this has triggered the media partner to re-start the roll out, hence the order and therefore the reason it has been announced. Therefore I do not think this is in the forecasts and should provide a bit of upside.
Hi davidjhill,
You could be right re. Journeo (LON:JNEO) - I am only guessing, as the company did not mention expectations in today's update and I don't have access to any updated broker notes today.
When a company flags up a new order without mentioning expectations, I tend to assume that it's actually business as usual and is already priced into forecasts. But this isn't always correct and may not be here.
Time will tell - perhaps the next trading update will include some clarity on current year expectations.
Roland
Journeo (LON:JNEO)
When a company flags up a new order without mentioning expectations, I tend to assume that it's actually business as usual and is already priced into forecasts. But this isn't always correct and may not be here.
very sensible stance that mirrors mine as a holder and my normal default stance - i always await the formal fish slapping before i celebrate good news - especially important if one is needing Rory to deliver a win !!!
Hi Roland - generally sensible but with Journeo (LON:JNEO) it is usually the opposite. Ie they tend to state “we’ve won xyz and it’s part of our expectations”. This time they didn’t and from memory going back to the results presentation they had said this contract was parked until traffic numbers came back so I very much doubt it was included anywhere.
It’s sort of irrelevant for me though as Journeo (LON:JNEO) are a long term investment. I rate the management highly and they believe they are on track to more than double the size of the business over the next few years. If they do that, and with some operational gearing, I suspect it will look very cheap at these prices. Certainly gets over my mid teens expected annual compound return hurdle rate.
Journeo (LON:JNEO)
Roland says he expects todays contract win is already baked into the forecasts but I think he is wrong.
I side with Roland here (just) - they will have a pot of potential contracts some of which they need to sign to make ends meet. Its likely that they simply need to get say 5 of these in the bank over the rest of the year so whilst i agree the contract may not have been expected it might be necessary to get over the line ref current expectations anyway if they need a project this size every 3 months say to turn up.
If this moved the goalposts so they would be ahead of expectations i would have liked to think they would have updated the market - the lack of update leaves me saying its not in itself enough to move the needle.
There is a middle ground here in that they are starting the year cautious and may upgrade at next formal update point perhaps. I have been bitten a fews times with companies with chunky contracts - so i will never presume stuff if we havent been slapped in the face. I have held Journeo for less than 12 months as i has slight concerns before buying in - up to now though they do seem to be professional at not over promising which i am liking- thats my main bugbear with companies like this that do overplay the future - or a purple patch exists that might explain slight dip. I must say as they have been on a decent run its much easier to hit targets when you know sales and profits are up - the real test in when there is a pause for breathe and some of the "good profit prior work" is struggling to find a replacement - hopefully they are being cautious and the outcome will be better than "not quite as good as 2024".
In the meantime with tepid current expectations (compared to 2024) we just need to wait it out to see how the mop flops -happy to play that game.
I’m pretty certain it’s not included rmillaree for the reasons above. If you’re minded to check I think this particular contract was referred to as on hold for the foreseeable future in the recent results presentation, though memory may not serve me perfectly!!!
IPO's advised by Cavendish (LON:CAV) in 2025
MHA Plc, Quantum Base Plc, RC Fornax and Amcomri Group Plc
"To have delivered such a strong fundraising outcome in the face of recent market volatility speaks to the quality of the business, the support of a highly engaged institutional investor base, and the determination of our management team and advisers, led by Cavendish.” - MHA Plc Chairman. This bodes well for Cavendish and hopefully they'll get more IPOs.
Roland re Bunzl (LON:BNZL) and Graham and other contributors - This sort of comment is the reason that Stocko subscription is of greater value to me than just the data / software!
What’s interesting here is that the StockRanks (and the market) appear to have picked up warning signs from Bunzl’s 2024 results in early March. These prompted a sell-off despite 2025 guidance being left unchanged. Shareholders who noted this might have been able to avoid today’s drop.
Next time I MIGHT now notice something similar seeing as every day is a school day. Many thanks
I do not have any shares in Jarvis Securities (LON:JIM) but my substantial ISA is with them and I have been happy with the service. Without an investment I have not being paying as much attention to the company as I should have. Looking at Companies House for Jarvis Investment Management (the principal operating subsidiary)I see that Andrew Grant’s position as a Director was “terminated “ on March 31st (announced April 1 ). Since he is a founder, and 47% holder of the JIM shares this more than surprised me, especially as i cannot see that the company issued an RNS.
I do not feel good about this, does anyone have a reassuring word?
Adding to my earlier comment, with a 52% holding it may be that Andrew Grant has been kicking any worthy suggestions from the rest of the Board into long grass, or simply AWOL?
Edit, looking to Simply Wall St:
Jarvis Securities plc (JIM) Risk Checks
Fail
Are revenue and earnings forecast to grow?
Earnings have declined by 1.3% per year over past 5 years
Fail
Is their share price liquid and stable?
Highly volatile share price over the past 3 months compared to the UK market
Fail
Is their dividend sustainable?
Unstable dividend track record
Fail
Do they have a meaningful market capitalization?
Does not have a meaningful market cap (£8M)
Fail
Do they have sufficient financial data available?
Latest financial reports are more than 6 months old
Fail
Do they have high quality earnings?
Large one-off items impacting financial results
Fail
Have profit margins improved over the past year?
Profit margins (25.4%) are lower than last year (39.4%)
Pass
Are there any concerning recent events?
No concerning events detected
Pass
Are they in a good financial position?
They are debt free
Pass
Do they have negative shareholders equity?
JIM does not have negative shareholders equity.
Pass
Do they have meaningful levels of revenue?
Revenue is meaningful (£12M)
Pass
Are they forecast to achieve profitability?
The company is currently profitable
Pass
Have shareholders been diluted over the past year?
Shareholders have not been meaningfully diluted in the past year or recently listed
No data
Has there been substantial insider selling in the past 3 months?
No 3-month insider trading information
Aislabie, like you I have an ISA with Jarvis Securities (LON:JIM) but thankfully don't hold any of their shares. Regarding the CEO's 'termination'; this was announced a year ago https://www.investegate.co.uk/...
Thank you for putting me straight on the JIM situation. I saw the notice for April 1st 2025 without being aware of the previous announcement. My bad
There was an RNS on 17.iv.2024 saying that Andrew Grant was retiring as CEO of the operating company (JIML) but would remain CEO of Jarvis Securities (LON:JIM). He is c. 65.
Mitchells & Butlers (LON:MAB) I wonder if M&B's policy of hacking down any ancient tree they can find (Whiteweb Enfield) on dubious Health and Safety grounds will affect their business? Unlikely, as Toby Inn customers probably don't care. Wetherspoon's preserve architecture, M&B destroy nature. Brand differentiation at last!
I posted the offer shown below yesterday and within 40 minutes they were taken so the team are creating a 'New to Mello' ticket that will allow any investors that are complete newcomers to our physical conferences a very significant discount to the one day entry price so that you can see what the events are all about. There are also videos on our website off course. There may also be other sponsors who offer their complimentary tickets to investors but it is rare as they like to attend normally so they can engage with investors.
Update....Six more companies have signed up in the last week and four more will be announced today. We are now at 29 and confident that we will reach our target of 50. That is one of the key differentiators for Mello as most other live events will only have a handful of listed companies available to meet plus our top quality speakers in the Mello theatre....and of course all of you ! The Mello community are always so engaging and welcoming which makes networking so much a big part of the two days...
Mello 2025 will be back for two days packed full of company presentations, keynote speakers, panel sessions such as the ever popular BASH and of course lots of networking with likeminded investors . Probably around 30% of the attendees are fellow subscribers from these Stockopedia boards...
Date: 3rd & 4th June 2025
Location: Clayton Hotel Chiswick 626 Chiswick High Road London, W4 5RY
Limited offer for newbies...One of our sponsors has provided two tickets to be given complimentary to two individual investors who have never been to a Mello conference before. So if you would like to claim one on a first come first served basis and remember you must be new to our physical events just email me at David@Melloevents.com
Highlights of Mello 2025:
Keynote Speakers: Hear from industry leaders and learn from the best in the investing world such as Lord Lee, Vin Murria, Christopher Mills, Ben Rogoff, Georgina Brittain, Gervais Williams and many more
Panel Sessions: Gain insights and learn about different investment strategies or approaches.
Networking: Connect with like-minded individuals and other excellent investors.
Exhibitions: explore the different investment opportunities in our exhibitor area and meet management face to face.
Register Now: https://melloevents.com/mello2025/
Discount Code: use code Stocko50 for 50% off tickets
Stay tuned for more updates and exciting announcements. We can't wait to see you at Mello 2025!
#Mello2025
David
A canny bit of business from Gear4music (HOLDINGS) (LON:G4M) , buying a decent amount of stock way below cost price from the administrators of a competitor.
Journeo (LON:JNEO)
ref the new york subway contract - i thought that it was likely that there wouldnt be any chunky new orders "until further notice" here so nice if they have picked up some extra sales there - i think that initital chunky project was nearing completion and further orders were in the "uncertain camp" - mostly due to woes within the subway system itself i think.
I dont know if my comments above are on the mark? - perhaps there might have been prior expectation this order would turn up so treat my comments as uninformed gossip. Without any actual upgrades deffo safe to presume orders are simply necessary to make year end projections and might have existed in the possible necessary income pot that may exist.
Journeo very often include a ‘included in management expectations ‘ comment with their RNS’s about new orders . So I think you are safe to assume this wasn’t in the forecasts …
Oxford Instruments performing well in tough markets. And good value relative to history. Intrinsic value is £32.50 in my calculations.
Bunzl is usually such a steady performer, but the TU speaks of some worrying missteps in their largest US division. Sell-off is well justified as it sounds like it will take some time to address the issues. With tariff uncertainty adding to woes, I wouldn’t be surprised to see another warning in due course.
Thoughts on Mercia Asset Management (LON:MERC) today? A bit of a contrast to Jarvis, I hope. But Premier Miton (LON:PMI) holding level or down a bit....
I was delighted to read "materially above expectations" on the Mercia's TU Greyinvestor, thank goodnesss we have a lot more money invested in their shares than we have in Jarvis.
We've published our thoughts today but sorry, can't post a link as against house rules but stick Equity Development Mercia into google and you'll find it. 30% of market cap is cash and our forecasts are on the conservative side.
Mercia Asset Management (LON:MERC)
We need all the information we can get on any share and I am apalled if you have been stopped from posting a link as you have in the past. So for anyone looking at this share here is something to help: https://www.equitydevelopment....
I’d agree access to this content is helpful. In fact, Graham and co often refer to the coverage and from other brokers in their own analysis in this report, so clearly adding value and opportunity to research further
It would appear that Jarvis for a long time have not been very good at their job, I hold and had great hopes but feel let down for what could be the final time.
Jarvis Securities (LON:JIM) As a customer of both x-o and ii, I will be relieved if the deal goes ahead. I suspect Jarvis made lots of money 'turning a blind eye' to nefarious activities.
Jarvis Securities (LON:JIM)
Have they?
Or are they just a small player outside the City which the FCA hate and know if they tie them up in knots for a couple of years they'll become unprofitable and throw in the towel.
Who knows?
But I know what I think.
(Don't hold)
Thank you for picking up on Jarvis Graham, I look forward to your observation. We are long term sufferers and the regulators medicine and comments seems to have finally ended the company's painful story. Another for the Capital loss column.
Sorry to hear of this JASVFS, it's an awful finish to a very unfortunate situation. Hopefully an experience that can be used to avoid similar in future - experience being what we get when we don't get what we want. G
experience being what we get when we don't get what we want
True. But I’m more partial to “experience being what we get just after we needed it”
Thanks for the text on Jarvis Securities (LON:JIM) Graham. In your experience what do you think is liable to be returned to shareholders? Finger in air and hope for the best for best case outcome or bail now expecting a worst case?
I don't know iain! If I had to guess I would say the current share price seems about right. Hopefully shareholders will get more than the current share price - but there's even the possibility that the deal falls through and then all bets are off. And winding-down costs for this sort of thing are always higher than my initial estimate. I'd be surprised if anyone outside the company or the FCA would be able to estimate this with any precision.