Daily Stock Market Report (Wed 17th June 2026) - PZC, HSP, SNWS, AO., GAW, CGS, BBSN, LIKE

Iran: The price of a barrel of oil has fallen by another c. $4 since yesterday, with a peace memorandum due to be signed in two days. The memo has been seen by Bloomberg News and includes the following points:
An immediate and permanent end to the war on all fronts, including Lebanon.
Undertakings to negotiate and reach a final agreement within 60 days.
The US to lift the naval blockade and Iran to allow merchant ships to pass through.
$300bn of financing for Iran, for rehabilitation and economic development.
The ending of all types of sanctions against Iran.
Iran will never produce nuclear weapons.
In summary: the conflict appears to be at an end.
SpaceX: the market cap of Space Exploration Technologies (NSQ:SPCX) was approaching $3 trillion at one point yesterday, overtaking Amazon and Microsoft and becoming the fourth-biggest US stock. It closed the day at $201.80, up an impressive 49% from its IPO price.
Yesterday was also important for the stock as it was the first day that options went live for it. 1.8 million contracts were traded, easily creating a new record for the volume of contracts traded on the first day of a new stock. Tesla has had an extremely active options market for years, and SpaceX has the potential to be even bigger in that regard.
Overnight market movements:
The FTSE is set to open down 0.1% at 10,480
S&P 500 is up 0.3% at 7,530
Brent crude is down 0.4% at $78.60/bbl
Gold is unchanged at $4,330/oz
Bitcoin is unchanged at $65,800
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Games Workshop (LON:GAW) (£6.7bn | SR79) | A dividend of 90p per share has been declared, the first dividend for FY27 (FY26: 85p). | GREEN = (Graham) | |
Tritax Big Box REIT (LON:BBOX) (£4.2bn | SR42) | Tritax has entered into an agreement to deliver a 125MW data centre in Essex, the second in its pipeline. The project will target a yield on cost of 10-11%. | ||
Kosmos Energy (LON:KOS) (£1.1bn | SR40) | Sale of interests in Ceiba Field and Okume Complex to Panoro Energy for c.$127m. Future contingent payments of up to c.$40m are possible. Proceeds will be used to repay debt. Updated full-year guidance will be provided in August. | ||
Hays (LON:HAS) (£568m | SR34) | Hays has sold operations in six European countries to Meraki Capital for net cash proceeds of c.£4m. The company is also exploring options in another 13 countries that are collectively expected to deliver a breakeven result in FY26. Hays now plans to focus on 16 core countries. | ||
AO World (LON:AO.). (£548m | SR72) | Revenue +11.4%, adj pre-tax profit +16.1% to £50.5m. Free cash flow up 152% to £66.4m, net cash of £16.4m. Will pay a £10m special dividend and carry out a £10m share buyback. FY27 outlook: external environment remains uncertain, but expect FY27 result in line with expectations. | AMBER/GREEN = (Roland) I can’t find much to dislike about these results. Profit margins doubled last year and the business appears to be generating attractive returns from its capital-light model. Cash generation is also good and shareholders should benefit through a special dividend and buyback. Forecast for FY27 are unchanged today and suggest slower growth ahead of a stronger result in FY28. The valuation looks reasonable to me, if not obviously cheap, so I’m happy to maintain our broadly-positive view on this founder-led business. | |
Guardian Metal Resources (LON:GMET) (£458m | SR28) | Purchase includes 841 acres of real property zoned for mixed use, as well as 2,540 acre-feet of annual water rights. The property is less than 10 miles from the Company's Tempiute Tungsten Project. | ||
PZ Cussons (LON:PZC) (£392m | SR83) | Upgrade to FY26 profit guidance: expect FY26 LFL revenue growth of c.6%, with reported revenue of c.£540m. Reflecting strong trading, expects FY26 adj operating profit to be at or slightly above previous guidance of £53-57m. The company has already taken actions to offset expected FY27 cost inflation related to the Middle East. | AMBER/GREEN = (Roland) Operating profit guidance for the year is nudged higher and is now c.13% above the company’s original guidance one year ago. This improvement hasn’t fallen through to EPS forecasts though, as I explain below. While I think PZC still faces some potential issues, I’m broadly positive about the outlook here. With the stock trading on c.13x FY27 forecast earnings, I’m happy to maintain our existing view today. | |
Social Housing REIT (LON:SOHO) (£284m | SR63) | Will acquire senior living assets comprising 1,907 rental flats and 256 housing manager flats from Residential Secure Income (LON:RESI) for £108.3m, with £45m in cash and c.£62.3m in new shares at 94.23p per share. The acquisition has a reported valuation yield of 6.63% and will increase SOHO’s EPRA NTA to £471.4m. | ||
Hargreaves Services (LON:HSP) (£249m | SR98) | Expects to report FY26 revenue ahead of expectations and pre-tax profit in line with expectations, reflecting the mix of contribution from the group’s three businesses. (Company-compiled consensus: revenue £288.2m, adj PBT £33.4m, EPS 64.1p). Cavendish updated EPS forecasts: - FY26E adj EPS: 75.7p (unch.) - FY27E adj EPS: 48.8p (unch.) - FY28E adj EPS: 50.7p (prev. 48.1p) | AMBER/GREEN = (Roland) [no section below] I’m a long-term fan of this business (and its management) and today’s update doesn’t alter that view. However, FY26 profits will be boosted by a £7m one-off item and earnings are currently expected to fall in FY27 – a view confirmed by broker Cavendish today. Hargreaves’ shares currently trade at c.1.3x book value and on 16x FY27E earnings. For a capital-intensive business with a trailing ROE of 11%, this valuation seems about right to me. I’m going to leave our previous broadly-positive view unchanged today. | |
Tristel (LON:TSTL) (£185m | SR79) | Appointed Christopher Lee as CEO from 1 August 2026. He was recently CEO of UK medical device business Summit Medical Ltd from 2020-2025. | ||
Rockwood Strategic (LON:RKW) (£185m | SR59) | NAV total return of 7.1% to 266.44p/share. NAV rose by 54.7% to £149.4m. Issued 17.3m new shares to meet demand, increasing share count by 44.5%. NAV Total Return from period end to 12 June was 17%, to 311.64p. | ||
Savannah Resources (LON:SAV) (£161m | SR37) | Has signed additional MoUs with various community groups in areas close to the proposed mine site. Plans for a bypass road around Boticas are being progressed. | ||
Smiths News (LON:SNWS) (£157m | SR94) | Secured long-term contract with News UK & Ireland (publisher of The Sun and The Times). The contract expands the areas in which Smiths is the exclusive distributor for News UK, “effectively securing national distribution of News UK’s leading titles” from July 2027 through July 2037. Expected to deliver a c.£125m uplift in annual revenue from July 2027. Certain implementation costs will be incurred ahead of this time. Dividend guidance unchanged. | GREEN = (Graham) | |
GreenX Metals (LON:GRX) (£144m | SR11) | Tannenberg mineralisation consistent with producing Polish Kupferschiefer copper-silver mines. Review by independent metallurgist confirms potential suitability for a conventional flotation-based processing route, as used at KGHM's long-running operations and planned for Lumina Metals' Nowa Sól project. | ||
Castings (LON:CGS) (£142m | SR84) | Revenue -2.1%, with operating profit +108% to £10m. Dividend maintained at 18.4p. Despite subdued demand, foundry is now operating more efficiently. Forward order schedule suggests an increase in volumes of 5% to 10%. A recent power restriction to William Lee has now been lifted. | AMBER = (Roland - I hold) [no section below] These results are in line with expectation and highlight a significant improvement in profitability after a cyclically-challenging period for the business. Looking ahead, there seems some scope for top line growth as well as improved margins. However, I think the real test will be whether the company can succeed in building a more diversified customer base that’s less closely tied to cyclical demand from truckmakers. Early signs seem positive, with increased orders from wind farms and new capacity for larger castings. But I think it’s too soon to be sure. Castings’ robust balance sheet and good cash generation provide some protection but last year’s improved results still only showed a return on capital of 7% – not really enough to justify a premium to book value. I’m naturally biased and inclined to be positive, but in reality I think the valuation is probably up with events on a near-term view, following recent gains. | |
Brave Bison (LON:BBSN) (£108m | SR42) | SP +5% H1 net revenue increased by “at least 92%” to not less than £23m, while adj EBITDA is in line with management expectations. Trading remains weighted towards H2. | AMBER/GREEN = (Graham) [no section below] Valuation makes me a little nervous here, given that this can be viewed as a marketing consultancy (P/E 12.5x as of last night). And today's AGM statement doesn't provide an overall organic growth rate, which undermines the values of the headline growth rate given. We are told that the acquired business MiniMBA has organically grown by 18%. We've been moderately positive on BBSN and on balance that continues to look like a reasonable stance, given the momentum it's enjoying. Do watch out for an H2-weighting, with 53% of full-year revenues anticipated to arrive in the second half. Cavendish are forecasting full-year EPS of 8p. | |
Roadside Real Estate (LON:ROAD) (£105m | SR15) | Acquisition of Ross Road Petrol Filling Station & Completion of Acquisition | Agrees to buy a standalone filling station in Gloucester for £2.9m. Has now completed the £28.6m acquisition of the Hoch Group portfolio of 12 petrol station forecourts and a standalone convenience store in Cumbria. | |
Speedy Hire (LON:SDY) (£92m | SR40) | Revenue down 0.1%. Adjusted EBITDA down 12%. Adjusted loss before tax £9.8m. Statutory loss before tax £32.3m. “New financial year has started well, with revenue to the end of May 2026 c.2% ahead of the prior year.” Reconfirms market guidance for FY2027. | ||
Arrow Exploration (LON:AXL) (£76m | SR72) | The Icaco 2 exploration well was spud May 18, 2026, and reached target depth on May 26, 2026. It was drilled, on time and under budget and encountered multiple hydrocarbon-bearing intervals. Total gross corporate production is approximately 5,000 boe/d. | ||
Likewise (LON:LIKE) (£68m | SR63) | Year to date revenue +17% like-for-like. Given the widespread Global tension and uncertainty, H2 26 is very difficult to predict, but the Board remains confident in achieving market expectations for FY26. | AMBER = (Graham) [no section below] Impressive growth continues here and Likewise has continued to build momentum in recent weeks (20.8% like-for-like growth in June so far). But I think we are right to be neutral on this share, e.g. see Roland's recent coverage which outlined various positives and negatives. Being very careful when it comes to the floor coverings sector is generally the right approach for investors, and pre-tax margins at this distributor are expected to be only c. 2.2% this year. The £80m market cap suggests to me that the market is already pricing in margin expansion in 2027 and beyond - years for which there are no broker forecasts. The market's optimism might be justified but I think we are right to stay cautious. | |
Frenkel Topping (LON:FEN) (£64m | SR77) | Revenue +11%. PBT +24% (£5.2m). Funds under management £1,803m (2024: £1,560m). Current year: Trading remains in line with board expectations for the current year to date. | ||
Aura Energy (LON:AURA) (£57m | SR8) | The Swedish Parliament voted to amend the country's Nuclear Activities Act so that uranium mining will no longer be regulated as a nuclear facility. Consequently, uranium extraction no longer requires explicit municipal consent, creating a more predictable permitting framework which will facilitate future uranium mine development. | ||
Oxford Metrics (LON:OMG) (£52m | SR61) | Revenue +3%. Adjusted EBIT loss £0.2m. Management's expectations for FY26 remain unchanged, with revenue for the 15-month period expected to be approximately £56m, noting the delayed timing of an IVMS customer project… [GN note: some revenue has been delayed but it is still expected to fall within the 15-month financial year to Dec 2026.] | ||
CML Microsystems (LON:CML) (£49m | SR65) | Revenue £20.45m (FY25: £22.90m). Loss from operations, excluding exceptional items, of £1.93m. Cash £12.8m. Net assets £51.45m. “FY26 delivered significant strategic and operational progress despite continued market headwinds.” | ||
80 Mile (LON:80M) (£43m | SR43) | Written guidance from the Greenlandic regulator confirms that no third-party licence can be granted over the Company's hydrocarbon concessions covering the Jameson Land Basin, East Greenland. The Company continues to maintain guidance for drilling to start during H2 2026, subject to receipt of final approvals. | ||
Cadence Minerals (LON:KDNC) (£29m | SR54) | Mobilisation of the Azteca restart programme at the Amapá Iron Ore Project in Brazil has been completed and refurbishment works are underway across the principal processing, infrastructure and electrical workstreams. Cadence's total investment in Amapá is c. $16.1m, representing a 36.2% equity stake. | ||
Wynnstay Properties (LON:WSP) (£23m | SR68) | Rental income +7%. NAV per share +3.8% to 1,212p. Portfolio valuation up 2.9% on a like-for-like basis. “We have delivered very satisfactory performance from our property investments and operations over the past year…” | ||
Frontier IP (LON:FIPP) (£13m | SR19) | Placing closed at 12p, raising gross proceeds of £3.9m plus another £0.1m from Subscription. Retail Offer being conducted to raise up to £0.4m. |
Graham's Section
Smiths News (LON:SNWS)
Up 6.5% at 67.5p (£167m) - Contract Win - National Distribution - Graham - GREEN =
Some positive news: Smiths News has agreed “a transformational long-term contract with News UK & Ireland Limited”. News UK publishes The Sun, The Times and The Sunday Times.
The contract provides “(i) an expansion of the distribution territories in which the Company is appointed as News UK's exclusive wholesale distributor, thereby effectively securing national distribution of News UK's leading titles across all of Great Britain, to take effect from July 2027 and (ii) an extension in the contract term of our appointment through to July 2037.”
The revenue uplift is c. £125m per annum from July 2027, although it will require expansion of their distribution network with one-off implementation costs and transition costs. These will be funded from existing cash resources.
CEO comment:
"We are delighted to announce the extension and expansion of our partnership with News UK through to 2037.
This deepens a relationship spanning more than 50 years, securing a reliable and sustainable national route to market for retailers and consumers - and enabling us to freeze delivery service charges for our retail customers for the life of the Contract.
Estimates: Canaccord Genuity have left their forecasts unchanged today, pending further guidance. Smiths News say that they will provide further guidance on the financial effects of this contract “in due course”. Preliminary results for FY August 2026 are due in November, and those results will include the new guidance.
Graham’s view
I’ve been GREEN on this due to its excellent cash generation and clean results which have seen the company move into a net cash position and continue the payment of generous dividends relative to the market cap (the expected yield was over 10% last night).
What’s fascinating is that this contract might change the narrative around the company’s declining distribution business. Instead of shrinking, the company’s network is going to expand - presumably at the expense of smaller distributors.
It’s counterintuitive, but in a world where print newspaper circulation is declining, it seems that News UK prefers to have one national distributor, rather than multiple distributors. Declining circulation has therefore created a growth opportunity, through increased market share.
In the long-term, of course, print circulation should continue its overall decline.
But for now at least, and perhaps for the foreseeable future, Smiths News’ long-expected demise has been postponed further into the future. An incremental £125m should boost revenue forecasts by over 12%.
I’m obviously going to stay GREEN on this today. This cigar butt appears to have plenty of puffs left in it. It was trading at 6x earnings as of last night’s close, and is categorised as a Super Stock by the algorithms.
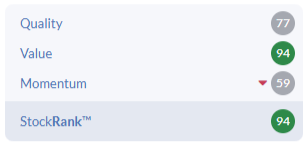
Games Workshop (LON:GAW)
Up 1% at £205.60 (£6.8bn) - Dividend Declaration - Graham - GREEN =
This is a tiny RNS:
The Board has declared a dividend of 90 pence per share, being the first declared dividend for 2026/27 (2025/26: 85 pence). This is in line with the Company's dividend policy as set out in its Annual Report and Accounts.
Graham’s view
Roland covered the full-year trading update here last month. That brief update didn’t mention any cash figure; the half-year report said that the company had cash of £171m, with a “cash buffer” of £85m.
For context, the dividend announced today will cost £30m. So there is no issue when it comes to affording it. Games Workshop has a long track record of successfully distributing the cash that is “truly surplus” to their requirements.
I also note this little line from the interim report:
We are not planning any share buybacks or acquisitions.
Refraining from buybacks is also what I would do at this valuation:
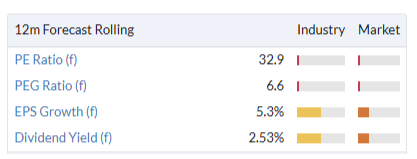
That said, I can’t find any record of Games Workshop buying back its own shares in recent decades, so I doubt that they would do so even at a lower valuation.
The absence of buybacks hasn’t held back the stock price:
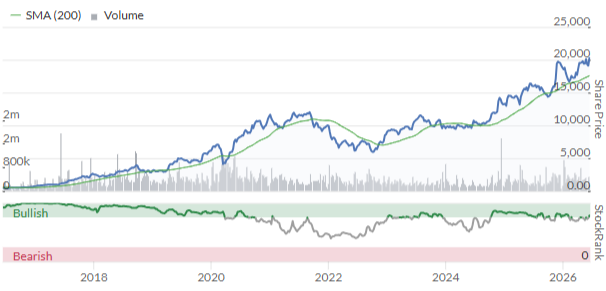
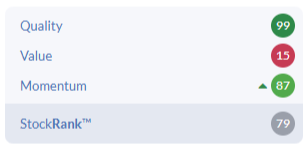
I’m going to leave our GREEN stance unchanged today. It’s a High Flyer, for good reasons (i.e. exceptional business quality).
Roland's Section
PZ Cussons (LON:PZC)
Up 7.6% at 98p (£421m) - Trading Update - Roland - AMBER/GREEN =
PZ Cussons shares have risen by 35% so far this year as signs have emerged that a difficult turnaround may now be delivering results for this venerable consumer goods group.
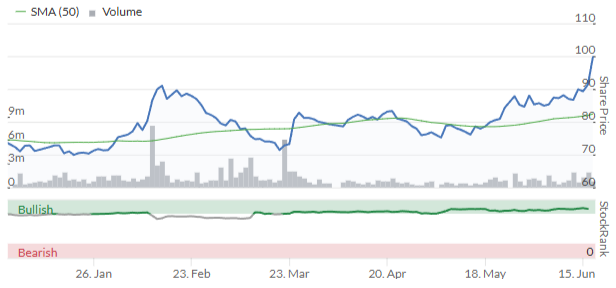
I covered this business in a recent Stock Pitch, so I’m pleased to see that today’s full-year update (y/e 31 May) confirms a return to revenue growth and nudges profit guidance higher.
Key points:
FY26 like-for-like revenue growth is expected to be c.6% (FY25: 8.0%)
Reported revenue (not LFL) is to be c.£540m (FY25: £514m)
FY26 adjusted operating profit to be “at, or slightly above” the upper end of the £53-57m guidance range.
Net debt is expected to be under £30m, a reduction from £112m at the end of May 2025. This largely reflects the proceeds from the sale of the group’s 50% stake in PZ Wilmar.
Is this a big upgrade? Not really.
In March’s Q3 update, the company indicated that profit would be “towards the upper end” of the guidance range. Today’s comment only indicates a modest increase to this expectation.
However, it’s worth remembering that PZ Cussons’ original guidance for FY26 was for an adjusted operating profit of £48-53m. Based on today’s guidance, I estimate that FY26 adjusted operating profit is now likely to be around 13% higher than originally expected.
EPS forecasts are flat: unfortunately, it looks like this improved operating profit isn’t expected to drop through to earnings per share. Consensus EPS forecasts have remained largely unchanged over the last 12 months:
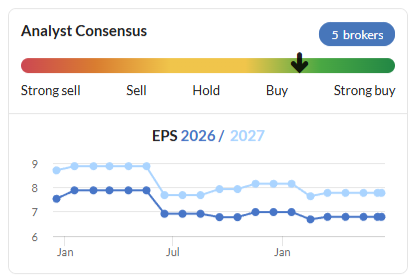
As I understand it, the reason for this is that a greater share of profits will be due to PZC’s non-controlling interests than last year. So-called minority interests are included in operating profit but are deducted from post-tax profit before calculating earnings per share.
Reflecting its complex and somewhat historic structure, PZC still has two subsidiaries where minority interests have a material shareholding. Both are listed in last year’s annual report as manufacturing businesses in Nigeria:
HPZ Limited (25.01% minority interest);
PZ Cussons Nigeria PLC (26.73% minority interest).
It looks like the improved profitability of the group’s Nigerian operations last year has translated into higher profits for these two manufacturing operations.
Even without researching this in detail, the StockReport shows us that profits due to minority interests can vary widely from year to year for PZ Cussons:
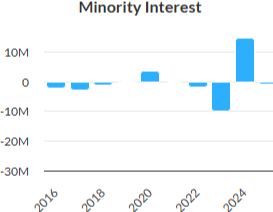
Last year saw minority interests take an unusually small proportion of profits. Recent forecasts from broker Singer Capital suggest their share of the group’s profits returned to a more normal level of c.£5m in FY26.
Outlook: there’s no new guidance for FY27 today, but the company has taken measures to manage expected cost pressures:
Looking ahead to FY27, the Group is mindful of the potential impact of the conflict in the Middle East and has already taken actions which are expected to offset a large majority of any cost inflation.
The minority interest issue makes it harder to model the impact of today’s revised operating profit guidance on earnings without some extra research. Unfortunately, I don’t have any access to updated broker notes today to short-cut this process.
What we do know is that consensus forecasts prior to today suggested adjusted earnings would fall slightly in FY26 (for the reasons discussed above) before returning to growth from FY27:
FY25 actual adj EPS: 7.34p
FY26E adj EPS: 6.8p
FY27E adj EPS: 7.8p
I would guess that full-year adjusted earnings may now be slightly above current consensus, but I don’t think the final result is likely to alter the broad shape of the earnings progression suggested above.
As Graham commented in March, recent share price gains for PZC appear to be out of proportion to the actual upgrades to guidance from the company.
Roland’s view
Of course, one possible reason for the strong share price performance is that investors are buying into a re-rating of the stock to reflect the recovery in sales and improved profitability.
PZ Cussons has been through a difficult period in Nigeria and elsewhere, but the balance sheet has now been repaired and the group’s performance does seem to have a new stability.
At 98p (at pixel time), I estimate the shares are trading on a FY27E P/E of 12.5x, with a possible 3.8% dividend yield. That’s still a fairly attractive valuation, in my view, especially as profit adjustments are expected to fall to minimal levels over the next couple of years.
However, given the level of change over the last year, I would like to see the FY26 accounts and updated FY27 guidance before getting too excited. As I discussed in my Stock Pitch, I believe this business still carries some risks relating to its geographic spread, (lack of) scale and product portfolio.
On balance I think it’s fair to maintain our previous moderately positive view today. AMBER/GREEN.
AO World (LON:AO.)
Down 2.7% at 93p (£532m) - Final Results for y/e 31 March 2026 - Roland - AMBER/GREEN =
Ed Sheldon covered AO’s full-year trading update in April, so we already knew that today’s results would be pretty strong.
Checking back through the archives, I’m relieved to see that I upgraded online electrical retailer AO World to AMBER/GREEN in November last year.
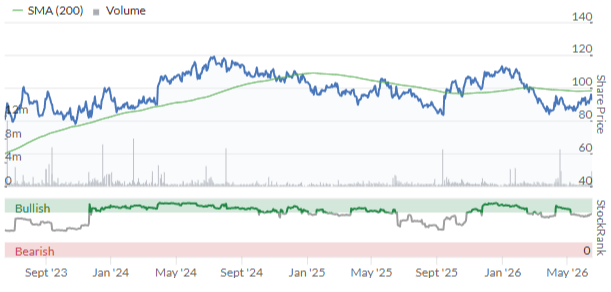
Although the shares haven’t actually performed especially well since then…
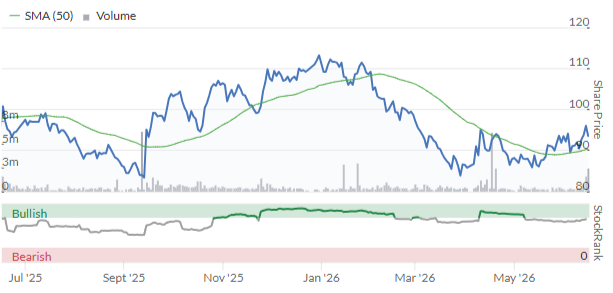
… the company’s performance has certainly improved, driving multiple broker upgrades ahead of today’s in line guidance:
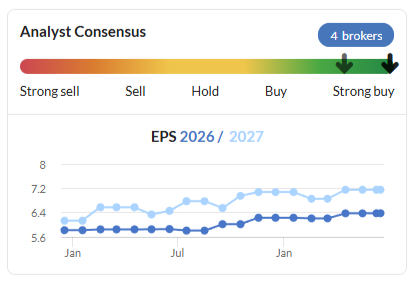
When earnings expectations are rising but the share price is falling, there are generally two likely explanations:
the shares were too expensive to start with;
market mood swings have provided an opportunity to buy at a more attractive price.
I think that both factors may apply here, justifying a closer look at today’s figures.
FY26 results highlights
Revenue up 11.4% to £1,266.6m
Core B2C Retail revenue up 9.5% to £911.0m
Adjusted pre-tax profit up 16.1% to £50.5m
Reported pre-tax profit up 145% to £50.5m – no adjustments!
Adjusted earnings per share up 11.6% to 6.36p per share
Free cash flow up 152% to £66.4m
Net cash of £16.4m (FY25: net debt of £35.9m)
Shareholder returns: to reflect the group’s improved cash position, AO is planning to return £20m to shareholders:
Special dividend: £10m
Share buyback: £10m
With a market cap of c.£540m, this gives a dividend yield of 1.9%.
The share buyback also looks reasonably valued. Using the methodology followed by Next, I estimate this purchase could provide a 9.3% pre-tax return. That’s comfortably above the 8% threshold used by Next to decide on buybacks.
Profitability: when profits rise faster than sales we know that profitability has improved. That’s certainly the case here – margins doubled last year:
Operating margin: 3.9% (FY25: 1.9%)
Return on capital employed: 21.1% (FY25: 10.6%)
For a business in this sector, I think the FY26 figures are pretty respectable.
AO has a medium-term target for an adjusted pre-tax profit margin of 5%, so founder-CEO John Roberts presumably still believes there’s scope for further improvement.
Balance sheet & cash flow: AO moved to a net cash position last year, but this appears to have been driven by a build-up of cash on the balance sheet rather than any repayment of debt:
Cash & equivalents: £81.3m (FY25: £27.4m)
Gross borrowings: £1.7m (FY25: £1.9m)
There’s a good reason for the lack of debt, though – AO effectively carries debt in other forms:
Lease liabilities: £63.1m (FY25: £61.4m)
Payables (mainly supplier credit on stock): £238.2m (FY25: £212.9m)
Cash, inventories and receivables broadly offset AO’s trade payables, resulting in a very capital-light business model:
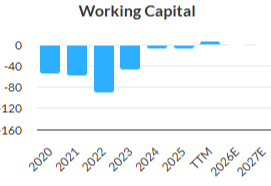
This type of business model can support strong cash generation and this is evident in today’s results.
Last year’s free cash flow of c.£66m was significantly higher than the group’s net profit of £36m. The largest single factor responsible for this working capital inflow of £20.6m, reflecting an increased payable balance. This is effectively increased credit from suppliers:
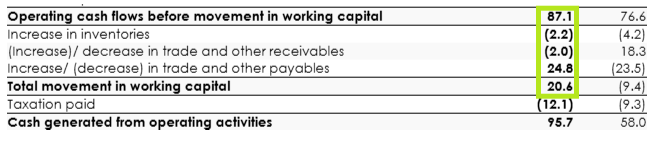
I’d be concerned if there was any sign that AO was stretching out its payment terms, but that doesn’t seem to be the case – in fact the reverse seems to be true. My sums suggest AO took an average of 87 days to pay its suppliers last year, down from 93 days in FY25.
The increase in trade payables last year simply reflects increased sales volumes. Even so, it’s a nice example of how the company can generate cash from fast-moving stock before it has to pay its suppliers.
Trading commentary
AO became the first retail globally to exceed 1 million Trustpilot reviews last year, with an average rating of 4.9 out of 5. I’m not sure how significant this is, but if nothing else it’s a useful reminder that the UK is Trustpilot’s largest single market, accounting for around 40% of its revenue.
Getting back to AO, operational progress last year included a new phone offering, cost savings and improved performance from its musicMagpie used business:
Attracted over 720,000 new customers.
The performance of AO’s membership offering is said to have improved, but no figures are provided.
Switch24 launched: this is a service that provides a new phone every two years for AO members; a flagship offer from last year was a new iPhone 17 from £17 a month.
Finance partnership with NewDay continues to perform well; 13% of sales were made on finance last year.
Completed offshoring problem, moving inbound sales to South Africa.
Post-pay mobile business is now profitable, reflecting improved network terms.
Soft launch of AO Mobile; planning full launch in the first quarter of the current year. Management believes that combining this offer with the Switch24 product could attract strong customer demand.
AO’s core major domestic appliance (MDA) business gained 1% market share to 17.1%; the company is now experimenting with own-branded offerings.
musicMagpie has moved from being a c.£6m loss-making business to being profitable on a run-rate basis.
Outlook
CEO John Roberts warns that the external environment “remains uncertain” but remains confident the company can deliver FY27 pre-tax profit in line with current market expectations.
Thanks to an updated note from commissioned research house Equity Development, I can see that adjusted pre-tax profit is expected to rise by 5.9% to £53.5m in FY27.
EPS forecasts are also unchanged for each of the next two years, with slower growth expected this year and a more significant step up in FY28:
FY27E adj EPS: 6.5p (+3% vs FY26)
FY28E adj EPS: 7.6p (+13.8% vs FY27E)
These estimates put AO on a FY27E P/E of 14, falling to a P/E of 12x in FY28.
Roland’s view
AO shares have been rangebound for three years. I think it’s probably prudent for investors to remember the core attributes of this business; it’s a low-margin box shifter that operates in an intensely competitive market.
Having said that, this business is performing well and appears to be following a similar strategy to UK sector leader Currys. I would guess AO will reach a point where competitive pressures cap further (profitable) growth, but I don’t think the company is there yet.
Although I wouldn’t want to pay a high earnings multiple for this business, I’m inclined to think the current valuation is fair given the positive earnings momentum. I think the leadership of founder-CEO John Roberts – who has a 14.6% shareholding – is also a positive factor for outside investors.
On balance I’m going to leave our moderately-positive view unchanged today. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
I have two EV's, 6.8 kwh solar panels and a 4.6 kw battery. I'm currently on Intelligent Octopus Go fixed tariff that gives me 6 hours of cheap rate electricity overnight. This is enough to charge one of the cars which has a 32kw battery for about £1.50 which equates to about 1p per mile. The other EV is a 77 kWh battery so takes about 10 hours to fully charge from near zero. This is easily managed by successive sessions over two days.
I rarely use public chargers except on extended trips away from home.
Solar has been a complete game changer for our electricity and vehicle fuel bills. On average I use just over 12 kwh of electricity per day across all seasons. 80% of this is cheap rate and I export an average of 9 kwh for which I receive 12p per kwh. We don't have a gas supply so rely on oil fired heating but try to buy when prices are seasonally lower.
Prior to installing solar and changing cars, my electricity bill was £157 per month. Now I expect to pay less than £30. A few behavioural changes like doing the washing overnight and generally maximising the advantages of the installation have made a huge difference.
Given the right location, and ours is far from ideal, solar can be very rewarding.
And I guess £17 of that £30 are the standing charges
indeed, £16.42 regardless of how much or how little I use. I guess it's fair to pay for the infrastructure that delivers my power but when it seems the government will ask me to pay per mile for driving my car, wouldn't it be fairer to base the standing charge on usage too?
We have 2 evs at home and charge via excess solar and have found that since March charging hasn’t cost anything through imported electricity so from our point of view charging at home via solar is a big thing and with a little planning we fully charge regularly. We also use an overnight Ev tariff of which may be needed from October to February.
What would be helpful if the vat rate of 20% charged at supermarkets, services etc was reduced to the domestic rate of 5%
Thank you for your comments on Castings Roland, we also hold and it was a pleasant surprise to read their more upbeat results and forecast this morning. Our holding started over ten years ago but by some judicious (reckless) adding, we're at break even, the dividends have helped of course. We'll hold but no more adding!
Daniel Thwaites (OFEX:THW) Stoncking figs from . Now at historic p/e of 7.5 and a 75% discount to NAV. !
Must be the cheapest stock in the sector, if not the market.
Smiths News (LON:SNWS) “Declining circulation has therefore created a growth opportunity, through increased market share” - fun fact, this is a rare example of the Old Warhorse category in the extended Boston Matrix which includes shrinking or negative market growth. These can be hugely profitable opportunities - well done to holders!
So, seemingly the beginning of an end to the ME conflict ( buy the rumour sell the news?) and UK inflation coming in better than expected yet main UK indices drop. A weaker pound would help the FTSE100 exporters and the FTSE250 CO’s should benefit. What am I missing??
TIA
If you discover the magic formula to predict how an index or market will perform, given a series of limited inputs such as geopolitics, economic indicators, currency, etc.
You'd win a Nobel Prize.
What are you missing? Oh... maybe a few hundred other factors. Ever changing weighting of said factors. Sentiment. Human buys and sells dictate the prices. Humans are fickle.
I've stopped trying to make "sense" of how an index, market moves day to day. It's like trying to figure out a unifying theory of the universe. Intellectually, it should be possible. Practically, you might go mad in the process.
One approach is just shut your eyes for the rest of the day, look again at 8am tomorrow :)
(Ignore all the above is your goal is to be Master of the Universe - whether its the stock market, or physics. Then I am rooting for you, as it would be really amazing if in my lifetime, someone discovers the magic formula for the stock market)
I entirely agree with you Boon, I'm giving up on looking for the holy grail and am sticking with what I know.
Wise words Boon regarding looking at the ticker all day.
It’s not even ethical to check your portfolio balance every 2 minutes while at work!
All the best
Please just go away as you have previously promised
My man
You are more obsessed about my posts than anyone here (even me).
That’s nice!
Personally I appreciate the widest breadth of views on this website ..I will however not follow Ben into Nanoco (LON:NANO) ..but.wish him the best
June, not a great month...
Nothing really - be curious - it's interesting to think about why the market doesn't move how you expect. BUT it makes no difference to long term returns. Warren tells you to compound long term returns so daily - monthly - annual returns make virtually no difference. Long run averages are all that matter and staying invested. During conflicts and other events that could turn either way - there is so much hedging extreme movements in place - knowing how this unwinds is very difficult. So they often involve misleading moves. The reason I look at VIX and MOVE is they measure volatility which tells you when fear is very high....which it was a month or so ago. Actually markets have already recovered their poise before Trumps announced peace plan.... so had less room to spike on the news. I think most economists would tell you wars, catastrophes etc have very little long run impact on markets actually. So far the Iran conflict has had next to no impact. Yet only a few weeks ago this would have seemed a naive claim to make. So in answer, you aren't missing anything - equities are a long term compound game - not what happens next.
Thank you RD . I was expecting a stronger start, mainly on the UK inflation numbers for the domestic CO’s in the 250 and exporters in the 100. So I thought I may have missed some relevant news. Obviously as soon as Wall St opens that is a different matter.
Oxford Metrics (LON:OMG) Mr Market apparently doesn't like the delayed revenues. The Non Exec Chairman has bought 33k worth. Would be nice to see the CEO and CFO buy some,
Optimistic I think.
ROAD
Am I alone in my sceptic's view of Roadside? Not sure I see the quality in buying up Petrol forecourts for redevelopment as what? The board seems replete with property ' heavyweights' and some high profile special situation investors seem on board
EV charging would be the obvious answer. Will EVs need more charging than fossil fuel vehicles? Takes longer for sure. There is still a shortage of EV charging points.
Not much longer now- Cardiff gate I can get 200 miles in 15 mins. So by the time been to the Loo , bought a drink
I see and how much do they charge?
My diesel would do well over 600 miles on a tank.
UK only 5.9% of cars are EV, that will change in the next 10 years, maybe these disused petrol stations will be needed. Or will batteries improve that they have 500 mile range and most people will charge at home using solar?
It's 77p but with my Kia card get 15% off. Hope charging is 9p from 12:00-6.00am. I get up to 390 miles depending on driving conditions. Got from Laugharne to Manchester on 50%- regenerative braking helped with all the Welsh hills as we went cross country. 600 miles should be available soon- though might mean solid state batteries and not sure what the current infrastructure could support. Choice thing for me, as a well knowns supermarket says every little bit helps. And I am aware of the cost of batteries etc in terms of the planet. the guardian now publish this reading daily
we certainly need more charging points for thats for sure.
i think there is perhaps though plenty of natural space at pressent though away from motorway networks at present.
perhaps there is scope in prime spots to have say mini supermarket greggs - burger place - wash your clothes and charge your car - so perhaps some scope.
As range increases there is no doubt that more and more charging will be best done at home overnight - so whilst there is extra capacity needed for sure - it it soemthing that can make wonga from asite compared to say building 6 or 8 flats ?
I don't think charging at home on Solar will ever be a big thing. Home chargers are already 'slow' at 7Kwh, not many people have a solar array of that size at home. A 3-4kwh charging rate (what a typical home solar array would be) is ok for a bit of topping up, but not full charging.
Assuming all the extra promised wind capacity comes online, then overnight charging should become very cheap, or even negative pricing if you're on the right tariff. There should be lots of surplus energy then.
Some of the pricing for EV charging is scandalous- the likes of BP Pulse & Gridserve charge 90p plus at Motorway services. Somehow Tesla do it for a max of 55p for non Tesla owners.
'A 3-4kwh charging rate (what a typical home solar array would be)'
How many days in a year do you see 3-4 kwh though? One thing I have never understood about my solar panels is that when it's really hot they only produce 2.5 kwh. For some reason, they don't like too much sun. And of course in winter, you can forget about getting meaningful quantities of electricity.
The efficiency of solar panels reduces with the hotter they get, plus it's the capacity of the inverter that dictates how much power you generate - these are usually sized smaller than the capacity of your panels.
I understand that the efficiency of the panels declines as they get hotter, what I don't understand is the physics behind this.
according to copilot
The short answer: solar panels produce less power at higher temperatures because heat reduces the voltage they can generate, even though the sunlight might be strong. Solar cells love light, but they don’t love heat.
roof mounted panels can get much hotter than the air temperature. However, mine can still generate impressive amounts of electricity even in hot weather so it's certainly not a reason to avoid roof mounted panels unless you have an empty field you can use instead.
the real dealbreaker for electric cars would be having charge points installed on streets where there is no off street parking - it cant and shouldnt be that hard to find a solution. note that should be done at equivalent price points to what your home rates would be - any infrastruicture costs should just be part of the highways budget.
slightly surprised there has been very little done in that area yet - perhaps thats not the worst thing in the world though - if the entire tech and clever solutions are improving each year do you really want to splash out money now - if stuff will be dated and not fit for purpose in 5-7 years.
Heck in the meantime even a botch it channel cut in the in the pavemnt to allow cable top be fed through would get the job done for many - as others have said electircx cars are perfect to use up spare night time capacity.
i wouldnt poo poo solary and battery combo - albeit pehaps for most as we are now thats not gonna work and would be too expensive.
if i go in a busy bar on friday night i am gonna pay treble what i pay in spoons for my drink - so i dont think we can expect out and about charging to be cheap - not sure if the charging structure reflects the fact they want to get their capital costs back too quickly? perhaps it would be up to the gov to sort something out if they want to make prices reasonable.
Not sure how long these charges last ? it alwqays used to be the fcat many would be out of order - so i expect the all in costs aint cheap - higher volumes might help.
I am huge electric car fan - i am quite happy with progress we have made - i think the original goals to get everyone electric uber quick were perhaps always doomed for failure.
is it just me or does it all seem to have gone quite ref doom and gloom ref end of the world - obviously its getting hotter and we have more co2 - and some areas wil obviously be hard hit (thats natural as climate changes) - but the polar bears dont seem to be dying - and i think it was quoted that with global warming we would actually have more green land than before - perhaps the solution is to move half the population of africa to siberia as that area warms up
We have charging from lampposts in the London borough where I live. The council did a deal with a company to install these for free but then gets the revenue. Not cheap.
I kinda guess the niche solutions will never be cheap - if it’s for local residents it has to be cheap to work - presumably that either has to be power from house with access point - or just lay cable along the entire street - for someone parking near their house it’s no use if they pay double or treble the unit price they pay at home - if gonna mandate an electric car charging near home must be reasonable - powers that be aint done owt yet in that regard - hopefully solutions will be worked out sometime in next 5 years
FT says the IEA monthly report predicts an oil glut next year.
Morning Graham ,I see another busy day for you! I suspect you will be covering SNWS ,RNS , as it seems to be a favourite income share . I hold ,but with the Iranian situation hav'nt added ,as a major expense must be diesel fuel . However that situation may be coming to an end ,thank goodness for all of us. I wonder what your thoughts are on the seemingly excellent RNS . It would appear there are a number of upfront expenses ,I'm guessing that's the extra vehicles and depots ,that may be required ? Although the fixed divi. seems to be safe ,do you think the 'special' will be used to cover the upfront 'new' expenses ,or have I read that wrong ?? thanks for your observation Tony
Hi Tony! I don't think SNWS themselves have figured out that full ramifications of this contract yet.... apart from it being very positive for them! G
Iran won, it seems. What will it now take to MAGA?
Meanwhile we have a Russian guided missile destroyer mooching about in the English Channel with its friend or foe beacon switched off, determined not to allow even a yacht to approach closely. Makes me wonder what those missile cross-hairs are targetted on right now.
My immediate reading on this is that the story is overblown. I've crossed the channel many times in a small yacht, one of the busiest shipping lines in the world. And one of the first rules of sensible sailing crossing major shipping lanes is you keep well out of the way of large ships, regardless of any notions power gives way to sail rules. The second is that if you change course to keep out of the way you make a large correction, 20 degrees or more minimum, so there is no chance the other boat doesn't understand what you are doing. I've seen it quoted twice, on separate occasions that the yacht changed course by 2 degrees. That's ridiculous. Far too small to be obvious that the yacht was taking avoiding action, it would hardly show, and well within margin of error with wave effects etc. So they were warned twice by conventional means, 5 horn blasts, and would have appeared to be taking no action. Warning shots as a back up certainly seems extreme, but for a Russian captain the possibility of a collision with a British yacht in the channel would have looked career ending, so it's not hard to see that given conventional means would have appeared to have failed to them, they tried something more extreme.
MIGA
That is a very strange statement. There are other social media channels for political statements. I wonder if the Iranian people feel they won!
Apologies,I should have been clearer. It seems likely that changing perceptions of US power will have an effect on many areas that will affect investors. I would welcome views on how this might play out over the next few years.
Trumps venture into the Middle East has been nothing short of disasterous and history will not be kind. Trump will spin this as US making the world a safer place to his fan base who either have no idea where Iran is or care even less. Most Republicans only think about the price of Gas and if they can cook it on their Grill. Nothing now matters until the mid terms elections and the ' hell' that would break loose if Trump becomes a ' lame duck' president. Wait for the increase in ' executive orders' ahead of Nov if the Democrats are likely to take control
Their cross-hairs will be firmly fixed on Lancashire Holdings (LON:LRE) as the US/Iran peace deal becomes effective thus removing the maritime insurance threat and they want a high teens yield!!!
I like that eggsbaconandbubble, I hold Lancashire Holdings (LON:LRE), having put the crosshairs on them earlier this year.
War risks, have been very profitable for Underwriters, in the past. Now the rates will fall.
Can you expand on this comment please with more explicit comment on the investment proposition at Lancashire Holdings (LON:LRE) ? "In the cross hairs" could be understood in various ways. While I think I understand where you're coming from concerning Hormuz risk and contingent premiums, presumably there is more to the company than the straits? My shallow understanding of LRE is that it specialises in catastrophic risk; which carries a double risk/reward. Higher incidence of insurance claims following disasters push up premiums, and the converse - which is no doubt what you are referring to? In short, do you see this therefore as a buy or a sell? I'd add that one is no doubt also buying not just the geopolitical risk but the company's expertise in assessing and underwriting, and its shareholder friendly dividend policy?
Bond yields have pretty much fallen across the board and MOVE remains extremely well behaved by recent standards sub 70. The TIP spread over conventional Treasuries has not moved and so Oil weakness has had no impact despite falling 30%. All the action was in spot however, Bulls were waiting for forward curves to rise to reflect shortages but bears expected spot to fall. So spots fall relieves some pressure but has little impact on financial markets thus far. For now I think rate expectations are in no mans land but lean up not down. All very dependent on whether the treaty holds and the straight does open, and thus remains open. The market is assuming it will.
However supplies and stocks are already low so we are more exposed to a deterioration than the first time....so it would be reasonable to expect Oil to remain a little higher than pre war. Net net that would be a small negative for the economy to absorb but nothing like as bad as the straight remaining closed. Seems to me, it's not been that straight forward to trade even though index levels are reclaiming highs. Id be happy enough lightening the load around here .... esp with Vix very normal at 16 ..... since risks to the economy remain in place.
With regards to Frontier Developments (LON:FDEV) has does it go literally overnight from a 96 Super Stock all the way down to a 63 High Flyer? How does this algorithm work?
Trying to work out if its a glitch and will be back up tomorrow, or sign of something going seriously wrong.
The market cap is wrong. I wish it was £633m. I reported it so hopefully will be fixed. Frontier Developments (LON:FDEV) FDEV
I suspect it is linked to an error with the Market Cap. Currently showing as £633m when I think it should be closer £150m which seems to have severely hit the Value score.
Thanks CharlieT and FederalReserve, I was close to hitting the sell (under 70 STOCKRANK) but will watch with interest.
Its just undergoing an ABC correction IMO. I'm looking for the buying opportunity. Around 410p IMO.
Rockwood Strategic seems to be duplicated on the table with the same RNS comment.
Fixed that, thanks!
FINAL CALL for AGAINST voters: Nanoco PLC (NANO).
Proxy Voting Deadline: Wednesday, 17 June 2026, at 10:30 a.m. BST (This is the final deadline to submit electronic proxy appointments or Forms of Proxy).
Folks I know I've made a few of these posts but this one might be the most important of all.
We really are looking at the final opportunity to vote now. HL have a voting deadline of later on today. Other brokers will be similar. Whether you have 10,000 shares or many more than that it all counts. Collectively we have real power here.
We know we are rapidly closing in on the GM day now. HL shareholders alone hold 21% of the shares here. Imagine the difference that makes to the outcome. We can easily defeat this. To vote with HL, just go to Investor Inbox or this link when logged in https://online.hl.co.uk/my-accounts/investor-mailbox If anyone isn't sure about how to vote with their own broker, please ask I'm sure somebody can help.
VOTE AGAINST TO STOP THIS HEIST AND KEEP THESE SHARES LISTED.
Nanoco PLC are trying to delist their company and take it private when it is more than 90% owned by retail shareholders. The market has voted about it by slashing its market cap to less than half its account balance. Nanoco PLC still has a cash balance of £10.1 million as at 19 May 2026. Hargreaves sent a note to its clients yesterday alerting them about this but they didn't tell them about the cash balance so some could have been frightened into selling. Please help us get the word out - if you have a following I would appreciate you tweeting this message.
Ben, I edited your message to make it shorter. Several readers have been unhappy with your posting re: Nanoco. In future, if you're going to make repeated calls for action, a shorter message would suffice. Thank you!
thanks but I hope you understand my mission. Nanoco PLC is mostly owned by retail investors and I'm trying to rally as many troops as possible to stop the delisting.
Doubt that there are many Stockopedia subscribers still wasting their money on Nanoco (LON:NANO) . It’s down 99%from the all time high,, and down 77% over 1 year. So constantly posting the same thing about Nanoco on this quality thread is likely to influence a tiny number of subscribers. Why not start a separate Nanoco (LON:NANO) thread instead?
too late now - most nominee accounts will close voting today.
Yes, but yours is not the ONLY topic of interest to the Stocko community, and by reposting a long lengthy post every day... isn't that just selfish spamming?
Especially when viewing this Report on a mobile device, where you have to scroll loads to get past your daily copy+paste.
Sorry for the harsh words. I know that Nanoco is a very important subject to you. But be aware that its one of tens of topics daily that people want to discuss on this Report.
Here's a suggestion. Keep posting daily to raise awareness. But keep it to 3-4 lines. If the topic is so compelling, find a way to tell it succinctly. And provide a link out to a previous comment in a previous Report, with the longer story (use the link button you see below each comment to generate that deeplink).
Is the market smelling that the delisting will be defeated? Stock is up today. Voting online has closed now. My questions. Was Glass Lewis genuinely acting in the best interests of Nanoco shareholders when it recommended support for this delisting? What due diligence did it actually carry out? And crucially, was Glass Lewis paid, directly or indirectly, by Nanoco or its advisers in connection with this recommendation? Shareholders deserve to know whether this was an independent assessment or just another piece of board-friendly cover.
Secondly, if the board uses the votes attached to the Nanoco Group PLC Employee Benefit Trust to push through delisting, then in my view that should trigger an immediate vote of no confidence in the board.