Daily Stock Market Report (Wed 2 July 2025) - BYIT, GRG, TPT, SSPG, STB

Good morning! It's a relatively quiet day today, albeit with one or two nasty profit warnings.
The agenda is complete.
Update 12:15: I'm afraid that's all we have time for today, thanks for you all your comments.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
Shell (LON:SHEL) (£152bn) | EY’s 2023 and 2024 audits were non-compliant with SEC rules. Now restated with no changes. | ||
Direct Line Insurance (LON:DLG) (£4.0bn) | DLG shares will be suspended from 07:30 today. Holders will shortly receive new AV shares/cash. | PINK | |
Spectris (LON:SXS) (£3.8bn) | KKR has made a cash offer of £40. This is a 6.3% premium to the earlier Advent offer of 3,763p. | PINK | |
Greggs (LON:GRG) (£2.0bn) | PW: H1 rev +6.9% w/ 2.6% LFL growth. Slower in June. FY op profit now exp below 2024. | BLACK (AMBER - Megan holds) The improved trajectory in lfl sales growth has come to a sudden halt, to the extent that management now think op profits will be lower than last year. It’s hard to tell whether this is a short term blip or a more fundamental problem. I am wary enough to move back to neutral. | |
SSP (LON:SSPG) (£1.4bn) | SSP is IPO’ing its Indian JV, in which it will maintain a 50.01% stake. Price range c.£1.2bn. | AMBER (Roland) [no section below] This IPO is being carried out to allow SSP’s Indian JV partner to sell its stake in the Travel Food Services business. SSP is not selling and will not receive any proceeds from the IPO. However, SSP says the book cost of its 50.01% stake will be just £70.4m. If this IPO achieves its target valuation, SSP’s stake in TFS will then be worth c.£600m, or nearly half the group’s market cap. The StockRanks are neutral on SSP, but I wonder if this situation could be worth a closer look for interested investors. | |
Bytes Technology (LON:BYIT) (£1.2bn) | Seen some deferred buying decisions. H1 op profit now exp below last year. FY update in Oct. | AMBER/RED (Roland) Bytes warns that a combination of internal and external issues has hit sales in H1 and is expected result in a fall in H1 profits. Full year guidance appears to have been withdrawn, with an update promised in October. I’m concerned by the change of tone since May’s results and the potential for a further de-rating, given the stock’s former High Flyer styling. For now, I think it makes sense to remain cautious. | |
Georgia Capital (LON:CGEO) (£706m) | Existing $50m buyback increased by $18m. Completes plan for GEL 300m of returns by end 2026. | ||
Capita (LON:CPI) (£379m) | Statement re H1 2024 segmental restatement & Amendment and Extension of RCF | £250m RCF extended by 12 mo. to 31 Dec 27 with £50m accordion. FY25 guidance unchanged for broadly flat rev w/ higher op margin. | |
Secure Trust Bank (LON:STB) (£152m) | Vehicle Finance to be run off. Pro forma FY24 PBT would be £56.6m (prev £39.1m) and +8% ROAE. | AMBER/GREEN (Roland) STB’s Vehicle Finance unit was heavily loss-making last year and accounts for more 30% of the group’s cost base. Today’s decision suggests to me that management can’t see a clear path to an attractive level of profitability. Given the more difficult regulatory and legal environment for motor finance at the moment, I think STB’s decision looks sensible and has the potential to improve overall returns. With a 50%+ discount to book value and 4%+ yield, I am happy to remain moderately positive here. | |
Avacta (LON:AVCT) (£118m) | FAP-Dox progressing in Phase 1b studies, FAP-EXd preparing for Phase 1 trial in Q1 2026. | ||
Topps Tiles (LON:TPT) (£67m) | Q3 sales +10.1%, YTD +6.1%. LFL sales +4.4% YTD. Confident can deliver “meaningful” FY profit growth. Zeus forecasts unchanged today: FY25E EPS: 3.3p | AMBER/GREEN (Roland) [no section below] | |
Metals One (LON:MET1) (£56m) | Acquired Uravan project in Colorado for $50k +500k new MET1 shares. 10yr explo lease. | ||
| K3 Business Technology (LON:KBT) (£39m) | Proposed Tender Offer, Cancellation & Notice of GM | Proposed £29m tender offer at 85p to return Nexsys proceeds. Will then be delisted from AIM. | |
Ariana Resources (LON:AAU) (£26m) | Identified 500m long gold anomaly, “geochemically significant”. In priority area for drill testing. | ||
Empresaria (LON:EMR) (£13m) | Possible offer (see May) of 10pps + 50pps in 3y loan notes. Already has 57% shareholder support. | PINK | |
Blencowe Resources (LON:BRES) (£13m) | Completed 3 deep drill holes at Northern Syncline. Confirm mineralisation to below 100m. |
Megan's Section
Greggs (LON:GRG)
Down 14% to 1696p (£2bn) - Trading statement - Megan - BLACK/AMBER
I don’t like it when non-meteorological companies blame the weather for a poor sales performance. Summer is warmer than spring, winter is colder than autumn. We’re getting a few more extreme events every year but, by and large, it’s the same pattern that we all learnt when we painted pictures of the trees in nursery school.
And yet, it’s the warm weather which Greggs’ management is blaming for a slowdown in like-for-like store sales in June.
I am also frustrated by the mathematical challenge presented by the dates in these announcements:
On 20 May, we had an announcement saying like-for-like sales growth for the first 20 weeks of the year (to 20 May) was +2.9%
Today’s trading statement covers the first 26 weeks of the year (to 28 June) and reports that lfl sales are now up 2.6%
But also today’s statement says that the performance in the first 11 weeks (to 17 May) was good and the trend continued throughout the rest of May
And it has actually just been June (i.e. the last four weeks) when trading has been more disappointing
My interpretation of this muddle is that in May, management were tentatively hopeful that the slowdown in like-for-like sales reported in 2024 and early 2025 had come to an end and perhaps jumped the gun a bit on reporting this to the market.
If they had waited until now to report a 2.6% increase in like-for-like sales to the market, we’d have probably been delighted. Like-for-like growth at 2.6% is still a welcome turnaround from the 1.7% reported in January and even the 2.5% growth reported in Q4 of 2024.
I am still bothered by the blame being pinned on the weather (although I must admit that when I was in the Greggs on the A12 near Witan on Friday, the lady serving me my sandwich did have a little moan about the heat). My fear is that there is only so much marketing the mega-machine at Greggs HQ can do to encourage the British public to ditch their McDonald’s, Starbucks and M&S sandwiches and lurch for a sausage roll instead.
Growth opportunities are more readily found in the store roll-out programme, which remains on track. In the first half, the company opened 87 new stores and says it is on track for between 140 and 150 net openings for the full year.
Higher costs lead to profit slowdown
The combination of weaker sales growth and planned store refurbishment means operating profits are expected to be slightly lower than the first half of last year when management announces its full interim results on 29 July. (In H1 2024 operating profits were £75.8m off £960m of revenue).
With total interim revenues of just over £1bn in the first half and operating profits now forecast to be below £75.8m, we’re going to see another disappointing erosion of operating margins.
In the second half, the impact of higher national insurance contributions will also have more of an effect on costs, but management says its “mitigation measures” should enhance the second half performance. Still, annual operating profits are also expected to be down on last year’s £195m.
Megan’s view:
I am really on the fence here.
Evidence from studies suggests that the worst thing to do in the event of a profit warning is nothing. Either take advantage of the share price weakness and double down, or cut your losses. Being caught in uncertainty is a mistake.
On the one hand, I really don’t think today’s announcement is as bad as all that. Further weakness in operating margins is disappointing, especially as some of that seems to be coming from the refurbishments which can’t be a surprise to anyone.
On the other, this is a change in trajectory. And it was the improved trajectory in like-for-like sales growth which made me add Greggs to my portfolio in the first place. Any change in the investment case is a reason to cut and run.
I am going to sit on this today and not make any rash decision, but my hunch is that Greggs might be getting replaced in my portfolio. I really don’t want stocks that make me uneasy and there are a few things in this announcement which just don’t sit right. AMBER
Roland's Section
Bytes Technology (LON:BYIT)
Down 24% to 383p (£922m) - AGM Statement - Roland - AMBER/RED
Bytes Technology stock opened down by 25% this morning, after the company warned of deferred buying decisions and a drop in H1 operating profit. Perhaps more worryingly, Bytes appears to have withdrawn its full-year guidance, instead promising an update with its interim results in October.
Commiserations to shareholders. I suspect many are looking at their screens and wondering what’s changed in the seven weeks since the company issued FY25 results in mid-May, when management confidently guided for “high single-digit operating profit growth” in FY26.
Today’s AGM Statement is relatively brief and I don’t have access to broker notes for this company. So what I’ve tried to do is to identify the key points and check back to the full-year result in May to see what was said on these topics at that time.
What’s gone wrong?
Bytes’ financial year starts on 1 March, so today’s commentary covers the first four months of the year.
Deferred buying decisions: the company says some customers have deferred buying decisions due to macroeconomic conditions, especially in the corporate sector.
In May, Bytes said “sustained demand in structural growth areas” underpinned confidence for continued strong sales growth in FY26.
Restructuring sales teams: the company has reorganised its corporate sales from generalist teams into segments based on customer size (e.g. enterprise, corporate, mid-market). This process seems to be taking longer than expected, although it is expected to deliver positive results eventually:
While this transition has resulted in a longer than expected readjustment period, it positions us to deliver more relevant solutions and drive sustainable services annuity income growth during the second half of the financial year ending 28 February 2026 and beyond.
This reorganisation was mentioned in May but no comment was made on any potential impact.
Microsoft enterprise sales incentives: apparently some changes made this year have had an adverse impact on H1, due to high levels of public sector renewals in March/April and June.
This was mentioned in May’s results, but again the impression I got was that Bytes had been able to plan ahead and mitigate this impact:
This year, Microsoft communicated a particular amendment to its enterprise agreement program, reducing certain transactional incentives, in advance of it taking effect in January 2025. This provided time for us to prepare and to realign our software and services offerings, as we have often done in the past […]
Updated outlook
As a result of all these factors, Bytes has issued the following guidance for H1 today:
H1 gross profit at a similar level to last year
H1 operating profit “marginally lower” than last year
Expect normalised growth in both metrics in H2
Update on FY26 guidance will be provided in October
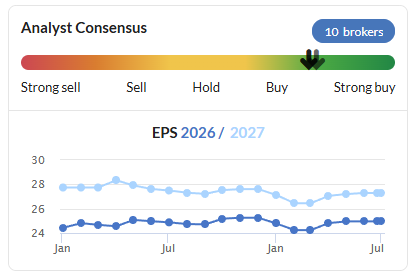
For context, consensus forecasts prior to today suggested Bytes would deliver c.14% revenue growth and 9% EPS growth this year.
Roland’s view
A slowdown in corporate sales may not be good news for Bytes. Although the public sector generated 65% of the group’s gross invoiced income last year, higher margins on corporate sales mean that the private sector contributed 65% of gross profit.
The issues raised in today’s update also suggest to me that operational failings or miscalculations may have worsened the impact of macroeconomic trends. I can’t help wondering if the process of restructuring the corporate sales team may have disrupted some corporate sales wins.
In the absence of updated forecasts, I’ve taken a stab at estimating what level of operating profit might be suggested by today’s statement.
Looking at the numbers, Bytes profits have consistently been weighted to H1 in recent years:
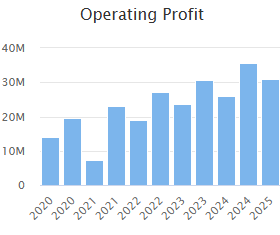
The H1/H2 operating profit split last year was £35.6m/£30.8m.
If we assume that today’s guidance for “marginally lower” H1 operating profit suggests a figure of perhaps £34m, then today's guidance for “more normalised growth” in H2 might suggest a figure of perhaps £32-33m.
A result like this would leave FY26 operating profit broadly unchanged from last year’s result of £66.4m.
This would be a downgrade from previous FY26 guidance of “high single-digit operating profit growth”, but perhaps not a disaster in the scheme of things.
I suspect the underlying reason for today’s big share price fall was that Bytes’ shares were priced for strong growth, on a P/E of 20. This kind of High Flyer styling isn’t sustainable without regular doses of positive news:
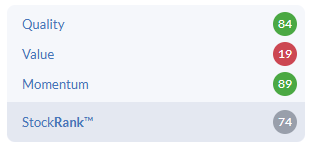
The combination of a de-rating and a likely earnings downgrade has resulted in a sharp fall – but Bytes shares are still trading on 17x FY25 earnings.
Private investors will have to wait to see what changes to consensus forecasts feed through in the coming days. I’m concerned by the company’s decision not to issue any updated full-year guidance today.
Statistically, we’ve found that a company’s first profit warning is often the start of a longer period of underperformance.
For now, I have no choice but to downgrade our view on this stock to moderately negative. AMBER/RED.
Secure Trust Bank (LON:STB)
Up 8% to 861p (£164m) - Strategic pivot to increase Group ROAE - Roland - AMBER/GREEN
Secure Trust Bank PLC ("STB" or the "Group"), a leading specialist lender, announces a pivot in its strategy away from Vehicle Finance that, over time, is expected to improve its Return on Average Equity ("ROAE").
Motor finance has become a difficult and fraught area for UK lenders recently due to a range of regulatory and legal interventions. Secure Trust Bank has decided to cut its losses and exit this sector altogether, in order to focus on its more profitable property and business lending operations.
With immediate effect, STB has decided to stop Vehicle Finance lending and put its existing loan book into run off. This division generated a pre-tax loss of £21.8m last year on net lending of £558m. Stripping this out would have increased the bank’s overall return on average equity by 8% last year, according to today’s update.
One problem here seems to be that Vehicle Finance carries unusually-high overheads. This division reported operating costs of £31.6m last year, or 30% of total costs. This is a higher share than for any of the group’s other (profitable!) lending lines. I’d guess this might partly be due to a relatively large number of small loans, creating a lot of overhead dealing with borrowers and brokers.
The average remaining Vehicle Finance loan length is 37 months and the longest is 60 months, so winding this unit down will be a gradual process. But management expects to achieve £25m of cost savings by 2030, with 284 roles at risk including 78 in FY25.
Roland’s view
This decision looks sensible to me. Motor finance lending seems to have got tougher and Secure Trust’s lack of profitability in this market means it seems prudent to exit if there is no clear line of sight to an attractive level of profitability.
Secure Trust has a new CEO starting later this year who has promised to prioritise returns from the business.
With the stock still trading more than 50% below its book value, there should be some scope for a re-rating here if this goal can be achieved.
Broker forecasts suggest solid earnings growth over the next couple of years:
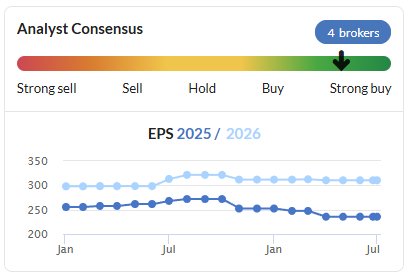
With a well-supported 4% dividend yield and big discount to tangible book, I think the risk-reward balance continues to look reasonably attractive here. While there will always be macro and regulatory risks, I’m happy to maintain our moderately positive view today. AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Jp morgan pumped 50 million pounds into this 4 days before results... tr1 rns on 10th oct showed they bought 12.7 million shares on 7th oct.
Lets see if they dump them just before or they have insider info?
Bytes Technology (LON:BYIT)
Gold Council Survey
time to sell gold then
Sell Gold
Yes if you bought at $2500
Hi
Sterling falling since PMQs and Reeves who seemed to be crying. Plus UK 30yr and 10yr Gilt yields risen
Regards
Howard
Real Estate, housebuilders and banks drop sharply this pm in response to the PMQ time. Fear about rising borrowing costs and increase taxation. Macro events take precedence to company account, at least in short term.
Tears for fears on Rachel's cheeks at PM's Questions Time today, a sorry sight.
In addition to the excellent points made by Megan, I wonder if the slow down in sales at Greggs (LON:GRG) has been in any way impacted by the significant increase in blatant shoplifting which seems to exist countrywide.
In both my recent visits to the Greggs (LON:GRG) store in Preston Lancashire I have witnessed people walk into the shop, help themselves to a couple of items then walk right out without even a cursory glance in the direction of the counter. Staff response in both these instances was to roll their eyes and shake their heads, though in fairness I'm not sure what else they could be expected to do. Hard to imagine much sales growth if this behaviour is allowed to continue unabated.
I was in Newcastle a few weekends back and one of the Greggs I passed had security guards! The design of the store in my opinion doesn't help with large open doors and everything except warm food easy to pickup and walkout with.
Thieving is everywhere, my oldest son works at Tesco part time in the village we live in which I would still class as a pretty nice place to live, but he was telling me there are now issues with people walking in and walking out with 5-10 bottles of champers. Staff can be sacked if they try to stop the thieves. One tool even turns up with an ankle bracelet on and walks out with stuff so not only thieves but generally thick also.
I am becoming increasingly annoyed by price distortions in small caps where there has been a UT (unusual for that share) which is taken as the closing price.
Today it is Elixirr International (LON:ELIX) - just FOUR shares changed hands at 720p so my holding is shown as down 2.78% whereas I consider that it is up from 690/700 at 16 30 yesterday to 690/710 now.
Having written that I now see posts here about the same thing with Bioventix (LON:BVXP) - it was 2700/2800 both yesterday and today but just FIVE shares changed hands at 3020 in the UT so shows as -8.94% today.
Ridiculous.
Hi Sharw - Ive just looked trades on LSE website and frankly its unbelievable that trades are going through for not even a handful of shares - who are these people. And it seems to occur around the mkt. Crazy.
That's odd - I bought £20k worth yesterday morning at 710p???
Bioventix (LON:BVXP) - What's the news behind the 10% fall today ?
The same news that was behind the 10% rise yesterday i.e. nothing.
Tiny trades can have an outsize impact on small illiquid companies.
Best ignored.
Thanks - Yes its been a bit of a sea-saw recently and missed the 10% up yesterday
K3 Business Technology (LON:KBT) propose to delist after making a tender offer.
Thanks for flagging this up Trident, I will add K3 Business Technology (LON:KBT) to the table.
Roland
Lots of PW lately, recurring theme seems to be unable to pass on NI costs
As a holder of Spectris (LON:SXS) it is nice to see a rival offer from KKR today with the Spectris board now unanimously withdrawing their support for the Advent offer! Over to you Advent.......
Greggs (LON:GRG) with a profit warning today, albeit a 'modestly below 2024', expect the share price to get hammered
Add Bytes Technology (LON:BYIT) to that list. Warning in the AGM statement and also likely to get hammered.
BYIT In the words of Stanley Burrell, "Hammer time".
I heard of BYIT as seeming to be quite popular amongst UK growth trusts. I never really took it myself, though, as I prefer companies to have been public for at least 7 years (to flush out all the dead rats) and its declining revenue over that time. The operating margins have improved dramatically, mind. Free cashflow has been improving nicely, too.
It seems that BYIT is rated as a growth company (PE is near 20, and the value score is 19), so any upset to the story is likely to cause a rerating, such as we've seen.
I don't hold, but folks shouldn't infer anything from that.
Struggling to pass on all the tax and ni increases or perhaps linked to the huge losses they must be suffering through shop lifting
Beautifully put. The way I see it albeit declining disposable income a factor as well
GRG And hammered it was.
I've had a few discussions with folks on Twitter and YT. GRG was mentioned.
On YT, there was a guy into UK dividend stocks. He came up with a Stocko screen of Quality > 70, TTM yield greater than 2% and less than 6%, with a market cap at least £300.
GRG comes up on that screen, along with a few others. The stuff that passes the screen actually looks pretty good from what little I've seen, and folks might want to use it for their own screening process. It seems to highlight stocks with a nice little divvie and pretty reasonable growth prospects. A good one for QARP/GARP type investors.
I don't know what rating Roland is going to give GRG (I'm going to guess Amber/Green ... did I get it right) , but I'm going to stick my neck out and say that it now presents a good buying opportunity given its modest valuation and long-term track record.
I don't own.
We're just about to post our analysis and I actually went all the way back to AMBER. Could be some value there, but from a growth perspective, I am concerned about the trajectory.
I can see why GRG is attractive for GARP type investors, I am just a little concerned that the expectation is for higher growth than what it is currently able to deliver.
GRG Thanks Megan. Yes, I thought expected future growth may weigh on it. I very much take your point. Maybe it's a bit like Domino's Pizza (LON:DOM), one can't expect infinite expansion.
But revenues were up 6.9%, LFL was up too. So far from a disaster.
According to the RNS, "The Board expects first half operating profit to be lower than H1 2024, reflecting the stronger comparative trading performance in H1 2024 and the phasing of refurbishments and cost recovery initiatives across the current year."
I'm reasonably happy with that. Directors seem pretty credible, unlike some truly atrocious behaviour we've seen on AIM stocks, for example. So then the question is: does one believe it's a hiccup, and hence a potential buying opportunity.
Interesting comments on Greggs today. I would like to put the glass half full perspective forward. Disclosure, I am a long term holder and have held the shares all the way back when they were £4.50. Its my second largest holding and I have long since got my original investment out.
When I first bought in Greggs they were blaming a very wet winter followed by a very hot summer for a hit in sales. Weather got back to "normal" and off they took. This June's weather killed the high street - I think its a genuine reason for a dip not a fabricated one. My betting is they will bounce back.
Not sure where I stand on shoplifting - I see no evidence but... I can only believe that Greggs will be on to this but that's just an opinion.
IMO a top quality brand paying a well covered 4.3% dividend (+specials). I bought back in today at £17.03.
Shoplifting is rife. I believe Greggs are refurbishing their shops to deal with this. Shoplifting and declining sales rather advertise the lack of disposable income. My suspicion is the economy is in a parlous state judged by the latest growth figures
I think since covid decency has gone out the window, thieving is the norm, police don't turn up, security guards are a deterrent but are told don't intervene.
I think since furlough loads of people no longer want to work, is it 20-25% of working age population now economically inactive and somehow all the benefits have to be paid for.
Look at the grief Starmer has got when he tried to do 1% of what is needed to try and get it all under control and somehow its all got to be held up by the zoomers the smallest generation on record.
"I think since covid decency has gone out the window, thieving is the norm, police don't turn up, security guards are a deterrent but are told don't intervene."
The role of the Police in the UK makes sense when viewed as a half hearted PR campaign rather than a crime fighting organisation. The moment you ring 111 you are aware of the subtle response trying to downplay your report to something less important, no doubt to reduce the severity of the crime in the official statistics.
Facebook gives Police the ideal opportunity to hide with lots of bland advice but little useable information to prevent real crime and there is now a whole segment of crime in the UK - shoplifting, phone theft, low level drug usage and dealing where the Police have given up completely.
When the Police do deem to turn up in person and investigate, they don't even try to hide their disinterest. Very poor.
Appreciate everyone has their own experiences but what you describe here is not the response that my wife and I had earlier this year when our house was broken into and our car stolen off the drive way. The response was immediate, arrived within 10 minutes, and followed up the next morning with forensics and neighbourhood officers.
We have had ongoing contact and updates on the investigation regularly over the last 3-4 months. All in all an extremely caring, engaged and effective response.
The vehicle was recovered 2 weeks later - sadly not in a good state. But the overall Police response was excellent.
Very pleased that you had a positive response. I still have the view that there is level of crime described in my post where the Police have largely retreated.
I would guess that in the next 12 months retail stocks will be reporting shoplifting as a major reason for declining profits - an d for some companies, it is not clear what can be done.
Greggs are redesigning their stores to tackle the issue. Not clear what Tesco B&M etc can do with a traditional supermarket open plan store.
Non food might retreat behind closed doors and the old Argos concept of catalogue collection could come back into fashion.
Whatever happens - as an investor, I would not rely on the Police to come to rescue
I remember someone high up in food retail telling me a while back they were contemplating people having to pay a deposit £25-£50 before being let into the store which would be taken off the bill at the end, hard to see how it could work for Tesco/Sainsbury etc.
Or move to a membership style like Costco, where you have to swipe your membership card upon entry (which is linked to a real ID like driver's license, etc in their systems).
Greggs (LON:GRG)
well said Beksbee - i remember 20 years ago when my local Greggs wentgto new formsat and they removed old stuff - my mate a greggs connoisseur thought those changes would make them a busted flush. The reality is they do their stuff well and should always have a place.
My slight worry here compared to 20 years ago is that - they now have more uk saturation and we have to admit that many town centres and not what they were - and higher costs are not going to go away so they will be living on the edge ref thgose that have modest funds. so future growth in uk wil not be as easy as it has ben the last 20 years.
Overall though they have lasted the test of time and if we are not buying in at peak ratings or when we are at peak profits i think its still a decent long term hold.
My main surprise with greggs is that they havent as of yet ventured outside of the uk successfully - there is huge untapped potential there. Ok logistics of getting uk based fare overseas probably makes it super hard at scale - but i would have thought they could deliver core popular items with perhaps a local slant - perhaps in that regard francise route? not sure if they have done many trials.
whilst earning expectations are on the downward spiral and the shareprice too - i am more than happy to sit on sidelines - but if they have no further banana skins and p/e is close to 12-14 * rating i think its a nice little long term add. I have previously held greggs twice sold both times at a profit - paid more second time to buy back in and price now is no lower than when i sold - so i would probably have been better off just holding forever - my main mistake here was selling out too early on the way up - perhaps that excess valuation did get a bit frothy though.
June weather may have been exceptional in the South where Greggs (LON:GRG) has less presence but in the North and Scotland - where I am and where Greggs is more concentrated - it's been quite nice but hardly exceptional. So I'm not buying this weather excuse. Like Megan I am a holder and stuck on the fence today; there may be research to contrary but I will probably stick with Charlie Munger's advice today: "the big money is not in the buying and the selling, but in the waiting."
For all these companies that blame the weather for drops in sales, I'd love to see what data they base that on. Do they have actual market research that shows that, or do they just look for some random events to explain slowdowns?
Greggs (LON:GRG) - I reluctantly sold a couple of months ago concerned about the push to open more and more outlets . Interestingly GRG is on Megan's list but I'm yet to be convinced to buy back in.
10 + years ago my local Greggs had a constant queue of bodies buying in-shop-made pies, loaves and doughnuts. Now everyone goes to Lidl which is half Greggs prices, and the Greggs pie "cafe" is mostly empty.
Greggs (LON:GRG) is looking increasingly like a value trap.
I have held on to it too long in the hope that, like one of its pastry slices, it would rise again.
Much of what they offer would be considered park ready picnic friendly finger food - sandwiches, scotch eggs, salad boxes. https://www.greggs.com/news/yo...
As said elsewhere, this looks like a case of over-egging their progress and delivering it to the market too early, resulting in an unpleasant taste as forecasts sink and we worry about a soggy bottom.
“I have held on to it too long in the hope that, like one of its pastry slices, it would rise again.”…made me smile!
I sometimes wonder if the simplest screens are the best screens. The naked trader is a big advocate of the quality rank.
Some academic wrote about "Buffett's Alpha" . "Berkshire’s returns can thus largely be explained by the use of leverage combined with a focus on cheap, safe, quality stocks."
https://quantopolis.com/wp-con...
And here's the thing, it doesn't take an investing genius to do well out of the stock market. I won't come even close to a guy like Paul Scott or Richard Crow, but I think I should do pretty OK using a common sense approach like looking for quality companies at reasonable prices.
I've just run it. A really helpful screen. All my target companies are on there which reinforces my view that dividend payments and quality amount to the same thing. I'd question why a 300m size threshold has been set but the results are compelling.
dividend payments and quality amount to the same thing....
... up to a point I think. I served on the investment committee for the company pension fund in the early 00s. The owner played a pretty strong controlling hand. kept us in cash when i wouldnt have and then bought companies that yielded 1-3% as that 'indicated financial stability but did not require gutting the company to pay the dividend' . The performance over 5 years was excellent.
So much common sense in this post. I read a great book by Charles Carlson 'Little book of dividend investing' where he cited the dividend payout ratio as the most important component in selecting a company. Anything over 60% questionable. The payout-ratio the most important tool in highlighting sustainable dividends. He would link something like the stock rank. Geraldine Weiss has a similar view. Sustainable dividend investing is the concept in reality. Total return potential.
For those interested I ran the screen adding the stipulation that earnings per share doubled over 10 years and had high interest cover.
Here are the results (first 10): IG group (LON:IGG) , ME International (LON:MEGP) , M P Evans (LON:MPE) , Kainos (LON:KNOS) , 4imprint (LON:FOUR) , Games Workshop (LON:GAW) , Morgan Sindall (LON:MGNS) , Hill & Smith (LON:HILS) , Rotork (LON:ROR) , Clarkson (LON:CKN)
They look pretty solid companies. (AEP also qualified in the top 10, but it was too similar to MPE so I excluded it).
Hi team. Any chance you could look at one the lowest Stockranked junk stocks, and most ramped share ever, Avacta (LON:AVCT) ?
What's the point? They seem to be stuck doing phase 1 trials with revenue (assuming it get through later trials) as remote as ever. I hold - not much more than loose change now.
Probably right! Proper AIM junk stock
AVCT Ok, I'll bite ... brings up Stockopedia Report ... sweet Republican Jesus.
Where to start on this one? Scores for Quality of 1, likewise for Value, Momentum and Rank.
Hasn't made a profit in at least 5 years. Share count keeps ballooning. The "Bankruptcy Risk" rating has an arrow pointing at the extreme distress position.
And get this, it has been public since 2003 with nothing to show for it. Market cap of £119m with trailing revenues of £0.1m. Why, just why, would anyone consider this investable?
Verdict: what a terrible day to be able to read.
That did make chuckle, Mark
Thanks. I like to twist the knife on things that ire me. My preference is for jagged blades.
Hi Roland, I notice that Water Intelligence (LON:WATR) issued results very late on Monday. I assume this slipped through the net because of this. I don't hold but thought I'd mention it.
It was publication of audited accounts to 31/12.
From an outlook perspective, already superseded by a Q1 trading statement in May.
OK, thanks MC
If you or the team have time Roland any observation about Mercia's results yesterday would be appreciated. We hold and I'm wondering whether to add to a decent sized holding, it's easy to get too optimistic when difficult periods seem to be easing.
Asset managers
All asset managers shares have gone up significantly.
PMI , I hold, is up 55% over the last three months.
Graham has been positive on all asset management companies. Even LIO is showing signs of life.
JASVFS, the recording of Mercia's yesterday InvestorMeet presentation might be available soon , I found the question and answer at the end of interest. I hold.