Daily Stock Market Report (Wed 22 Jan 2025) - STB, BKS, EZJ, JDW, HEAD, LBG, KOO

Good morning! What are the chances of another day without any profit warnings, mishaps, or unwanted surprises?
Update at 7.30am: it looks like we have possibly started a streak of days without any profit warnings!
1pm: thanks for dropping by, see you tomorrow!
Spreadsheet accompanying this report (updated to 17/1/2025)
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Intermediate Capital (LON:ICG) (£6.2bn) | TU | $22bn raised in 12 months, 2x 2023. Fee-earning AUM +2.8% QoQ to $71bn. | |
easyJet (LON:EZJ) (£3.9bn) | TU | Q1 LBT of £61m, improved vs LY. ASK capacity +11% YoY. Holiday profit +39%. FY25 outlook in line. | AMBER/GREEN (Roland) |
Quilter (LON:QLT) (£2.2bn) | TU | Core net inflows £2bn in Q4, £5.2bn for the year. | |
J D Wetherspoon (LON:JDW) (£747m) | TU | H1 LfL sales +5.1%. LfL sales for main Christmas period +6.1%. Labour-related costs to rise £60m. | AMBER (Graham) Downgrading this as I'm not sure it has enough of a profit margin (after interest costs) to absorb higher NICs from April. |
LBG Media (LON:LBG) (£261m) | Full-year Results | Ahead of exps for 2024 and positive Q1 for FY Sep 2025 gives confidence for new financial year. | AMBER (Graham) US expansion provides a growth opportunity. Perhaps it's fairly valued at current levels. |
Enquest (LON:ENQ) (£246m) | Acquisition of Harbour Energy Vietnam business | $84m. 53% interest in 2 production fields. Fast payback, low capex, reduced carbon intensity. | |
Beeks Financial Cloud (LON:BKS) (£177m) | Exchange Cloud now live with Nasdaq | Agreement enables Nasdaq to offer cloud infrastructure and analytics. Underpins FY25 exps. | AMBER/GREEN (Roland) |
| Secure Trust Bank (LON:STB) (£88m) | Media: Reeves bids to intervene to cut lenders’ £30bn bill | Treasury applies to Supreme Court to prevent economic harm from excessive compensation. | AMBER/GREEN (Graham) A proportionate outcome to legal situation is now more likely. |
Headlam (LON:HEAD) (£112m) | TU | Rev -9.7% to £593m. Adj. pre-tax loss c. £34m. Cash £11m and remaining properties worth £95m. | AMBER (Roland) |
Colefax (LON:CFX) (£46m) | Half-year Results | H1 sales+1.8%. PBT -0.5% to £4.4m. Strong in US, challenging in UK/Europe. Cash £18.6m. | |
Transense Technologies (LON:TRT) (£24m) | TU | FY25 in line. H1 revenue +37% at £2.4m, but net earnings exp c.20% below prior H1, due to hiring. | |
Itaconix (LON:ITX) (£21m) | TU | 2024 results to be in line with expectations. Rev $6.5m, GP margin +4% to c.35%. | |
Cordel (LON:CRDL) (£17m) | Half-year Results | Revenue +16% to £2.3m, EBITDA loss reduced to £159k. No. clients +3 to 11 during half year. |
Graham's Section
Secure Trust Bank (LON:STB)
Up 33% yesterday to 462p (£88m) - Close Brothers, Lloyds Banking, Secure Trust jump on UK bid to protect car-loan providers - Graham - AMBER/GREEN
I’ve chosen STB to be the main stock mentioned here, as it had the most extreme reaction to yesterday’s news (up 33%).
We also had Close Brothers (LON:CBG) up 22% and S&U (LON:SUS) up 15%. At the bigger end of the spectrum, Lloyds Banking (LON:LLOY) was up 4%.
The case in question is not just about discretionary commission arrangements for car loans, but about the presence of commissions arrangements in the first place, where the active consent of the customer has not been obtained.
The Court of Appeal ruled on this in November, and the case is now progressing further to the Supreme Court.
The Court of Appeal ruled that a car dealer, when acting as a broker, had a fiduciary duty to their customer, and this implied the requirement that it needed the fully-informed consent of a customer to the payment of a commission for arranging a loan.
I’m not a lawyer, but I’ve always understood that a fiduciary duty - the obligation to put someone else’s interests ahead of your own - is something that falls on a doctor or a lawyer, someone who is entrusted with a great responsibility for the welfare of another person. Or in the financial sphere, a fiduciary responsibility often arises when someone is entrusted with the financial wellbeing of others, for example when they are investing other people’s money on their behalf.
However, I’ve never ever thought that a car dealer had a fiduciary responsibility. If a car dealer has a fiduciary responsibility, then I think almost anyone you do business with has a fiduciary responsibility. But that’s where we are, apparently.
Rachel Reeves and the Treasury are trying to stop another PPI-style disaster for the financial industry:
…the Treasury submitted an application to the court arguing it should be able to contribute evidence in a case that could “cause considerable economic harm” and make car loans harder to get and more expensive.
The Treasury submission on Monday added that the case might “generate a perception that regulation in the UK is uncertain”. The letter, first reported by the Financial Times, also warned judges that “any remedy should be proportionate to the loss actually suffered by the consumer and avoid conferring a windfall”.
Not everyone is happy with this intervention. Law firms such as Slater & Gordon (you may remember them as the purchasers of Quindell) can make a fortune from these compensation cases:
Elizabeth Comley, chief operating officer of the law firm Slater and Gordon, said her firm represents “tens of thousands of individuals who have been unfairly impacted” by car finance sellers’ practices.
She said: “While we recognise the importance of maintaining confidence in British lenders, this cannot come at the expense of justice for the individuals affected.
Consumers deserve accountability and redress when they have been wronged, and Rachel Reeves’ attempts to shield lenders from the consequences of their actions risk undermining public trust in the financial sector as a whole.”
Graham’s view
I was GREEN on STB at much higher levels (836p), while Paul was RED after legal issues arose in Nov 2024 (see here).
The difficulty is that STB was (and I still think is) extremely cheap, but the risks are difficult to quantify.
I’m going to moderate my view to AMBER/GREEN: it remains amazingly cheap, but for a reason. If it turns out that consumers can only claim compensation for harm actually caused - at worst, this might be a slightly higher cost of finance than they would have agreed to - then I don’t think there is much to worry about. That outcome is more likely now than it was yesterday, but I can’t predict what might happen.
J D Wetherspoon (LON:JDW)
Down 1.5% to 602.4p (£738m) - Trading Update - Graham - AMBER
This is a brief H1 update, the main purpose of which is to have a pop at people who prefer dinner parties to pubs.
On the financials:
25 weeks to mid-January: LfL sales up 5.1%, led by slot/fruit machines up 11.7%.
Total sales up 4%, lower than LfL sales as there have been a few disposals.
LfL Christmas sales up 6.1%.
Debt is expected to finish the current financial year (FY July 2025) between £680-700m, slightly up on the £660m at which it finished FY July 2024.
Property: nine pubs to open this year. The estate currently consists of 796 pubs.
Outlook: it’s another funny outlook statement from Tim Martin, but with a political point, calling on the government to end the VAT discrimination against pub-goers and in favour of people who like to have dinner parties in their homes (supermarkets pay no VAT on food, while pubs pay 20%).
The other main point is that labour-related costs will increase by c. £60m annually (from April when the new tax changes kick in), and Tim Martin argues that this is another instance where supermarkets have an unfair advantage over pubs, as supermarkets are less impacted by government-mandated wage increases.
Graham’s view
Given that JDW only earned £74m of adjusted PBT last year (FY July 2024), under the old national insurance regime, I’m very concerned as to how it’s going to mitigate £60m of additional wage costs. Even if it fully mitigated 50% of the increased costs, that could still potentially cut down profits by about half.
If it was debt-free, it could have absorbed these costs into its c. £140m of operating profit.
But after paying its hefty interest bill, it doesn’t seem to have a lot of wiggle room to pay extra costs.
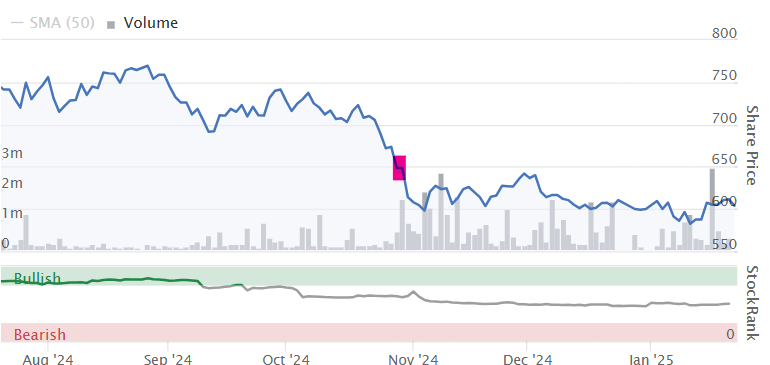
The shares have de-rated since around the time of the official announcement of the upcoming changes (marked blow in pink), but only by around 15%, not by an amount that suggests great alarm:
Tim Martin isn’t promising much, only saying:
"The company is confident of a reasonable outcome for the year, although forecasting is more difficult, given the extent of the increased costs."
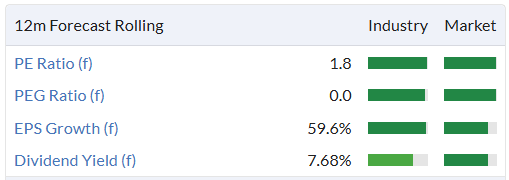
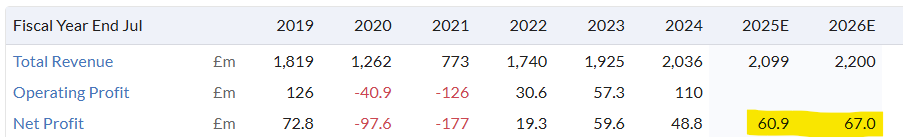
Consensus forecasts suggest that the company can earn after-tax profits of about £60m in the current year (FY July 2025), but this only includes four months of higher NICs. What about the financial year after that, which begins in a little over six months? Forecasts suggest that earnings will increase pleasantly that year, despite it being the first full 12 months during which the company must face these higher wage-related costs.
I’m worried that the FY July 2026 could be a poor one, and that JDW might have taken on a little too much leverage given the deterioration in trading it could be about to suffer. I’m going to downgrade this to AMBER, as I’m concerned that current forecasts may need to be revised quite a bit lower.
LBG Media (LON:LBG)
Unch. at 125p (£261m) - Full Year Results - Graham - AMBER
LBG Media, the global digital entertainment business with a focus on young adults, is pleased to announce its results for the nine months ended 30 September 2024 ("FY24" or "the period"). Following the change in year-end, statutory financial results are being reported for the nine months ended 30 September 2024.
It’s a little confusing straight away, as the company reports results for nine months but then immediately tells us that its performance is ahead of market expectations “for the calendar year to December 2024”.
These expectations, for what its worth, are revenues of £86.3m and adj. EBITDA of £23.4m.
None of these time periods given are entirely satisfactory:
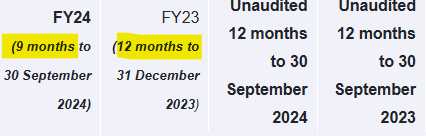
FY24 (9 months) can’t be directly compared to FY23 (12 months), and the unaudited 12-month periods to September don’t include the three most recent months.
For now, I’ll use the unaudited 12-month periods to September. The headlines are that revenue rose 22% to £86m and that PBT rose 32% to £14.5m.
LBG owns Unilad, Lad Bible, Sport Bible, etc. It claims to be “one of the largest publishing groups in the world”.
It makes nearly as much money from “Direct” sources as “Indirect” sources, meaning revenue that is shared with a social media platform such as Facebook.
It is one of Facebook’s largest publishers, which unfortunately I would view as a risk as sites such as Facebook can change their policies and algorithms on a whim.
This happened during 2024, but LBG seems to have survived it ok:
From July to September 2024, changes to Facebook's commercial model resulted in lower Indirect revenues from Social compared to the same period in the prior year. As with previous platform changes, we were able to adapt quickly and saw a return to normalised levels on exiting Q1 FY25, providing positive momentum for the remainder of the new year ahead
Outlook:
The Group has entered FY25 with good momentum across its three growth lenses of Direct, Indirect, and U.S. expansion. The Board remains confident in the size of the opportunity ahead and may consider further investment to accelerate the U.S. growth strategy.
Building on a robust first quarter that achieved double-digit growth compared to the same period last year, management is confident in the growth trajectory for the remainder of FY25 and expects revenue to increase by approximately 10%.
CEO comment:
"2024 was a transformational year for LBG Media. We are running more campaigns for more blue-chip brands, particularly in the U.S., the largest advertising market in the world…
More than half a billion people globally, including Gen Z and Millennials, see us as the go-to destination for digital content. The biggest brands and the biggest celebrities therefore want to partner with us to access the growing buying power and influence of this hard-to-reach demographic…
Estimates: Zeus have updated their forecasts to reflect the change in the accounting year-end.
They see current year (FY Sep 25) revenues of £94m, rising to £104m for FY Sep 2026.
Over these two years, adj. PBT is forecast to rise from £21.6m to £23.1m.
They calculate that that stock is trading at a PER of 15x for FY26.
Graham’s view
I’m too old now but even when I was younger, I never saw the appeal of LADbible or Unilad.
But I should put that bias to one side and look at the facts and figures.
The brands that LBG works with are undeniably blue-chip and of the highest quality: Google, Lloyds, and Costa Coffee are mentioned as examples where LBG has built “deeper, more strategic partnerships”. LBG says it has become “an integral part of corporate marketing strategies”.
The cash position is fine at £27m, with no debts, even after £20m was spent on an acquisition to boost US-led growth.
Balance sheet equity is about £36m after you deduct intangibles - not enough to support its market cap but it’s nice to see that the company has a positive position.
Overall, perhaps I’m biased by my (generally negative) attitude towards its main titles, but I can’t bring myself to give this a positive stance, even though I admit that there is nothing obviously wrong with these results or with the outlook.
Quality metrics are good:
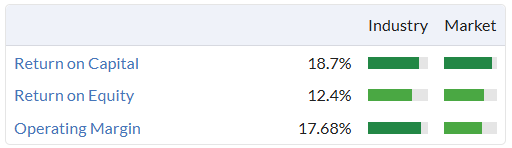
The valuation arguably reflects this:
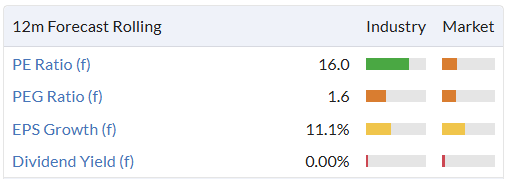
Where the investment case falls down for me personally is that I don’t have any conviction that LADbible/Unilad will be relevant long-term. But again that may just be a reflection of my personal bias.
What is more objective is the risk faced by publishers that the likes of Facebook will change their algorithms or payout calculations. That risk is always, always there, and I do think it should affect how investors think about the publishers who rely on these platforms.
I’m happy to put this at AMBER, but I can see that someone else might give it something better.
Roland's Section
Beeks Financial Cloud (LON:BKS)
Up 9% to 287p (£193m) - Beeks’ Exchange Cloud now live with Nasdaq - Roland - AMBER/GREEN
Beeks Financial Cloud provides cloud computing and connectivity for financial markets. Today’s update confirms the identity of a major new client as exchange operator Nasdaq.
[Beeks] … is delighted to confirm that the major Exchange Cloud Customer announced on 6 February 2024 is the Nasdaq Stock Market (Nasdaq), a global technology company serving capital markets and other industries. The service is now live, with customers expected to be on-boarded at the end of February.
This news has been well received, sending the stock up 8%, but it does appear to have been an open secret due. I’ve seen it commented on previously (including here), but it’s good to have confirmation.
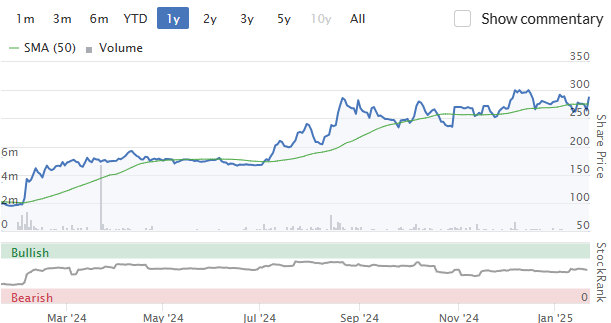
Beeks says that its Exchange Cloud service will initially be deployed in Nasdaq’s core data centre in New Jersey, “with the potential for further expansion”. The agreement enables Nasdaq to offer Beeks’ services to its customers, but does not appear to guarantee a specific level of demand.
Guidance unchanged: this deal appears to have the potential to make a significant contribution over time. But it looks like the impact on FY25 earnings (y/e 30 June) will be modest, merely supporting existing guidance (my bold):
Consequently, this material multi-year contract has scope to grow, further supporting the Group's growth aspirations, as well as underpinning the Board's FY25 expectations.
Estimates: with thanks to broker Canaccord Genuity, we can see that earnings forecasts are unchanged today:
FY25: 7.7p per share (+21% vs FY24)
FY26: 9.5p per share (+23% vs FY25)
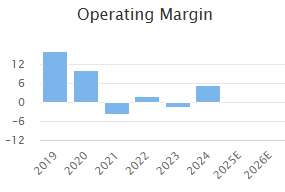
Canaccord also says it expects to see c.40% revenue growth and a c.1.8% improvement in operating margins for FY25. Operating margins have deteriorated as the group has expanded, so I think this would be welcome news:
Roland’s view
Nasdaq is clearly a valuable reference customer and is presumably endorsing the value of Beeks’ services to its exchange members. The acid test will be how strong takeup is over the next 12 months or so.
I do not know all that much about Beeks’ services, but I assume that Nasdaq exchange members currently use alternative low-latency colocation services to meet their needs. So the test will be whether Beeks can demonstrate sufficient benefits to justify members switching to a new provider.
Revenue has grown at an average 31.5% CAGR since 2019 – an impressive record that suggests to me the company could have some competitive advantages:
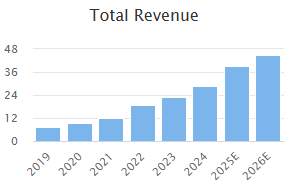
However, this revenue growth has not yet really translated into improved profitability. Last year’s results (covered here) showed an operating margin of just 5.5%, with a sub-4% return on capital employed.
My understanding of Beeks’ business model is that it requires fairly heavy upfront capital expenditure to set up the necessary infrastructure in client data centres. This should then be followed by years of sticky, recurring revenues. At least, that’s the bullish investment case.
The StockReport shows Beeks generating positive free cash flow last year for the first time (since at least 2019):
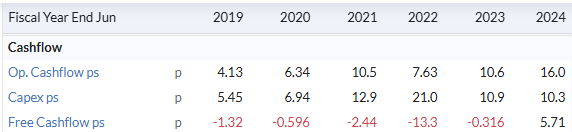
One concern for me might be the possibility that equipment renewal costs will be high and fairly frequent – last year’s accounts showed a £5m depreciation charge, for example.
I can see the bull case here, but it’s probably fair to say that a certain level of optimism is already priced into the stock at >30x forecast adjusted earnings (Beeks is quite a heavy adjuster):
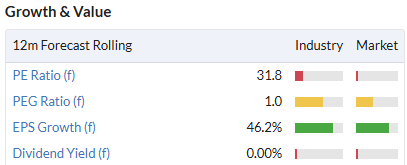
The shares are up 150% over the last year. The rolling PEG ratio of 1.0x above suggests to me the stock may be reaching a point where it’s fairly priced for expected growth.
I’m impressed by long-term revenue growth here and encouraged by the presence of founder management – CEO Gordon McArthur has a 31.9% holding. I’m going to take a cautiously optimistic view ahead of March’s interim results. AMBER/GREEN.
easyJet (LON:EZJ)
Down 5% to 485p (£3.7bn) - Q1 Trading Update - Roland - AMBER/GREEN
Today’s trading update covers the three months to 31 December 2024. That’s traditionally a quiet period for leisure travel. This is reflected in easyJet reporting a loss for the quarter, as is usual for this business.
The market seems a little disappointed by today’s statement. But it doesn’t read too badly to me and appears consistent with the guidance provided in November’s results, which Keelan covered here.
Q1 highlights: easyJet reports a headline pre-tax loss of £61m for the quarter, but this is less than half the £126m figure for the same period last year. Improved operating metrics supported a stronger Q1 performance:
Passenger numbers +7% to 21.2m
ASK* capacity +11%, avg sector length +6%
Load factor: 88% (Q1 24: 86%)
Total cost per ASK down 4%, due to 13% reduction in fuel costs
Revenue per ASK flat, as guided previously
*Available Seat Kilometre - an industry capacity metric
easyJet Holidays generated a £43m profit in Q1, an increase of £12m (+39%) from Q1 last year.
H1 guidance: it looks like H1 results will be negatively affected by the later timing of Easter this year, which means it will fall into H2. The company expects this to cause a £30m hit to profits.
Last year’s release of “aged balances” will also cause a £34m negative comparative versus last year.
However, the company also says that underlying unit revenue in Q2 will be “modestly lower” than in Q1 due to an increase in longer leisure routes. These newer routes are expected to perform better next winter as they mature.
Fuel costs are expected to continue falling in Q2.
FY25 Outlook: guidance is unchanged, with FY25 ASK growth expected to be c.8%.
The traditionally busy Easter period is seeing strong demand and bookings continue to build for Summer 2025. At this early stage of the year, the current booking trends are supportive of FY25 consensus
The company also helpfully provides an internally-compiled consensus estimate for FY25 headline PBT of £709m (FY24: £610m).
easyJet Holidays is expected to report customer growth of c.25% in FY25, although the company doesn’t translate this into expected profit growth.
Profits from the airline’s newish package holiday business rose by 56% to £190m last year, but extrapolating the 39% rate of growth in Q1 suggests the increase might be lower this year.
Slower growth rates are natural as a business scales. I think the holidays business is a valuable, margin-enhancing addition to easyJet’s offering. Presumably the airline saw the success of Jet2’s model and decided that it would quite like to replicate it!
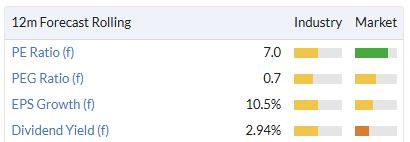
Consensus forecasts on Stockopedia suggest adjusted earnings could rise by 16% to 71.3p per share this year, pricing easyJet on a P/E of 7.
Roland’s view
easyJet says it remains focused on its medium-term target of generating a headline pre-tax profit of £1bn.
Today’s update suggests to me that the business is performing largely as expected and is likely to make progress towards this target in 2024/25.
As we’ve seen with some other airlines, easyJet has been able to repair its balance sheet more quickly than expected following the pandemic. Last year’s results showed a net cash position for the second consecutive year.
This isn’t a sector that attracts high valuations, but easyJet’s share price does not look unreasonable to me.
Looked at differently, the stock is currently trading at 1.3x its book value and reported a 15% return on equity last year. Buying the shares at this level would imply a return on cost of equity of 11.5%, which seems satisfactory to me, if not outstandingly good value.
Airlines are traditionally a difficult investment, with high fixed costs and plenty of macro risk. But I’m broadly positive here. AMBER/GREEN.
Headlam (LON:HEAD)
Down 1% to 138p (£112m) - Y/E Trading Update - Roland - AMBER
We’ve commented on this struggling flooring distributor several times recently. It’s been selling some of its large freehold property portfolio to release cash and shore up its loss-making operations.
Today’s year-end update confirms the year-end trading position and cash position after recent property sales.
2024 group revenue down 9.7% to £593m
H2 revenue down 7.4%, improved versus H1 decline of 11.8%
Expected 2024 underlying pre-tax loss of c.£34m
Growth in the Larger Customers and Trade Counters divisions is being offset by weak trading in Regional Distribution.
However, Headlam’s strong balance sheet has proved its worth with property sales generating £54m in December (see here).
These transactions left Headlam with net cash of £11m and a property portfolio valued at £95m at the year end. Those items alone are nearly sufficient to cover the £112m market cap, even without the ongoing value of Headlam’s business and inventories.
Updated estimates: with thanks to broker Panmure Liberum, we have updated earnings estimates for Headlam today.
Unfortunately today’s update appears to have been slightly below Panmure’s previous expectations, so earnings estimates for 2024-2026 have all been cut:
FY24e: loss of 42.4p per share (previously 41.1p)
FY25e: loss of 29.3p per share (previously 26.0p)
FY26e: breakeven (previously earnings of 3.1p per share)
Roland’s view
I don’t think today’s downgrade is too significant. In reality, I think the exact pace of Headlam’s recovery will be dictated as much by external conditions as company actions.
In the meantime, Headlam shares continue to trade at a hefty discount to book value, underlining the value appeal of this stock which Mark discussed here.
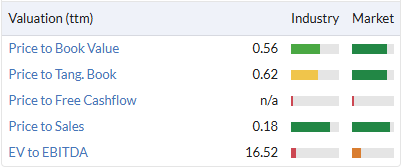
I think this provides us with a useful reminder of the value of a strong balance sheet. Headlam seems near-certain to survive long enough for its trading to recover. That might not have been true if it had entered the current slump with too much leverage and a wholly-leased property estate.
The distant timing of a recovery prevents me from taking a positive view, but I’m comfortable remaining neutral. AMBER
Kooth (LON:KOO)
Down 2% to 170p - Trading Update - Mark - AMBER
Revenue is in line, showing some phenomenal growth rates here:
2024 revenues are anticipated to be in line with consensus market expectations of £65.8m (2023: £33.3m).
EBITDA growth is even better, and beats expectations:
Adjusted EBITDA is expected to be at or ahead of the top of the range of analyst forecasts of £12.7m (2023: £2.3m), helped by certain items which are not expected to recur in the current year.
However, it's this last line, which shows that the beat is likely a one-off, which is why the shares are actually down today in response.
I’m not sure I trust the broker consensus here, so doing some simple maths, at the half year, they said:
● Adjusted EBITDA to £7.8m (2023: £0.0m)
● Profit after tax of £3.9m (2023: £0.5m loss)
This gives H2 EBITDA of £4.9m. D&A in H1 was £2.6m, giving PBT of £2.3m and £1.7m PAT on a standard tax charge. That’s £5.6m PAT for the FY or 15.4p EPS. The P/E of 11, then, is potentially not that expensive for a company with their growth track record.
The problem is that their product, which is a mental health platform for teens, has faced some significant pushback in the US. The perceived issue is that parents do not have sight of the support given. My own view is that without something in place, there will be an increasing crisis in teen mental health, and the benefits outweigh the risks in this regard. However, logic rarely wins out in such emotive issues. The good news is that they keep winning pilot projects, although these won’t move the needle unless they become more than a pilot:
As announced in December 2024, Kooth has agreed terms for a new pilot contract with the State of New Jersey valued at $1.45m. Under the terms of the Contract, Kooth is providing mental health support via its Soluna platform to school districts within New Jersey, reaching 50,000 students aged 13 to 18. This pilot went live on 7 January. The Company continues to hold negotiations, which are expected to be concluded in Q1, regarding a second pilot contract in the US.
Mark’s view
This is a potentially interesting growth company, having a positive social impact and on a relatively modest valuation if my maths is correct. The problem is that the political risk in their key market of the US is almost impossible to quantify or mitigate. So it's an AMBER for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Morning Yiannos. Interested to see your Twitter account if you are willing. @ryvetsprog is my X name DD
There are a lot of companies reporting, at the moment, but only 6 each day this week, have been covered, therefore many companies are being missed. Would it not be possible, to do more short reviews, on some of these?
VP (LON:VP.)
Interesting development in that Jeremy Pilkington , Chairman has bought over 200,000 shares in the last week at an average of around 565p.. That is well in excess of £1 million.
Probably meaningless given that he holds directly or otherwise over 50% of the equity. However £1 million is a bit more than lose change even for someone as wealthy as him. I have a modest holding.
RE: VP
Thank you for flagging this up
As a rough calculation this takes him over the 50% holding? Slightly unexpected as it was often speculated that due to his age he might retire shortly and want to reduce his holding
He had wanted to sell out in 2022 didn't he?
So this is a very interesting development at VP (LON:VP.)
He hasn't bought in the years since, so the timing is interesting.
Hi Roland - I think you are missing the point on Beeks Financial Cloud (LON:BKS) - If you want to value it on a value share type basis then sure it is fully priced, but it simply isn't a low growth value share. It is expected to compound aggressively over the next few years and is building what looks to be quite a moat advantage, not locally to the UK but globally. It is close to landing several other exchanges and each of these add £10m p/a of revenues.
If you look at previous market transactions (eg NEX sold to CME) you will see that the type of businesses selling to sticky financial service institutions/exchanges sell for 1y fwd PERs of 40* or PEGs of 1.5+ or 15* EBITDA (that would put Beeks Financial Cloud (LON:BKS) on quite a significant discount to fair market value of 25%+ even before the revenues from Nasdaq, rather than being up with events which you suggest). Put simply it is just too cheap in my view. As usual the UK market doesn't actually recognise a global leader even when it is slapped in the face with one!!
That doesn't mean it will get taken out any time soon - whilst I am sure there are plenty of buyers out there the CEO has his own target in mind that appears to be considerably north of this price and he controls enough that it's probably not getting taken unless he wants it to.
You mention life of asset and depreciation. From memory they depreciate the assets over 4 or 5 years but have actually found that this is way too conservative and asset life is more like 8-10 years so I think you're likely to find the value of those assets is marked at a considerable discount in the accounts. I don't think they've changed policy (that I noticed anyway). Of course that essentially means future profits will be higher.
Beeks Financial Cloud (LON:BKS) interested to understand how a state of the art low latency connectivity business model squares with an 8 year hardware lifespan David…that seems the opposite to what is occurring in the rest of the tech sector…I’m no expert but that looks illogical
it was in one of their video presentations rhomboid a couple of years back I think but I don't remember which one I'm sorry. It was in relation to questions around capex, cashflow and depreciation. I only remember them discussing that they had found the hardware had a much longer lifespan than they had depreciated. Be interesting to see if that has changed at the next set of results.
I have the impression that the yearly share options charge of approximately £2.5m for generating nothing is equally a major concern and a bright red flag. If you take the rule of 10% then the FCF amount should be equivalent to £25m!
Not in a million years.
I know the ending.
All the best
there are just 6m share options in issue (less than 10% if fully vested). Those options only vest under fairly challenging profitability and are not zero cost but issued at the price - so mostly above £1 ranging £1-£1.60
They are generally not paid to directors but senior employees in the majority.
The share based payment charge of £2.3m is a function of black scholes option modelling which of course looks at how far in the money the call option is and given the large share price rise that is what is generating the payment charge.
If you look at net issuance c. 500k or less than 1% in the last year. not unreasonable, hardly dilutive.
I personally view J D Wetherspoon (LON:JDW) as a long term hold.
One way for JDW to mitigate the increased NI costs and Minimum Wage would be to pass on some of these additional costs to customers and I suspect they will still be cheaper than a lot of other pubs if they did so.
I also think that Tim Martin has a good point when he complains about the VAT charges on pub food being unfair. When people purchase meals in pubs (and restaurants) they generally buy drinks; and they will quite often have travelled by bus, train , tube or taxi to arrive at their destination. All of this contributes to the economy and increases GDP. This suggests to me that the VAT treatment should at least be equal. I think the Government should focus more rationally on these issues and think about the impact of VAT on the country's economy generally.
The general reduction of pubs in the UK is considerable as is the reduction in opening hours of some of them. In my view I think JDW will succeed on a survivorship basis.
Has the bottom been reached at Liontrust Asset Management (LON:LIO) ? CFO and CEO + Mrs CEO buying a decent chunk:
Liontrust announces that on 22 January 2025 it was notified that Vinay Abrol, Chief Financial Officer, purchased 25,000 ordinary shares of 1p each in the Company ("Shares"). Vinay Abrol is a PDMR.
Liontrust announces that on 22 January 2025 it was notified that John Ions, Chief Executive Officer, purchased 37,500 ordinary shares of 1p each in the Company ("Shares") and his wife, Paige Ions, purchased 12,500 Shares. John Ions is a PDMR and Paige Ions is a PCA to Mr Ions.
J D Wetherspoon (LON:JDW) - Hi Graham - I can understand concern for the future profitability here but on the positive side - (and I am a biased holder) Tim has been cleverly adding profitable locations and closing less profitable ones. He has a major following - the pubs are always busy and cheaper than elsewhere so may well weather the storm of increased costs better than others. Despite the infamous cost of living crisis - people are still spending - but trading down and thats where JDW scores
Herald Investment Trust (LON:HRI) Shareholders voted against SABA and supported current board and strategy. 65% in favour of status quo. More views here https://www.stockopedia.com/co...
My thoughts are that this clearly supports the view that Katie Potts and team are one of the few outfits dedicated to small caps (not just UK listed) - especially of a tech bent - which have generally been poor for the last year or so but which have a briliant l-t record. But it also leaves me wondering whether ITs really have a future. They have typically been at fairly deep discounts to NAV over the past couple of years and in the case of Herald, like it or not, the discount has dramatically narrowed since the intervention of Saba. I noticed the 'agreement' between Saba and the Blackrock stable of ITs this morning and am hoping for some sort of rationale beyond knowing that Saba is a microminnow set against the might of Blackrock. But do closed-end funds like our British ITs actually have a future?
All I can say is if you buy a trust on a discount and it remains on the same discount you have not lost out. The discount is a function of the market, what is important is the underlying NAV performance, and a wide discount, if out of the norm provides an opportunity.
Many companies, especially Property ones trade below their Asset value- should they all be wound up ?
Gearing, in my opinion, gives a closed end fund a huge advantage over open ended funds "unit trusts". Plus no issue with redemptions. Trusts have been around since they started off funding railways in the US , projects in South America in the 19th Century and I am sure they will be around a lot longer.
Thanks for the daily report and the summary table remains very helpful.
On the topic of profit warnings, I did spot one from Revel Collective (LON:TRC) which was formally Revolution Bars staying true to form which a warning today. Share price down c31% at time of posting.
Good to know that "We currently have headroom on our banking facilities", with the operative word being "currently"!
Since floating think profits warning or rights issue or insolvency have been at least a yearly occurrence!! They report ebitda of £2 - £4m they then say they have £14m of debt to pay and that this years profit will be impacted by £4m due to the budget impact….. these figures don’t add up
Revel Collective (LON:TRC) That is under £10m mcap. I wondered what had happened to Revolution Bars, thought they had gone bankrupt or dislisted.
They changed the name after the last rights issue (late last year) as a new beginning…….then went straight back to the usual performance…….
Wonders will never cease, Centaur Media (LON:CAU) has actually put out a positive trading update at noon today! This is the first I have seen from them in a very long time and a pleasant change from the usual downgrades. Maybe the shares might actually make some progress from here - I certainly hope so (I hold).
Centaur Media (LON:CAU) Why at noon, did they not do this before?
However, I’ve never ever thought that a car dealer had a fiduciary responsibility. If a car dealer has a fiduciary responsibility, then I think almost anyone you do business with has a fiduciary responsibility. But that’s where we are, apparently.
I think at face value if you have mislead someone with regard to an apr interst that you have made up (as the salesman) or you have inflated to such a degree that then apr being charged bears no relate to the actual apr that has been charged - then clealry you are not being transparent with customers.
as far as i can see the fca has simply asked the fiorms to check that they havent been ripping of customer by using uber sketchy stuff that amounts to a lie by ommission.
On that regard as fca regulated entities i can see why the fca wants to uphopld basic standards of transpaency - what is silly is that the fca didnt actively intervene when intervention was necessary to cut it out in then fisrt place.
I dont think on any level is fine to say apr of 20% is comercial reality is that half of that is the extra sales fee of the garage. In that regard those that have done no wrong probably had nothing to worry about anyway.
These are fca regulated activities so the link is 100% clear that in soem cases the apr was outright piece of fiction that bore no basis in reality - every lender should easily have sen there was aline they shouldnt have crossed. I think the reponsible lenders have come forward and confirmed they did not participate in uber sketchy tactics.
i think then fca come out this worse than anyone else though - they only protect the consumers by upholidjbg standards in real time - its clear to me they failed in their duty if they were asleep at the wheel. If thtas the case perhaps RR stepping in is the right thing to do perhaps - despite my worries its being doen for other reasons.
I fully understand i am putting forward a minority viewpoint here -
I think this is more to do with a case heard in the Court of Appeal back in October that ruled it illegal for banks to pay commissions to car dealers without customer consent, rather than the FCA’s review into allowing dealers to take variable commissions.
In my view, the Court of Appel decision goes too far in favour of the consumer. It feels like changing the rules after the fact.
The FCA review, however, I think appropriate. Whilst I think most of us would expect a car dealer to be paid commission for organising finance, I don’t think many of us would expect them to be able to decide how much they take.
Secure Trust Bank (LON:STB) mkt cap is £88m. Could it fall prey to a predator?
The FCA is and has never been fit for purpose.
And there I had to sit through all those financial compliance videos (money laundering, customer is king, complaints, whistleblowing, integrity, act in good faith, avoid foreseeable harm, align customers financial objectives) - see I was paying attention.
It is one of the important purchases in life and "buyer beware" but all the emotions are in play and you have to be smart to overcome that, in which case you probably would not be arranging finance through the car seller in the first place, unless one of those 0% interest for 3 years etc deals - but who knows all the financial deals going on with that.
Point is you have to try and train the ethics, integrity and fair play whilst making a profit. Unfortunately it seems rare in the soft pillow of public service.
The Financial Conduct Authority (FCA) is funded by fees paid by the financial firms it regulates. The FCA is an independent public body that operates outside of the UK government.
The FCA by virtue of its funding is not independent. Their history is littered with failures to prevent fraud and mis selling.
2029 next election. We of course don't want Trump, or Elon etc but do need someone with integrity and power. Otherwise just a back water of Europe which was the plan. It worked.
The FCA is and has never been fit for purpose.
i would say we probably protect consumers better than we used to back in the day - but yes i would agree the FCA do seem to be an incoherent outfit when i expect them to be coherent - the main annoyance should be is that if customers were being shafted by unfair practicies how could they not work that out sooner and ensure that was not the case.
I dont think its a compcliated notion that where such arragemnets are in pace everything should be transparent particularly if you are quting an apr number
Revel Collective (LON:TRC) terrible results today, really think the BOD needs clearing out with new faces / ideas coming in. The share price has dropped from £1.80 to 0.3p restructured last year for the 3rd or 4th time and now saying results not so good due to restructure process. Unfortunately I hold and foolishly didn’t sell years ago…..
The fatal flaw in Revel Collective (LON:TRC) is hoping that the nightclubs side of the business can return to growth instead of continuous decline.
The pubs business is probably doing decently and worth multiples of the current market cap.
Not long soon till the next restructuring; probably a split of the two businesses but not sure current equity holders will get much. Meanwhile, insiders like Luke Johnson will get to dictate the new structure and participate in fresh fundraising at a price they like.
Off topic I know but the markets really are driving me to distraction. As part of a clear out of disastrous/poorly performing investments at the start of the new year I sold ENGAGE XR Holdings (LON:EXR) a meta verse speculative punt after it had fallen by 95% from cost (fortunately it was a relatively small punt) over the 4 years I had held it. This was after yet another profit warning and its continued share price decline and the ongoing sucker stock rating from Stockopedia. So what happens - today the share price goes up a staggering 178% (!!!) on the back of a new educational product launch at some upcoming show. It might only have gone from my 0.5p sale price to nearly 2p and if I had continued to hold it would have only been down 88% but it still hurts. Not investment advice but perhaps subscribers should keep a close eye on my other clear out sales for massive share price increases. Try Xaar (LON:XAR, Diageo (LON:DGE), Mondi (LON:MNDI), Saga (LON:SAGA), Robert Walters (LON:RWA) and GSK (LON:GSK). They may not go up 178% but you never know. All meant in jest of course!
Thank you for the prod re Mondi (LON:MNDI) .
Stocko expects an earnings release 20 Feb. I also think some holders of DS Smith may move their money here once the takeover is complete... but it doesnt look like they are doing well.
RE: STB et al.
Some comment in the Telegraph that Reeves intervention in the car finance case was driven by the rumour that Santander was considering exiting the UK due to red tape etc.
According to the Telegraph , Santander have since stated that they "have no plans" to leave Britain.
The Telegraph adds..
"There remains speculation that the group is considering stepping back from retail banking, which would put thousands of jobs at risk."
LBG Media (LON:LBG) has changed its year end from Dec to Sep. This makes analysis so much more difficult. Stockopedia is still showing year end Dec because its hard for them to deal with too. For me this is just going into the "too difficult" bucket because I don't want to spend all day on it. And there is always the suspicion that they have changed the year end to help gloss over some awkward details.
Beeks at a PEG of 1 is, by the standards of the fish in whose water it swims, undervalued by a third. A PEG of 1.5 would be considered fair value in the US market, against which the company aspires to be valued. No, it’s not cheap by UK standards but that’s irrelevant to the long term investment case. If I was running NASDAQ’s infrastructure I’d be seriously thinking about buying the company and it’s tech before my competition got hold of it!
All that said, not low risk because setbacks or ever higher interest rates would produce a big drop in the SP.
PEG of 1.5, fwd PER of 40* or 15* EBITDA private market value for this type of business.
All of those suggest 350-400p is fairer private market value and therefore Beeks Financial Cloud (LON:BKS) on sale!!
Note the Nasdaq revenues are not really included in the forecasts as I understand it so it feels as though FY26 is set up for a beat.
NWOR I have received an email from ii encouraging me to vote my shares in this company.
Obviously , as ii knows perfectly well, I can not vote shares that I do not own. The shares are owned by ii nominees and they can vote how they like regardless of what instructions I give them.
But , I suppose we can all play pretend ?
Good to see that you are up to speed with shareholder democracy DGF.
Yes, I could not resist a pointless moan, Lord G.
Had to Google it, NWOR means Not Worthy of Reply and long ago I gave up voting using ii when I knew the Institutions held more shares then private investors and now I can forget the whole voting business.
Know what you mean, I thought it was Not Without Risk
One interesting piece of news yesterday was the defenestration of the head of the CMA for being insufficiently pro-growth:
https://www.bbc.co.uk/news/art...
You'd imagine a lot of regulators will be running around this morning rapidly revising their plans ...
timarr
Yes Interesting timarr.
It was reported over a year ago that under the digital markets, competition and consumers bill that the CMA was to be given wider powers to counter privacy concerns from Big Tech.
Looks like this is slowly being kicked into the long grass.
I would guess that Big Tech, in the interest of "growth" will now have much more say in the UK.
On the theme of fund managers this week and the early signs that outflows for some are starting to turn I was surprised to see that Record (LON:REC) has dropped from 60p to 46p since their last update. They have a Q3 trading update on Friday and they haven't been suffering outflows in the same way as many of the traditional fund managers over the last year. Although, Roland did cover an interesting piece on forced redemptions in October (i think), noting that Record shares were caught up in that to an extent. I've purchased today, fingers crossed for some positive AuM news on Friday.
Record (LON:REC) .
There's a good thread by Wexboy_Value on X stating his reasons for adding more recently
https://x.com/Wexboy_Value/sta...
Thanks eParo, i'll take a look.
The YOY 25% customer growth in package holidays reported by easyJet (LON:EZJ) bodes well for Jet2 my preferred airline pick in which I have a full size position.
I though it boded well for easyJet (LON:EZJ) but there’s something the market didn’t like about it… -5%
oh well, they are still on track for medium term target of £1 billion in operating profit- patience is the key
Share buy back should be initiated like BA
Well done to Graham and the team for the new tabulated format on company announcements. I really like it.
Also great how quickly it's uploaded. Great job Graham and team.
Trump announces a $500 billion AI infrastructure investment in the US
Stargate will build “the physical and virtual infrastructure to power the next generation of AI,” including data centers around the country, Trump said. Ellison said the group’s first, 1 million-square foot data project is already under construction in Texas.
AI leaders have for months been sounding the alarm that more data centers — as well as the chips and electricity and water resources to run them — are needed to power their artificial intelligence ambitions in the coming years.
This and Elon pushing the EV and autonomous vehicle agenda should help companies like Volex (LON:VLX). Tesla is a major client.
*BERENBERG RAISES VOLEX PRICE TARGET TO 415 (400) PENCE - 'BUY'
Volex (LON:VLX) also has two manufacturing sites in China and one in Mexico according to this page. I think we need to work out what the tariffs impact will be. Although, they've gone up a bit the last 5 days which I am wondering whether is due to the Trump tariffs not sounding as bad as people feared?
In the December issue of Small Company Share Watch (scsw.co.uk), the editor wrote that FD Jon Boaden indicated Volex (LON:VLX) could switch production to Indonesia and India from Mexico and China within weeks for its customers.
So a tariff hike shouldn't be a big issue.
Volex (LON:VLX) manufacturing plant in China is for domestic market.
The one in Mexico is vulnerable as it is there to serve the American market.
Their major manufacturing is in Turkey and that would also be vulnerable.
Quite worrying for their 2 major items ie charging cables and the cables for the big communication centres such as the new one being constructed in Texas.
I hold but am concerned as it is my largest holding.
Volex (LON:VLX)
As far as China is concerned get your answer straight from the horse's mouth - go to https://www.investormeetcompan... press the Q&A button (LHS under date) and listen to the answer to Q4.
Beeks Financial Cloud (LON:BKS) finally announce their deal with the Nasdaq. Really could be a game changer here in this one
59 likes for that - shows how crowded this trade really is.
Hmmmmm.
Spot on!
All the best