Daily Stock Market Report (Wed 24th June 2026) - VTU, LIO, SGRO, PHP, AVG, BKG, CAV

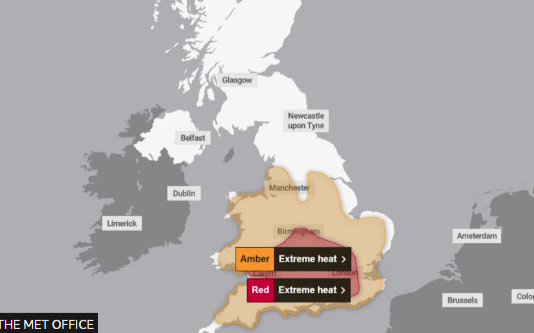
Heatwave: the Met Office says there is “a risk of serious illness or danger to life” over the next few days. There’s a Red weather warning for London and surrounding areas, including parts of Wales. A maximum temperature of 39 degrees is possible today:
I made it to a big box retailer just before it shut yesterday evening, and picked up a tall, cheap, oscillating fan that resembles a skinny Dalek. About 90% of customers in the shop were there for the same reason, and supplies were rapidly diminishing! My new friend should be a wonderful boost to my productivity (and will therefore be included on my tax return).
Alan Greenspan passed away on Monday, aged 100. One of the first times I came across Mr. Greenspan was when I read the book Capitalism: The Unknown Ideal as a teenager. First published in 1966, it included several chapters written by Greenspan. I thought he was a genius! For example, he wrote this in a chapter called Gold and Economic Freedom:
"...prior to World War I, the banking system in the United States (and in most of the world) was based on gold and even though governments intervened occasionally, banking was more free than controlled. Periodically, as a result of overly rapid credit expansion, banks became loaned up to the limit of their gold reserves, interest rates rose sharply, new credit was cut off, and the economy went into a sharp, but short-lived recession. (Compared with the depressions of 1920 and 1932, the pre-World War I business declines were mild indeed.)...
When business in the United States underwent a mild contraction in 1927, the Federal Reserve created more paper reserves in the hope of forestalling any possible bank reserve shortage. More disastrous, however, was the Federal Reserve’s attempt to assist Great Britain who had been losing gold to us because the Bank of England refused to allow interest rates to rise when market forces dictated (it was politically unpalatable)...
The “Fed” succeeded; it stopped the gold loss, but it nearly destroyed the economies of the world, in the process. The excess credit which the Fed pumped into the economy spilled over into the stock market-triggering a fantastic speculative boom. Belatedly, Federal Reserve officials attempted to sop up the excess reserves and finally succeeded in braking the boom. But it was too late: by 1929 the speculative imbalances had become so overwhelming that the attempt precipitated a sharp retrenching and a consequent demoralizing of business confidence. As a result, the American economy collapsed.
Unfortunately, by the time I read this book in the early 2000s, there was nobody at the Federal Reserve who seemed to understand the Fed's role in creating booms and busts.
Overnight market movements:
The FTSE is set to open down 0.4% at 10,415
S&P 500 is up 0.25% at 7,380
Brent crude (August) is down 1.1% at $76.30/bbl
Gold is down 0.9% at $4,075/oz
Bitcoin is up 0.7% at $62,850
The Agenda is complete.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Anglo American (LON:AAL) (£43.7bn | SR61) | Definitive agreement to implement a joint mine plan for the Los Bronces and Andina copper mines in Chile, following receipt of the required competition and regulatory approvals. | ||
SEGRO (LON:SGRO) (£10.0bn | SR73) | Prologis sent a letter to the SEGRO board. The proposal was unequivocally rejected. SEGRO shareholders would receive 0.084 new Prologis shares for each SEGRO share. Based on the Prologis share price of $145.3, this would represent a 24.6% premium to the most recent SEGRO share price. | TAKEOVER (AMBER) (Roland) Prologis shares trade on 2.5x book value, so it would obviously be a good trade for the US firm to use its stock to buy SEGRO at 1x book value. I think SEGRO’s board is right to reject this proposal, though. If Prologis won’t offer a premium, then I don’t see much reason why SEGRO shareholders would want to sell out. While market conditions in the UK and Europe may have been more difficult than in the US, I don’t see any reason why SEGRO can’t continue to generate value for shareholders on a medium-term view. | |
Berkeley group (LON:BKG) (£3.2bn | SR47) | £451m pre-tax profit. NAV per share up 9% to £39.17. Outlook: While short-term buyer caution has been driven by uncertainty over the timing of interest rate reductions, underlying demand indicators remain positive, and transactions will recover as conditions and confidence improve. | AMBER = (Roland) [no section below] I covered this respected housebuilder in more depth in April and concluded that the valuation was almost certainly cheap, but the catalysts for and timing of any recovery were uncertain. I don’t have much to add to this today except to note that as far as I can see from my research, until this year, Berkeley shares had not traded below book value since 2008. I’m going to stay neutral today as the group’s subdued profits mean the current valuation is probably fair, in my view. Consensus shows earnings falling again in both FY27 and FY28. But for a patient buyer or an investor with a more bullish view on prospects for London housing (perhaps under the next PM), I think Berkeley could be worth a closer look. | |
Primary Health Properties (LON:PHP) (£2.4bn | SR56) | PHP confirms that it is in advanced discussions with an investor regarding the potential contribution of the private hospital portfolio to seed a new joint venture. | AMBER/GREEN (Roland) [no section below] An updated note from broker Shore Capital this morning suggests the unnamed JV partner might be GIC – the Singapore sovereign wealth fund. A private hospital JV to help deleverage following the Assura merger has been in the pipeline for some time, so it’s good to see signs of progress. While PHP’s loan-to-value ratio of 57% is higher than I’d normally want to see, the high occupancy and long lease terms of the REIT’s healthcare estate mean I’m willing to be relatively relaxed about this in the short term. With the stock trading slightly below book value and offering an 8% dividend yield, I’m inclined to be moderately positive ahead of PHP’s interim results on 30 July. | |
B&M European Value Retail (LON:BME) (£1.88bn | SR54) | New CFO with effect from February 2027. Currently VP of Commercial Finance at ASDA. | ||
ITM Power (LON:ITM) (£873m | SR23) | ITM and DB Systemtechnik have signed a Letter of Intent to forge an innovation and research partnership for the development, piloting and testing of green energy solutions for the transport and critical infrastructure sectors. | ||
Trainline (LON:TRN) (£766m | SR86) | New CEO from September 2026. Most recently he was CEO of the UK & Ireland division of Flutter Entertainment. | ||
GlobalData (LON:DATA) (£586m | SR36) | The new CFO will join from September 2026. Was CFO at Keywords Studios. | ||
THG (LON:THG) (£524m | SR27) | Full year guidance reiterated. H1 Group revenue growth of c.+6.5% (H1 2025: -2.5%) and H1 Adjusted EBITDA of at least £40m. | ||
Beximco Pharmaceuticals (LON:BXP) (£389m | SR n/a) | Q3 25 Results, Q1 26 Results, Half-Year 26 Results & Q3 26 Results | Nine months ended 31 March 2026: net sales increased 13.1% to Bangladesh Taka 41,428.0m / £256.9m. Profit after tax increased 34.0% to BDT 7,048.6m / £43.7m. | Beximco shares have been suspended since 2 Jan 26. |
Empire Metals (LON:EEE) (£303m | SR10) | Total consideration of A$750,000 cash, comprising the A$50,000 non-refundable deposit previously received and the balance of A$700,000 received by the Company on completion. | ||
Essentra (LON:ESNT) (£234m | SR39) | The transaction has been completed at an acquisition multiple of 6.5x FY25 EBITDA and is expected to be accretive to margins and adjusted EPS in the first full year post-completion, with a return on invested capital of 15% anticipated in the third full year of ownership. | ||
Vertu Motors (LON:VTU) (£228m | SR97) | Group margins remain stable and overall trading performance remains ahead of prior year levels. The Board expects FY27 results to be ahead of current market expectations (consensus: adj pre-tax profit of £23.5m to £25.1m). Shore Capital broker estimates updated: - FY27E adj EPS: 5.9p (prev. 5.7p) - FY28E adj EPS: 6.3p (unch.) | AMBER = (Roland) Vertu appears to be taking sensible measures to improve the performance of its dealer portfolio, tilting further towards Chinese brands and combining sub-scale/underperforming franchises. Today’s c.4% upgrade to FY27 profit forecasts still leaves expectations well below the level seen before March’s downgrade. While I share the company’s view that the government regime mandating a shift to EV sales is an adjustment period, I think Vertu’s subdued profitability means the valuation is probably about right at the moment. I’m staying neutral today. | |
Avingtrans (LON:AVG) (£203m | SR65) | The Board is pleased to report that FY26 profit will be in line with market expectations. The Group has continued to secure strategically significant contract awards across its core nuclear and infrastructure markets, while also making encouraging progress in expanding its presence in adjacent growth sectors. | AMBER/GREEN = (Roland) [no section below] This seems a positive update overall, with news of new contract wins in the group’s nuclear business in both the US and South Korea. There’s also a contract win in the UK for high-spec tunnel doors for the HS2 project. Revenue in the Medical & Industrial Imaging division was “lower than had been intended” due to the timing of regulatory clearances, but progress is being made. The only dud note is that Avingtrans now expects to have to repay c.$5m of Covid-era loans to which it was not entitled as a foreign-owned business. While this is a material amount for a business that generated £8m of operating profit last year, payments are expected to be spread over 24 months. With earnings growth running at double digits and a mid-teens P/E, the outlook seems favourable to me. My only niggle – without in-depth research – is that profitability appears low, with an operating margin of c.5%. I’m going to leave Graham’s previous view unchanged today. | |
Liontrust Asset Management (LON:LIO) (£177m | SR94) | Adj pre-tax profit -36.9% to £30.5m, with adj EPS -35.4% to 36.7p. AUMA -13.4% to £19.6bn, with net outflows of £4.2bn. | GREEN ↑ (Graham)
I’m glad I resisted the temptation to take a neutral stance on this last time, as I stuck to the view that “profits are profits”. The algorithms take a similar view, calling it a Super Stock: It’s unfortunate that outflows continue, but we can look on the bright side: outflows are currently much slower than they were before, and market movements are offsetting them very well. Plus, it looks like broker forecasts might have finally stopped falling:. So as a contrarian value play, I still like this. Indeed, I’m going to trust my instincts and go GREEN now, on the back of today’s upgrades. | |
Jadestone Energy (LON:JSE) (£150m | SR35) | Based on the strong performance of the first well and data gathered while drilling the second well, the third well has now been confirmed and drilling has begun. 2026 capex guidance of $50-80m is unchanged. | ||
Pharos Energy (LON:PHAR) (£106m | SR93) | Pharos is recommending a cash offer from Ratio Petroleum Energy for up to 28p per share, including dividends. | TAKEOVER | |
Vulcan Two (LON:VUL) (£76m | SR35) | In March 2026, the Company completed a £40m fundraise and the acquisitions of CloudRx, Webmed and Hyperdrug, creating a diversified healthcare platform spanning both B2B and B2C digital pharmacy services. A new distribution facility in Leeds is also being fitted out. | ||
Cobra Resources (LON:COBR) (£47m | SR9) | Approx 80% of drilling results from Boland and Head have been received to date. Latest assays from the Head prospect point to a scalable system open to the north and south, while unique acid generation characteristics further enhance production economics. | ||
PROCOOK (LON:PROC) (£42m | SR75) | Revenue +23% with LFL +11.8%. Pre-tax profit +64.5% to £2.5m, with free cash flow of £3.5m. New customers +24.6%, active customers +24%. Outlook: confident of delivering FY27 expectations. | ||
Cavendish (LON:CAV) (£36m | SR61) | SP -5% Revenue +2.3%, pre-tax profit +114% to £1.5m. Adj EPS -15% to 0.8p. Transaction volume 96 (FY25: 100). "While market conditions remain uncertain, Cavendish is well positioned to benefit from improving sentiment over time." | GREEN = (Graham) [no section below] According to Hardman Reseach, "all main figures were in line with expectations". Checking the balance sheet, I see that net assets are £25m, after excluding intangibles, covering most of the market cap. Looking ahead, Hardman forecast that PBT will more than double in the current financial year (FY27) to £3.6m on the back of a modest increase in revenues from £56.9m to £60m. Cavendish themselves have offered a balanced outlook statement today. Personally, I remain of the view that this continues to offer value at the current level. The unchanged 0.8p dividend provides a yield approaching 10% while investors wait for some capital appreciation. | |
Coppa Collective (LON:COPC) (£25m | SR82) | LFL sales +1.8%, with group revenue flat at £25m. Adj EBITDA +200% to £0.3m, with pre-tax loss narrowed to £1.7m (H1 25: £2.2m). Group continues to see resilient consumer demand, albeit with cost pressures. | ||
Haydale (LON:HAYD) (£25m | SR N/A) | Revenue +463% to £2.25m with gross profit +325% to £0.85m and adj operating loss of £1.16m (H1 25: £0.68m), “reflecting investment in platform execution and the enlarged Group operating structure”. Outlook: the board “remains focused” on delivering current FY26 market expectations (Revenue £8m, adj pre-tax loss of £2.5m). | ||
Light Science Technologies Holdings (LON:LST) (£18m | SR4) | The Group currently has two passive fire protection installation projects in progress with a combined contract value of c.£390k to c.£775k depending on the extent of remediation required. Additionally, total Injectaclad material supply orders secured since the acquisition of RLUK now amount to c.£885k. | ||
River Global (LON:RVRG) (£17m | SR34) | The Financial Conduct Authority has approved the change in control for River Global Holdings and the proposed acquisition of RGH by Liontrust is therefore expected to complete on 30 June 2026. AUM on Friday, 19 June 2026 was £3,442 million (31 March 2026: £3,101 million). | ||
Eco Buildings (LON:ECOB) (£16m | SR5) | Following a recent £2.35m fundraise, Eco has started construction of a second manufacturing online at its production facility in Durres, Albania. | ||
Lexington Gold (LON:LEX) (£13m | SR7) | Entered into an agreement with GoldOz Ltd to acquire 100% of the issued share capital of Global Asset Resources Ltd ("GAR") from Lexington Gold. GAR is the company through which Lexington Gold holds its 51% interests in the Company's three principal Carolina gold projects. Lexington will receive A$350k and 25.5m new GoldOz shares when GolzOz relists on the ASX. | ||
Fulcrum Metals (LON:FMET) (£13m | SR12) | FY25: no revenue and pre-tax loss of £553k. Highlights: completed acquisition of Teck-Hughes Gold Tailings Project and divestment of Tully Gold Project. Successfully raised £1.9m during the year and £1.3m subsequently to fund project developments. | ||
Thor Energy (LON:THR) (£12m | SR31) | Programme will acquire c.464 line-kilometres of 2D seismic across the HY-Range project in Q3/Q4 2026. Fully funded from existing cash. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Up 14% at 336.3p (£202m) - Annual Financial Report - Graham - GREEN ↑
While the results from this fund manager are poor, they aren't too far off the existing forecasts at Panmure Liberum.
Revenue £123m vs. Panmure estimate £126m
Operating profit £29.5m vs. Panmure estimate £30m
Adj. EPS 36.7p vs. Panmure estimate 37.6p.
Net outflows during FY26 were very large at £4.2bn, but this was already known.
What’s more interesting is the outlook, and that’s where things are looking up.
Panmure have increased their EPS forecasts for FY27 (from 35.7p to 36.7p, matching the FY26 result) and for FY28 (from 41.7p to 43.1p). They also introduce a new FY29 EPS forecast of 49.7p, which sounds a little aspirational to me while still being within the bounds of possibilities.
At the current share price, that gives a P/E multiple of 9x for the current year, falling to 8x for next year.
The acquisition of River Global is going ahead at the end of this month, slightly sooner than expected, bringing in another £3bn pounds of AUM.
Current Trading Update
AUM as of last week was £21.4bn, up strong from £19.6bn at year-end (March 2026).
In Q1 of the new financial year, so far, there have been net outflows of £276m - a much slower pace of outflows than we saw last year.
CEO comment:
"The improvement in Liontrust's flows over the past nine months is testament to the expansion of our distribution internationally and broadening of client types. This reflects the significant development at Liontrust over the past couple of years, with net outflows now at £276 million for the current quarter with one week to go, and strategies such as Cashflow Solution benefiting from both strong performance and client diversification….
We have had a very positive response from both RGH and Liontrust clients to the acquisition and are pleased with the way in which the two companies have come together to ensure completion is as smooth as possible… We will take advantage of any other such strategic deals as and when they appear.
Dividend: this has been rebased at a much lower level. The total dividend for FY26 is 19p, vs. 72p in the prior year. At ;east 19p is covered very well by EPS.
Outlook: nothing too specific here.
Liontrust is showing positive results of all the progress we have made over the past few years. We are well positioned to take advantage of the opportunities ahead for active management.
Graham’s view
I’m glad I resisted the temptation to take a neutral stance on this last time, as I stuck to the view that “profits are profits”.
The algorithms take a similar view, calling it a Super Stock:
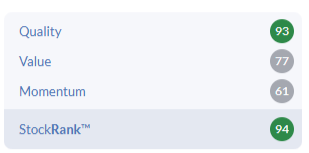
It’s unfortunate that outflows continue, but we can look on the bright side: outflows are currently much slower than they were before, and market movements are offsetting them very well. Plus, it looks like broker forecasts might have finally stopped falling:
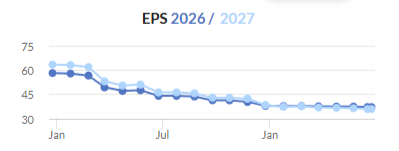
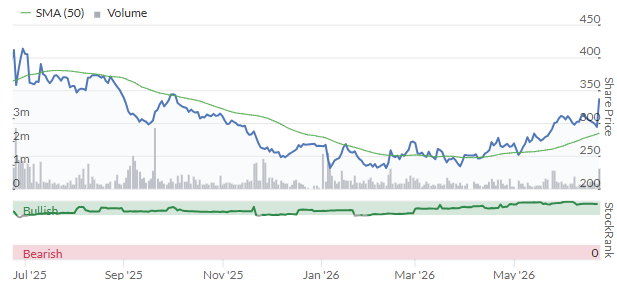
So as a contrarian value play, I still like this. Indeed, I’m going to trust my instincts and go GREEN now, on the back of today’s upgrades.
Roland's Section
Vertu Motors (LON:VTU)
Up 2.8% at 75p (£234m) - AGM Trading Update - Roland - AMBER =
Today’s AGM update is short but relatively positive, with a modest upgrade to full-year profit guidance for the year ending 28 February 2027.
… the Board anticipates that full year results for FY27 will be ahead of current market expectations
Trading appears to be relatively positive despite well-documented headwinds:
The Group continues to trade positively in the financial year, with like-for-like volume growth in all channels: new retail, Motability, used vehicle and fleet and commercial. Aftersales is contributing to growth in Group profits year-on-year. Group margins remain stable and overall trading performance remains ahead of prior year levels.
One factor behind the company’s success appears to be the company’s growing tilt towards Chinese car brands. These are among the fastest-growing in the UK market at the moment due to their low prices, high specs and weighting towards EV models:
The Group will launch its first Omoda and Jaecoo dealership on 1 July 2026 […] another Group outlet will be re-franchised to Omoda and Jaecoo on 1 October 2026. The Group will have 15 sales outlets representing Chinese automotive brands following these openings.
Checking the company’s website, Vertu already has a number of BYD, MG and Geely franchises.
Sales of the Chinese brands sold by Vertu have rocketed this year according to SMMT (trade body) data for the year to May:
BYD +113% to 31,553 (3.4% market share)
Geely +n/a% to 4,378 units (0.5% market share)
Jaecoo +369% to 27,996 (3.0% market share)
MG +9% to 38,346 (4.2% market share)
Omoda +169% to 15,078 (1.6% market share)
For context, popular brands such as Ford, BMW, Toyota, Peugeot and Volkswagen have all seen sales (and market share) decline this year, quite materially in some cases.
I expect Chinese car manufacturers to continue to carve out a permanent share of the UK market. This would repeat a process seen historically with Japanese brands and more recently with Korean firms Kia and Hyundai.
Cost savings are also being made by combining (presumably) underperforming sites into multi-franchise operations:
Cost benefits will arise from portfolio changes, such as the relocation in the coming months of Sheffield Mazda from a stand-alone site to a multi-franchise operation alongside the Nissan franchise in the city. Group operating costs remain tightly controlled.
Updated forecasts
Vertu doesn’t tell us what its new expectations for profit are, but fortunately we do have access to updated broker coverage today, adding some numbers to the commentary.
Here are the latest forecasts from Shore Capital, with thanks for making these available on Research Tree.
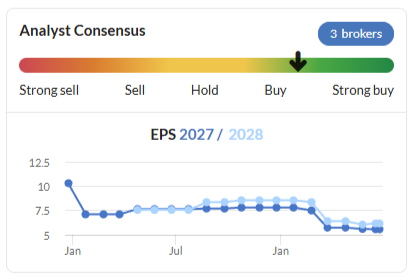
FY27E adj EPS: 5.9p (+3.5% vs 5.7p previously)
FY28E adj EPS: 6.3p (no change)
Today’s upgrade is limited to FY27 and is fairly modest. When set against the backdrop of downgrades earlier this year, we can see that expectations are still significantly lower than they were six months ago:
Roland’s view
UK car retailers (and European car manufacturers) have issues with the government’s ZEV mandate, which requires a fixed percentage of sales to be zero emission on pain of a financial penalty for each non-compliant car sold.
Manufacturers are forcing discounted EV stock on dealers, stimulating sales but putting pressure on dealers’ margins. Consumers still have mixed views on EVs and aren’t quite buying enough of them yet to meet targets, preferring hybrid models.
There’s pressure on the government to dilute its target of 80% ZEV new registrations by 2030. Perhaps the incoming Prime Minister will do this.
SMMT data and forecasts suggest EV market share will have risen from 16.4% in 2024 to 26.8% in 2026. The government targets for those years were 22% and 33% respectively, so it looks like adoption is running c.5% behind target. Even so, there’s clearly strong momentum in EV uptake.
Vertu has previously referred to this as an adjustment period and I think it’s fair to expect the situation to ease over time. But the structural challenges facing European automakers are significant, and I think it could take some time for profitability to improve.
In the meantime, forecasts suggest Vertu will continue to generate a 5% to 6% return on equity on its asset-rich balance sheet.
For me, this suggests the current valuation of 0.6x book value is probably about right, as it gives buyers today a c.10% expected return on cost of equity.
Looked at differently, a forward P/E of 12+ and a dividend yield of 2.8% seem high enough for a slow-growing, low-margin car dealership group.
On balance, I don’t think today’s slight upgrade is enough to justify an upgrade to our view, so I’m going to leave Mark’s previous AMBER unchanged.
SEGRO (LON:SGRO)
Up % at p (£m) - Prologis: Statement re Possible Combination and SEGRO: Statement Regarding Possible Offer - Roland - TAKEOVER (AMBER)
This FTSE 100 REIT is not a stock we’ve looked at before, but it’s the UK’s largest listed REIT, with a £19bn portfolio of logistics properties and – increasingly – data centre projects.
SEGRO’s share price spiked during the pandemic, but the valuation has since returned to more earthbound levels.
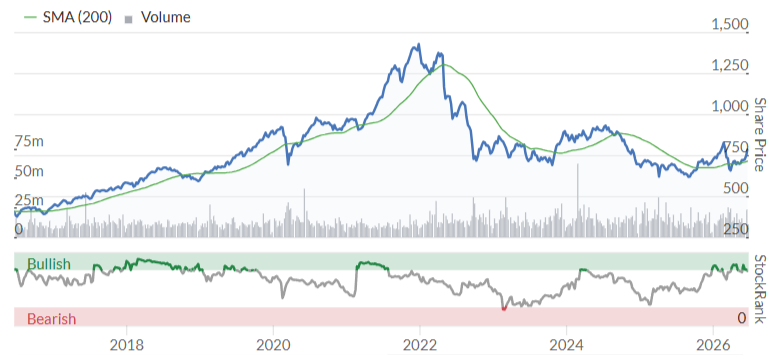
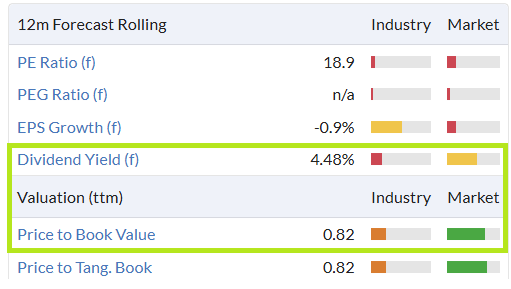
Prior to today’s bid news, SEGRO shares offered a small discount to NAV and a useful dividend yield:
That brings us up to date, so let’s take a look at today’s news.
Offer from Prologis
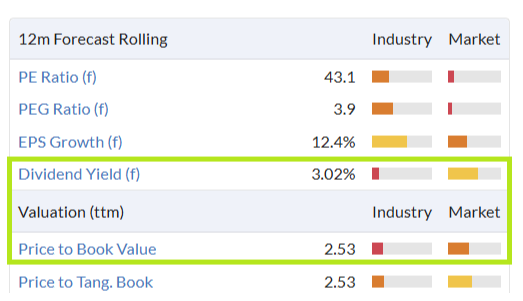
Prologis (NYQ:PLD) is a US REIT with a similar focus to SEGRO. Naturally, it’s a lot larger, with $235bn of assets under management. It’s also much more highly rated, with a £100bn market cap and a price/book ratio of 2.5x:
Here are the details of the Prologis offer:
0.084 new Prologis shares for each SEGRO share
Based on the Prologis share price of $145.3 and GBP:USD exchange rate of 1.32 as at market close on 23 June 2026, the Proposal represented a value of 925 pence per SEGRO share.
SEGRO’s net asset value was last-reported at 925p, on an adjusted basis. So this is an offer at book value.
SEGRO’s board has rejected the proposal:
The Board of SEGRO has unanimously and unequivocally rejected the Proposal, which falls a long way short of SEGRO's own views on value.
The Board of SEGRO considered the Proposal together with its advisers and believed that the Proposal was opportunistically timed and sought to take advantage of the clear dislocation between SEGRO's current share price and its highly attractive underlying business and strong prospects. This has been accentuated by major geopolitical issues which have adversely impacted trading valuations across the UK and European real estate sectors relative to the US REIT sector.
This situation reminds me a little of the bid for Ramsdens yesterday.
It makes perfect sense for Prologis to use its shares to attempt to buy SEGRO at book value when Prologis shares are valued by the market at 2.5x book value.
Making an acquisition on this basis will theoretically lift the share price of the acquiring company, as it benefits from a re-rating of the acquired earnings. We can see above that the Prologis P/E is double SEGRO’s P/E rating.
Prologis comments on acquisition
Unsurprisingly, the US firm is quick to highlight the potential for share price gains:
SEGRO shareholders would receive shares in the world's largest logistics REIT with a $140.9 billion market capitalisation, unlocking, on closing, significant upside to the current share price.
Prologis also believes it is able to provide “accelerated growth” compared to what might be achievable by SEGRO as an independent business.
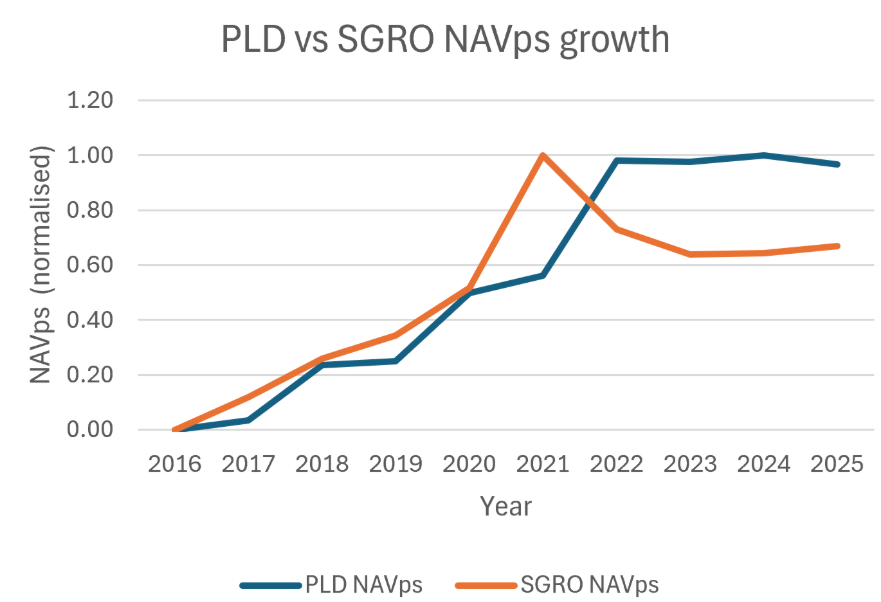
Using net asset value per share as a guide, performance over the last five years appears to support this claim, but a 10-year view shows the companies to be more evenly matched:
Prologis 5y NAVps CAGR: 5.8% / 10yr CAGR 8.1%
SEGRO 5y NAVps CAGR: 2.3% / 10yr CAGR 7.3%
Zooming out to take a 10-year view suggests that SEGRO’s claim of more difficult geopolitical conditions in the UK and Europe may have some merit. Until 2022, both companies were level-pegging on NAV growth:
Roland’s view
Whether either of these companies is really worth a significant premium to book value is a more nuanced question.
I would personally be very reluctant to buy shares in a REIT at more than 2x book value, especially as Prologis has a five-year average return on equity of just c.7%. If market conditions change there could be little to prevent the stock de-rating to trade closer to underlying asset value.
However, there’s no denying the scale and momentum of the US market and investors’ apparent willingness to support much higher ratings for US stocks. Prologis has also turbocharged its growth in recent years with a number of large acquisitions – I guess this could continue for a little while yet.
SEGRO shareholders can choose to sell into today’s spike or wait to see if Prologis comes back with a more convincing bid by the Takeover Panel deadline date of 22 July.
Personally, I would be inclined to continue holding SEGRO shares if I owned them and liked the sector. I think the valuation remains fair and don’t see any reason why the business can’t deliver further growth over the medium term.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
Micron Technology (NSQ:MU)
ABSOLUTELY CRUSHED THEIR EARNINGS
• Revenue $41.5B vs Est. $35.5B
• EPS $25.11 vs Est. $20.39
• Net Income $33.7B vs Est. $23.9B
• Gross Margin 85% vs Est. 82%
Q4 Guide
• Revenue $50B vs Est. $43B
• EPS $31.00 vs Est. $25.07
• Gross Margin 85% vs Est. 84%
All the best
Micron Technology (NSQ:MU) That is good news, managed to buy some under $1,000, this evening, already up 20%.
The volatility in the Micron Technology (NSQ:MU) share price is extraordinary. It's forecast for another big rise today. When it stops rising this time I'm going to sell half my holding.
Thanks but it was Roland!
:-))
Roland, apologies, great work on Telecom Plus (LON:TEP) yesterday. Worth a read .
DONCASTERS $DPC IS MORE THAN 30 TIMES OVERSUBSCRIBED AHEAD OF ITS IPO PRICING TODAY.
The 250-year-old aerospace and gas turbine parts maker is the latest industrial name catching demand for indirect AI data center exposure.
The deal:
- Marketing range of $28-$32 per share
- Now expected to price $1-$2 above the range
- IPO raise of up to $746.6M at the top of the marketing range
- Up to $887.7M in aggregate with two private placements
The backing:
- Qatar Investment Authority investing around $75M
- Company directors and insiders buying about $66M
- Jefferies, Morgan Stanley, Barclays and Moelis leading
The business:
- Engine product order backlog of $930M as of March 29
- Power generation turbine parts for GE Vernova and Siemens Energy
- Aerospace castings for GE Aerospace, Honeywell $HON and Pratt & Whitney
Listing as DPC Holdings on the NYSE Thursday under $DPC.
FOUNDED IN SHEFFIELD, UNITED KINGDOM!
All the best
Do any of you have any insight / information on when the suspension of Beximco Pharmauceticals (BXP) will be lifted for its UK listed shares? All I was able to gather was that they are awaiting a Court case in Bangladesh related to appointing new NEDs. Any insight welcomed.
Anyone else experiencing gremlins in the Stocko system today?
Been flicking through various pages related to Works co uk (LON:WRKS) when I was suddenly alerted that "This stock is in a takeover situation" !
Refresh the screen and it's gone.
Phew!
Hi Graham. Thanks for the brief reassurance on Cavendish (LON:CAV) which I hold. I just looks so cheap. I am constantly wondering what have I missed? Glad to read that you think its cheap too.
Agree Revs. I have been following it for a year or so. Bought some to-day for the yield initially and would hope to see some capital growth next year.
This is what I though in Feb 2024 and have been sat on a 15% loss ever since, I know it does look cheap but they seem to have missed target again don't they? And they were due to increase the divi slightly, can't really do that when they are paying it out of the cash balance
Having followed it for a year it looks like things are iomproving. Obviously depends on market activity to a degree.
Below is an AI summary
Core profit before tax* £3.5m (FY25: £3.7m)
- Core EPS* 0.80p (FY25: 0.94p);
- Profit before taxation £1.5m (FY25: £0.7m)
It strips out the volatile, non-operational, or paper-only accounting adjustments to show how the business is actually trading day-to-day.
To get from the reported £1.5m to the £3.5m core figure, they add back:
I attended a Yellowstone presentation this evening by Cavendish (LON:CAV) management.
Some interesting tidbits, from memory. I have scribbled lots of notes, but need to organise it and will have it in my month-end Boon Fund performance post.
(I hold in the Boon Fund)
Graham,
A brief note of appreciation of your investigative dive into Telecom Plus (LON:TEP. Personally I thought it a great piece of work.
Thank you.
seconded
SK Hynix (KRX:000660) IS GOING PUBLIC IN THE US IN JUST 3 WEEKS
SK Hynix (KRX:000660) is planning a $29.4 Billion US listing with trading set to begin on July 10th
This would be one of the top five share sales in history, comparable in size to Saudi Aramco's record 2019 IPO.
SK Hynix controls 57% of the global high-bandwidth memory market by revenue. HBM is the chip that sits inside every NVIDIA GPU powering the AI buildout. Without it, the data centers do not work.
The numbers behind the business:
Q1 2026 operating profit: $24.3 billion, a record high
Q1 2026 sales: $34 billion, nearly tripling year over year
Stock performance: +300% in Seoul this year.
Market cap: over $1 trillion
The proceeds will fund additional capacity expansion and purchases of EUV lithography machines needed to make next-generation chips.
Lead underwriters: Bank of America, Citigroup, Goldman Sachs, JPMorgan.
All the best
SK Hynix (KRX:000660) - I wonder if Nasdaq investors will see any value here
The quality isn’t bad either
SK Hynix (KRX:000660) was added automatically to the QM Core Blueprint - Best of Best 40 Worldwide portfolio back in late April. Currently up 111%. No sector or technology knowedge required, just factor based screening using Stockopedia, a process and discipline.
High cyclical stock
DRAM and NAND boom and bust cycle of memory chips.
I wouldn’t take much notice of any figures and I would not be taking part in the IPO as the company is already listed.
All the best
A genuine question Yiannos...
Why did you highlight this stock?
This thread starts with you stating that SK Hynix will list in the US in 3 weeks - various people have given a thumbs up to your message, a couple more have replied to you, but then you say you won't be investing in it and don't pay attention to any of the figures.
A friend of mine highlighted SK Hynix two years ago at the side of my local football pitch, watching his son play football.
It had already been on a huge run. I'm frankly astonished it's 15 times higher, and the P/E ratio on a forecast basis has dropped to only 7x .
Certainly, from my point of view, I had no idea that SK Hynix was floating in the USA - good to know !
Hi Ed,
I would like to see US stocks covered and analysed and I believe it’s something that many subscribers are interested. Your article on the Space Exploration Technologies (NSQ:SPCX) IPO was excellent.
The US market is mentioned daily in the DSMR and there is no point in discussing crashes all the time. Has there ever been a US crash that did not affect UK equities? We should all be careful on what we wish for.
We all know that the US market is going to grow much bigger and the UK market smaller.
All the best
Graham is obsessed with the SK market, mentioning it every time it goes down but never when it goes up-:).
For example he mentioned in the past that the SK market is down 10%. Then it goes up 30% and there is no mention. Then it goes down 10% and the flags are out. Of course this behaviour has to do with the semiconductors hoping that this will spill into the US…….and we will have a crash..
Since SK Hynix (KRX:000660) has in the past been mentioned in his morning DSMR, I thought to share the news with everyone and not concentrate on today’s special topic regarding Rachel Reeves.
We will crash at some point but the big firms like Alphabet (NSQ:GOOGL) and the rest will become even bigger……
Hope I have answered your genuine question. My answer is as genuine as you can get.
All the best
Given that the majority here is focusing on politics rather than finance, I suggest to all to take a close look at Stack BTC (OFEX:STAK).
Political with a bit of finance in it!
In early 2026, Nigel Farage invested over £200,000 to acquire a 6.3% stake in Stack BTC, an Aquis-listed Bitcoin company where Kwasi Kwarteng serves as executive chairman. Farage subsequently appeared in a promotional video for the firm, pushing the button on a £2 million Bitcoin purchase.
UK politics and the economy have such a bright future ahead of them-:)
All the best
Liontrust Asset Management. (LIO)
After a few false dawns, maybe Graham is proved right on this one!
The numbers are awful but the market reaction is positive and so is the stocko ranking. This tells me we have reached the bottom.
When the world's largest investment fund buys over £1 million pounds worth of shares in May, there's a good chance the share price is heading North.
Just a quick thank you to Graham for the book reference and effective recommendation in his opening comments which I find are a very helpful opener to the daily report!
It’s so disappointing these days to see fewer and fewer useful posts covering the Companies reporting today, and reacting to the excellent analysis from Graham or Roland etc. Instead there are these pointless off topic spats from the same few posters, that are of zero use or interest to those looking for the quality comment that used to feature here.
This seems to have driven away previous regular quality posters. It’s so disappointing and imo shows lack of appreciation for the tremendous hard work and high quality analysis from Graham and the team.
Very little if anything came from Graham and Roland today Ken but I tried my best to raise some enthusiasm for a small-cap miner.
Ken, time you got back on the topic of discussing the companies reporting as above!
I disagree Ken. The world at large and the machinations of those that rule it are the reason that most of us are here trying to beat them at their own game. Political comment is inevitable for a comprehensive debate. You might not be interested in politics but politics is interested in you. You often comment from some lofty position which makes me suspect retired public sector on an inflation linked pension talking down to the less fortunate. Empathy is something you could work on to balance the hubris.
Samsgrandad, Hear, hear!
Correct Ken!
All the best
I completely agree. When I want to hear drivel about politics, I'll join a golf club.
P.S. Thanks, Graham, for the weather forecast. I didn't know it was going to be hot!
Would love to hear how you'd encourage quality posters to engage, and for the discussions to remain on topic.
I do not think advertising your new business here is really something we want to see every day either
Ok, fair enough. I've been a member for 8 years and this exact debate has kicked off several times every year. We're trying to fill a gap that we think exists, but point taken.
A massive gap!
All the best
Beximco Pharmaceuticals (LON:BXP) The share is not yet back from suspension - having looked at the Dhaka SE this morning I suspect that the legislation in the High Court to prevent a cohort of new Directors is still ongoing, but they have sought and had permission from the Securities and Exchange Commission to publish the past four quarters results.
These read very very well - there's money to be made on return.
Graham?
Avingtrans (LON:AVG)
Cavendish have increased its forecast for adjusted PBT for year to end May26 by 3.9% to £12.3m from £11.8m with a similar increase in eps to 31.7p from 30.3p
The shares are down around 7% which seems somewhat harsh, but the slower revenue growth in the medical division due to timing of receipt of regulatory clearances and the repayment of $5m of covid loans has taken the shine off the shares.
The takeover of SEGRO (LON:SGRO) by Prologis (NYQ:PLD) makes no sense to me ... why would i want to take highly rated Prologis shares (PE 43) for a c.25% premium ? As a shareholder, I am not interested.
Agreed. But as a holder I am very interested in the market reaction of a rise of 139p atm. This brings it nearer a sensible rating.
I hold SGRO and will wait for the higher bid-which I expect will come. I also hold Tritax Big Box REIT (LON:BBOX) and bought some more today. Trades at a near 15% discount to NAV. Blackstone hold 8%.
It's good to see that Empire Metals (LON:EEE) has been, and is using, its assets to fund the Pitfield project rather than diluting investors share in the company as Harry in KEFI Gold and Copper (LON:KEFI) has done and is still doing there. I hold both.
Be interested to hear more on Primary Health Properties (LON:PHP) ?
They would like to get a investor in on a joint venture basis so they can reduce the LTV ratio to nearer 40% down from the current 57%. Sounds like they picked up a rumour that some organisation had got hold of the story and was about to publish. I hold.
As Graham has stated above - it looks like the JV partner could be the Singapore Wealth Fund - GIC which makes a lot of sense (they already have other UK property JVs) and would surely be beneficial for PHP shareholders with the injection of cash to reduce their debt. And they are serious long term investors - not SABA shakers.
My REITs seem to be up a fair amount at the open today. Did some kind of reforecasting on future interest rates just take place?
Offer made for SEGRO (LON:SGRO) .
My tip for keeping cool is to open windows wide early morning and close when temperature starts to rise. Close curtains on sunny rooms. Have a decent de-humidifier running during the day to remove the moisture resulting from your perspiration. Fans will cool you down better if the air isn't saturated with moisture, 60% RH is ideal and this will ensure a comfortable working environment. Move the de-humidifier to the bedroom in the evening to assist in a good night's sleep.
Or get AC fitted! I think its inevitable many houses will with summers like this becoming the new norm here. (I've already bitten the bullet and done it this year and many colleagues and friends are doing the same)
I am of the view that if you have the privilege to work from home you also have the burden of providing yourself with a home office setup properly to do your best work.
Fair enough but a de-humidifier will only cost £100-150 and off the shelf in Amazon. Running costs are also within reach of elderly relatives with approx 75watts consumption.
Any ways to play this theme on the UK markets?
Probably not, you'll be seeing plenty of dehumidifyers etc at car boots before Christmas that people don't have room for.
That would be very shortsighted, I originally bought two dehumidifiers to counter a condensation problem with two bedrooms in the winter. Quite a common problem I believe.
Madness in my opinion. The world is warming because man is pumping carbon into the atmosphere in humungous quantities and our answer to staying cool is...........use more energy?? The end game is pretty clear in that approach.
The uncomfortable irony is that as the world gets hotter, our immediate response is often to consume even more energy to stay cool. Air conditioning may be necessary, even life-saving, but unless that energy is clean and buildings are designed better, it risks becoming a very expensive way of running faster on the same treadmill.
The uncomfortable irony is that as the world gets hotter, our immediate response is often to consume even more energy to stay cool
this sound like half a story here presenting a somewhat false narrative?
as it gets its hotter some will need extra energy to cool down i would agree with that statement - but we should also need less energy to heat people up - would you not concede? So for every person splashing out on air conditioning - there is is probably someone who previously needed to put the heating on who now doenst need to do that now as its warmer.
I dont know the stats but i would guess we spend materially more on keeping people warm than we do on cooling them down - so it would seem logical to me that would save energy overall if that is the case - or perhaps it may be closer to neutral - thats the opposite of the line you are spinning.
I havent fact checked my presumptions so i could be wrong on the detail here.
We are actually burning millions of years worth of sunshine stored in the form of oil and gas and we are taking only a couple of millennia to do so. Of course the Earth is going to overheat but hey, tomorrow is another day.
Trading ahead of expectations AGM statement from Vertu, we no longer hold but this is good news for current holders. Note 15 Chinese outlets by October!
I understand Rachel from Accounts is mucking around with both Cash ISAS and Stock & Shares ISAS. Can we please have an update on that.? Cheers!
She's getting the elbow apparently. Whatever she does might get changed, regardless of what she implements.
I have doubts that anything she does or has done will get undone, she'll be around to take the blame for a long time.
I understand Rachel from Accounts is mucking around with both Cash ISAS and Stock & Shares ISAS. Can we please have an update on that.? Cheers!
Highlights:
In short - very little to see here. In particular, given the ability to utilize money market funds, this is unlikely to make much difference to stockmarket liquidity or change the inherent timidity of the average UK saver.
I'd also note that "Rachel from Accounts" is generally regarded as a misogynistic and condescending trope intended to demean and diminish the role of the first female Chancellor.
Not that she's likely to be Chancellor for much longer.
timarr
Very nice if interest in ISAs was "payable" at 22%! Sadly, I suspect you mean "taxable"
Very nice if interest in ISAs was "payable" at 22%! Sadly, I suspect you mean "taxable"
Correct - and corrected. Thanks!
timarr
Slightly ironic that only a few years back the government put pressure on the platforms to pay interest on uninvested cash deposits when previously it was common to get nothing. Seems they need not have bothered. As someone who tends to be fully invested it’s not really a big issue in and of itself personally. I do wonder whether the platforms will collect directly or it will be another responsibility come self-assessment.
But as some press articles have commented the real issue is with the precedent I.e. that the tax wrapper has essentially been pierced. How soon given the dreadful state of public finances will the new Chancellor be coming back for a solidarity 22% tax on ISA dividends. Terrible, terrible precedent in my view…
i think its much more an issue now that cash isas will be limited to 8k going forward - this is one of the "easier ways" to prevent abuse by people using stocks isa when their 8k cash amount is used up (next tax year ?)
ISAs will be capped at some point too - probably 100k or 250k cap would be my guess.
We are becoming a banana republic. So sad to see. Why don't we embrace low tax, low regulation, pro-growth, and promotion of individual responsibility. A small minority of working people are carrying the entire country on its shoulders. This will not end well
Agreed but one would think like pension there will be some form of protection certificates issued to anyone over the cap but the bottom line is like pensions it just makes the whole issue more complicated for raising really not a huge amount of money.
It was the FCA that put on the pressure on the platforms to pay interest on uninvested cash deposits - and while the FCA might technically be part of "Government" the thinking process (or lack of) and intended outcomes are totally different !
I can't agree timarr,
I'd also note that "Rachel from Accounts" is generally regarded as a misogynistic and condescending trope intended to demean and diminish the role of the first female Chancellor.
Reeves is no Margaret Thacher who could have taught her a thing or two about good housekeeping.
Silver
In principle taxing ISAs would be a big mistake. Need to encourage people to understand and use stocks and shares ISAs not make them more complex. She will definitely go but who knows whether the next one will try the same.
I would agree, but that is not what is being proposed.
They will be taxing the interest element that is earned in cash in an ISA, not income derived from an ISA. i.e. If you have £10,000 invested and then that delivers a return of £1,000 in cash and is not reinvested, and your ISA pays interest at say 4% (£40), you will be liable to pay 22% tax on that interest (£8.80).
Yeah understood I was commenting on the cash element as per the other discussions. Its principles for me, if you start taxing elements of ISAs what will future governments do.
About a breakfast for one sailor on HMS Target or whatever it’s called. Sorry Ken.
Well said Timarr
I'd also note that "Rachel from Accounts" is generally regarded as a misogynistic and condescending trope intended to demean and diminish the role of the first female Chancellor.
in what planet do you get this utter tripe ?
are you denying she faked her cv on linkedln
she couldnt even get her landlords licence correct - bearing in mind extra taxes levied on property owners its not a great look
she has published numerous planned tax and similar changes they have had to back track on later - its kinds unprofessional to set your stall out then change it soon after.
she has been worful at following "normal conevtions"
the chancellor has 2 dates per year at which time it is customary to update ref plans for tax changes - not its standard practice now to flag up changes following april in autumn budget so there is enough time to implement stuff - she has completely ignored how it should be done
eg she belatadly announced increase in mileage rate "last month" the normal convention is for stuff like that to be flagged up in october so hmrc can get their guidance updated in timely fashion - is it a coincidence this change was announced when starmer was fighting for his job ?
ditto reduced at rate on kids stuff - that shoudl have been flagged up
on the basis its a matter of fact she lied on her cv to pimp up her job role - how on earth can anyone argue if misogeny ? i dispute that genrally its agreed to be misogeny - its just the normal no nonsense stuff throw at politicians who are abjectly useless
i have misogeny but i am not having it here that theer is misogeny at play she gets the same (harsh?) treatment as otehr politicians imho - if she didnt want the "trope" she shouldnt have lied on her cv. Its matter of fact she went back and correct all the "lies" on her cv - do you think its likely that everything that she made look better than reality - was everything that she got wrong ?
Well said RMillaree, there is too much of this sort of comment and use of various isms to shutdown reasonable debate and comment on uncomfortable facts. The woman couldn't be trusted to run a bath in my humble opinion and I love women in general and capable women in particular. My late mother-in-law as a teenager, rode a motor-cycle as a fire-service messenger in WW2 and then joined the WRNS. Her feisty daughter carries on her spirit in spite of disabilities..
No fan of Reeves but i think this Rachel from Accounts thing is demeaning and should stop. Play the ball not the man.
So carrying on your topical football analogy, would it be mean, if she lied to get into the Lionesses team, to point out if she couldn't play football. Was her appointment as chancellor because she was a woman?
i understand that some will strongly disagree with what i say - i get that.
would you say its acceptable for someone to put on their cv that they were an ecomomist when their job role was clearly more clerical duties in nature (senior accounts manager) . imho i suspect if an employer found our staff member had lied in such manner they may have a good case for sacking them on the spot.
why do you think its unfair when someone lies about their title - she should be able to sidestep the consequences of "pimping it up" - is it not an actual fact that she was more rachel from accounts rather than what she said she was ? is that not actually the truth rather than her fake narrative?
from my point of view the ball here is her lies - and the truth is she was rachel from accounts (there is nothing wrong with being an accounts manager) - not rachel the economist
from my point of view i am very much playing the ball here - her lies and her pretending she wasnt rachel from accounts when she was.
Didn’t she have 14 years to prepare for government and being the Chancellor? You would have assumed that would been enough time to plan properly, get her ideas properly costed. “Pro-business, pro-growth” she told everyone and then after her first disastrous budget she claimed there would be no more tax rises, which was another lie. Only last year she called senior CEOs to a meeting and asked them for ideas on growth! She’s negligent and incompetent
I don't v think she was shadow chancellor for 14 years. She's only been in the Commons for 16 years.
I don't v think she was shadow chancellor for 14 years. She's only been in the Commons for 16 years.
huh - i dont think Paul said or indicated she had been shadow chancellor for 14 years did he? simply that she would have been preparing for the role for 14 years. Pauls comments look spot on to me - its all about the career progression path - the job has most certainly been on her radar for 14 years as far as i can see.
I think the nicknames just come with the job (whether that's right or not) regardless of male of female? If she was called equivalent of 'Dishy Rishi' there would be uproar! There was 'Spreadsheet Phil' Hammond which is probably similar. And, of course, Jeremy Hunt.
'
https://www.gov.uk/government/...
It reads to me as if income from money market funds will be taxable at 22%, but income from gilts will be tax free. So every few months I have to buy another short term gilt. End result: I pay the broker a bit more in commission. The Treasury gets nothing. What's the point?
Liontrust Asset Management (LON:LIO) will be interested in the team analysis. Green shoots among the weeds.
Me too Dr Dave. Profit warning or turnaround…. Or both!
Gear4Music G4M
The company announced it's FY2026 results yesterday. Revenue increased by 30%, Operating margin up to 6% and the company made a profit before tax of £10.3m, against a market cap of £56.6m.
To add to this, we got another “ahead” outlook for 2027, with revenue running at a double digit increase on last year. This is the 7th upgrade since early September 2025. You may be surprised to learn that during this period the share price has actually fallen! It sits on an historic PE ratio of below 8.
So what's going on here, I ask myself? To get the full picture, you may need to zoom out a bit on the share price chart. This is probably one of the most bizarre share price graphs you will ever come across. Two “sugar loaf mountains” sitting proudly side by side, and yes, I've travelled nearly every inch of them. Fortunately I bought low. I just kept forgetting to sell high! With a history like this, it's maybe not surprising that investors aren't rushing to join the company's latest reincarnation, but is the market ignoring a bargain sitting in plain sight?
Over the last couple of years, it does feel like things have changed. Two competitors in the UK and one in Holland went into administration and G4M has certainly benefitted from the new competitive environment to increase its market share. They're also investing in a new automated warehouse facility that will greatly increase their capacity and add to efficiency. This is a £10m capex that is being financed from cash flow and a revolving credit facility of £45m. The company has been able to out-compete its rivals and they are setting themselves up to widen the gap, in my opinion. This was always the story that made G4M an attractive long term bet, within a quite fragmented market. Add to that, the more disciplined approach to margins introduced over the last couple of years and maybe we are in the foothills of another glorious ascent!
I'm a bit surprised that Graham or Roland haven't taken a look at G4M in a while. I know Graham raised it to “Green” some time last year. Roland was waiting for a clearer view on 2027 momentum, which I think we have now. I’d be interested in any views out there.
'To add to this, we got another “ahead” outlook for 2027, with revenue running at a double digit increase on last year. This is the 7th upgrade since early September 2025.'
I agree this was a good update but I think this needs a qualification. They did say they're currently experiencing double digit revenue growth - which is positive versus the single digit market expectations - but they went onto say 'Trading in FY27 to date is in line with the board's expectations.' So I don't think it's quite correct to say this was the 7th upgrade.
The potential for an upgrade has got stronger though and I think the share price this year has indicated the market may have felt FY26 was a one-off, benefiting from the failed competitors and cheap stock it managed to acquire. It's good to see Gear4music (HOLDINGS) (LON:G4M) doing well again.
Pharos Energy (LON:PHAR) Bu**er! I was in and out a few days ago for no more than a round of drinks and now an offer has come in!!!!
Imagine if it was more than about an 8.5% premium though;-)
If it makes you feel any better I sold half my Legal & General (LON:LGEN) a few weeks back thinking they were top of trading range and I would be able to buy them back cheaper, plus thought the same with Natwest (LON:NWG) sold 80% and saw them put on 10% plus doh.
I think the lesson is keep 80% of your core monies invested no matter what (I'm talking ftse 100, ETF's and Investment Trusts) rebalance twice annually and keep 20% in money market/ultra short bond etf's to pounce in crashes.
Granted with single stocks especially ftse 250 and below you need to watch them as we have seen with Telecom Plus (LON:TEP) this week but with collectives such as etf's and investment trusts try and resist the urge to chop and range rarely works in my experience.
Is the heat getting to the Stocko servers? Doing some unusual stuff this morning. Doesn't want to access some pages.
Getting really frustrated with it !!!
Resorted to ADVFN ffs
The service has been unreliable since ported to Google Cloud (from memory) used to be fine when they hosted it themselves. I feel for the team it’s stressful when you have ongoing infrastructure issues affecting your application.
it’s a great platform Stocko it’s helped reform my investing style and become more profitable.