Daily Stock Market Report (Wed 25 June 2025) - LIO, ULTP, FTC, BBSN/CAU, MRK, SDG, GST

Good morning!
The Agenda is complete.
Spreadsheet accompanying this report: link.
We're finished for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Babcock International (LON:BAB) (£5.22bn) | Op profit +51% (£364m). £200m buyback. FY26: to hit adj. op margin 8% target one year early. | ||
ITM Power (LON:ITM) (£478m) | Launch of a German subsidiary that will build, own and operate hydrogen production plants. | ||
| Warehouse Reit (LON:WHR) (£454m) (also Tritax Big Box REIT (LON:BBOX) (£3.74bn)) | Recommended Acquisition of Warehouse REIT | Price per WHR share: 0.4236 new BBOX shares and 47.2p cash. Total value: 111p plus dividends. | PINK |
THG (LON:THG) (£406.8m) | Q2 much improved, as anticipated. Return to constant currency growth. Unch. FY25 guidance. | ||
Halfords (LON:HFD) (£376m) | Adj. PBT +6.4% (£38.4m). Early FY26 trading in line. Remain cautious on consumer spending. | ||
Filtronic (LON:FTC) (£339m) | Rev, EBITDA marginally ahead. Rev +120% (£56m). Strong position to meet FY26 exps. Forecasts at Cavendish for the current year (FY May 2026) are unchanged and suggest a small reduction in revenues (from £55m to £54m) and a larger percentage drop in adj. PBT (from £14.1m to £8.3m). These FY26 forecasts are still far ahead of FY24 performance, even if they don’t match FY25. We do not yet have forecasts for the following year. | AMBER/GREEN (Graham) [no section below] | |
Liontrust Asset Management (LON:LIO) (£262m) | Adj. PBT £48.3m (LY: £67.4m). Capital Allocation Policy (only 50% of EPS to be paid as a minimum). | AMBER/GREEN (Graham) Keeping a moderately positive stance on this due to its sheer cheapness, but there are still serious problems. Other fund manager stocks remain significantly more appealing than this one. | |
Hargreaves Services (LON:HSP) (£224m) | Revenue and PBT to be ahead of exps. Services Division: future years to also beat current exps. | ||
Vertu Motors (LON:VTU) (£202m) | FY26 anticipated in line. New car retail LfL volumes +7%, gaining mkt share. Used volumes -3.8%. | ||
Anglo Asian Mining (LON:AAZ) (£188m) | Momentum has continued to increase significantly. Demirli mine to start production in H2. | ||
Renold (LON:RNO) (£182m) | Italian manufacturer and distributor of transmission chain and ancillary products. €10m price. | ||
Duke Capital (LON:DUKE) (£148m) | Recurring rev +6% (£25.8m). Q1 FY26: £6.6m of recurring revenue expected, +4% year-on-year. | ||
Avingtrans (LON:AVG) (£139m) | Adj. EBITDA and Adj. PBT in line with recently upgraded market expectations. Net debt excl. IFRS16 £12.3m | ||
Marks Electrical (LON:MRK) (£66.1m) | Rev +2.6% to £117.2m. Adj. EPS -37% to 1.54p. Net Cash £8.8m (FY24: £7.8m). As we look ahead to the remainder of FY26, we anticipate improving revenue growth and higher gross margin than prior year, enabling us to reiterate our full year guidance. | AMBER/RED (Mark) [no section below] | |
Ultimate Products (LON:ULTP) (£64m) | Profits Warning. Four months to May 2025 Rev +3%, Adj EBITDA flat, impacted by lower order intake. H2 revenue now expected to be broadly flat = FY25 4% lower than FY24. adjusted EBITDA for FY25 to be around £12.5m (vs current consensus of £14.3m). Expects 2026 revenue to be lower than FY26. | BLACK (AMBER/RED) (Mark) | |
PROCOOK (LON:PROC) (£43.6m) | Revenue +11% to £69.5m, LFL revenue +5%. U/L Op profit +51% to £3.2m. Net cash £1m. 26Q1 revenue +13.7% (+2% LFL). “Beginning to deliver improved performance and we have both the opportunity and a clear plan to accelerate this further.” | ||
Brave Bison (LON:BBSN) (£41m) (also Centaur Media (LON:CAU) (£50m)) | Mini-MBA acquired from Centaur Media for £19m EV. expected to increase Brave Bison pro-forma net revenue by 43% to £36.5 million and Adjusted EBITDA by 80% to £8.1 million. £13.5m placing (29.3% of enlarged share capital at 2.45p). | AMBER/GREEN (Mark - I hold Centaur) | |
Sanderson Design (LON:SDG) (£32.8m) | “…continues to trade in line with the Board's expectations for the full year.” Retail launch of the Highgrove by Sanderson very well received. Licensing continues to perform well - strong u/l revenue growth from previously signed agreements. New licensing agreements signed during the year-to-date. Manufacturing on track to achieve around break-even for the current FY, plus further cost-saving measures. Planned inventory reduction means net cash position is beginning to build. | AMBER/GREEN (Mark - I hold) | |
GSTechnologies (LON:GST) (£24m) | “The Treasury Policy allows for a significant proportion of the cash resources of the Company, as determined by the GST directors from time to time, to be held in Bitcoin.” | RED (Graham) [no section below] RED might be a harsh stance without having done in-depth research, but this one is categorised as a Sucker Stock and I think all companies joining the "bitcoin treasury policy" bandwagon should be treated with great caution. Bitcoin may be many things but GST justifies its new policy by saying that it is "a reliable store of value". | |
Various Eateries (LON:VARE) (£22.8m) | H1 Rev +9% to £24.7m, LFL sales flat, Adj. EBITDA £0.1m (24H1: -£1.3m), Net Cash £2.9m (24H1: £4.2m). Post-period LFL sales +7%. “The Group is trading in line with market expectations for the full year.” | ||
Tissue Regenix (LON:TRX) (£21.8m) | Rev +9%, Adj. EBOTDA $1.9m (FY23: $0.7m), Cash $1.9m (FY23: $4.7m). | ||
Velocity Composites (LON:VEL) (£16.2m) | Rev -3% to £10.4m, Adj. EBITDA £0.3m (FY24: -£0.2m), Net Cash £0.4m (FY24: £0.6m). “expects to achieve positive adjusted EBITDA and be cash generative in H2 FY25 - in line with current market expectations.” | ||
Pri0r1ty Intelligence (LON:PR1) (£12m) | “...applied to the OTC Markets Group for its Ordinary shares to be cross-traded publicly on the OTCQB Market in the United States.” | ||
Kelso group (LON:KLSO) (£10.7m) | Holds 5 investments. Since 23rd April 2025, The Works: +185.0%, Angling Direct: +34.3%, Selkirk: +19.7%, NCC +4.1%, THG flat. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Down 7% to 381p (£243m) - Annual Financial Report - Graham - AMBER/GREEN
Liontrust Asset Management Plc ("Liontrust", the "Company", or the "Group"), the independent fund management group, today announces its Full Year Report for the financial year ended 31 March 2025.
I last covered this fund manager in April, when we learned that the company had suffered net outflows of £1.3bn in Q4 of its financial year (to March).
We also learned that its AuMA had continued to fall since the end of March, down another 4% to £21.6bn. That was when tariff-related fears were at their worst.
As you’d expect, there has been a bounce since then, with AuMA back up to £22.7bn as of 17th June. So AuMA is back where it started this financial year.
These full-year results show adj. PBT of £48.3m and actual PBT of £22.3m.
Before going any further, let’s check if the adjustments are reasonable.
Last year, adjusted PBT was £67m, but there were £68m of adjustments. I was quite critical of these adjustments: here’s my analysis from last year.
This year, we have £26m of adjustments. At least it’s an improvement on last year!
The main item is £12m of spending on the “Business Transformation Programme”. There is also nearly £10m of intangible amortisation.
I’m happy for the amortisation to be adjusted out, which makes sense if we treat its intangibles as already being worthless. The latest balance sheet has net assets of £138m, or £66m if we exclude all intangibles. So roughly speaking, that’s the balance sheet support.
However, I’m not willing to look past the costs of the “Business Transformation Programme”. I’m consistent on this when I look at companies in general: I’m not willing to ignore the costs of changing how they do business, because companies are often changing how they do business, so it’s not a one-off cost.
The BTP cost £12m in FY25, and nearly £6m in FY24.
Here’s what the Chair said on the topic, so you can decide for yourself if you’d be willing to treat these costs as one-off:
The Group has also been engaged in a business transformation programme designed to overhaul Liontrust's operating model. This includes implementing BlackRock's Aladdin platform; a Middle-Office operating model with BNY; BNY Front Office Services; and a new enterprise data platform - BNY Data Vault. The Group also outsourced factsheet and regulatory reporting in 2024 and has been finalising the outsourcing of trading for investment funds and institutional accounts to BNY's Buyside Trading Solutions service. These changes are strengthening data management, delivery and analysis across the business while also providing operational and cost efficiencies.
Remember that actual PBT for the year was £22m. With the adjustments, PBT rises to £48m.
I’m willing to add back in the intangible amortisation. So for me, the “real” PBT figure is £32m. We could perhaps allow a portion of the BTP spending to be treated as one-off, depending on how much benefit of the doubt we are willing to give, which could bring adj. PBT closer to £40m.
Dividends
The company is paying out 72p for FY March 2025, which is significantly higher than adjusted EPS (56.8p) and far higher than actual EPS (26p).
As it’s not sustainable to pay out like this, the company announces a “Capital Allocation Policy”.
As part of the new CAP, our dividend policy has been updated to reflect a disciplined approach to capital management, targeting a sustainable dividend funded by current earnings. As such, Liontrust's dividend policy will be to pay a minimum of a 50% of Adjusted diluted EPS in ordinary dividends, to be paid to shareholders following the publication of the Company's Half Year and Annual results.
If this had applied to the current year, Liontrust would only have been obliged to pay out 28.4p.
There is also a pledge to buy back shares with excess capital “when it makes economic sense to do so”.
Outlook
The outlook statement doesn’t seem to acknowledge the problems facing the business. They just experienced nearly £5bn of outflows, or c. 18% of starting AUM, and this is what they say:
Liontrust continues to build on the strong foundations of the business by executing our four strategic objectives…
Our investment strategies have maintained their strong reputation and independent recognition, and we are broadening our offering, including in alternatives for which we believe there will be strong demand.
This impressive progress in the development of the business to achieve our four strategic objectives puts Liontrust in a very strong position to take advantage of the opportunities for active asset managers. Our brand, communications, distribution, operating model and strong capital position will enable Liontrust to deliver growth.
Would it not be more reassuring if they admitted how badly they were doing?
Graham’s view
I’ve been pretty clear for a while that I don’t rate Liontrust very highly against other fund managers. Their strategy, competitive positioning and even their commentary on their own performance - none of it fills me with confidence.
Despite this, I’ve stuck with my AMBER/GREEN stance for a while, due to the extraordinary cheapness of the stock against its historical norms.
Investors at the current share price get £93 of AuMA for every £1 invested in the stock.
Stockopedia categorises it as “Contrarian”, offering quality and value but without momentum.
Note, however, that the dividend yield shown below will not be paid on an ongoing basis. The real yield might be in the region of 5-7%.
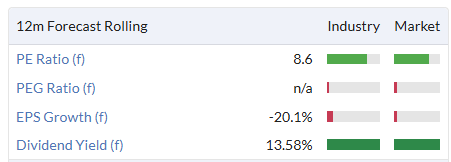
I’m reluctantly going to stay AMBER/GREEN on this as despite the negatives, it does still offer some attractions. I admit that these attractions are based on the numbers, not on the quality of the business.
Balance sheet strength, for example, which is a legal requirement: Liontrust has £75m of working capital.
And even at the lower payout ratio, the dividend yield should still be useful, with the potential for cash to also be set aside for buybacks and other opportunities. The share count should start to go down rather than up.
I’m AMBER/GREEN because the numbers still seem to justify this, even if the quality of the business and its strategy don’t. Out of all the fund managers I’ve studied, this is the one that I think is most badly in need of a change in leadership.
Mark's Section
Ultimate Products (LON:ULTP)
Down 30% to 50p - Trading Update - Mark - BLACK/AMBER/RED
As is often the case, the word “now” reveals that this is bad news:
As a result, H2 revenues are now expected to be broadly flat vs H2 FY24, with FY25 revenue expected to be approximately 4% lower than last year.
Which they helpfully quantify at the EBITDA level:
Accordingly, the Board expects adjusted EBITDA for FY25 to be around £12.5m (versus current consensus of £14.3m).
The reasons given are:
A weighting towards lower margin product categories and sales channels
Lower order intake, with orders deferred from Q4 FY25 to Q1 FY26.
The shares had been recovering recently, presumably on the expectation that the company would benefit from lower freight rates:
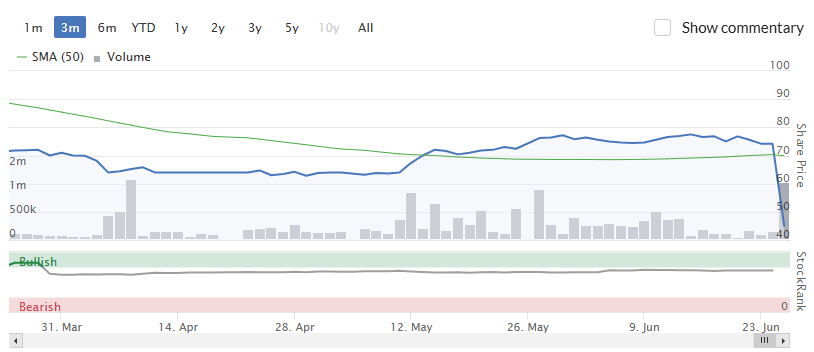
This is confirmed in today’s update, but is not enough to overcome the weakness in sales and mix.
Forecast Changes:
The real kicker is that this is a multiyear warning as they also say:
Looking ahead to FY26, the current order book indicates a slow start to the year (currently down 7.5% vs this time last year). Given the current trading environment, the Board therefore believes it is prudent to expect FY26 revenue to be lower than FY25, at a level broadly in line with the current order book position.
Previously they had been expecting a boost to sales and a recovery in EPS, as the table they provide of the consensus prior to today’s update shows:
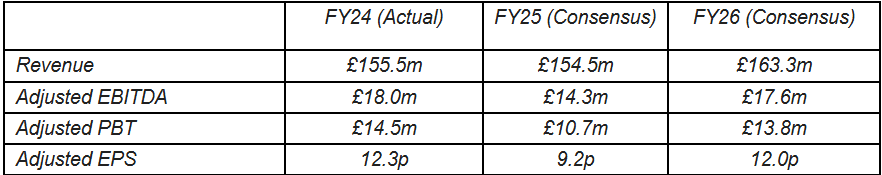
Strangely for a company of this size which has issued very few shares over the years, they have four brokers covering them. So, I can build a new consensus quite easily:
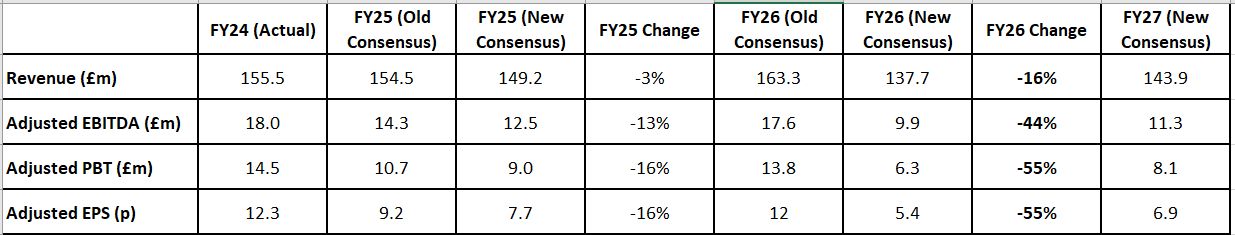
I’ve highlighted the FY26 change here, as the RNS doesn’t give specific figures. Despite them saying orders have been delayed into FY26, revenue is now forecast to be 16% lower, and EPS drops by a whopping 55% versus previous expectations. The FY27 consensus is only Cavendish, who were the only one of the four to look that far ahead. Even here, the recovery is modest by historical standards and still significantly below 2024 actuals.
Net Debt, Dividends & Buybacks:
The bad news keeps coming. While the brokers vary slightly in their modelling of net debt, the consensus is mostly for net debt to be a little worse in FY25 and a little better than previously forecast in FY26 due to lower working capital on lower trading. However, the lower forecast EBITDA means that net debt to EBITDA soars. I’ve taken Cavendish’s figures here as they’ve done the calculation for me!
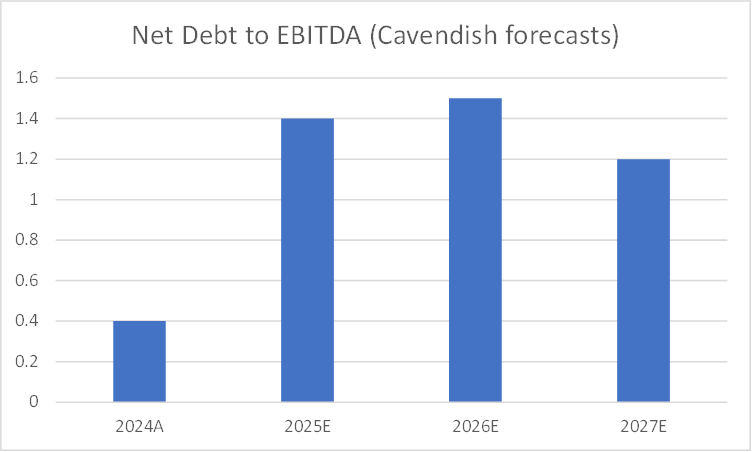
While this isn’t such a high figure that would imperil the company’s existence, the current capital allocation policy is to target net debt to EBITDA of 1.0 and only buy back shares below this figure. This means that, under the current policy, we can expect no share buybacks for the next few years. Indeed, this drop shows the folly of this type of policy - they were recently buying back shares in the high-70 pence range, and will not buy back shares no matter how low they go over the next few years.
The dividend payout is also a victim of the current weak trading and higher net debt ratio. Canaccord, for example, cut FY25 estimates from 4.7p to 3.8p and FY26 from 6.2p to just 2.6p. What was a potentially very good income stock for investors, has a more modest (in current UK markets) yield of 5% at current prices.
Strategy:
Finally, one has to question the strategy here. There has been a shift in management roles, with Andy Gossage taking the CEO role. His skillset is much more aligned to scaling a branded business. Indeed, they say in the RNS:
In recent years the Group has delivered substantial improvements to its branding, product development and operational performance, including the deployment of robotic automation, AI and process change. The Group's focus now is on replicating those improvements within the sales function, with a number of initiatives underway which the Board is confident have the potential to deliver a significant improvement in the Group's financial performance.
However, so far this strategy has failed to generate the sales growth necessary to offset the increased costs of implementation. The jury is out as to whether this is a strategic misstep or whether it is just taking longer to bear fruit.
Valuation:
At around 50p, this is on 9.3x 2026 earnings. This isn’t crazy, but not particularly cheap for a forward multiple in the current markets. This looks worse on an EV value and rises to around 12x. If we take Cavendish’s stab in the dark for FY27, then things look better at around 7x earnings or 10x debt-adjusting. Buying on this basis is largely a statement of faith. On an asset basis, the company still trades on around 2x Tangible Book Value. While this metric doesn’t mean it is necessarily overvalued, it will not provide any support if trading should deteriorate further. The 5% forecast yield is reasonable, but as already described, there will be no buybacks with current debt levels.
Mark’s View
There is no getting around that this is a stinker of a warning. The downgrades to FY26 are severe, and impact the company on a number of levels. There are a lot of fans of this company for its straight-talking management and willingness to engage with investors. While it may be that a strong recovery is on the cards in better consumer conditions, this is a fair way in the future. I’m not convinced that basing an investment case on a strong recovery far out in the future is a great one. Especially as we have now had three profits warnings and there are questions over the recent strategic shifts within the business. Roland rated this AMBER/GREEN for the recovery potential after the last warning. However, with that recovery seemingly now very far in the future, I think this may be now and AMBER/RED.
Brave Bison (LON:BBSN) / Centaur Media (LON:CAU)
Acquisition of MiniMBA - Mark (I hold Centaur) - AMBER/GREEN
This deal was well known with Sky News breaking this as a rumour in early May, which was subsequently confirmed by RNS from both companies. Last week the exclusivity was extended by 7 days, which suggested it was a done deal, as it has proven today. The details are as expected with £19m paid on an EV-basis.
Long-term this looks to be one of those rare sales where both parties are getting a good deal. Centaur get cash, which simplifies their business and enables them to maximise value from the rest and return cash, as major shareholder Harwood is no doubt pushing for. Brave Bison gets a business they can grow and has cross-selling synergies with the rest of their business. They presented at the Mello investment conference recently and the story of development they had and cross-selling opportunities was quite impressive. This must have captured other investors too as the price has been strong recently:
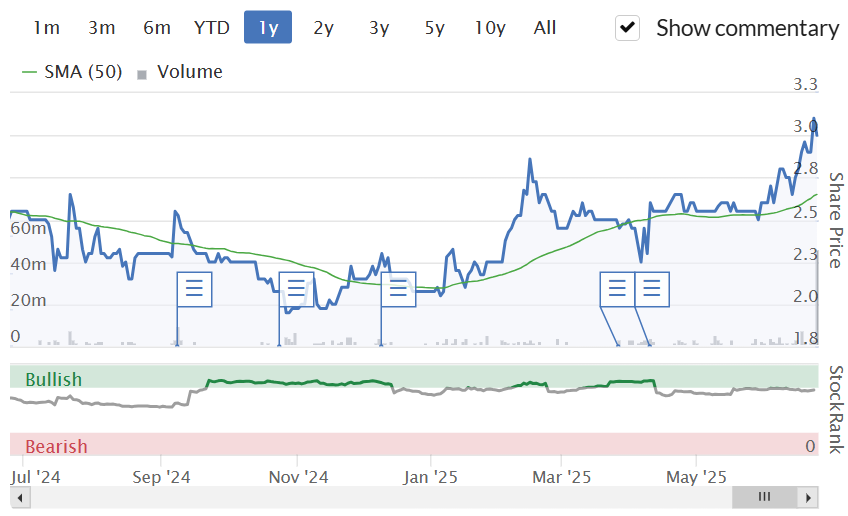
What put me off investing was the uncertainty over the financing of the deal. It seemed to me that there would have to be an equity component, and this has been borne out with today:
Brave Bison will partly finance the cash consideration for the Acquisition through a placing and direct subscription of 27,615,467 new Ordinary Shares at a price of 49 pence per Ordinary Share (on a post-Share Consolidation basis) (the "Issue Price") to raise gross proceeds of approximately £13.5 million (the "Fundraising")
· Issue price (prior to the Share Consolidation) of 2.45 pence represents a discount of 4% to the mid-market closing price of 2.55 pence on 8 May 2025, being the last trading day before the potential Acquisition was announced.
The scale of the raise exceeds what I was expecting and the price is marginally worse. I’m surprised that the shares haven’t reacted more negatively to this today. After all, any institutions or HNWs that wanted increased exposure here could have bought at 2.45p in the placing, so why buy today at 3p?
One of the most impressive parts of this deal is that Mini-MBA founder Mark Ritson has put £4m of his own money into Brave Bison equity (or at least he will have over the next two years). As far as I am aware, he had no equity in the previous owner Centaur Media.
In terms of the impact on financials, this is what Brave Bison say:
The Acquisition of MiniMBA is expected to increase Brave Bison pro-forma net revenue by 43% to £36.5 million and Adjusted EBITDA by 80% to £8.1 million. Post-completion, 47% of operating profits (before central costs) will be derived from repeatable, non-cyclical, high-margin income from the monetisation of digital content, with the balance generated from marketing & technology services.
However, the dilutive impact of the raise makes the EPS changes much less impressive. Cavendish are forecasting EPS (prior to the upcoming share consolidation) to rise to 0.31p in FY25. This is up from 0.28p last year making around 10% EPS growth. This makes the P/E of around 9 still look good value. However, it is worth noting that when I last reviewed this on the DSMR the P/E was 8x and the company was forecast to have more net cash. So the rating here has increased. This is probably justified by the improving outlook from this and recent deals.
In the event that the mid-market closing price per Ordinary Share exceeds 3.0 pence on the date(s) of redemption(s), the B Shares will be capable of redemption by the LTIP Executives at any time with an aggregate value (the Redemption Value") equal to 15% of value created for the Company’s shareholders from the adoption of the LTIP to redemption(s) of the B Shares...
The total awards are limited to 12.5% of the Company’s issued ordinary share capital, but this could still be significant dilution. When the shares were trading at 2p, this wasn’t really an issue. However, with the shares starting to trade around the point where the LTIP kicks in, this should start to be considered in any valuation.
Centaur
On the other side of the deal:
Following Completion, it is the Board's intention to use the net proceeds from the Transaction to return capital to shareholders and will consult with shareholders before deciding how the proceeds will be returned. The quantum, timing and form of any such return of capital shall be at the discretion of the Board…Further details of the Capital Return (including the quantum, timing and form) will be announced in due course.
Apart from the use of the unnecessarily pretentious “quantum” instead of “size”, this is as expected. No doubt the return will be made in the form that major shareholders, Harwood and Aberforth, prefer:
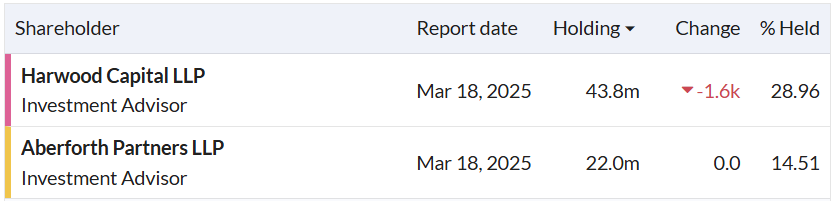
It was actually Christopher Mills’ enthusiasm for Centaur at Mello that persuaded me to take a small position here. Following completion, Centaur will have £27m cash, for a £23m EV at 34p. The Lawyer is clearly the high value asset here:
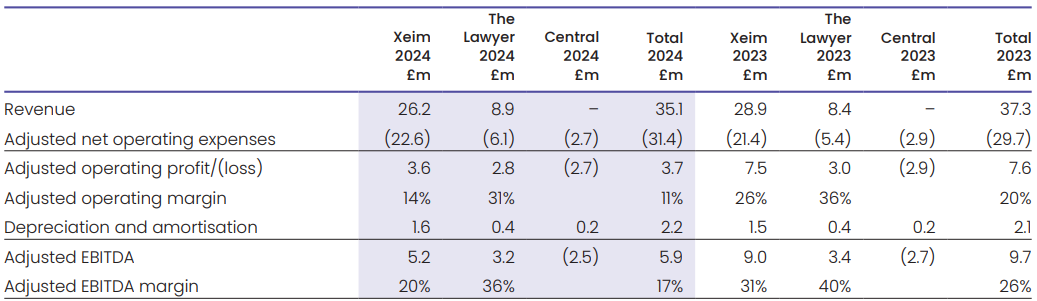
Given its moat and cash generation, they must hope to get around 10xEBITDA or more for this. The read through is that the rest of “Xiem” excluding mini-MBA must generate around £0.8m EBITDA, but will probably not fetch a high multiple. Still, that suggests upside from here. The big problem is the central costs. How quickly the company can get a good price for the remaining assets and how easily they can slash those costs are central to the investment case here. I’m sure Harwood will be pushing hard on both fronts, though.
Mark’s View
Brave Bison: Although the rating has gone up a bit since I last reviewed it on the DSMR, so has the potential upside from recent deals. I am a little cautious that the execution risk has also increased and that we are nearing the share price level where options dilution may kick in. Plus the shares may come under pressure in the short-term due to the placing price now being someway below yesterday’s close. However, on a long-term view I like the potential, especially the shift to more recurring revenue in a highly competitive industry. So am happy to keep the AMBER/GREEN rating.
Centaur: As a trading company, without mini-MBA and based on last year’s EPS downgrades, this would be an AMBER at best. However, with the end in sight for value realisation, I think it deserves a slightly more positive view. Until The Lawyer is sold, we won’t know if it truly is a valuable, high-multiple business. Plus the central costs will be an increasing weight until all sales (or closures) are concluded. However, with Christopher Mills pushing on both fronts behind the scenes, I think the chances of a positive outcome form the current price are high. So I’ll go for AMBER/GREEN as a special situation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Nice 4.7% move today from Foresight group (LON:FSG) ahead of earnings release tomorrow. Hopefully someone knows something that I don't! I hold - in eager anticipation
Thanks for the heads-up. Not seen the oddly named Foresight before. In hindsight since 2021 it seems to bobble between 360-460p and back again regardless of revenue growth and stable margin. Wondering if that's the foresight plan in the prospectus?
Foresight group (LON:FSG) It has been between 300 and 549p in the last year, not sure what chart you are looking at. Also pays out over 6% dividend.
Could be a good one to buy around 320p, dividend will be higher then,
Portfolio thoughts:
The negatives:
Ultimate Products (LON:ULTP) I certainly called that wrong! The investment theses was I think correct. Reduced shipping costs, strong £/$ exchange rate making imports from China, which to my knowledge are priced in $ cheaper, share buy back, decent balance sheet etc. However the decision to buy at 75p was clearly a mistake. I exited at 50p as there are in my view better risk/reward shares available in UK small caps. Fortunately it was a relatively small position.
The positives
Hargreaves Services (LON:HSP) Surprisingly good update. Services and Raw Materials trading ahead with Land steady and progress with the intended sale of renewable energy land assets, the first tranche of which is expected to complete this year. A top five holding.
Avingtrans (LON:AVG) Very nice update confirming the previous 'ahead' trading update. My largest holding, with a blended purchase price of around 220p. More than happy to continue to hold. A very competent management team who know how to sell and how to buy. The Advanced Engineering Services Division has significant exposure to 'nuclear', which is flavour of the month, at present anyway.
No guarantees, but I wouldn't bet against the 'two Steves' successfully commercialising Adaptix (portable 3D X-ray) and Magnetica (portable helium free MRI scanner)
Van Elle Holdings (LON:VANL) I sound like a broken record, but the share price continues to tick up. Up 15% or thereabouts in the last week, despite the recent profit warning. Why? Wish I knew, perhaps Richard Staveley and Peter Gyllenhammer do? Currently around 45p to buy on increased volume. A sizeable holding for me.
All in all despite dropping the ball with my purchase of Ultimate Products, the portfolio continues to make progress, thanks in large part to good fortune and a fair bit of research, which doesn't always 'read the tea leaves' correctly.
All the best
It's been interesting to read everyone's comments on Ultimate products, especially Mark's analysis but having had success with it once before and as a dedicated bottom fisher, we opened a small position this morning at 51.80p. We also added to a losing position in Sanderson design. I can see heads shaking now! Thank you Mark ,Amber Red is clear enough warning. We also hold Centaur Media.
Having real world experience of working on similar 'Business Transformation Programme's', most recently spending 2 years on one, these very rarely deliver any tangible benefits to the business.
They usually come about by either a new head of department coming in and recommending all kinds of changes, and/or as a CV boosting exercise.
To spend £12m on changing a trading system, a data management system and outsourcing some other functions is verging on daylight robbery! I believe Alpha consulting did very well out of it!
I would be very wary of the quality of what other decisions the management of Liontrust Asset Management (LON:LIO) may make down the line.
Sorry that was my alter ego commenting on PROCOOK (LON:PROC) which is making a real and imaginary bowl....
I thought amber/greens a bit generous for Liontrust Asset Management (LON:LIO) - still seeing huge outflows, funds performing poorly and not that cheap on downgrades EPS figures. I personally wouldn't value fund managers with reference to AUM as it doesn't factor in the margins of that AUM (eg if a fund manager has low fees and/or high running costs then it won't necessarily deliver much profit).
I personally wouldn't value fund managers with reference to AUM as it doesn't factor in the margins of that AUM (eg if a fund manager has low fees and/or high running costs then it won't necessarily deliver much profit).
At this point the question is perhaps whether someone else fancies they can do a better job than the existing management. Take over the funds, ditch the management, all of the backroom staff and technology ... sadly there's probably not much in the way of brand equity here.
timarr
The problem is that AUM can disappear very quickly, especially if the managers get taken over and replaced by a new team - so from a buyer's perspective you're not buying anything tangible that has permanent value.
RE: Liontrust Asset Management (LON:LIO)
The problem is that AUM can disappear very quickly, especially if the managers get taken over and replaced by a new team - so from a buyer's perspective you're not buying anything tangible that has permanent value.
Hostile takeovers in the fund management industry aren't common because of the reason you've given - however, given the dire performance I very much doubt there are many investors who are with LIO because of their management teams. Inertia is the most likely factor, and someone with a better track record (which is - frankly - anyone) might well be attractive to that particular demographic.
The UK fund management sector is full of cheap companies, and the most likely time for M&A is as the market recovers but before that's reflected in fund figures. So if it's going to happen it will likely be soon.
timarr
But - In some cases there is both brand loyalty and inertia. Just look at Fundsmith - high fees and dismal performance over the last few years yet there's still over £24b held in the fund
But - In some cases there is both brand loyalty and inertia. Just look at Fundsmith - high fees and dismal performance over the last few years yet there's still over £24b held in the fund
From a high base, of course. If you were around Stocko in the last years of the last decade you may remember that anyone daring to suggest Fundsmith, Buffetology or Lindsell Train were catching a mighty tailwind from generationally low interest rates was considered - to put it kindly - an idiot who didn't know what they were talking about, when it was perfectly obvious the managers of these companies were staggering geniuses, who could never possibly put a foot wrong.
Still, Fundsmith and LT have a distinct style which hasn't really changed (frankly I have no idea what Buffetology's style is) so you roughly know what you're investing in. And yes, there's considerable loyalty, especially from longer term holders who've still done very well despite years of underperformance.
By and large all active management firms have done poorly against the market indexes in the last five years. In large part that's because of the skew towards the US and the Mag7 which hasn't left a lot of room for smart people to get ahead. As always investors decided that the latest trend was a permanent feature of the market and piled in and are now reverse ferreting while waiting for the next trend to jump onto. Hopefully UK mid and small caps, but who knows? Lots of money going into defence companies, for sure.
Anyway, poorly performing active management firms are two a penny. In that undistinguished company Liontrust Asset Management (LON:LIO) manages to stand out without giving the slightest hat-tip of acknowledgement to long suffering shareholders. I'm probably delusional in thinking this might get bid for, but that's confirmation bias for you ...
timarr
In my extensive experience with Liontrust Asset Management as a NED in a highly successful company, in which they held a major stake, I found the range of competence from very astute to downright arrogant and ignorant one has to deal with alarming. Enough said.
Bizarrely up 4% shortly after opening, now down 5% on the opening price. Yet the report suggests they're ahead and making good progress.
Who?
You follow the line up, look, you'v e got one too.
How to interpret Liontrust Asset Management (LON:LIO) new capital allocation policy announced today. They say they will distribute at least 50% of EPS as dividends and return further suplus as share buy backs.
Should it be read as a gentle introduction to a pending dividend cut? The enormous historic yield (17% plus) flags that the markets beleive this to be a sure fire case. On the other hand, share repurchases might be suggesting that the directors see the current share price is a bargain.
Not sure if today's RNS is overall positive or negative!
Ultimate Products (LON:ULTP) - 3rd profit warning from this branded homewares business...an air fryer hangover! The FY26 outlook seems to have spooked the market. It's still a pretty good company, so maybe all the bad news is now in the price, with expectations lowered? One to watch. Unfortunately, I still hold.
I bought a small number of shares recently on the rationale that sales growth would increase albeit modestly in 2025 and 2026 - a contrarian approach. I actually thought the brands would be reasonably defensive given their prevalence in dollar type stores. A warning sign for the macro economy. Quality metrics are good but of no use if the top line has stalled. I will await graham's comment but I may bail out. Analysts remain quite positive strangely.
Me too, that's what I did, having sold my previous holding on a peak.
'It's still a pretty good company'.
I am less sure. Because:
* It's basically a marketing business given they just source products and stick a name and branding on them. The brand names like Salter are doing a lot of heavy lifting. And, as someone working in marketing, I am not convinced the recent marketing rebrands are particularly inspiring or clear in who they're trying to target either e.g.: https://beldray.com/?srsltid=A...
* Anyone with a Which? subscription should check out the product reviews. I place more weight on Which? reviews as they're independent (they don't get sent products from manufacturers) and thorough versus user-led Amazon reviews. E.g. a couple of Beldray vacuums are described as 'don't buys' with Which? noting model BEL0776PURWK is 'dreadful' at cleaning. The BEL01982 iron is described as 'bog standard' and 'slippery' which could be a problem. My favourite: the Retro 4-EK5739PNK family toaster doesn't fit medium sized bread (oops).
* Several other consumer companies over the last few months are reporting revenue steadying or improving now. Why not Ultimate Products (LON:ULTP)?
* It's occupying the cheaper end of the spectrum. If their products aren't particularly innovative, or well rated, then it just risks getting undercut on price by e.g. Temu. I am starting to wonder if it's about to become the latest victim of Chinese direct-to-consumer companies?
On the plus side it's still making some profit rather than losses, and the business model allows it to quickly adapt to trends and source products to take advantage of booms in e.g. air fryers. I did hold a small portion of shares this morning for those reasons and for the potential upside. However, after today's update I've sold out and will sit on the sidelines until there's clearer evidence of a turnaround and in case there's something fundamentally wrong with the company.
Even the CFO isn't feeling particularly inspired! ' on 25 June 2025, Chris Dent, Chief Financial Officer, purchased 1,992 ordinary shares of 0.25p each ("Ordinary Shares") in the Company at a price of 50.1778 pence per Ordinary Share'
Blimey ULTP down 40% (i don't hold)
Probably justified though - looks a pretty miserable update with no sign of any recovery on the horizon.
I guess we won't be buying any shares now untill the morning of the trading statement and even going so far as to sell the day before it.
It’s recovered a bit since the bell, but still seems somewhat overdone, given a 12.5% profit miss and a lot of potential downside already priced in. Possibly private investors losing patience.
Yes but forecasts for next year have been slashed from 12.4p to 5.2p (looking a the Canacord note) - that's the worrying thing and the reason I got out first thing - thankfully only a small position!
I think the biggest problem is that they stated in the interims that things were getting better and they'd hit forecast. They obviously didn't, and it's as much now a confidence in management issue as the actual reduction. On value grounds it still looks relatively ok, so I'm keeping my small holding, but certainly not buying any more until there are signs of recovery.
Re ULTP
I think that the share price reaction is because it appears to be broadly the same reason for the profit warning as the last time - customers deferring orders. There will be some concern that more deferrals are not one offs but a new normal level of trading for the company.
The company has spent quite a bit of effort re-branding the products, which might be a redesigned product in a new box. This is fine if this has been identified as the best way to increase sales. In a premium brand, presentation is very important, in a budget brand, it is probably more the cost of the product. This strategy needs more explanation.
I would guess that ULTPs main problem is that it is being squeezed by other budget brands and aggressive pricing of the likes of Curry's who will be offering better brands.
Be interesting the see the read across here to the retailers that ULTP supply. I would guess that some of these are also finding it tough at the moment.
I see that the company has scheduled an investor webinar. I saw the one of previous webinars and thought it it could be improved. It was a bit wordy, and in my view lacked the key answers for investors.
I don't hold but ULTP is one of the shares that keep in view to get a feel for the retail environment.
A lot of their brands are located in discount stores so a worrying signpost for the retail environment.
Re ULTP
Yes, they supply some of discounters. With the last profit warning, I speculated that there might some read across to B&M. Though it has to be said that B&M seem to be stocking more products from other suppliers.
I don't think that they supply Home Bargains who have in the last year increased their electricals range via Pifco. I don't know for sure, but I suspect that HB might have some connection with the Pifco brand?
One of the comments was consumers were switching to even more discounted brands. Analysts seem quite positive long term.
Hi all - lots of chat on Ultimate Products today - for those interested, check out the Equity Development website for a new (freely accessible) research report with new forecasts that came out pre-market open this morning.
We are also hosting a webinar with management this 2.30pm with live Q&A if you'd like to register to attend - all are welcome!
As a holder of PROCOOK (LON:PROC) I'm interested in your thoughts. It was one of the stocks covered in Ed's recent article about three simple rules that would have captured a 36% Post Earnings Announcement Drift this year. Unless I've missed something, it doesn't look like this has been covered since 2023 when it was loss-making but it is now seeing growing revenue and has started to be profitable.
I like their shops. Not much free float tho, only 13%, looks to have a huge family ownership
UK's Warehouse REIT Warehouse Reit (LON:WHR) agreed to a 485.2 million-pound takeover by Tritax Big Box REIT Tritax Big Box REIT (LON:BBOX) rejecting Blackstone's BX.N 470 million-pound offer, which it had accepted in early June.
Implied price/share 114.2p (based on 47.2p cash + 0.4236 BBOX shares at 150.6p) versus Blackstones previous offer of 110.6p (including 1.6p divi)
As a long term BBOX and in the end a short term WHR holder - would have been long term holder but sold after the first bids came in - pretty happy with this news. I get to continue to be a long term holder of two businesses I rate and want to have in my portfolio. Surprised with the way REITs are flying off of the table no one has put in public offers for BBOX. Would bet they have had some enquiries behind the scenes...
Positive for Tritax Big Box REIT (LON:BBOX) (I hold) in my opinion. Blackstone could come back as the bbox bid is just under the last nav announced by whrw.
If it goes through BBOX say there will be savings of £5.5m .
Inevitable that Tritax Big Box REIT (LON:BBOX) come in with offer of 114.2p! I sold at 108.2p following Blackstone offer. thought I had made a good decision when Blackstone suggested due diligence meant not keen to pay 110p and Warehouse Reit (LON:WHR) price dropped to 95p but no wrong again!! 108p +1.6p dividend not a huge huge difference vs 114.2p but worth a few hundred £.
I must say I’m delighted that Tritax taking Warehouse means that these assets will remain listed on the UK market and not siphoned off into Blackstone.
Disappointing to see no upgrade to FY26 expectations at Filtronic (LON:FTC) today. Seems odd but perhaps the operational expansion is coming at significant cost, keeping profits down? Either way, it's now on a p/e of 52, which seems quite high but perhaps warranted?
Filtronic (LON:FTC) serially under promise and over deliver. The brief Cavendish note today sums it up. They say they expect "strong revenue growth over the next 2-5 years" but also leave the 26 forecast unchanged, so are actually forecasting revenues to decline next year. I suspect we will see multiple trading ahead statements over the next 12 months.
You hold perchance? It strikes me as a good quality company, which has grown rapidly in recent years, but I don’t see anything to suggest that that level of growth must continue. In fact I would suggest a period of consolidation seems likely. Its shares are, to put it mildly, fully priced, seemingly expecting significant outperformance. It will be interesting to see the reaction if that doesn’t happen.