Daily Stock Market Report (Wed 3rd December 2025) - G4M, ZIG, BMY, SPI, PAG

Good morning!
Today's report is now complete - thank you for reading and commenting. We'll be back in the morning!
Spreadsheet accompanying this report: link (last updated to: 10th November).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
| Smiths (LON:SMIN) (£7.9bn | SR75) | Sale of Smiths Detection | Agreed sale to CVC (private equity) for £2.0bn, equivalent to 16.3x FY25 adj operating profit of £122m. | |
Big Yellow (LON:BYG) (£2.1bn | SR55) | Budget changes mean that BYG expects its annual property rates will increase by £1.8m or 8.5% to £22.9m. Notes that this may be reduced following ongoing rateable value appeals. | PINK | |
Greencoat UK Wind (LON:UKW) (£2.1bn | SR n/a) | UKW Investment Mgr Schroders Greencoat responds, highlighting potential disadvantages of current RO proposals and its opposition to the options being proposed. | ||
Paragon Banking (LON:PAG) (£1.64bn | SR82) | Pre-tax profit +1.1% to £256.5m, with adj EPS +8.5% to 109.7p (Stocko consensus: 104.5p) RoTE stable at 17.5%. Impairment charges +71% to £41.9m (FY24: £24.5m), mainly due to underperforming pre-2022 property development loans. | AMBER ↓ (Roland) Today’s results look fairly decent, as I hoped when I took a fairly positive view on the interim results in June. However, today’s results have highlighted a couple of headwinds that could put pressure on profitability over the coming year. Are the shares cheap enough to reflect this risk? Today’s results show tangible net asset value up by 7% to 655p. At 798p, the stock still trades at a 22% premium to TNAV. I think that’s probably fair given the bank’s 17% return on tangible equity, but as a non-expert, I am inclined to take a neutral view until we see credit losses and margins start to level out. | |
MONY (LON:MONY) (£989m | SR73) | Reports growth in revenue and adj EBITDA during July-Nov. FY25 expectations remain unchanged, with consensus for adj EBITDA of £142.7m. | ||
Spire Healthcare (LON:SPI) (£900m | SR57) | SP -15% Rev +3.6% in July-Oct, but lower volumes of NHS work mean FY25 adj EBITDA to be at lower end of guidance for £270-285m. FY26 outlook “broadly in line or slightly ahead of 2025”. Proposed NHS Payment Scheme prices for 26/27 are said to be below inflation. | PINK/BLACK (AMBER/RED ↓) (Roland) [no section below] In September, Spire reported that it was holding discussions with a number of parties about possible options, including a sale. In the announcement, management effectively complained that Spire’s share price was too low. At the time, I commented that this business might have some valuable freehold assets, but profitability was extremely low while leverage was relatively high. Today’s update highlights weak revenue growth and appears to cut guidance for both FY25 and FY26; broker forecasts have previously suggested that FY26 was expected to be a much stronger year for earnings. I can’t help feeling that this business may be overly dependent on a supply of NHS work to subsidise its slow-growing private medical business – this year's H1 results showed NHS revenue up 16.2%, but revenue from private payors rose by just 0.8%. Given that today’s downgrade affects both FY25 and FY26, I’m going to move down one notch and adopt a more cautious view. | |
ZIGUP (LON:ZIG) (£779m | SR85) | Rev +2.9%, adj EBIT +11.5% to £81.7m. Confident FY26 profit to be “at least at top of current range of expectations. Expectations are given as being for adjusted PBT of £150-155m. | AMBER/GREEN = (Roland) This looks like a fairly solid set of results to me, supported by good underlying growth in the rental business, especially in Spain. While rising leverage and modest returns on capital suggest to me that the current valuation could be about right, I have to respect the evidence of positive momentum and am encouraged by signs that cash generation should now start to strengthen. On balance, I’m happy to maintain Graham’s previous AMBER/GREEN view today. | |
Bloomsbury Publishing (LON:BMY) (£402m | SR54) | Will combine Bloomsbury’s publishing expertise with AI tech including NotebookLM, Vertex AI and Gemini. Hopes to show how AI can help “increase the discovery and sales of books”. | AMBER/GREEN = (Roland) [no section below] Bloomsbury is paying Google to provide a range of advanced AI services for use internally. The company says the cost of this investment has been factored into existing spending plans. I’m not sure how significant this is likely to be – in some ways, I think it could be seen simply as an IT upgrade. To be honest, this RNS seems a bit promotional to me and I’m not inclined to attach any value to it. Given the fall in Bloomsbury’s share price over the last year, I’m happy to leave Graham’s previous view unchanged today ahead of the peak festive trading season. I’ll be interested to see if there’s any revision to full-year guidance when the company updates in the New Year. | |
Judges Scientific (LON:JDG) (£373m | SR29) | Acquiring remaining 18% of Geotek do Brasil for £1.9m plus earnout of up to £0.7m. Initial consideration payable in 60x £45k monthly instalments. | ||
NextEnergy Solar Fund (LON:NESF) (£308m | SR38) | NAVps -6.6% to 88.8p, mainly due to lower power price forecasts. Cash income of £48m (HY25: £45m). Dividend unch. at 4.21p. Strategic review ongoing, new chair appointed who is former Drax CFO. | ||
Victorian Plumbing (LON:VIC) (£239m | SR61) | Rev +5%, adj PBT -6% to £21.8m. Net cash £17.7m. Gained share in bathrooms, relaunched MFI brand. Outlook in line with market expectations. | ||
Beeks Financial Cloud (LON:BKS) (£147m | SR26) | Signed 3yr, $1.5m Private Cloud contract with Canadian bank. Also signed £2m Proximity Cloud extension to existing deal with “large FX broker”, taking total contract value to £4m/5yrs. | ||
SDI (LON:SDI) (£78m | SR85) | FY26 expected to be in line with market expectations. H1 revenues +10.1% (£34m). H1 adjusted PBT +21.7% (£3.8m). | ||
Fevara (LON:FVA) (£68m | SR49) | £5m Brazilian acquisition, plus £0.8m-£1.9m of deferred consideration in March 2028. Macal is a leading provider of minerals and supplements, offering a wide range of products across several branded lines for cattle, sheep and horses. | ||
Gear4music (HOLDINGS) (LON:G4M) (£60m | SR97) | SP +7% Very strong sales momentum highlighted in previous updates continued over Black Friday. Sufficient confidence to again raise expectations for FY March 2026. EBITDA to be not less than £16.7m (previously £15.2m). | AMBER/GREEN = (Roland) [no section below] Cyber Monday marked “the highest revenue day in our history”, with over 14,000 orders dispatched. FY26 EBITDA guidance has been lifted a further 10%. Taking a longer view, EBITDA expectations for FY26 have now risen by more than 50% (from c.£11m in April 2025) – an impressive turnaround. I’ve been AMBER/GREEN on this stock for some time now, most recently in November when I was reassured by evidence of underlying growth and market share gains. However, I also noted the rising cost base (including a new warehouse) and this year’s one-off benefit from selling bankruptcy stock acquired at below book value. One related point management is keen to emphasise is that the competitive environment has improved for them this year, thanks to the failure of some competitors. This is expected to reduce the level of aggressive discounting in the sector and should help to sustain a higher level of market share for G4M. I’m happy to maintain my previous view today, but I don't see enough value to consider an upgrade until there's more clarity on the outlook for next year. | |
Ondo InsurTech (LON:ONDO) (£42m | SR13) | H1 revenues +26% to £2.1 m. Full-year revenues will be £4.5m to £5m, EBITDA loss £5m to 5.5m. Cash £0.6m at end of H1. Proposed equity fundraising for £2.2m. | ||
Solvonis Therapeutics (LON:SVNS) (£16m | SR30) | SVN-015, targeting methamphetamine and cocaine use disorders, has been accepted into the US National Institute on Drug Abuse's Addiction Treatment Discovery Program. NIDA will fund and conduct early preclinical evaluation. | ||
SysGroup (LON:SYS) (£13m | SR40) | Revenue -3% (£9.9m). Adj. EBITDA £0.2m. Loss before tax £1.6m. Cybersecurity now 47% of revenue. AI delivering measurable ROI. Headcount reduction from 111 (FY23) to 80 (FY26). Full-year performance is expected to be in line with expectations. | ||
Oxford Biodynamics (LON:OBD) (£11m | SR3) | (OBD share price fell and rebounded in the last few days.) The UK National Screening Committee’s draft recommendation on prostate cancer screening has no direct impact on OBD or its PSE test. |
Roland's Section
ZIGUP (LON:ZIG)
Up 12% to 383p (£883m) - Interim Results - Roland - AMBER/GREEN
When Graham last covered van hire and incident management group Zigup in September, he summed up the situation with this pithy comment:
I’m leaning towards the conclusion that everyone is right: the company is right to borrow heavily, Roland is right to be careful, and yet there is an opportunity if nothing goes wrong. So let’s give this an upgrade by one notch […]
It looks like Graham was right to highlight the opportunity and take a more positive AMBER/GREEN view than the neutral view I’d previously held. Today’s results from Zigup look fairly strong to me and have prompted management to nudge full-year guidance a little higher:
… we now expect our full year underlying PBT to be at least at the top of the £150-155m range of analysts' expectations.
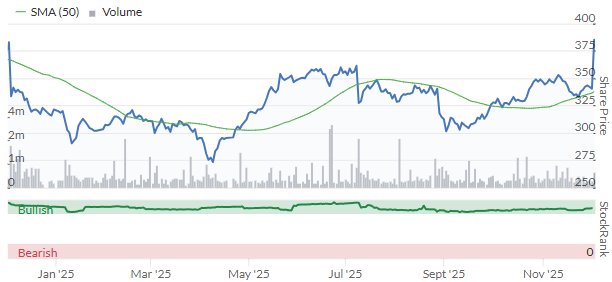
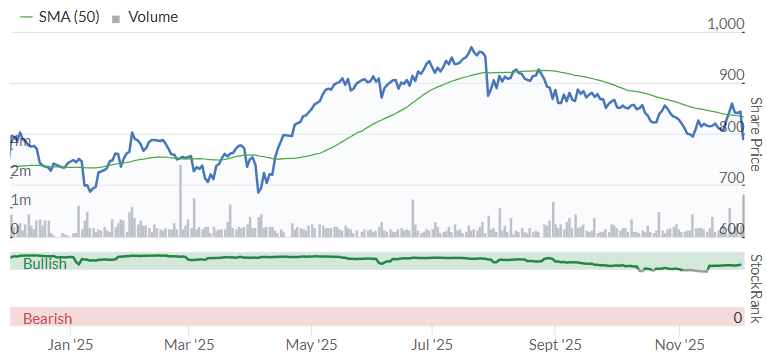
The share price has also reacted favourably and has now round-tripped back to the level it was at a year ago:
Let’s take a look at the numbers and some of the changes announced by the company today.
H1 results summary
These results cover the six months to 31 October 2025:
Revenue up 2.9% to £929.6m
Reported pre-tax profit up 15.8% to £65.0m
Underlying pre-tax profit -0.4% to £81.7m
Underlying earnings down by 1.8% to 27.6p per share
Interim dividend unchanged at 8.8p
The company’s segmental reporting shows some significant differences in trading across the business:
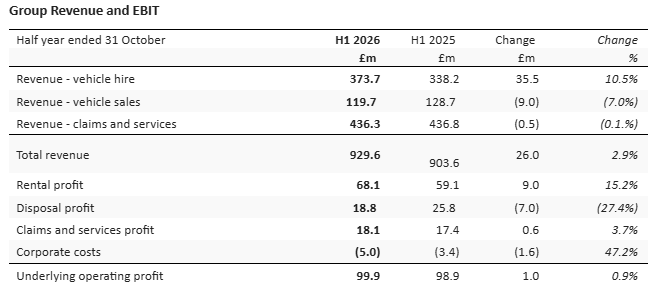
Vehicle hire: trading during the half year appears to have been particularly strong in Spain, where vehicle hire revenue rose by 16.3% as the company’s fleet expanded, aided by “a major rail maintenance fleet win”.
In the UK, vehicle hire revenue rose by 6.5% due to “a combination of product and vehicle mix alongside pricing actions”. However, the average number of vehicles on hire in the UK fell slightly “as we restructured our broker channel approach”.
In total, Zigup’s hire fleet rose by c.2,500 to “over 135,000 vehicles” at the end of October.
Vehicle sales: selling ex-rental vehicles is an integral part of the vehicle hire business model, so I tend to view this as part of the hire business. However, Zigup likes to split out the two in order to highlight underlying operational growth in the rental business.
What these figures show is that the post-2023 decline in vehicle disposal revenue and profit is continuing as new vehicle availability normalises:
FY24 disposal profits: £61.9m
FY25 disposal profits: £52.5m
HY26 disposal profits £18.8m (HY25: £25.8m)
I’d expect this process to bottom out fairly soon as the company’s fleet replacement programme normalises and the backlog of older vehicles is cleared.
Claims & Services: Zigup’s claims management and repair operation increasingly targets contracts with insurers. For H1, the company reports a multi-year renewal with Tesco Insurance and a new contract with broker Howden Insurance during the half year.
However, overall Claims & Services revenues and margins were said to have been flat, due to lower claims volumes.
Profitability: there’s a sharp divide in the profitability of the two halves of this business. Combining rental profit and disposal profit gives me an underlying operating margin of 17.6% in H1.
In contrast, the Claims & Services business generated an equivalent margin of just 4.1%, with guidance suggesting a figure of c.5% in H2.
Of course, margins only provide a partial picture, especially for a capital intensive business. A more relevant metric for me is return on capital employed. Zigup reports an underlying ROCE figure of 11.9% for H1, down from 12.8% for the same period last year.
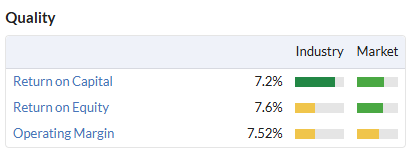
My calculation using statutory figures suggest a trailing-12-month ROCE of 7.2%, consistent with the StockReport metrics for last year:
For a capital-intensive business with this level of profitability, I’d argue that a valuation of somewhere close to 1x tangible book value makes sense.
In today’s results, Zigup reports net assets of 480p per share (FY25: 473p) and net tangible assets of 393p per share (FY25: 381p).
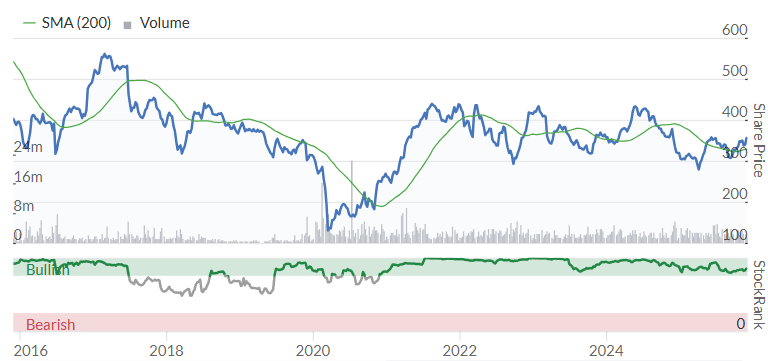
At today's share price of c.383p, I'd argue the business is fairly valued or perhaps slightly below fair value. The long-term share price chart suggests to me that the market may share this opinion:
Cash flow & Balance sheet: running a big rental fleet inevitably requires a fair level of debt. My rule of thumb with hire businesses is that I prefer to see borrowing limited to around 50% of the rental assets' value.
By this metric Zigup still appears to be just about within my comfort zone, albeit at the outer edge.
The group’s net debt rose by £156.8m in H1 (versus April 2025), while the value of the company’s rental assets rose from £1,511m to £1,683m over the same period. Based on these assets alone, net debt was 55% of the value of the rental fleet – a little high for me.
However, it’s probably reasonable to view net debt in the context of the whole group. Adding in £174m of other fixed assets gave a net book value of £1,857m at the end of H1, giving a net debt/net asset ratio of 51%.
Using the company’s preferred measure, net debt/EBITDA leverage was 1.9x, up from 1.8x at the end of April 2025 (and 1.6x in October 2024).
Rising debt suggests weaker cash flow. A quick look at the cash flow statement shows that operating cash flow fell to almost zero in H1. This was due to a combination of higher fleet capex and reduced proceeds from disposals:
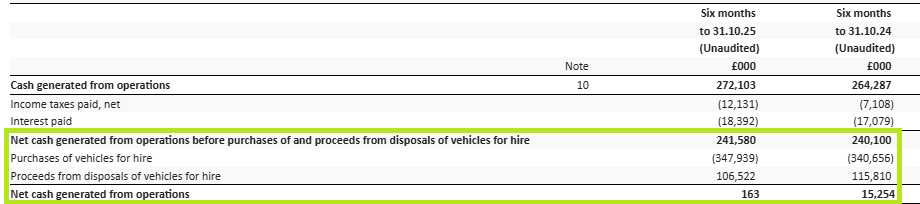
Commenting on capex in today’s report, the company says that steady state cash flow is expected to increase in coming periods.
My reading of this is that growth and replacement capex may ease as the fleet age and size stabilises at the desired level. This should help to improve operating cash generation and limit any further growth in leverage – I wouldn’t want to see this rise above 2x EBITDA.
Organisation structure: Zigup was formed in 2020 by the merger of Northgate (UK & Spain van hire) and Redde (UK claims management and repair).
I was never entirely convinced about the potential for merging these two rather different businesses. It now seems as though the company may also be coming round to my point of view. Today’s results include a comment on the “continuing evolution of the UK&I operating model":
This autumn we commenced a new phase of simplification and transformation, with workstreams encompassing a further evolution of the UK&I operating model into two operating businesses focused on each of Rental and Repair. It is fully aligned with our strategic framework and will enhance the competitive advantages of our integrated platform.
To me, “two operating businesses focused on Rental and Repair” sounds a bit like Redde and Northgate before they merged! Management expects this restructuring programme to take up to 18 months and provide £20m of annualised cost savings by FY28.
Outlook
Strong performance across the business, especially in Spain, provides confidence that full-year performance will be “at least at the top of the range of analysts’ expectations”.
These are given as being for an adjusted pre-tax profit range of £150-155m.
I don’t have access to any broker notes today, but this morning’s 12% share price rise suggests to me that perhaps some brokers have upgraded following these results.
Here’s how consensus expectations looked for the business prior to any changes today:
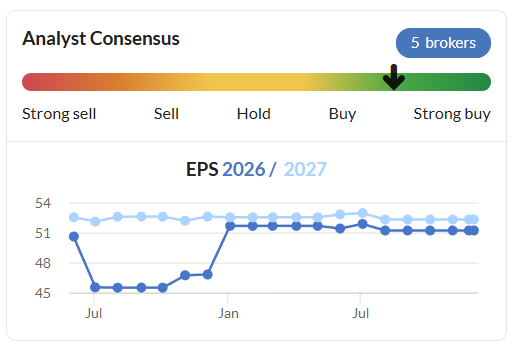
Assuming a 5% upgrade to consensus earnings forecasts would give a figure of around 54p per share. That would put Zigup on a forward P/E of 7, with a 7% yield.
Roland’s view
In my view, this is a capital-intensive business that’s always likely to generate somewhat average returns on capital. Zigup’s leverage is now also at the top end of what I’d want to see.
I’m also amused to see that the company now appears to be planning at least a partial reverse of the 2020 Redde - Northgate merger. The low-margin Claims & Services business has never seemed very attractive to me.
Having said that, I do remain a fan of the core Northgate business, which has good scale and has been a market leader in its sector for a long time, delivering reliable results.
On balance, I think the valuation remains reasonable here given the momentum implied by today’s upgrade. While I would personally prefer to purchase the shares at a discount to tangible net asset value, I think it’s appropriate to leave Graham’s AMBER/GREEN view unchanged today.
Paragon Banking (LON:PAG)
Down 6% to 795p (£1.55bn) - Final Results - Roland - AMBER ↓
Today’s results look fairly decent, as I hoped when I took a fairly positive view on the interim results in June.
- Pre-tax profit +1.1% to £256.5m, with adj EPS +8.5% to 109.7p (Stocko consensus: 104.5p)
- RoTE stable at 17.5%.
- Net Interest Margin 3.13% (FY24: 3.16%)
- Net loan book +4% to £16.3bn
However, today’s results have highlighted a couple of headwinds that could put pressure on profitability over the coming year:
- Motor finance provision increased from £6.5m to £25.5m based on the FCA’s consultation paper.
- Impairment charges +71% to £41.9m (FY24: £24.5m), mainly due to underperforming pre-2022 property development loans.
This appears to lave prompted a mild sell-off today.
One issue is that the performance of pre-2022 property development loans still appears to be worsening. At the end of the year, Stage 3 loans (where borrowers are not expected to make a full repayment) accounted for £104m (11%) of the development finance portfolio. The company blames this on cost inflation and higher interest rates since 2022, but these bad debts are still being worked through the books.
Paragon’s impairment charges have now risen from just £14.0m in 2022 to £41.9m in 2025 – a threefold increase that’s a useful reminder of cyclical risks in lending.
Higher motor finance provisions are another possible headwind, although the final outcome of the FCA proposals isn’t yet known.
The end result from all of this appears to be that Paragon’s net interest margin could remain under pressure next year, potentially falling below 3% according to the newswire.
Are the shares cheap enough to reflect this risk? Today’s results show tangible net asset value up by 7% to 655p. At 798p, the stock still trades at a 22% premium to TNAV. I think that’s probably fair given the bank’s 17% return on tangible equity, but as a non-expert, I am inclined to take a neutral view until we see credit losses and margins start to level out.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Family members and myself are all very happy with A J Bell. None of us have had a single issue with them in the several years we have dealt with them.
PayPoint (LON:PAY)
Sold off about 15% on Nov 20th following the half year results. Many thought this seemed harsh - it looked perhaps cheap on a FY27 pe of 7x. I am surprised to see it has dropped another 20% in the last 2 weeks - now trading on 5.6x pe FY27. I don't hold but am considering it, it does look oversold to my eyes. Any opinions on what's causing the further fall (can't see any big sellers selling down). Is this just sentiment based on their operational issues with Collect+, which have caused some customer dissatisfaction - obviously this can seriously hurt their brand / service - but could also just be a short term issue. Evri has a very bad reputation but it still does a lot of business. Very unsure on this one, could be a bargain or could be struggling in many parts of the business. Any optimistic holders still left?
PayPoint (LON:PAY)
it is a looking very interesting now
i saw some chatter - you have seen it too with regard to whether there may be impending competition with other parties (locked boxes of some sort?) - ref ability to use shops as collection points for deliveries?
You mention Collect plus operational issues but dont mention that there might be issues with them losing volume due to above reasons? - i might has misread the chatter i saw.
If anyone does understand the potential impact of that if they can give us a quick update that would be appreciated.
i am not a chartist but the chart is interesting - its obviously woeful - but i am wandering if the facts its at or close to lows for the past 10 years plus whetehr that may provide some support.
the stocky rankings most certainly seem to have fallen out of love with this share - its not exactly uncommon for the stocky rankings to be slightly mystic meg in that regard - albeit the shareprice decline must at least partly copntribute to pants current ranking
as things stand current 2027 (year starting 1/4/26) estimated are for a tidy eps of 83p
PayPoint (LON:PAY) - yes, does look interesting. I sold earlier in the year when I thought it was fairly valued at the £100m EBITDA target. I'm holding off re-entering for now as operational issues at parcel companies don't normally get fixed quickly, from my experience. Very good company though.
It might have been my comment on PayPoint (LON:PAY)! Can't find it now, but if you go into my user profile and scroll through my Activity/comments feed... will be there...
I did analyse their latest results, and here's my view:
Overall, still a very good moat IMO, very high quality. But markets were probably expecting bigger growth here, so been sold off. I think it is getting to a value point. In the past I'd bought at 440p and sold at 660p, and its around those levels again now, but much bigger and better company.
I did note that in their report, management just said the good stuff. To get the bad numbers or the less flattering commentary, one had to dig quite a bit. Not active deception... but I don't like it if management can't just be upfront honest with things that are not going as well. Its not a red flag, but more amber for me. Suggests that management are a bit cocky and have an ego, which is not what you want if they are hitting a rough patch of trading / competitive pressures, as they could be blind to them thinking their company is the best thing since sliced bread.
PayPoint (LON:PAY)
cheers - it sounds like if there is a more structural issue withn stuff perhaps being diverted to inpost methods then that would be a double whammy - if that means whats left doesnt cover the fixed costs as well.
I would expect that if that is the case that potentially that might show up in then future updates fairly quickly - so i migght be minded to say avolid until they update again and we see the direction of travel ref 2027.
copilot agrees that collect+ might lose out on tehe battle with Inpost
one additional question is the collect+ stuff material to the bottom line ? if that was closed down would that be seriously bad news ?
Many thanks rmillaree, topvest, and boon for the responses. I am in 2 minds on this one. I think its probably prudent to wait for evidence of improving business performance. On the other hand, I think if I wait I might miss a decent re-rating - which will probably happen before the improved performance is evident. I think I would be more inclined to take a punt if the stock rank was higher - for now it will remain on the watchlist. Thanks again for all the responses...much appreciated.
Hercules (LON:HERC) Bowl forming? I hold.
I hold Hercules (LON:HERC) Yes, Hercules have confirmed that they are expanding into Scotland, with the opening of an office in Motherwell (Central belt). There is also increasing evidence that the construction market in Scotland is slowly improving, (after a fairly benign 2025), with a number of infrastructure & housing projects commencing in the early Spring of 2026. As is the case with the remainder of the UK, there will undoubtably be a shortage of skilled labour and specialist plant in the near future. Hopefully Hercules can assist in filling this void.
I live in the Highlands and the number of wind farms being considered is causing alarm to a lot of people. Not the land owners, who will make millions. These projects will initially require a lot of labour, which cant be filled locally, so it seems like a good move by Hercules.
On Beach group (LON:OTB) looks great value to me, results/outlook a lot better than i was expecting!|
Headwind at 220-225, once cleared should be a nice run to 240 ish
Or what am i missing?
JohnDoe, I cant see you have. I have followed this on and off for a few years and finally bought yesterday. There is obviously an execution risk in terms of delivering their ambitious growth plans. I am slightly surprised Easyjet have not made a move, they are keen to expand their package business to try and improve margins.
Ask the audience
AJ Bell v Stocktrade v Transact
My dentons sipp no longer friends with ii so money flow between dentons / ii is painful
Solution is use one of three above that are all linked to dentons so flows like warm honey .
Of course dentons “cant provide any advice”
So asking the audience
AJ Bell v Stocktrade v Transact
Any recomendation , low cost platform for Sipp share dealing ??
I use AJ Bell for my SIPP and I have found them to be very helpful and costs are reasonable. No experience of the other two I'm afraid.
Same for me. Definitely recommend AJ Bell
I use Transact. Downside is generally not live trading and you have to pay £10 for a "special" (i.e pushed through) trade, but even then it's not live. £3.75 a trade otherwise, unless someone else is trading the same share at the same time.
I'm not a day trader so it doesn't really matter to me...
Edit : Just remembered I think you need to go via a registered adviser. "Orphan" clients get stung.
Charles Stanley AlphaSipp. Not a trader, so the efficient, comprehensive but unfussy and good value service counts for me.
Happy with AJB does all that I need ISA and SIPP
Hey welcome back planetx !!
Gear4music (HOLDINGS) (LON:G4M) just announced excellent Black Friday trading today 3rd Dec -so wonder why it will take until 20th Jan to get Christmas trading?
Returns? Unwanted gifts maybe?
Morning Roland,
Would appreciate a few words from you on Paragon Banking (LON:PAG) which looks a good candidate for our income portfolio
Thanks for good work over the many mornings when I fail to get up for 8am (like today)
Thanks Roland
ZIGUP (LON:ZIG)
This is one of my larger holdings - its very solidly run company on cheap earnings multiple with NTAV above current shareprice and a chomping dividend
todays update says they are at the top of expectations ref year end - plus perhaps something on top to come - practicably speaking if we were previously looking at midpoint of expectations - thats an earnings upgrade.
The positive outlook for the remainder of the year gives us confidence that underlying PBT will be at least at the top of the range of analysts' expectations.
Shareprice is up 10% and company has a vey solid 85 stockrank.
pe is still pretty miserly - i kind of see whay though. They have materially had to up the fleet value and the net debt - just to standstill ref profits as the prior tailwinds ref easay money on elevated van values has pretty much all gone. Its probably to their credit that overall they are still making very decent money. they started 2024 with 692 million net debt thats now £939 million.
Dont get me wrong the NTAV is doing fine so its all gone on extra fleet - but on lfl basis its much better to make the same profit with less assets and less debt than more. I think alot of this is morphing over to the new new that everythig costs more !!
The good news is that they have at last stated that they have reached the inflexion point ref cashflow - at last is all i can say in that regard !!!!!!. If this company can simply keep fleet value increases in line with future turnover increases only it has great potential to turn into cashflow beast - and thats what it needs to do. Once debt drops finance costs drop and that can work out very nicely. I am hoping there is an eleemnt of them investing the last 18 months for longer larger commercial contracts where te payback is over the 4 year or so term that the vehciles will last - so hopefully there is a bit of hidden lag here that the investment made already should pay dividends. The proof of the pudding is in the now and future though in that regard - so postive update today is good starting point.
Per company today
With good progress made on fleet replacement I am pleased with our cash performance; we are reaching an inflexion point, paving the way for sustained improvements in steady-state cashflow in the years ahead.
Hopefully now the infelxion point has been used the shareprice may zigupo more than it zigs down going forward.
Been an holder of ZIGUP (LON:ZIG) since the COVID times so done pretty well from it in both share price appreciation and dividends. I've been very positive about management (except when they changed the name and mulled taking over Halfords) and believe they have shown they know what they are doing.
Clearly the debt levels have scared some people off but when asset based on and increasing NAV I haven't been too bothered by it as long as they are able to put the assets to use. Its never going to be an high rated company but even at 10 times earning brings its SP close to 500 than its current price.
I've been of the opinion for a while that for a cash rich PE company or the like this would be a great acquisition as their cost of capital would be lower and hence they would be able to get more profit from it but a happy sitting on my 7%+ dividend in the meantime.
ZIGUP (LON:ZIG)
(except when they changed the name and mulled taking over Halfords)
To be fair with regard to Halfords they walked away from that deal - i think the fact Halfords have so many sites and they could have used those sites to store or collect vehicles i was very pro Halfords takeover as long as it was done on terms that suited zigup.
Ultimately halfords board probably turned downa decent deal that values the company more than the market does now.
Ref the name change - if you look at their lightning bolt symbol i can see the zigup and see the reference - i dont disagree if name seems silly or is hard to spell when its not clever using name.
Clearly the debt levels have scared some people off but when asset based on and increasing NAV I haven't been too bothered by it as long as they are able to put the assets to use. Its never going to be an high rated company but even at 10 times earning brings its SP close to 500 than its current price.
The thing is its all added risk - note the big hidden risk here with higher fleet value is that any change to depreciation policy that knocks down asset values weighs higher if the aset value is higher. In the recent past they have gone the otherway - but if they needed to writeoff 10% of fleet value thats getting on for a year and a halves profits. So no imediate worried - but it should be easy to make money of shiny new assets - can you make money and are they worth the book value you have in 4 years time ? many equipment rental companies have parcicably speaking not been conservative enough - so it is a sector danger. I have zero evidence though that the board are pimping anything here - the fact prior policy was too conserative derpreciating too quickly suggests they are reasonably cautious.
I thought debt might have peacked ayear ago it hasnt - but the fact they say they are at thew inflexion point now - hopefully in 12-18 months time it will all look so much better.
I've been of the opinion for a while that for a cash rich PE company or the like this would be a great acquisition as their cost of capital would be lower and hence they would be able to get more profit from it but a happy sitting on my 7%+ dividend in the meantime.
Yep - eg if they got decent offer for the spanish unit and returned funds to shareholders. I thought it was a speculative purchase at 200p back in the day - but mangement have impressed me enough to make this one of my core holdings for now - until such time as value outs - so happy to do exactly as you are doing here.
Gear4music (HOLDINGS) (LON:G4M) Another share price Jump today on a SR of 97. Record Black Friday weekend sales with Xmas to come..... “This follows the upgrades announced in June, September, October and November 2025, and we now expect EBITDA to be not less than £16.7m”; from 15.2M. On a (drum) roll?
Good bounce for Bloomsbury (LON: BMY) with their type up with Google. Up 3.5%
Agreed - will be fascinating to see what earnings enhancement comes of this collaboration ?
As the dust settles on the budget the verdict from markets is fairly clear...Bond yields have fallen, 5-10bps....so nothing huge but they moved in a market friendly direction. News flow has been supportive as debate rages on whether the tax rises were needed or not. Looking further out the conclusion thus far is the budget will hold back growth. I hope that this serves as a catalyst for more positive policy. Without this the GDP Growth for the UK looks lower. A difficult scenario for any government. Equities would appear to be hanging their hat on US rate cut expectations being more positive for growth....and since confidence in this seems high I am more tempted to lean the other way. Not really bearish - but looking for a change in leadership. J Authers on the consumer goods sector this morning did not strike me as overwhelmingly positive so it's all work in progress for me. The conclusion for the UK, sadly, is this government like those before it, has few ideas to stimulate better growth without spending money. Fortunately UK equities are not expensive so expectations are low. Hopefully the disappointing prospects stimulate the government into action ....and the outlook improves.
It is an ever increasing challenge to find the right portfolio balance. UK equities are cheap but the economy is non growth. Large parts of the US market are overpriced with a risk of correcting but has high liquidity and a less restrictive, pro growth mix. I am currently 20% cash and torn between holding more cash versus greater US exposure with a FED rate cut likely.
Europe - ETF - CEU1
UK is just dreadful
By any recommended measure I am overweight UK. Europe is on my radar.
I can help put this in context, UK indices are all up this year..which I think is pretty good.
All share index is up 17% slightly less than the FTSE 100 but reflecting weaker FTSE 250 midcap stocks which have only risen 6.44% ( Which is still ok). Although S&P 500 is also up 17% this is a dollar return that is lower in £ sterling. The Nasdaq is out in front for obvious reasons. The year hasn't finished but these returns are actually pretty good - way better than dreadful - I am up 20%+ and consider this year to be above average. Whilst not stellar I like the UK market and we should not get carried away by returns of a small number of stocks overseas. Small cap stocks have done less well everywhere but are still positive. Plenty of reasons to be positive.
Think I'm talking dreadful also from my perspective. 20% is a great return, similar to what I had last year. This year unfortunately, not so good
Important thing longer term is to stay in the game, it's your long term compound number that maters not any individual year.
......but NAPS is up 32% ytd. This is a good year for UK stocks despite everything.
Yet SNAPs is only up 2%,:when the market is up 8%. Most of NAPs gains is due small gold miners.
True but NAPS usually has one or two big winners that carry the rest. That's pretty much the basis of the basket of shares theory as I understand it.
Yes but many don't invest in commodities or mining, especially a small one in the Philippines. So not very representative of the UK market.
Hi Rusty could you remind me what is the difference between the naps and snaps ?
SNAPs is done halfway through the year, 1st July, NAPs is 1st January or close to those dates.
Cash to me is bonds because I can generally get the money out quickly but I am at least getting a good return while waiting.
My focus generally is on companies on the UK market with a lot of non UK exposure (particularly in the small cap area) as they are rated on UK multiples but have the advantage of international growth and covers any currency losses. At least thats the plan
Ed Shing made some good points re Poland in his recent write up
Agreed. RDHOWARTH. Interestingly, 10-yr gilts are currently being led more by Japan, of all places. https://tradingeconomics.com/b... Rates are up to 1.9% today. The issue here is that Japan (with debt:GDP of c240%) cannot afford to refinance its debt at these sort of rates. Whenever Japan's 10-yr gilt rates goes up the US and UK are doing similar and the US stock market selling off. Could all blow over or blow-up, but worth watching!
Japan 10 year bond yield has risen 0.84% from a rate of 1.05% last year. A massive jump and the largest of a G7 economy.
This is currently not much discussed but might have a very substantial impact if this is a precursor to rises elsewhere. Sovereign bond market is very much an international market.
Whats your view on how it could play out if rates continue to go up Topvest ? could the carry trade unwind and much of the seven trillion estimated involved head back to Japan and put a cap on the Japanese ten year yield, given there's estimated to be a trillion Japanese holdings in US treasuries.
You could argue you can still get 4% ish in US 10 year against 2% ish in Japanese 10 year bond but if a lot of that money returns home I'm assuming that would weaken the dollar and push up the yen so even allowing for the interest rate differential it would still be a safer outcome.
This to me seems the biggest current possible black swan but not getting much air space and I suppose counter argument is generally black swans when they hit are normally something under the radar.
Interested in your thoughts and welcome anyone else who wants to chip with possible outcomes.
Spire Healthcare (LON:SPI) once again disappoints, only reason I'm holding is for a takeover, not the most sound plan, but...
Roland, a brief look at the biggest deal of the day would be appreciated i.e. Smiths (LON:SMIN) sale of its detection business for £2bn. Thanks.
Well Greencoat UK Wind (LON:UKW) have responded very strongly on the RO consultation. I fully agree. The Government are defaulting on a regulatory promise, which will just increase energy bills (i.e. the opposite of what they are trying to achieve).
"The response highlights, among other items, the following:
i. The proposals set out in the RO consultation will not have the desired impact of reducing consumer bills. Instead, it will drive up consumer costs by increasing the cost of capital to finance new infrastructure.
ii. There has already been an increase in the cost of capital as a result of the RO consultation which can be seen in the share prices of the listed renewables funds. This will increase the cost of the energy system which will ultimately be borne by consumers.
iii. The need to preserve grandfathering and, the principle of avoiding retrospective change such that the UK's reputation for predictability, stability and reliability in the way it treats investors, should be preserved. There are precedents within other parts of the regulated utility sectors where the principle of neutrality has been observed.
iv. The Government has not allowed sufficient time for a fulsome consultation which creates further uncertainty for investors.
v. These types of interventions risk the achievability of the Government's Clean Power Mission and wider infrastructure investment targets.
vi. Accordingly, neither option set out in the consultation should be pursued.
vii. The RO should continue to use RPI until 2030 and then switch to CPIH as clearly signalled to investors already by the UK Statistics Authority.
viii. Other options, such as the introduction of a voluntary Contract for Difference, can reduce consumer bills and not impact investor confidence. This is where the Government should turn their attention."