Daily Stock Market Report (Wed 3rd June 2026) - RFX, BME, DEBS, HWDN, DSCV

SpaceX IPO price: Reuters has exclusively reported the price of the SpaceX IPO as $135 per share, with 555.6 million shares offered at a $1.8 trillion valuation.
For those who believe that the demand for AI stocks is running at highly speculative levels, not tied to the fundamentals, the market is providing a natural solution: supply.
A tidal wave of new shares is going to hit the market to soak up the demand:
SpaceX: $75 billion of new shares at a $1.8 trillion valuation
Anthropic (creator of Claude) has started on the paperwork for an IPO this Autumn. Its private market valuation is $965 billion, recently raising $65 billion at this level.
OpenAI (creator of ChatGPT) is already widely rumoured to be planning an IPO this year. Its private market valuation is $852 billion.
Alphabet is setting up for the biggest fundraise of all time, looking to raise $80 billion to build AI infrastructure.
My view is that if investors are willing to pay absurd prices for AI-related shares, then it makes sense for companies to supply the market with as many AI-related shares as possible.
In the words of Ed Seykota: Win or lose, everybody gets what they want out of the market.
Overnight market movements:
The FTSE is set to open unchanged at 10,370
S&P 500 is unchanged at 7,600
Brent crude is up 2% at $97.80
Gold is down 0.7% at $4,460
Bitcoin is down 0.3% at $67,350
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Tritax Big Box REIT (LON:BBOX) (£4.1bn | SR45) | The sale to EQT Real Estate includes a mix of big box and urban logistics assets. They were sold in line with their respective book values and generate total contracted annual rent of £12m. Proceeds will support investment in higher-returning development opportunities. | ||
Howden Joinery (LON:HWDN) (£4.1bn | SR87) | Acquisition for an EV of £390m, with £292.5m in cash and £97.5m in Howdens’ shares. Valuation gives a multiple of 8.5x last 12 months’ EBITDA to March 2026. DIY Kitchens generated revenue of £136m and EBIT of £37m last year (a 27% margin, versus 14.7% for Howdens). No change to previously announced £100m buyback. | AMBER (Roland) [no section below] Today’s acquisition is priced in line with Howden’s own valuation (8.5x EV/EBITDA). It looks small enough to be manageable and should be margin accretive. However, it’s worth noting this is a new line of business for the group. DIY Kitchens sells online, direct to retail customers who want to design their own kitchen. Howdens sells only to trade customers. There’s limited overlap in production, too: DIY Kitchens operates “short production runs for a made-to-order offering”. Howdens manufactures for stock and has long production runs. For these reasons, I guess, DIY Kitchens will continue to run as a standalone business, albeit with some consolidation of raw material supplies, etc. This acquisition opens up a new customer base to Howdens and seems to be a nice business. But there’s very little overlap with the group’s core activities. We’ll have to see how it pans out. More broadly, I can’t help feeling Howden’s valuation is approaching an area where it could be interesting – this is generally a quality business with a strong track record of growth. We haven’t looked at this stock since 2024, so I’m going to open our coverage today with a neutral view, reflecting the StockRank. | |
B&M European Value Retail (LON:BME) (£1.71bn | SR55) | “Profits at the midpoint of current guidance”. FY26 revenue +3.6%, adjusted pre-tax profit -37.7% to £284m. Adj EPS -36.4% to 21.3p. Net debt down 15.9% to £656m, within 1.0x-1.5x target range. Outlook: Back to B&M Basics “on track”, targeting “medium term” return to double-digit EBITDA margins. | AMBER ↑ (Roland) Sales were flat last year in the core UK business and margins fell sharply due to the twin pressures of higher costs and price cuts to stimulate demand. But my impression is that CEO Tjeerd Jegen is correcting the operational issues in the business and has a sensible strategy to return to growth. I am also encouraged by his regular share purchases since taking charge, which have totalled c.£1.5m over the last year. With a FY27E P/E of 9 and c.6% dividend yield, I believe there’s probably an opportunity here. However, difficult market conditions and relatively high leverage mean I’m going to upgrade to a neutral view today, in the hope of turning positive over the coming year. | |
Currys (LON:CURY) (£1.61bn | SR77) | Tønnesen has been the CEO of Currys’ Nordic business since March 2023 (40% of group revenue) and has over 20 years experience with the group, starting as a sales assistant. | ||
Ninety One (LON:N91) (£1.49bn | SR86) | AUM +31% to £171.8bn with net flows of +£2.8bn, mainly from Asia Pacific. Pre-tax profit +2% to £207.5m with adj EPS +12% to 17.4p. | ||
Energean (LON:ENOG) (£1.44bn | SR37) | Company has been informed by seller Chevron that one of its JV partners plans to exercise its pre-emption rights in relation to the Energean’s planned acquisition of interests in Block 14 and 14K offshore Angola. The JV partner must now demonstrate its suitability for the ownership of this deepwater asset. | ||
ITM Power (LON:ITM) (£1.28bn | SR27) | Protium Green Solutions and ITM have formalised a partnership to develop, invest in and operate green hydrogen plants across the UK, with an immediate focus on the Cromarty Project in Scotland, which was recently acquired by Protium. | ||
Discoverie (LON:DSCV) (£757m | SR59) | Revenue +5%, adj pre-tax profit +4% to £51.9m with adj EPS +4% to 40.3p. Organic order intake rose by 5% (+14% in Q4) and three acquisitions were announced, totalling £95m. Outlook: “good start to the new year” with orders ahead of sales and improving industrial market conditions. | AMBER = (Roland) [no section below] Today’s results from this electronics business appear to be in line with consensus. Broker forecasts for the year ahead are also unchanged. The growth rate remains unexciting and Discoverie’s operating margin of 10% and ROCE of 9.3% suggest to me that this is an average quality business and/or that some of its past acquisitions have been made at a relatively high price – a point Mark flagged up in December. I’m going to maintain our neutral view here today. I don’t see any obvious problems, but the sub-5% free cash flow yield implied by today’s results suggests to me that the valuation is up with events. | |
Rockhopper Exploration (LON:RKH) (£663m | SR32) | Sea Lion Phase 1 sanctioned, Rockhopper funded for Phase 1. First oil targeted Q1 2028 with 110m bbls 2P reserves net to Rockhopper. Debt financing in place including $350m of RKH debt plus $142m raised through placings. | ||
Griffin Mining (LON:GFM) (£563m | SR74) | Reinstating buybacks, plans to purchase $15m/3.7m shares by 30 Nov 26, after which further buybacks may be considered. | ||
Intuitive Investments (LON:IIG) (£523m | SR53) | Discussions regarding the possible offer continue. IIG has requested and received agreement for a further extension of the PUSU date for Acceler8 Ventures to make a firm offer to 5pm on 1 July 2026. | TAKEOVER | |
Seraphim Space Investment Trust (LON:SSIT) (£497m | SR93) | NAV +24.8% to £421.3m (NAVps: 177.63p). Portfolio valuation +30.7% to £433.3m. Gains driven by increase in unrealised fair value of £102m, mainly due to ICEYE, Xona Space Systems and Tomorrow.io. Raised £136.5m through C Share issue in May. | ||
Boohoo (LON:DEBS) (£263m | SR19) | Gross Merchandise Value +0.5% year-on-year, improving to +8% in May. Growth strongest across the Debenhams and PrettyLittleThing brands. Gross margin improved, to 53.5% (52.1% prior year), while the returns rate fell by 5% supporting a material improvement in EBITDA margin. FY27 Outlook: confident in delivering double-digit adj EBITDA growth and free cash flow in FY27. | AMBER ↑ (Roland) Today’s update is essentially in line and broker forecasts are unchanged. But I think there are some positives here, especially reiterated guidance for improved margins and positive free cash flow in FY27. Boohoo’s valuation looks up with events to me, but the future of this business seems a little more assured than it was previously. To reflect this situation, I’m moving our view to neutral today. | |
Capricorn Energy (LON:CNE) (£229m | SR98) | Alamadiyaf al-Masiyyah continues to progress its funding arrangements and, accordingly, the Company has requested, and the Panel on Takeovers and Mergers has consented to, a further extension of the PUSU Deadline. | TAKEOVER | |
Aew UK Reit (LON:AEWU) (£173m | SR60) | AEWU has bought an interest rate cap to protect against the risk of higher interest rates when its fixed‑rate debt facility with AgFe expires on 20 July 2027. Covers 50% of the company’s current debt. One-off premium of £638k paid. | ||
Ramsdens Holdings (LON:RFX) (£148m | SR96) | Revenue +62%. PBT up 173% to £16.7m. Resulting from the continued strong performance across our diversified income streams and the additional benefit of the sustained high gold price, the Board currently anticipates that profit before tax for FY26 is expected to be in a range of £30m to £33m, ahead of current market expectations” (prior consensus was £28.6m). | GREEN = (Graham) | |
Eleco (LON:ELCO) (£109m | SR47) | "The Board remains confident in the outlook and trading remains in line with market expectations for the full year." | ||
Avation (LON:AVAP) (£81m | SR38) | Signed an eight-year lease agreement, extending to 2034, at current market lease rates with FlyJaya, an Indonesian airline, for an ATR 72-600 aircraft. | ||
Venture Life (LON:VLG) (£69m | SR56) | Buys brands from OrganiCare Nature's Sciences, LLC for up to $28m. The brands are sold in Walmart, Walgreens, CVS and Target and generated net revenues of c. $12.1m for the 12-month period to March 2026. | ||
Frenkel Topping (LON:FEN) (£62m | SR72) | FCA Condition has now been satisfied. The Scheme of Arrangement remains subject to Court sanctioning. | TAKEOVER | |
Zenith Energy (LON:ZEN) (£29m | SR44) | Exclusivity agreements in connection with the potential acquisition of a combined shareholding of approximately 82% in Daybreak Oil and Gas. Daybreak is an independent, OTC-traded crude oil and natural gas company, active primarily in California. | ||
Tan Delta Systems (LON:TAND) (£24m | SR20) | Revenue flat at £1.22m. Adjusted loss before tax £1.55m (2024: £1.14m loss). Cash £1.49m. “The increased loss reflects increased overheads to support expanding customer trial support activities… we expect a number of ongoing evaluations to progress towards commercial rollout decisions during late 2026, with adoption expected to build thereafter.” | ||
European Green Transition (LON:EGT) (£23m | SR17) | Operating loss £1.36m (2024: £2.2m loss). Post year end, acquired the Wind Energy Services business for £3.5m. Raised £7.5m. “EGT has strong near and medium‑term revenue visibility, supported by a growing repowering pipeline, recurring revenue and maintenance contracts across its existing customers.” | ||
FIRST CLASS METALS (LON:FCM) (£12m | SR10) | Re: the monetisation of one of the company’s Ontario assets, “material commercial terms have now been agreed between the parties and the definitive transaction documentation is close to being finalised”. |
Graham's Section
Ramsdens Holdings (LON:RFX)
Up 8% at 492.4p (£160m) - Interim Results - Graham - GREEN =
These results are quite astounding and have led to yet another round of upgrades.
Analysts have struggled to keep up with how the business is performing:
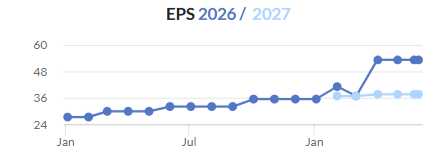
I’ve been saying for a while now that it has turned into an almost pure-play bet on the gold price. This company has been in the right sector at the right time. Here are the interim highlights:
Revenue up 62% to £83.7m
PBT up 173% to £16.7m
Net assets up year-on-year from £55m to £70m.
Special dividend: the ordinary interim dividend increases from 4.5p to 6p, and the special interim dividend jumps from 0.5p to 3p. The total interim dividend has therefore almost doubled from 5p to 9p (H1 earnings per share were 37.9p, so this is easily covered).
One remarkable fact about these results is that the company has earned more PBT in H1 than they did in the entire previous financial year.
Precious metals purchasing: this is the standout performer with revenues up 141% and gross profit up 130%. The weight purchased was up 50% year-on-year.
I would like to give management credit for strong execution: while the high gold price does provide a windfall, it’s up to management to maximise the opportunity. This they have done:
While the high gold price, which has been well publicised in recent months, is one of the reasons for the increase in weight purchased, improved in store conversations, additional digital advertising following the launch of our new dedicated gold buying website www.ramsdensgoldbuying.co.uk and a TV advertising campaign have all helped too.
Pawnbroking: this is also supported by the gold price, and the Ramsdens loan book is up 30% year-on-year. They will lend 55% of the intrinsic gold value of an item, which they say is less than 40% of an item’s retail value as a pre-owned item. Pawnbroking gross profit is up 18%.
Jewellery retail: revenues here rose 26%, gross profit up 31%.
Currency exchange: the total value exchanged fell 0.5% and gross profit fell 9%. This sector is getting more competitive and Ramsdens themselves offer more competitive rates on their own currency cards.
Outlook is extremely strong as you might expect.
Global factors led to a sustained high gold price in H1, c.50% higher than H1 FY25. Many economists are predicting that the gold price will remain elevated for the remainder of 2026 and all through 2027…
We have a number of stores in their infancy which have capacity to mature and grow their profitability…
Should the gold price reduce, the Board believes that it will continue to deliver a strong performance, albeit with lower precious metal profits, and that it will remain capable of delivering further growth and rewarding shareholders with a progressive ordinary dividend.
As a result of the record H1 results and considering the macroeconomic backdrop and the continuing strength of the gold price, the Board is pleased to announce an upgrade to the Group's full year profit before tax, which is currently expected to be between £30m and £33m.
They helpfully provide a consensus PBT figure of £28.6m.
CEO comment:
"The Group is in a great position. While the gold profits grab the headlines, the Group has also delivered gross profit growth of 18% in pawnbroking and 31% in retail jewellery. Customer numbers in FX continue to be strong with total currency exchanged broadly flat…
Whilst the economic backdrop remains challenging with increasing employment costs, high interest rates and continued inflation, we remain highly confident in our opportunity to further strengthen the performance of our existing stores while adding new locations, executing against our established long-term growth strategy. Our balance sheet remains strong and our high level of cash generation provides options on how we allocate our capital to achieve growth.
Graham’s view
Let’s start with a gold price chart against sterling. Here’s a view from early 2024 with thanks to BullionbyPost:
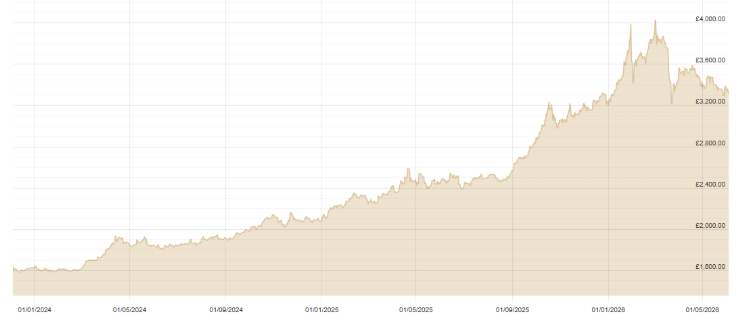
My view on Ramsdens is entirely unchanged from what I said last time: this is a terrific way to gain access to gold exposure. I had a similar trade myself for many years, owning shares in a rival pawnbroker - the one that is no longer listed, sadly. But Ramsdens has picked up the mantle and now provides investors with that opportunity to get gold exposure away from the mining sector (which people like myself find to be a very difficult sector).
Since my comment on this in February, the market cap has increased from £130m to £160m.
And yet if after-tax net income comes in at somewhere around £23.5m (based on PBT of £30-£33m), then we are looking at a P/E multiple of only about 7x this year’s earnings.
It’s important to understand that market forecasts here assume that the gold price is going to fall, so if the gold price merely stays where it is, more upgrades will be coming.
Cavendish, for example, still uses the assumption that the 9-carat gold price in FY September 2027 will be £32/g. The current price is £40/g. As a result, they forecast that EPS will fall from 67p this year to 45.5p next year.
As something of a goldbug, I’m happy to roll with the idea that the gold price has a decent chance of not falling 20% from the current level. That’s not a prediction - but I do think it makes sense for us to stay positive on Ramsdens.
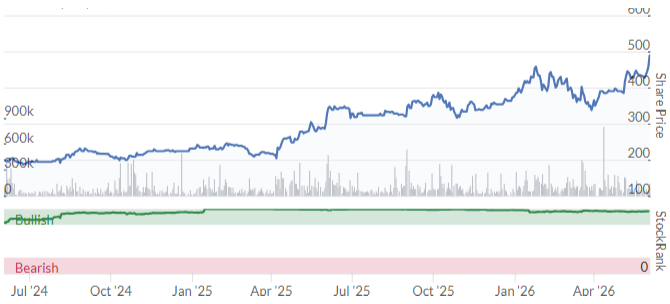
Two-year chart showing very strong Momentum:
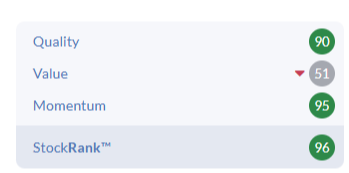
And theStockRank is 96, making this a Super Stock:
Roland's Section
B&M European Value Retail (LON:BME)
Up 16% at 197p (£2.0bn) - FY26 Preliminary Results - Roland - AMBER ↑
We’ve been increasingly cautious about value retailer B&M since it ran into problems in 2024/5 and this view has paid off so far – B&M’s share price is 60% below historic highs and is still c.30% lower than it was one year ago – even after this morning’s gains.
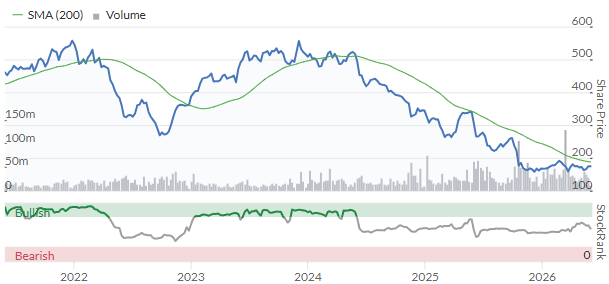
However, today’s results suggest to me that the tide could be turning. Despite flattish sales and a slump in margins, cash generation was good last year and net debt fell.
Operationally, the business is also starting to correct the problems that crept in under previous leadership:
The past six months has seen us sharpen our pricing, improve on-shelf availability in best-selling brands and revamp our in-store promotions. We cleared discontinued lines well in Q4 and are now embarking on SKU count reductions across all our FMCG categories.
Let’s take a closer look at today’s results.
FY26 results: key points
These figures cover the 52 weeks ended 28 March 2026 and highlight sluggish sales, rising costs and plummeting profits:
Revenue up 3.6% to £5,775m
Adj pre-tax profit down 37.7% to £284m
Reported pre-tax profit down 47.3% to £227m
Adj EPS down 36.4% to 21.3p (Stocko consensus: 20.1p)
Net debt (exc leases) down 15.9% to £656m
Dividend down 36% to 9.6p per share
Various adjustments mean that reported pre-tax profit is around 25% lower than the adjusted figure, but I don’t think the adjustments are particularly sinister or surprising:
£36m impairment charge: this relates to an assessment of “individual store profitability” across all three of B&M’s operating segments. It looks like B&M has impaired some store leases and other related assets to reflect reduced expectations for future profitability. This is disappointing, but relatively small in the context of the group’s c.£1.5bn in lease liabilities.
£7m: “significant infrastructure projects” (new warehouses/import facilities)
£7m: redomicile project (moving the plc domicile from Luxembourg to Jersey)
£4m: external costs relating to strategic business projects (planning the Back to B&M Basics project)
£4m: costs incurred in “strategic leadership reset”
Except for the impairment, these are all cash costs. However, I think it’s fair to say they are also one-off items – so investors can choose whether to include or exclude them.
Profitability: I prefer to include the bad news as well as the good news in my view of profits. Using statutory operating profit gives me the following view on profitability:
Operating margin: 6.5% (FY25: 10.2%)
Return on Capital Employed (ROCE): 12.2% (FY25: 18.8%)
Last year’s numbers are well below the levels achieved by B&M in the past, but they are still better than those achieved by Tesco, Sainsbury or Pets at Home over the same FY26 period.
However, one thing that strikes me from today’s results is that the decline in margins seen last year could take some time to reverse, due to the twin pressures of lower bought-in margin and price cuts to stimulate demand in a tough consumer environment:
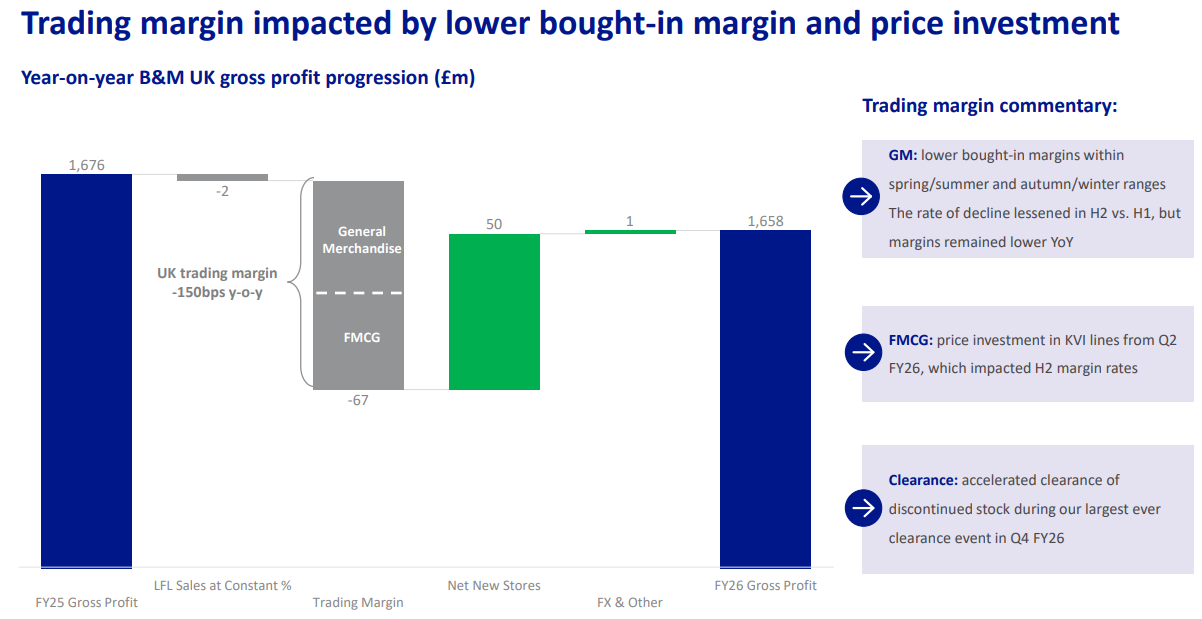
Cash flow & Balance Sheet: one of B&M’s main attractions as an investment historically was its strong profitability and resulting strong cash generation. Reassuringly, my sums suggest cash conversion remained excellent last year:
Free cash flow: £258m (FY25: £258m)
FCF conversion from net profit: 157%
The cash flow statement doesn’t flag up any one-off benefits that I can see last year, so this performance really is very good, in my opinion.
This result also allowed B&M to reduce net debt (excluding leases) by £125m to £656m last year. However, it’s worth pointing out that the fall in EBITDA last year means that overall leverage still increased:
Net debt to EBITDA (exc. leases): 1.4x (FY25: 1.3x)
Net debt to EBITDA (inc. leases): 2.9x (FY25: 2.6x)
I don’t see these multiples as being too concerning given the fall in net debt last year and strong underlying cash generation. But I would like to see bank debt fall further – gross borrowings were still c.£1bn at the end of the year.
I see most large retailers as businesses that should have low levels of bank debt, in order to offset high levels of lease liabilities and supplier credit.
Looking at peers, Pets at Home recently reported a FY26 net debt to EBITDA multiple of 0.1x excluding leases. Currys expects to report net cash excluding leases for FY26.
Trading commentary
Performance across the group’s businesses was mixed last year. The star of the show was the smaller but fast-growing B&M France division:
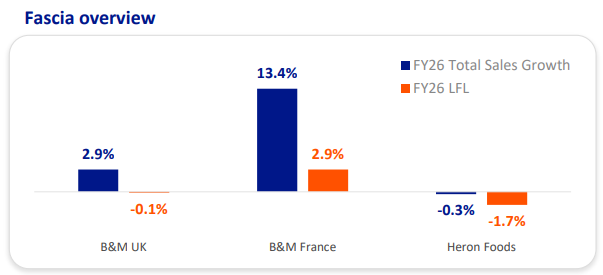
Source: B&M FY26 presentation
B&M UK: “positive value and volume LFL performance” in General Merchandise offset by a continued decline in FMCG LFL sales (branded consumer goods). This is said to be improving as stock availability and ranging choices improve. 41 new store openings and 19 closures (+22 net), taking the total to 799. The company has reiterated its target of growing the UK store estate to c.1,200 stores, opening c.23-35 new stores annually.
B&M France: total sales growth was supported by 12 new store openings, taking the total to 147. The business gained market share to 8.4% of the discount market (FY25: 8.1%). With a store estate <20% of that in the UK, management see a strong runway for growth in France and are targeting at least 15 new stores per year.
Heron Foods (also operates under B&M Express): a poor result from this discount convenience grocery format (a kind of mini-Iceland). Despite having 342 stores, this business contributed <10% of sales and almost no profit last year. I wonder if it could become a candidate for disposal (B&M acquired Heron in 2017).
The French business was also the only division to generate an increased profit last year::
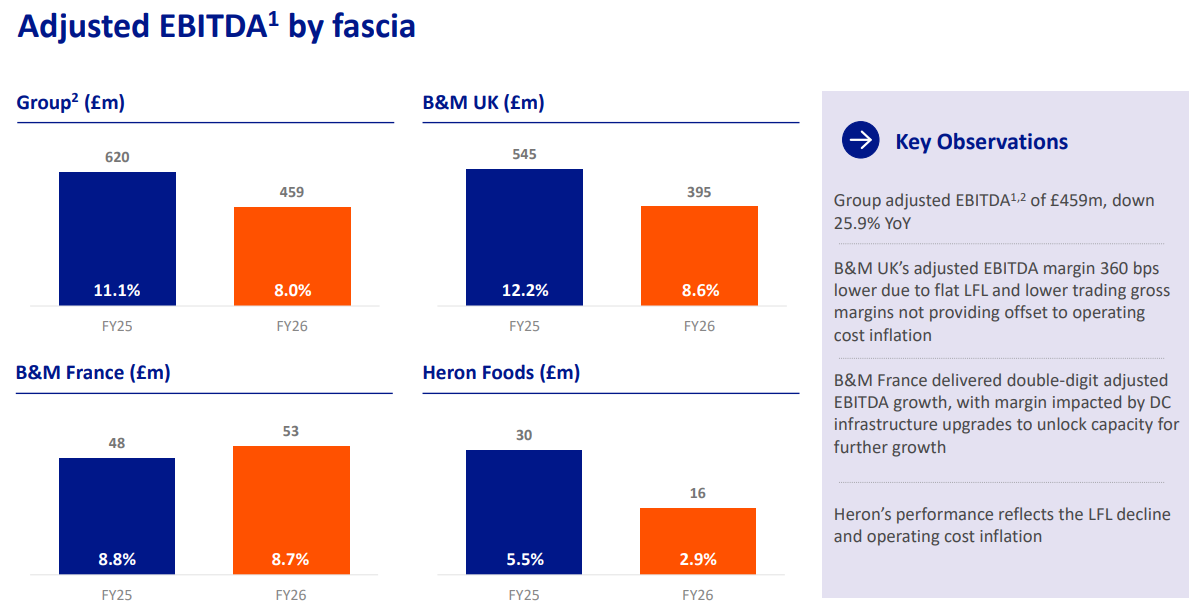
Source: B&M FY26 presentation
Interestingly, even though it's much smaller, the French business generated a return on segment assets of 18.9%, ahead of the 15.4% figure achieved by the much larger UK business. I'd normally expect the larger business to benefit from more favourable economies of scale. This suggests to me that the profitability of some B&M stores in the UK may be a little sub-par.
Outlook
Forward guidance is perhaps the only weakness in today’s results. Turnaround CEO Tjeerd Jegen is not rushing to commit to any near-term financial targets (albeit understandably). Instead, his outlook commentary emphasises near-term cost pressures and his medium-term target for margins:
One certainty of retail is that costs will always rise. In the past year, it was statutory costs in wages and environmental charges that challenged us. In the year ahead, the Middle East conflict will place upward pressure on our international freight, fuel and energy costs.
We are confident we have sufficient levers to offset this impact with cost mitigation. Over time, these benefits will flow through to our bottom line once we have returned B&M UK LFL sales to growth. In the medium term, we continue to see no reason why B&M UK cannot return to double-digit EBITDA margins.
Broker consensus ahead of today’s results suggested B&M’s earnings growth could be minimal in FY27:
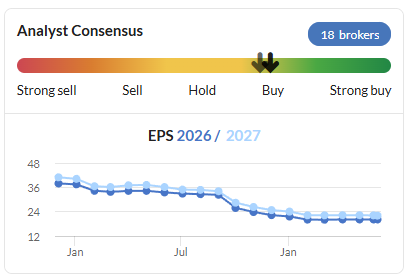
I am inclined to think these forecasts might be nudged up slightly following today’s results, given the 16% share price rise at the time of writing.
However, without any access to broker forecasts, I can't be sure.
Roland’s view
Tjeerd Jegen was appointed CEO with a strong track record in retail at companies including Ahold Delhaize and Tesco.
He has also been a regular buyer of shares since taking charge, investing c.£1.5m over the last year:
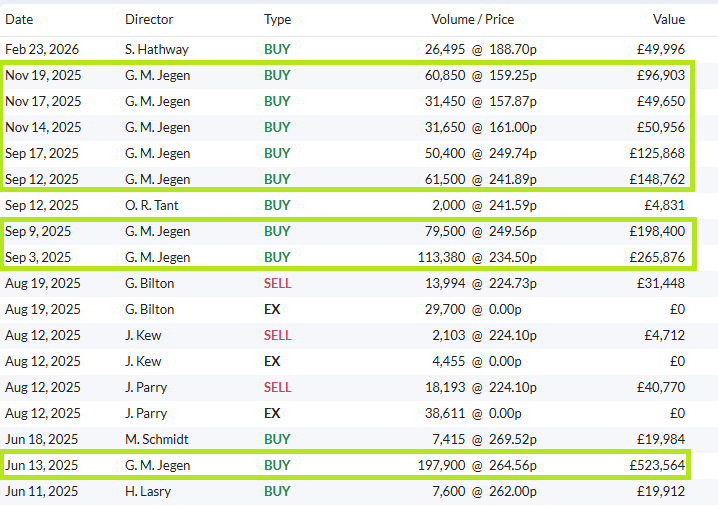
We often say that significant buying by CEOs and CFOs can be a positive leading indicator. No one knows the business better, after all.
Jegen’s record of buying since taking charge reminds me of the regular purchases by Rolls-Royce CEO Tufan Erginbilgic shortly after he started at the industrial group. Those purchases proved to be a signal worth following, although of course there’s no guarantee this will happen at B&M.
Even if FY27 forecasts are unchanged today, B&M shares are still only trading on a P/E of 9 after today’s results, with a prospective dividend yield of perhaps 6%.
I am inclined to think this could be an attractive entry point and I share the StockRanks’ view that B&M could offer a contrarian opportunity:
However, I can still see some risks relating to cost pressures and limited pricing power in the UK, overlaid by B&M's relatively high leverage.
I'm going to upgrade our view on this retailer to neutral today, in the hope that I'll be able to turn positive over the coming year.
Boohoo (LON:DEBS)
Up 25% at 23.5p (£308m) - Q1 FY27 Trading Update - Roland - AMBER ↑
Today’s update from Boohoo is only in line with expectations, but it’s generated a very positive reaction from the market. When I see this combination, I usually assume the market was expecting bad news and is expressing relief.
There is certainly some good news in today’s update, which covers the three months to 31 May:
Group Gross Merchandise Value +0.5% - “returned to growth”
May trading particularly strong, with GMV +8%
Gross margin improved to 53.5% (prior year: 52.1%)
Customer return rate fell by c.5% during the quarter
All of this should add up to an improvement in profit margins and Boohoo confirms this, at least an adjusted EBITDA level:
Adjusted EBITDA margin expanded materially year on year, delivering a substantial increase in Adjusted EBITDA in the period.
The company also reports a decline in exceptional costs (-72%) and capital expenditure (-54%) during the quarter, “keeping the Group firmly on track towards free cash flow generation”.
Outlook
Today’s commentary relates to the FY27 financial year, which ends on 28 Feb 2027. It’s still early in the year, but today’s guidance addresses several key concerns:
Confident in delivering “double-digit adjusted EBITDA growth” relative to the £53m guided for FY26.
Reduction of net debt to less than 1.0x EBITDA is “on track” for the current year. This will be aided by property disposals.
On track to achieve £100m of cost savings through 2027. This would take the cumulative total to c.£200m since the new management team was appointed.
Capex will be 50% lower this year, continuing a trend of reduced spending (FY25: £27.5m, FY26: 16m)
The overall result is expected to be a return to positive free cash flow in FY27.
Broker forecasts from Zeus and Panmure Liberum are unchanged today. Both reiterate a much-improved outlook for FY27, compared to the consensus estimate for a loss of 1.5p per share in FY26:
Panmure Liberum: FY27E adj EPS: 1.6p
Zeus: FY27E adj EPS: 0.9p
There’s quite a wide range between these two estimates, but averaging them gives me a FY27 EPS estimate of 1.25p per share, well ahead of the 0.6p shown in the StockReport.
Based on this morning’s 23p share price, that implies a forward P/E of 18x for the current financial year.
Roland’s view
I’m impressed by the level of cost that’s being stripped out of this business. Assuming the new management team aren’t cutting too deep, I think today’s update adds credibility to the company’s aim of becoming a more profitable and capital-light operation, built around the Debenhams brand and various fast-fashion labels.
If this transition is successful and the business does return to sales growth, then margins could improve quickly due to the beneficial effect of operating leverage on a lower cost base.
I would imagine this is the assumption behind Zeus and PanLib’s medium-term price targets of 56p and 60p respectively.
However, even today’s share price of 23p looks relatively full to me, based on near-term prospects.
Whether Boohoo – or Debenhams Group as it would like to be known – can achieve the hoped-for potential of its changing business model isn’t clear to me.
The eventual outcome for the business is also complicated by the 23% shareholding controlled by Frasers group and the large block of shares owned by the co-founding Kamani family.
We’ve been AMBER/RED on this stock until recently, but I think it’s probably fair to move to a neutral view today to reflect the stabilisation of sales and expected improvements in profitability and free cash flow. AMBER ↑
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
FTSE changes confirmed https://www.lseg.com/en/media-...
Is Boohoo investable after their past outrageous corporate governance shenanigan? B&M European Value Retail (LON:BME) is a victim of the rise of Lidl & Aldi and perhaps TEMU, I doubt they will ever fully recover previous profitability. Gold is massively above its inflation adjusted historic average price, there is a huge risk of mean reversion and that would tank the SP of proxy equities like Ramsdens Holdings (LON:RFX).
Gold miners are just as susceptible as a couple of pawning companies, there's far more at stake so it will be one hell of a total market crash as a result of a mean reversion in the price of physical gold.
Gold price fell for 20 years straight after the 1980 peak and that was before adjusting for inflation. Today it is even more expensive than in 1980 ($3600) in inflation adjusted terms. Caveat emptor.
My mini-portfolio of gold miners is down 10% over the last 3 months, the next 3 months is going to be telling. As Stocko classes it as Speculative I could put a 25% Stop Loss on each company, or, load up at that point.
Will be even lower…..unfortunately.
All the best
Thankyou yiannos.
Ramsdens Holdings (LON:RFX) Thank you Graham for excellent coverage today. As a holder for a number of years I am not surprised by these most encouraging figures. I have taken profits in the past and still sit on a 70%+ gain overall, with the shares representing the second largest holding in one of my portfolios today. My view is that Ramsden’s management has not received the recognition nor commentary that their strategies and decisions deserve. Having shops located in many parts of the country offers a much better proposition to sending unwanted gold/jewelry in a prepaid envelope for evaluation and payment and provides the opportunity for on the spot pawn broking. Their premises attract a lot of attention, especially with their displays of pre-owned watches etc. Their advertising has also been ‘spot on’.
As stated in your commentary, the shares offer an excellent alternative to those involved in gold mining. They also offer the possible upside to the value of gold (which I believe will happen) as and when the war in Iran comes to an end. The fact that a reduction in the price of gold has been factored into projections adds comfort and confidence to present and future stakeholders.
Ramsdens Holdings (LON:RFX)
Boohoo (LON:DEBS)
fair play to current managment here they seem to be doing top notch job of getting basics right - they have taken a reet steaming turd and have polished it into something close to a proper business now - crazy how it took so long for the company to go back to basics though - its always a bit late doing it after you have had to cap in hand to others to keep the lights on - personally with the turnaround going as it it i am not even convinced they needed to raise the funds they did.
Just goes to show what a difference it makes when a compitant captain is steering the ship... Debs is a world known brand...
Mike Ashley didn't sink all that money in to lose it..
Boohoo (LON:DEBS)
Just goes to show what a difference it makes when a compitant captain is steering the ship... Debs is a world known brand...
boohoo and debs is certainly a weird one - i think the leaders just lost touch with reality - boohoo was a great company one minute - next minute they were trying to take over the united staes - other random brands and spending £100 mil plus on corporate heaquarters - i get it the original bods were risk takers to a certian degree but its just unbelievable how far detached from reality they got. Hey ho golbal domination might perhaps have worked under different more stable economic times - i perhaps shouldnt give too much credit to the management - clearly the cash had run out and they were loss making - that doesnt leave many options in the real world - and if one is selling £700 mill plus pa of that you would hope you could at least break even - i have liked the grounded tone of the updates though - simple clear message and on point delivery - compare that to superdy when they were struggling where every update was new excuse - even if it is only getting back to breakeven that no mean feet from where they were.
RE SPACE X and Anthropic=Anyone for a Tracker?
I hold SMT and BG US Growth which have stakes in both these. I agree the price mooted for Space X is seemingly big ( like Dan Quayle said ' Space is big' ). My gut says Anthropic will have a better reception. I assume a lock up for long term holders will apply as neither of these 2 Trusts would not want to reduce. More of a concern is what impact does the need for Tracker to obtain stakes in these companies produce and how will they fund these positions. Could this have a material impact on other companies in the index. Is there sufficient liquidity in the market to absorb these floats and does the retail element suggest there are issues with the latter.
My very grubby crystal ball( finger in the air) says Space X valuation around 1T is about right so some downside but Musk is marmite and TESLA has never conformed with any standard metrics on company valuation. Buckle up for the ride? I would have thought with the cash from the float other Space linked companies were potential beneficiaries if only from a transparency point of view
Interested in other people's views
Have a look at the constituents of Schiehallion Fund (LON:MNTS) . 7.3% of their fund is invested in Anthropic and 11.8% in Space Exploration Techonolgies
Hi Yes looked at it before. I struggle with the Bending Spoons position given it is hardly a run away success.
Hopefully the real world realities here are starting to take affect - i would not be betting against anyone AI related doing very well. I wouldnt presume though that they will all succeeed - its easy to look at the likes of apple - amazon - google - etc - and see that what might look a toppy valaution now - isnt necessarily head the ball stuff.
I have seen interetsing recent comments ( ihavent really fact checked) - that companies like Microsoft et al have been spending money on ai token purchases at sucha quick rate - that effectively what one engineer may spen on tokens may exceed their salary - so if you are paying them and AI - you need multiplles of vulume of delivery from that worker using AI.
Note whats perhaps most jaundiced here is that the likes of microsoft et al may have also been making investments in the companies they are buying AI tokens form - so whilst they are handing over the cash - and seing their investment grow - the reality is that some of the great growth shown by AI companies may not be on complete arms length basis.
That just makes it messy.
would be intersting to see in 6 months time - if someone has us tyracker fund - what % of those funds are tied up in the biggest 10 tech companies - its easy for 2 trillion to become 1 trillion. The us market seems to have avoided any major crashes (that havent bounced back)in that regard over then recent term - i think.
You ignore america at you peril - over the years i kinda shied away from the us tracker funds and have probably underperformed others due to that - when i do us i tend to pick companies - and i aint always picked great ones depsite america looking easier to makie picks from.
' More of a concern is what impact does the need for Tracker to obtain stakes in these companies produce and how will they fund these positions'
There is an article on this very topic in this morning's FT written by the chief investment officer of Vanguard Capital Management. A company's weight in an index is based on the shares investors can actually buy, not including unlisted shares. According to Reuters, SpaceX plan to set an IPO price of $135 per share, targeting a $75 billion dollar cash raise. This is not a trivial sum of course, but it's a fraction of the $1.8 trillion total figure being thrown about. The other shares will continue to be held by insiders and other private investors.
I see that Vanguard's S&P 500 tracker has become the first $1 trillion ETF as people pile money into it ready for the forthcoming IPOs. It's looking as if the market will absorb the IPOs quite easily.
Space X shares will be one crashed rocket away from a significant fall. Space X has been very reliable so far but sending rockets into space without setbacks should not be taken for granted.
If you have a chance to have a ramble on Ninety One (LON:N91) team would be appreciated no pressure if your already stacked out with possibles.
anyone know why wise is down again ?? maybe penalty harsher ?
It traded off in the US ....but all just noise really at the moment. As I hinted and famous last words but Id be surprised if much comes of this money laundering stuff.... and no doubt this type of things gets looked at a lot. Id be amazed if they get caught out because it's way too obvious but probably eat my words. Funny to me that it conveniently surfaces now when the Nasdaq listing has gone so badly but it makes a nice price to close shorts or set up longs for a bounce. Would be nice to understand why the introduction to Nasdaq flopped so badly - best guess is a load of loose stock only holding for the listing pop has overwhelmed demand in the short term....and I can't really get my head round the valuation tbh .... but tempting to bottom fish.
Wise (LON:WISE)
what you never want to be in shares - is in an information void when others have a much better picture of the how price sensative that info void will impact the future compared to you - and you will perhaps be the last to find out if future news is good or bad. Its not to different to the market hating uncertainty. so on the basis the 500 milion euros being looked at by belgian prsecutors might or might not have a material impact on future events - well the market aint going to like it and you have to expect ity might not be pretty - it might end up as much ado about nothing - perhaps if they have found 500 mill of dodgy items - well that might be thne tip of the iceberg. Its matter of fact business and people can easily lump fraudulent transfers of ill gotten gains in withn legit transactions - Wise jhaev an almost impossible job of flagging up items where the "laundered" dosh is hidden in plain sight or might have innocent explanation - it cant be unususal for folfs to move m,oney back to country of origin for very legit reasons - how are wise meant to tell if 25% of that is ill gotten gains.
does the share price trend reflect real "inside info" that hasnt been communicated to you yet - heck that might be possible - it might just be natural flow though of people heading for the door - rather than hanging around.
Note wise didnt exectly have uber cheap valuation - so you also have to factor in if you have p/e of 20 plus - when it does not go "exactly as planned" - you can also get rating reduction on top of any of the bad news.
Could wise cope with having funds frozen and the only mechanism for funds being returned is for individuals to prove that funds are from genuine source - all i know is they wouldnt want to be there - and money laundeering rules allow authorities to sieze funds now and questions to be asked later.
This isn't really my understanding - Id say as long as they have made all the right checks etc - then the transfers are legitimate - and unlikely to be challenged. If they haven't this is a rather obvious own goal which I would be very surprised they have fallen foul of. Not least because it is mission critical to confidence in their business. I am happy to be proven wrong but I don't see it being any more difficult for Wise (NSQ:WSE) than a bank etc to identify who is who and turn away business that doesn't look whiter than white.
I have used Wise to transfer money, you do have to give a reason, for the transfer. With banks, l just transfer the money. I did have a load of problems with my bank, blocking transfers, about 2 years ago. Had to go through security several times, which took about 30 minutes each time, numerous stupid questions, they said it should not be blocked, try again, same thing happened, then have go through all that security again.
Recently it has not been a problem.
What checks are Wise supposed to make? If l transfer money to Joe Bloggs in Vietnam.
It's all very interesting - Saxo wanted me to confirm where my deposit came from and although I felt like saying none of your business - since it was my SIPP tax free lump sum I let them know. The thing is - since it was being trasferred to them from a UK bank - it is clean whatever it is from. At the point money enters the system it need to be conformed it is what you say it is - and normally confirming you are you is enough. Cash is a problem - you will struggle to walk up to a bank with a suitcase full of money these days....except in Switzerland. Although I believe the Swiss are a little more sensitive to Arabs arriving with suitcases these days. So for me and I could well be wrong - the issue for Wise is not acting for criminals etc its that they don't verify people and allow various transactions say cash to Europe ....but this would be so" unwise" especially given their ambitions ....I would fall off my chair. Much more likely is money is disguised in a corporate shield and they haven't checked out the company well enough ....and the underlying owners fall foul of the rules. In this case depending on who needs to take the fall the company have an issue but probably not life threatening. Personally I continue to believe it's a risk for Wise (NSQ:WSE) but since everything they do relies on trust I would be amazed if this is any more than a slap wrist job. Famous last words..... but a 28% share price fall when most people expected it to rise is tempting.
axo wanted me to confirm where my deposit came from
The thing is - since it was being trasferred to them from a UK bank - it is clean whatever it is from
that an outdated view as as to how money laundering works "now" its not like it used to be. ie "now you cant simply cycle cash via uk acount and presume its clean " - the enhanced checks may catch you up on that if there isnt the backup of business earning profits that allow withdrawals - the onus is rightly on you to evidence fully that source funds were totally legit with reasonable trail - i had this when i sold a boat load of shares - put funds into premium bonds before buying rental property- they wanted proper evidence showing the trail backover and flowed through (handily had capital gains comp) . the fact funds may have come from legit source means nothing - it could simply be that the bank and acountant and powers that be havent realised they may have been dodgy.
this is the problem wise have - its so easy to put dodgy stuff in withn legit transactions - thje expectation now that checks are being made is different levels above where it used to be. Just look at all the fines ditched out to estate agents to see how the rules now are uber tough.
I am happy to be proven wrong but I don't see it being any more difficult for Wise (NSQ:WSE) than a bank etc to identify who is who and turn away business that doesn't look whiter than white.
Wise (LON:WISE)
the way i see it most banks tend to deal with flow of funds that stay within the country of origin - other than payments going overseas to the obvious knows trusted entities.
Go to hsbc or barclays and tell them you are opening a branch in Azerbaijan - start movinmg your legit setup funds to that country and see if hsbc and barclays wont close dont your acount - i would be surprised if they wouldnt at least have issues. I have seen plenty of clients have bank acounts closed with no explanation from uk banks - they have done little more than go on holiday to us - or bought the odd item from usa.
Whats the first thing you want to do with laundered money ?- well pretty obviously get it out the country as soon as you can - well thast right up wises streeet as the vehicle to do that.
So your average banks will generally have very little volume of such stuff when for wise its bread and butter - plus to boot they dont have the advantage of having access to all the day to day bank transactions that would allow them to do ongoing checks - they only tend to get involved when its about to go overseas - so they have to make decisions witha fraction of the info that the bank have.
Note i am not saying wise arent up to the job of doing it right - its clear to me here many of the comparisons being made are slightly naive with regard to the realities of what is expected ref due diligence nowadays compared to how it was in the past.
If nothing else at least this current investigation does give them the chance to prove that at least as far as this particular belgian prsecutor is concerned that they have hopefully met their legal obligations - plus also not pout themselves at risk should moeny be confiscated - hopefully if funds are confiscated by the authorities they have agreement with "their customers" that that its their teh customers problem and not thant of wise. What happens if its found our wise passed funds over though that were proceeds of crime - could the authorities say that even though its been handed over to third part - as dirty money that was in wises hands they need to hand it back ? - obviosult allegations made by the belgians may be wide of the mark,
Some interesting commentary on Wise (LON:WISE) from UK portfolio manager Andrew Hollingworth:
Wise is one of our top holdings. Its shares fell c.10% yesterday on fears it is being investigated for failing to comply with money laundering regulation. Whilst we don’t give a running commentary on our holdings, yesterday’s market fears we thought were interesting and revealing.
Is a financial/payment institution vulnerable to misuse by bad actors/money laundering? Absolutely. The best managers that oversee such businesses know this and realise the crucial role that ‘trust’ plays in the business of money. As such compliance must be strict and oversight well-enforced, not just lip service. Any suggestion to the contrary can result in investors becoming nervous, so share price falls are understandable when new stories surface. Notable we thought in the Wise RNS statement yesterday was the following text:
“Around one third of Wise’s global team is dedicated to protecting our customers from financial crime.”
We knew this fact before today and think the company right to again bring it to investors’ attention. Compliance, money laundering and fraud are the under-reported moat around the best financial service businesses. In that context we think not only is Wise extremely well placed, but its ongoing adherence with so many global regulatory licences (80 and counting) in fact widens its moat.
Wise vs Facebook of old
Below is an extract from a 2021 research piece of ours on Facebook (now Meta). We hope readers will see the parallel:
This issue raised further the important debate about safety online and the use of a huge amount company resources and systems like AI to manage the various Facebook social networks to make them safer. Across 150 languages the cost of such compliance is now enormous with Facebook claiming it was employing 20,000 people and spending c.$5bn on the process in 2021 alone. Whether from politicians or activists the question constantly being asked is, “yes, but is that still enough?” In truth it is for regulators to answer this question, not for us as investors.
What we think investors should be doing however is seeing the other side of this coin. They need to be considering that all this investment is creating a far stronger and hopefully in time a far more trusted and safer network. It will also be a far more compliant network, in many many more languages. If Facebook was a hard business to replicate three years ago in terms of scale and reach, the new compliance requirements just made its moat 10 feet wider.
This we think is an important point. Many in US politics and the media are rushing to complain about the state of social networks today, but they are not considering what they might look like tomorrow. If regulators one day required greater compliance by social networks, which companies will best be able to comply? Source: Holland Advisors: Facebook/Meta – Owner Manager Inc., Nov21
Wise words from a Wise man
Some of the powerful financial networks of the future will be online businesses who today are far smaller than incumbent banks. Those that win will have great entrepreneurs leading them and powerful low-cost digital empowered business models. However, such companies will not get a second chance if they lose the trust of consumers or regulators. We have heard Wise talk about this fact time and again and know (and can see) how seriously they take this responsibility. See links below.
The analogy with Facebook we think can be taken further. When we were writing about Facebook in 2021, other investors saw two threats to the business. One was new competitor networks emerging and the second was the huge regulatory compliance burden. We saw the second (if handled correctly) as a reason why competitors would find entering this space far harder than say c.10 years before.
With much investor discussion lately on how easily stablecoins can make money transfers quicker and easier, far too little attention has been paid to the importance role of policing fraud and money laundering. Regulation and compliance is very very hard to do, real time, every day in 40 currencies. This moat might be unsexy, but its huge. Thankfully, some in the industry see clearly that the future will require a balance between low friction, low cost, instant money transfers and ‘being regulatory compliant and legitimate from a financial crime perspective’. In case you wonder who said that and when, see below!
“Stablecoins are becoming a more visible part of the payments ecosystem and could be an exciting development in how money moves globally. At Wise, we have spent more than a decade building the infrastructure that delivers what many see as the promise of stablecoins: instant, low-cost and reliable cross-border payments. New technology will not only need to improve upon the speed and cost of our cross-border transfers, but it will also need to do so in a safe way – being regulatory compliant and legitimate from a financial crime perspective.” Kristo Kaarmann, Wise Plc, interim results, September 2025
Today Wise is in Mr Market’s cross hairs, but we think it will be a long-term beneficiary of the rightly required high level of compliance of global money networks.
Wise (LON:WISE)
is the danger though that whatever wise are throwing at the problem might not be enough ? you say regulation is a moat - i say regulation is a nightmare waiting for the book to be thrown at any listed company. Just look at uk listed Close Brothers (LON:CBG) - they have ben around for yonks are a listed company in stable area of simple business - and they have been hauled through the coals. The reality with any listed company is that fca and the like are only ever a negative when they exist - you might be right that those that do go above and beyond do have a moat - do wise need to play around the edges to get business done though ? all i know if the amount of agencies they have to deal with makes that an enormous task - its good that they clearly have systems in place and they are more token ? are they enough though with regard to "upholding the highest standards being demanded" - well thats another thing. At face value if there is 500 million of dodgy funds that Wise didnt "spot" or spotted to late - well should that not be a worry ?- its not exactly trifling amounts if that value needed to be confiscated.
Well I am on the side of Spacex ipo being too expensive too. But hey, I'm a contrarian and I don't know enough about it to really make a call. What I would say is, if it is such a good price, why is so much being raised by retail? Normally if it is so good a price the institutes would be buying up a far larger percentage. Anyway, what do I know.
Wonder if Scottish Mortgage Investment Trust (LON:SMT) with their long standing holding in SpaceX can be viewed as a bell weather for how the Mkt reacts.
SpaceX has all the hallmarks of a ridiculous situation.... selling $75bn cash investment valued at $2tn ....no earnings - free cash flow etc only a cash burn for a dream. By any standard it's not an investment so line as many fools up as possible ... and with so many index funds in the queue what could possibly go wrong? Good luck to them all and Im glad I can just ignore it. Giving someone $75bn to fire our rare resources into space in the hope of finding a viable business .... you couldn't make it up. Doing amazing things with a lot of money isn't a business... if it fell 80% on day 1 it would still be expensive IMO. Compared to Bitcoin though - at least it does something - ha ha apologies to all but just because it might go up, it isn't an investment.
The Iran war kicking off again, crude remains relatively low considering (though there is a disparity between the market price and the price really been paid for the physical), huge debt across the world, Russia threatening the use of tactical nuclear bombs and sky high valuation IPO's. What could possibly go wrong? Personally I think we are due a major market crash, and I don't mean the corrections we have seen over the last few years. Lets just get the IPO money taken first, because who would invest in an ipo if the market had crashed?
I had the good fortune for a Goldmans Buy the UK note to pass over my desk yesterday - reminding investors the UK has merit. Research - Services and defence being strengths not reflected in discounts on equities and bonds. Nice to be reminded all is not lost for dear old Blighty and IMO never too bad if the mighty vampire thinks we are attractive.
I'm in Vilnius today, there are 5 Unicorns within walking distance of the old town. The Nato /Ukraine defence technology conference is on here and a worldwide business angels investor meet is taking place. Which country has no attendees? All the payments systems here are built in Lithuania. I was here 35 years ago when the British thought the country too small to be of interest. We are about to miss out on AI. Why is Vinted here and not in Newcastle or Edinburgh or Bristol?
Poland is set to overtake the UK in GDP per capita in the next five years.
Would be interested how Rachel Reeves explains why this has happened.
Would be interested how Rachel Reeves explains why this has happened.
she will be blaming the person doing her current job at that time
I don't particularly like Rachael Reeves, but its fair to say that Brexit and the Iran war have damaged the UK economy. Neither of these is her fault.
I think its 25-30 years of poor decisions that have got the UK to where it is accelerated in 2008 when politicians sent QE into overdrive thinking inflation and interest rates would stay low forever.
The Iran war has definitely hurt the UK economy this year. This isn't Rachel Reeves fault but I think the fact that the UK has the highest number of neets in the G7 is her fault. This is traceable to her inflation busting minimum wage and increased employers charges of national insurance.
Your note also blames Brexit for our decline. However once the EU was formed it consisted of 27% of world GDP whereas now it is only17% of GDP despite being joined by other countries. The recent struggles of France and Germany do not suggest to me that we are missing out. Nor does the continuing decline of the EU in the world economy.
In the circumstances I think we need a broader global based approach.
I read the other day (not sure where) that some expect Poland to overtake the UK in GDP per capita by the end of THIS year.
And I believe you can walk the streets without being blown up/stabbed etc..just saying :-)
Ramsdens HY seems impressive for a pawnshop company, forecasting above expectations for FY and interim dividend up 33% plus 3p special dividend. We hold and wait to see the markets reaction after a recent rally.
Ramsdens Holdings (LON:RFX)
I think "pawn shop company" is a little wide of the mark. I have held for 2 years, but top sliced a little early on the way up.
I would say you did top slice a little too early. Another upgrade on top of the recent upgrade. It is clear that people will be finding inflation a problem in the coming year and therefore more people will be using their local pawn broker to get cash. All good news for Ramsdens Holdings (LON:RFX) . Cavendish have conservatively upgraded their target price to £5.96 and suggest further upgrades will likely come. PE for the full year of 2026 is just 6.8, so still cheap.
Pawnshop certainly well wide of the mark with their foreign currency dealings and precious metals sales nowadays, coupled with their position of lender of first and last resort for many with poor credit scores finding themselves in need of temporary financial assistance. Like several commenting I took my gains from a holding in RFX as gold seemed to peak and be falling in price coupled with a drop in RFX share price from January, but thanks to this daily analysis I have been quick to swap a poorly performing equity for another investment with Ramsdens. Interestingly the Financial Times ran a good article yesterday stating that physical gold storage, was now well ahead of the US dollar for the central banks of many countries wanting to safely store their wealth and this is likely to make holdings recently reported on in SRB and RFX even more secure.