Daily Stock Market Report (Wed 3rd September 2025) - WOSG, CHH, MNG, CRN, HFG

Welcome to Wednesday's report!
All done for now, see you tomorrow!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ashtead (LON:AHT) (£22.8bn) | Rev +2%, adj PBT -4% to $552m. FY26 rev exps unch, free cash flow $2.2-2.5bn (prev. $2-2.3bn). | ||
M&G (LON:MNG) (£6.2bn) | Adj op profit ~flat at £378m, asset mgt net flows +£2.6bn. AUM +2.5% to £354.6bn vs Dec 24. Reuters: adj op profit below market consensus of £398m. | AMBER (Roland) According to the newswire, today’s operating profit is slightly below consensus expectations. Even so, results from this complex business look broadly as expected to me at a high level, and do not appear to flag up any serious concerns. I’m also encouraged by possible signs of a return to growth in PruFunds and overall net inflows. Although asset management growth is not yet sufficient to offset outflows from the group’s legacy Life products, progress seems positive. On balance, I feel M&G’s valuation is probably up with events after a c.25% rise this year. However, I remain confident in the 8% yield and would view M&G as worth considering for a high-yield income strategy. | |
Bakkavor (LON:BAKK) (£1.32bn) | Rev +0.9%, adj op profit +9.8% to £61.5m. FY25 adj op profit (cont) to be at upper end of range. | PINK (under offer) | |
| Cairn Homes (LON:CRN) (£1.16bn) | Half Year Results | Rev -22%, op profit -30% to €42.7m. FY25 op profit now exp c.€160-165m (prev. c.€160m) | AMBER/GREEN (Graham) Very healthy trading at Cairn: I'm impressed by management here, and I think the company is very well-positioned both economically and in the political context. However, balance sheet tangible equity is only €760m (£660m) and the shares are trading at a very rich premium to this level. That has to count for something: I usually wait for housebuilders to trade at a discount before getting too excited about them. On that basis I can’t be overly positive on this stock, no matter how well it’s trading right now. I leave my existing stance unchanged |
Watches of Switzerland (LON:WOSG) (£744m) | SP +7% H1 results to be in line with exps. Strong trading in US despite tariffs. UK stable w/ YoY growth. | AMBER/GREEN (Graham) A reassuring update and the market has reacted strongly to it. I'm upgrading my stance on this by one notch as I think the shares may offer some value here. The luxury watch market has apparently become very stable and predictable, creating nice conditions for WOSG. At a single-digit P/E multiple, I'm willing to stick my neck out and suggest that this may offer some value here - but based on my track record here, I'll probably change my mind again next time I look at this one! | |
Hilton Food (LON:HFG) (£739m) | SP -16% Rev +7.6%, volume +2.5%. PBT -4.7% to £24.3m. Cost inflation. FY25 to be within range of exps. Shore Capital updated forecasts: FY25E EPS: 60.4p (prev. 62.0p). FY26E EPS: 65.9p (prev. 67.2p) | AMBER (Roland) [no section below] This may not technically be a profit warning, but it looks like a slight downgrade to me for this meat/fish producer. Hilton is reporting difficult trading in its salmon business and broker Shore Capital has trimmed its FY25 earnings forecasts today. Hilton has attractive market share, but this is a very low margin business that’s also exposed to pressure on pricing (from supermarket buyers) and higher input costs. While returns on capital have been adequate in the past, debt levels have risen sharply over the last year. There are some attractive growth opportunities on the horizon – with Walmart in Canada, for example – but this isn’t a stock I’d want to buy on a high rating. After today’s indifferent update, I’m inclined to take a neutral view. | |
Naked Wines (LON:WINE) (£62m) | Trading in line with FY26 guidance. Adj EBITDA and cash generation ahead of FY25. | ||
Aoti (LON:AOTI) (£59m) | TWO2 is now active on NHS Supply Chain Framework, allowing AOTI to accelerate marketing. | ||
Videndum (LON:VID) (£49m) | VID will focus on core professional markets. Proceeds undisclosed, will be used for debt repayment. | ||
Churchill China (LON:CHH) (£47m) | Rev -5%. Adj. PBT -35% (£3.1m). Net cash £5.6m. “Performing well within… a difficult trading environment.” | AMBER (Roland holds) These results appear to be in line with July’s reduced expectations. They show Churchill continuing to invest in areas such as automation in order to control its cost base and improve its competitive positioning. However, in a market where demand (and pricing power) are depressed, the company has not been able to fully compensate for higher labour and energy costs. Churchill remains a market leader and the combination of net cash and a share price below tangible net asset value suggest to me that the stock is probably attractively priced. However, there doesn’t seem to be any sign that external conditions are improving, so I feel there might be more compelling opportunities available today. For this reason, I’m staying neutral. | |
Ondo InsurTech (LON:ONDO) (£43m) | Two-year agreement with Admiral to continue offering Leakbot to home insurance customers. | ||
Gelion (LON:GELN) (£36m) | Major technical milestone in advancing Gelion’s next-gen battery technologies. | ||
Maintel Holdings (LON:MAI) (£26m) | Delays in pipeline closures and loss of a key deal. New revenue guidance £95m, adj. EBITDA £7m. | BLACK (StockReport: previous revenue expectation was £101m). | |
James Cropper (LON:CRPR) (£23m) | Confident in full year performance. Recent 18-week period is slightly ahead of exps in both divisions. | ||
Cirata (LON:CRTA) (£23m) | Outlook unchanged. H1 revenue $4.8m (+41%), adj. EBITDA loss $4m (H1 last year: loss $9.6m). |
Graham's Section
Watches of Switzerland (LON:WOSG)
Up 7% to 342p (£814m) - AGM Trading Update - Graham - AMBER/GREEN
We have an “in line” update from this watch retailer.
As a Burberry shareholder for many years (to my detriment, it could be argued!), I like to keep an eye on the luxury watch market, as it sits adjacent to luxury clothing..
WOSG reports stability in the UK, and consistently strong trading, particularly in the US.
We are delighted with the success of the flagship Rolex Boutique on Old Bond Street, London, which is exceeding our expectations. The response from clients has been excellent and traffic levels and conversion rates are very good. The Rolex Certified Pre-Owned salon on the lower ground floor is fast becoming the destination for Rolex aficionados.
Roberto Coin Inc, the acquired distributor of Roberto Coin products in the United States, is also “performing strongly”.
We plan to grow and develop the Roberto Coin brand and have launched an impactful advertising campaign featuring Dakota Johnson as global brand ambassador. Elevation and brand expansion within our own showrooms is proving very successful. We continue to develop and refine the offering and there are opportunities to extend this to our retail partners.
Showroom projects: detail provided on various refurbishments, openings and relocations in the UK and the US - there seems to be very active management of the store portfolio.
Outlook: performing is “encouraging and in line” with guidance given in July.
That guidance was for revenue growth of 6-10% (at constant currencies), and for flat to minus 100bps adjusted EBIT margin.
They are not expecting “any material impact” from US tariffs in H1 FY2026, which is the period from May to October 2025 (year-end is April 2026), which they say is due to increased inventories. So presumably the impact will be felt once these inventories have run out and need to be replenished?
Graham’s view
The luxury watch market appears to have fully stabilised, providing pleasant and predictable trading conditions for WOSG.
While other retailers have reported on a weak consumer - has the cost of living crisis really ended? - the luxury end of the market seems to be holding up well.
WOSG benefits from earning nearly half of its revenue in the US. US luxury consumer spending has been under some pressure in recent years, but it’s an enormous market in which to expand.
On valuation grounds, I think I’ll allow my stance on this to tick back up to AMBER/GREEN today. I’m hovering between AMBER and AMBER/GREEN, but the share price today is has dipped a little compared to when I reviewed it last. This earnings multiple is modest - this is based on last night’s close:
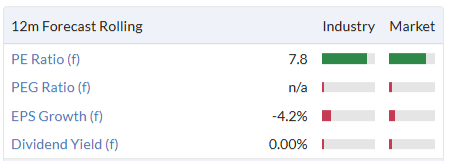
Bear in mind that EPS estimates have been under some pressure:
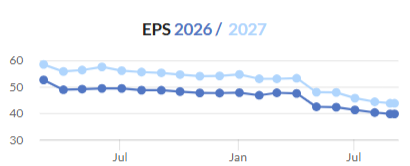
This is not a particularly high-quality company in terms of having clean accounts (it doesn’t), brand ownership or quality metrics. It’s a capital-intensive, economically exposed retailer of 3rd-party brands. But I’m willing to stick my neck out and say it may offer a little value here! Although given my track record, I’ll probably switch back to AMBER again next time!
Cairn Homes (LON:CRN)
Down 3% to 181p (£1.14bn) - Results for the Six Months Ended 30 June 2025 - Graham - AMBER/GREEN
Cairn Homes plc (“Cairn”, the “Company” or the “Group”) (Euronext Dublin: C5H / LSE: CRN) today announces its interim results for the six months ended 30 June 2025.
This Irish housebuilder is dual-listed on both Euronext and the LSE.
Its share price has increased only marginally since I last reviewed it in January, when I took a moderately positive stance.
The company is benefiting from a housing shortage in Ireland that is most acute when it comes to rentals, but is also very significant in the buying market. Cairn primarily caters to first-time buyers:
Our strategy of significant investment in construction activities and operational scaling is clearly delivering, with exceptionally strong sales in H1 2025, notably from First Time Buyers (FTBs), driving €625 million growth in our closed and forward order book to 4,092 new homes (€1.54 billion net sales value). This underpins our expected H2 delivery and another year of growth in revenue and profitability, supporting our upgraded FY25 guidance and new FY26 guidance provided today.
H1 revenues falls from €366m to €274m - this is pinned on “transaction timing and mix” compared to H1 last year, and there’s an H2 weighting.
With such a large revenue fall, it’s not surprising that measures of profitability are all down in H1 compared to H1 last year.
But what matters more is the full-year outlook, and that is upgraded as follows:
Revenue of c.€945 million (previously revenue growth in excess of 10%);
Operating profit of c.€160 – c.€165 million (previously c.€160 million); and
ROE of c.15.5%...
I note that the revenue outlook has in fact slightly deteriorated, as the new revenue guidance represents growth of 10%, not “in excess of 10%”.
But the operating profit figure looks set to exceed the previous target, and the forecast ROE is excellent.
Let’s turn to the new FY26 guidance:
Revenue of c.€1.02 – c.€1.05 billion;
Operating profit of c.€175 – c.€180 million; and
ROE of c.16.0%...
It’s still very early, but these will be great results if they are achieved.
CEO comment:
the business is performing strongly, our strategy is working, and we have doubled down on investment in our construction activities. As this unwinds, it will lead to a strong second half which is why we are raising our guidance today for 2025 and also introducing new guidance as a result of increased housing output for 2026.
In keeping build cost inflation under control, maintaining average sales price consistency, and placing a strong emphasis on energy efficiency, a well-designed Cairn home represents an attractive proposition for first time buyers. In parallel, the delivery of cost-effective new homes for our State partners, in mainly scaled apartment developments, plays a critical role in addressing the national housing challenge…
Net debt: €307m has almost doubled year-on-year. I note that inventories are up year-on-year by €170m, driven by higher construction work-in-progress. So hopefully this will unwind as H2 progresses and as work is completed and exchanged.
Buybacks: the company has completed a €45m share buyback programme. I’m not convinced that Cairn shares are obviously cheap right now, so I’d be nervous if the company were to launch another large buyback.
Graham’s view
Not enough companies use ROE as a key metric for management for their investors. Cairn uses it prominently and is showing a knack for delivering it.
More broadly, Cairn continues to look very well-positioned to me. It devotes a large section in today’s report to “supportive policy developments”, outlining various beneficial government policies.
There is heavy government involvement in the Irish housing market, which can be a double-edged sword for a housebuilder, but as things stand the policies are working for Cairn. Cairn provides social and affordable housing for government agencies, and of course it is also reliant on the planning system. On both fronts, it’s a beneficiary of current government priorities.
Its forward order book has ballooned from 2,361 new homes (end of Dec 2024) with a value of €910m to a current level of 4,092 homes (Sep 2025) with a value of €1.54 billion.
For me, this puts to bed any immediate concerns about the debt load and the inventory position.
However, I think I’ll keep my existing AMBER/GREEN stance, rather than giving it an upgrade today.
Balance sheet tangible equity is €760m (£660m) and the shares are trading at a very rich premium to this level.
That has to count for something: I usually wait for housebuilders to trade at a discount before getting too excited about them.
On that basis I can’t be overly positive on this stock, no matter how well it’s trading right now. Experience says that the really juicy opportunities in housebuilders are when they trade much cheaper than this!
Roland's Section
Churchill China (LON:CHH)
Up 0.5% to 432p (£48m) - Roland - Interim Results - AMBER
(At the time of publication, Roland has a long position in CHH.)
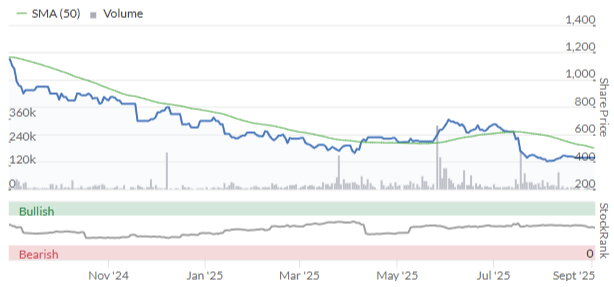
Shareholders in this leading manufacturer of tableware for the hospitality trade have had a torrid time over the last year:
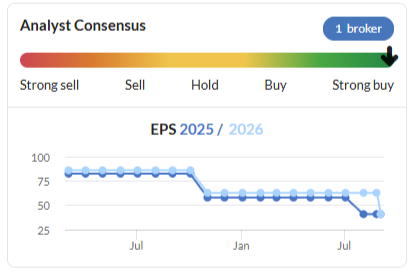
A dramatic slowdown in the hospitality sector has hit sales and profits, culminating in a big profit warning in July (which Mark covered here):
Today’s results give us a fresh opportunity to appraise progress and review Churchill’s accounts, which have historically been strong and conservative. The immediate good news is that there doesn’t seem to be any further change to guidance today – as far as I can see, these results are in line with July’s downgraded expectations.
Whilst the performance in the period has been below that initially expected, as highlighted in our July trading update, the Board believes that the Company is performing well within what is currently a difficult trading environment.
H1 results summary: turning to the accounts, the general theme is that Churchill is maintaining its market share in a contracting market where cost inflation is also an issue.
The financial headlines highlight a nasty dose of reverse operating leverage, with profits falling much faster than sales as lower volumes are spread across a relatively high fixed cost base:
Revenue -5.2% to £38.5m
Pre-tax profit down 35.4% to £3.1m
Adj EPS -35.9% to 21.0p
Interim dividend -39.1% to 7.0p per share
Net cash -28% to £5.6m
The dividend cut had already been flagged up by broker forecasts on Stockopedia, but it’s still a blow for income-seeking shareholders like myself. It’s a prudent decision though – it makes no sense for the company to run down its cash reserves paying an uncovered dividend.
Today’s management commentary confirms that the company was not able to increase prices sufficiently to offset lower volumes and higher employment costs, which equate to £1.5m on an annualised basis.
However, the company is continue to invest in automation and modernisation in an effort to reduce its production costs and maintain competitive positioning:
Our focus internally is on reducing our cost base without damaging core skills and on employing capital spend to bring down cost of production and enable new product launches at competitive price points.
Another cost headwind is energy. Churchill has switched much of its energy usage from gas to electricity to reduce its carbon footprint but is not seeing any reduction in costs due to the high cost of UK electricity, relative to gas.
The company would like to add more solar generation to its sites but says that grid bottlenecks mean that no new solar will be able to be added to the grid until 2032, “hampering our transition to a lower carbon environment”.
Management are engaging with the UK government and other relevant organisations to press for change on these issues – as I imagine many other UK industrial firms are doing. But there’s no doubt the twin issues of grid connection delays and high electricity prices are a competitive headwind for UK businesses at the moment.
Geographic results: UK investors tend to associate Churchill with the UK market – and the company is a major supplier to this sector, including large chains such as Wetherspoon. However, European exports are equally important:
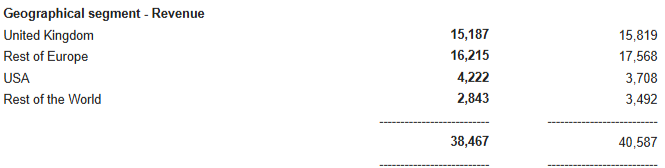
Management say trading in Germany was particularly weak in H1, as the company is more heavily exposed to independent operators in this market than in the UK. Similar dynamics applied in the Rest of the World markets, where new restaurant openings were down and transaction values reduced.
However, sales in the US actually rose by 1.6% despite some turbulence caused by tariffs. Churchill has increased its stockholding in the US to improve its service proposition, noting that it has been “taking advantage of service problems” suffered by competitors. Perhaps this could be a medium-term growth opportunity.
Balance sheet: the balance sheet remains relatively strong in my view, with net cash of £5.6m and scope for further cash generation from planned inventory reductions in H2.
My sums suggest a net tangible asset value of just under £52m or 470p per share, excluding the pension surplus.
The shares are currently trading around 10% below this level, suggesting Churchill could be an attractive value opportunity for investors willing to bet on a medium-term recovery.
Outlook
Management believes Churchill is “maintaining share in key territories” and is outperforming the market in the UK and USA.
The company can’t control external conditions, but is using Churchill’s strong cash position to invest capital in automation and other improvements that should help to reduce ongoing operating costs. This could support an attractive recovery in profits when (if?) volumes do start to recover.
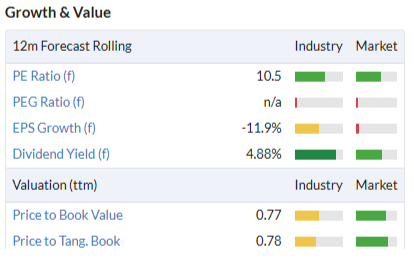
I don’t have access to any broker notes today, but my feeling from these results is that full year expectations are likely to remain unchanged. Stockopedia’s consensus figures show earnings of 40.9p per share in both 2025 and 2026, putting Churchill on a P/E of around 10. The reduced dividend is expected to provide a 4.9% yield.
This valuation looks pretty undemanding to me, if we assume this year will be a low point for earnings:
Roland’s view
When labour costs are low, companies tend to invest less in automation. When labour costs rise, investing in automation makes more sense. In my view, Churchill is doing all the right things. The business is able to make these decisions because it’s historically maintained a debt free balance sheet with significant net cash.
The cash pile is now somewhat reduced, but remains c.10% of the group’s market cap.
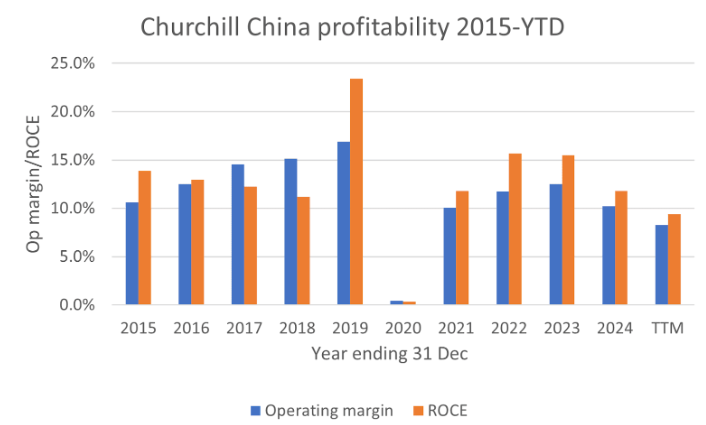
My main concern is that profitability will continue to erode due to difficult market conditions and persistent cost pressures in the UK. However, I don’t think we’re there yet. Today’s interims show profitability at the bottom end of the group’s historic range, but I don’t think the numbers are too alarming yet:
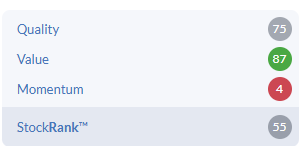
I think Churchill shares look reasonably priced at current levels and could offer significant value in the event that market conditions improve. However the stock’s low MomentumRank is perhaps a warning that the current situation could persist for some time yet:
I’m going to maintain our neutral view today. AMBER
M&G (LON:MNG)
Down 1% to 254p (£6.13bn) - Roland - Interim Results - AMBER
While a private investor might reasonably claim to understand the fine detail of Churchill China’s accounts and business model (see above), very few are likely to be able to make this claim about life insurer and asset manager M&G.
This doesn’t necessarily make this FTSE 100 financial a bad investment, but it is something I always keep in mind when reviewing (and investing in) such stocks. I don’t own M&G shares, but this is a company I’ve followed with interest in recent years, due to its extremely high dividend yield and seeming ability to maintain this payout.
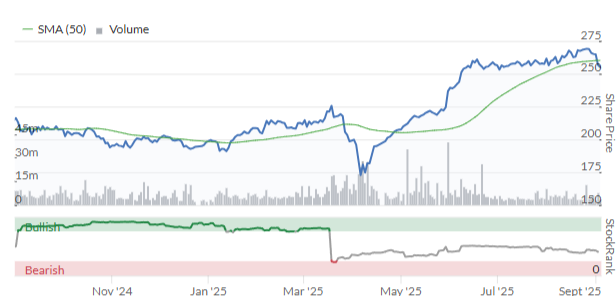
Shareholders who bought M&G at the start of this year, when the dividend yield hit 10%, have subsequently enjoyed a c.25% share price gain that’s reduced the yield to around 8%:
Interestingly, Stockopedia’s algorithms are now flagging the stock as a Momentum Trap:
In my experience, this is a relatively unusual styling for a large, mature financial stock. But it seems that it could be apt today, as the Reuters newswire is reporting that M&G’s half-year profits have come in slightly below consensus expectations today.
Let’s take a look.
Half-year results summary: the main headline numbers reported by the company today present a mixed view of performance, relative to the same period last year:
Net flows from open business of £2.1bn (H1 24: £1.1bn outflow)
Assets under Management or Administration (AUMA) up 3% to £354.6bn
Adjusted operating profit +1% to £378m (vs market consensus of £398m)
Operating capital generation -16% to £408m
Solvency II Coverage Ratio 230% (Dec. 24 223%)
Interim dividend +1.5% to 6.7p per share
Operating capital generation can broadly be seen as equivalent to surplus cash generation. The H1 result equates to just under 17p per share, providing comfortable support for the interim dividend.
The increase in Solvency II coverage (a regulatory measure) reflects the net increase in surplus capital during the half year, despite the payment of last year’s final dividend during the period. I don’t see any concerns here, as this result is well above regulatory requirements.
Segmental results: it’s easier to understand M&G if we divide the business into its two parts, Life and Asset Management. While asset management is a key focus for growth, the Life business remains the main source of profits and surplus cash for dividends:
Asset Mgt op profit: £129m (H1 24: £128m)
Life op profit: £340m (H1 24: £344m)
Central costs: £94m (H1 24: £94m)
Asset Management: performance was positive during the period, with net inflows of £2.6bn from external clients. This helped to support a 2% year-on-year reduction in the cost:income ratio to 75% and continued the company’s expansion of its external asset management business, reducing dependence on internal assets managed for the slower-growing Life businesses.
M&G also announced a partnership with Japanese life insurer Dai-ichi in May that’s expected to generate at least $6bn of net new flows over the next five years.
Like its UK-listed peers Schroders and Legal & General (I hold), M&G is keen to expand its presence in private markets. It’s not hard to see why – fee margins are roughly double those achieved on public market assets:
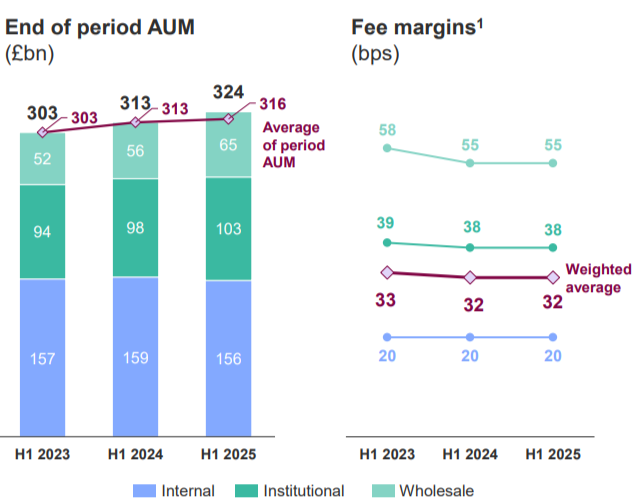
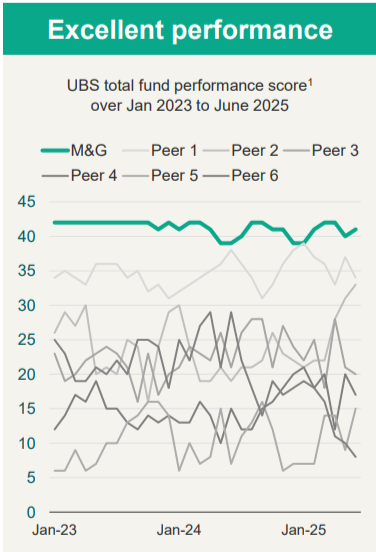
Whether this superior profitability will be sustainable and justified by investment performance as more capital crowds into private markets remains to be seen. In fairness, though, industry metrics published by M&G seem to suggest that its overall fund performance is better than that of many (unnamed) peers:
Life: this business has two parts, the PruFunds business (multi-asset funds for retirement solutions) and the Traditional With-Profits business, which is largely in run off.
CEO Andrea Rossi has been focused on expanding Asset Management to help offset an expected long-term decline in profits from Life, as the With-Profits funds run off.
For some context, Life was responsible for £5.1bn of outflows during H1, including £4.6bn of outflows from legacy products in run off. Seen in this light, the £2.6bn net inflow from asset management looks less impressive – it was only a strong market performance that allowed the company to report an increase in overall AUMA:
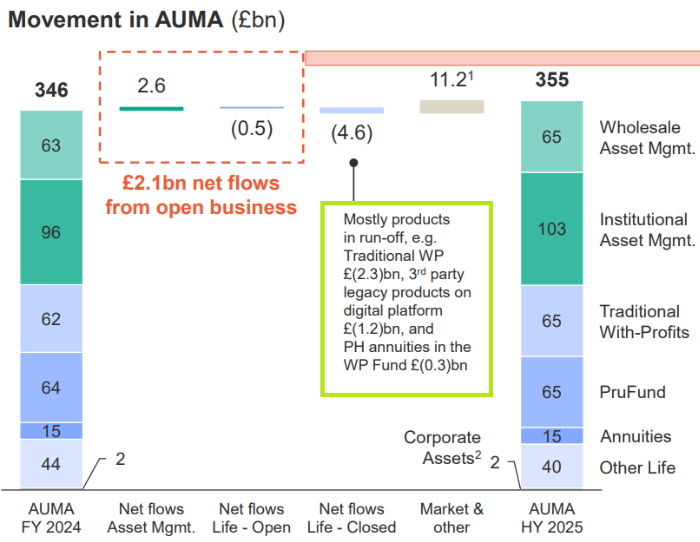
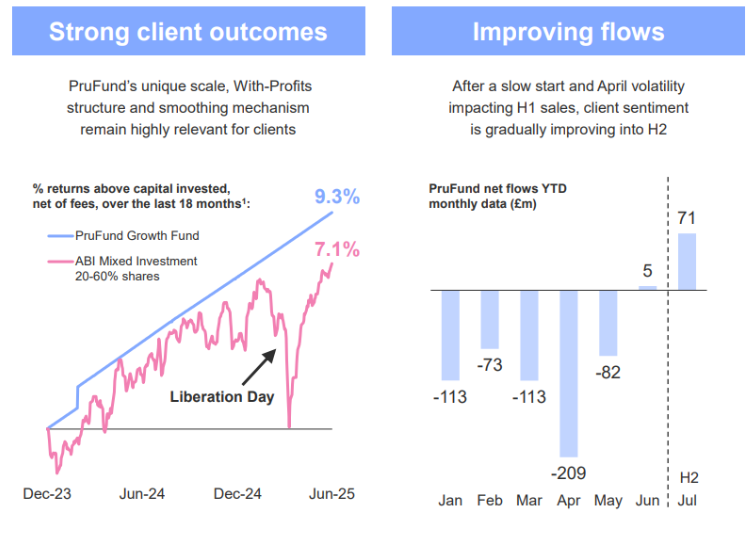
However, there may be some signs that the PruFunds business is returning to growth, after a period of sustained outflows. The company says these products provided attractive, smooth returns in H1, demonstrating their value to clients during a volatile period.
While flows were negative for H1 as a whole, they did turn positive in June:
Outlook: there’s no explicit financial guidance today, but the tone of the commentary suggests to me that full year expectations are largely unchanged:
The progress achieved in the first six months of the year underpins our continued confidence in the delivery of our strategic priorities and financial targets, as we remain focused on delivering great customer, client and shareholder outcomes.
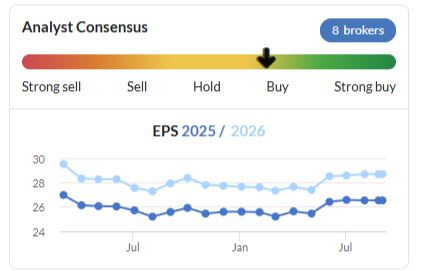
Stockopedia consensus forecasts have been fairly stable over the last 18 months and suggest further progress in 2026:
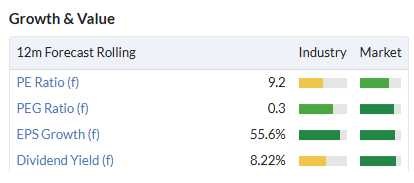
These estimates put the stock on a rolling forward P/E of 9, with an 8.2% yield:
Roland’s view
I see M&G primarily as an income investment. This means that the key questions for me are whether the dividend is sustainable, and whether the current yield is attractive.
As far as I understand them, today’s results look fine and do not flag up any underlying problems in the business.
The company has committed to a progressive dividend payout and seems likely to target growth of c.2% per year. I reckon this should remain affordable thanks to the strong cash flows from the Life business, at least in the medium term.
On a longer view, there’s potentially a risk that growth in Asset Management and PruFunds will not be sufficient to replace declining cash generation from legacy With-Profits funds. That’s something I’d watch.
In terms of valuation, an 8% dividend yield plus 2% dividend growth implies an expected return of c.10% per year. That seems about right to me, especially given that we can get a supposedly risk-free 5%+ from long-dated UK government bonds at the moment.
I’m tempted to maintain Graham’s AMBER/GREEN view from March, but I’m aware that the shares have risen sharply since then and that the StockRank has fallen.
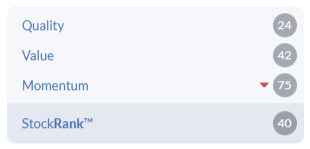
I also have to consider the complexity and inherent black-box tendencies of this business.
On balance, I think M&G’s valuation is nearing fair value for the time being, so I’m going to move our view down by one notch to AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Journeo (LON:JNEO) It's been quite a week thus far. Today's IC has an excellent article of yesterday's announced acquisition titled: 'This company’s acquisition is an absolute belter.' As you may reasonably infer it errs to the positive.
Any chance of an Cairn Homes (LON:CRN) review please
Wealth tax proponent fiddles her own taxes. Who'd have guessed?
today cora gold came up with an update and the stock price reacted accordingly
but then one has to ask (!)
how the feck is cora gold valued at 49 million when the projects are in Mali?? Landore Resources only has a market cap of 11 million and the resource is substantial in a much safer jurisdiction (Canada!)
Cora Gold – Sanankoro - ~1.044 Moz (689 koz Indicated, ~354 koz Inferred)
Landore – BAM (2024) ~1.5 Moz total (~1.03 Moz Ind., ~467 koz Inf.)
Is this some kind of joke? Landore Resources seems hugely undervalued or Cora is hugely overvalued. But I think its the whole mining sector that is so unloved that you get those extreme ambiguities.
Landore Resources (LON:LND) Rick Rule and Eric Sprott are onboard which is very bullish.
Ashtead Technology Holdings (LON:AT.) is the most shorted stock in the UK. Recent update indicated a positive outlook with delayed projects now back on track.
Directors have been buying recently. Price well off the highs of 700p+
Moves to main market on October 6th.
Completely off topic - the newsfeeds are reporting that Angela Rayner is now admitting that she has not paid enough stamp duty on her property transactions.
she is clearly toast now.
i was absolutely stunned by the general consensus that she had done absolutely nothing wrong in any manner here if i am being honest. Obviously with personal affairs that are private it can take time for the truth to out - but this seemed anything like a main residence at face value bearing in mind teh ongoing existence of the other property .
the comedy here is the amount of commentators who backed her to the hilt and cast accusations on others saying that what she has done is what anyone would have done and that she was being rargetted maliciously.
Its simply not plausible to have all those complcacted trust issues and not be aware of the 40k mismatch question - ok her advisors may have ffed up royally - but in the absence of thme throwing themselves under the bus it seems like the most likely thing is boundaries were collectively pushed and she has been caught out.
dont know exactly what she said at fisrt here - but if she didnt immediately say - i will recheck and come back - she is a complete idiot if she relied on sketchy advise.
Lets not pretend this is then fisrt time she has sailed close to the wind - the fact that she stated she did not live with her husband ref prior cgt - might have been mostly correct - but i supect if your average joe tried to use that argument with the beenfits agency they would conducted investigatioon to fact check the living arragements.
What is most sad here is that she coould live up to the basic standards she was preaching about - even if what she had done was right -unless she had actually moved into tne brighton address in some real "main residence manner" - she should have known that it would look like double standards to us normal members of the public.
She'll pay the tax and interest, sue the advisors for a big sum, then buy another property although whether she'll pay the correct tax is up for debate!
On a serious note she has a disabled son who needs lifetime care which resulted in this. It must be very tough for her and her family.
On a serious note she has a disabled son who needs lifetime care which resulted in this. It must be very tough for her and her family.
i am aware of that - i actually quite like her feisty attitude we need more people like her (passion wise) in politics. But sailing close to the wind twice and getting it wrong when you have used "top level super aggessive tactics deployed" is plain silly whether you have disabled kids or not - the quote about glass houses is completely appropriate here imho as she has thrown stones at others in the past ref exactly what she has got wrong now.
Note its very very active decision that has to be made when choosing or not choosing to pay the extra stamp duty - imho she has clearly put herself in a situation where she needed to be able to robustly defend not paying the extra - and she failed. hmrc even allow fairly generous leeway here - for example you can sell prior residence up to 3 years later and claim back stamp duty - 99.9% of people accept that pay up and claim back when prior main residence is "factually no more" The line she is a victim of bad tax advise imho is somewhat suss unless there is some evidence otherwise.
Hove, actually.
The post is somewhat on-topic for investors in my opinion. Why? Because it is indicative of the UK Government not having a grip on things.
Financial markets have a sort of hive mind, and the upward drift of long term gilt yields tell us they see increased risk in how things will unfold in the UK economy. I have seen another explanations in yesterday's FT- that it is about less demand as defined benefit pension liabilities unwind. I don't really buy this explanation,
For the sake of the UK I hope the current government gets a grip soon. It's likely to be in power for at least the next 3 years.
On Angela Rayner, I wish she hadn't done the tax underpayment thing. She's from a much underrepresented demongraphic, and Parliament ought to have a wider cross section of society. Her best bet now would be to resign and spend a period on the back benches (and Hove!)
At least she has a place by the beach so she can pursue her hobby of sailing close to the wind
UK Autumn budget not being announced until November 26th (usually late October/early November) - nobody ever delays good news! Will be interesting to see any impact on UK markets
Darren Jones may need a month or two to set his new agenda - my money's on Rachel not be delivering the budget
Great comments by Ken Clark in the Lords yesterday - telling the Treasury Secretary to stop floating ideas / leaking them to the press and make serious plans to balance the books, including revisiting some of their so-called capital projects to cut the debt and interest burden
- telling the Treasury Secretary to stop floating ideas / leaking them to the press and make serious plans to balance the books,
dont yhou love politicians (not) - the last government were equally bad in this regard - i bet Ken said didly squat when "his lot" where in charge when exactly the same was happening.
Whilst i sympathise with your view on politicians the issues Ken makes a fair point.
Ken makes a fair point.
i agree its a fair point - just pointing out that he should have complained when his lot did it if he wants to look anything other than "biased politician ". for the last 3 years tories were in power the rumours about pension relief being cut were pretty rampant. they then went and removed then lifetime limit - which basically allowed the mp's to get much extra from their super generous pension pots without being hit by extra tax - whilst at same time upping corp tax rates.
in some respects if there are leaks or not the press will always make a field day anyway so i doubt we could stop the "noise"
i would say if as an example if they know they are not going to get rid of tax free pots with immediate effect in the budget they should ensure that there is no excessive tittle tattle that suggests people need to cash in before budget day - its sad that many thought they needed to cash in their tax free pots due to an information void - when the fair thing to do would have been to say we will not do that
i do know that any party that removes the 25% tax free pot (this is already accrued) will ensure they are not elected next time round. no way back for any party that does that imho.
Normally when they have done extreme things with pension rules they have put protection certificates in place every time .
I would expect the same to apply to tax free cash changes and if that was the case they would probably be looking 15-20 years out to get any meaningful revenue in by which time they would be out of power anyway.
They will be looking for quick wins what ever they may be.
I 100% agree - I thought those that did cash in were being over cautious at the time . But in a void of uncertainty I don’t blame anyone who would only be minorly disadvantaged using caution and cashing in - there really should never be any uncertainty ref 25% tax feee - I still think they would never simply steal from that pot anyway - but if a rumour is out there some will always proceed on the basis risk is not 0.0000% very sad that there is any doubt ever
WOSG
i am the only one who feels conned when the stocky eps predictions show consistent monthly declines in expectations - then the trading update comes along and the company says "figures are in line"
am i being unfair here - is it perhaps simply some tardy brokers are updating "late" to give the impression that downgrades are later than what they are. eg if soem brokers only update late august reference the 03/07/2025 update.
do we have any access to more detailed info ?
i think this company last updated 03/07/2025 - on that date expectations went down based on trading update.
however since then we have had further downgrades per stocky on 03/08/2025 - and somewhat sketchy downgrade on 27/8/2025 - thats on top of the downgrades on 03/07 update. todays update does seem to have not gone down - but to me that simply looks to me like those in the now simply downgraded last week so they could in in line today.
I am perhaps overthinking here - many of these poorly performing companies share the exact same characteristics so they all tend to stick out lokie a sore thumb - the trend in eps for this year and next is either trending down or sideways - and if it is trending sideways that hasnt been for very long.
does anyone know if there is a nod and wink exercise before updates are done so that the brokers can quietly update in advance of the market being formally told ? it virtually never seems to happen that updates are lowered just before trading update - for company to then say - ah we are doing better than what brokers predicted last week - that virtually never happens in my experience.
Hey ho let the trend in forecasts be your friend - if it aint trending upwards it aint positive news and i would gues the next change is more likely to be down than up.
Looking at Burberry their trend seems more static than WOS - witha couple of blips up - but they almost seem to be rounding errors. JD. seems similar so perhaps the worst for most retailers ? BME does seem to stil be trending down albeit getting close to non material adjusts downover.
I am not minded to get to excited about any of these stocks till things actually get better - as always there is one execption to teh rule - i have taken the plunge with Greggs (LON:GRG) despite the trend being exceptionally poor. Serves me right if i have bought in here too soon before evidence of decent stabilisation or upward movement.
I can only say that when I was in Investor Relations, there were no nods and no winks. But analysts tended to brief their clients in the period leading up to results announcements, so there were sometimes late changes. We were only aware of one who made a habit of raising his forecasts close to the announcement so that he could say that the results were slightly below forecast - but there were probably others who did the opposite.
cheers pj8 fascinating insight
But analysts tended to brief their clients in the period leading up to results announcements, so there were sometimes late changes.
hmmmm how does that works in practice though without a nod and a wink ?- surely mangement are the ones that have more of an idea than analysts as to how stuff has progress over say te last 2-3 months - seems like these analsysts where there have late updates nearly always (i like your example to the contrary) seem to get the in the right direction ref moving up or down. If managment are blanking them they must be very good at their job working out the up or down without some help.
Time was if you were on the main list and dropped expectations the FCA was on your case for an explanation. You can't expect the same rigour with AIM companies, though market pricing consequences for offenders tend to be the adjustment mechanism.
Attention any remaining Zytronic Zytronic (LON:ZYT^E25) shareholders:
Henry Spain (Tom Spain/Glen Arnold) - 19% holders - have had a change of heart, and, having originally voted in favour of selling all assets and returning the cash to shareholders, have now requisitioned a GM to remove the current board, install themselves, and halt the return of cash.
Instead, they wish to invest YOUR cash in tiny private unlisted nano businesses, citing Warren Buffett's principles.
However, their long term record is certainly not up to Buffett's standards:
https://www.henryspain.co.uk/wp-content/uploads/2025/08/2025_Q2-Henry-Spain-AIM-Portfolio.pdf
Documentation has been posted by the company today. If you want to see your cash again, as per the previously agreed strategy, please make sure you exercise your right to vote!
Firstly, there is an AGM, to approve the accounts and to re-elect the chairman John Walter (5% holder) and Mark Atkinson (of the Desert Island Investor podcast, who will be familiar to many), which I shall be voting for:
https://assetmatch.com/app/OurCompanies/DownloadFile?realFileName=Factsheet%20VOTE%20FOR%20the%20AGM%20Resolutions.pdf&fileName=Factsheet%20VOTE%20FOR%20the%20AGM%20Resolutions.pdf
Immediately after the AGM is the GM, which seeks to oust the existing board, and replace them with Spain and Arnold instead, which I shall be voting against:
https://assetmatch.com/app/OurCompanies/DownloadFile?realFileName=Circular%20VOTE%20AGAINST%20the%20GM%20Resolutions.pdf&fileName=Circular%20VOTE%20AGAINST%20the%20GM%20Resolutions.pdf
There is also an IMC scheduled for Thurs 18th September at 2pm.
I'm a holder - I'm posting here to make sure people are aware and use their right to vote!
This is a very interesting status and will as an ex-holder who lost 77% of my investment watch for the final outcome. At a guess, whatever it is, any cash will be swallowed up in paying off debt and expenses.
No, it is a 48p-58p cash return, and expected to be towards the top end of that, as stated in FRP's most recent valuation letter (from last week). The assets have all been liquidated, the property is sale agreed, and assuming Spain don't get their way, the cash return is expected in October.
Thanks for the write up on WOSG Graham, It is one I have been keeping a close eye on for quite a while, however, as the North American market is now their biggest market I cannot see how (once the inventories have reduced) in the future the 39% tariff won’t have a material impact - or am I missing something?
Yes the 39% US tariff on Swiss goods from last 7 Aug - WOSG currently relying on inventory build in its largest market - is why the shares are priced on a seemingly 8x P/E, for now anyway.
Watches of Switzerland (LON:WOSG)
Hi Mark
I sold out earlier this year amidst the tariff confusion, but I am keen to buy back in.
Even at these levels I see significant value relative to the valuation, especially with those sticky Rolex revenues with long waiting lists.
Strip out the expansionary capex (estimated c£65m for FY26) and I am forecasting that they'll make c £120m-£140m in FCF vs a current EV of £900m.
This doesn't seem expensive.
However, as you rightly pointed out, I can't see how there won't be a hit in the near future from tariffs.
Perhaps this won't significantly affect the top line with expansions and acquisitions, but I don't see how their suppliers won't force them to accept lower margin; the guidance today implies that they're not expecting much impact at all.
Perhaps I'm being pessimistic, but I just don't understand the lack of caution in their outlook.
A
Hi Mark, I agree with your position. That said WOSG does offer exposure to an alternative asset class which is an invaluable trait in markets where frankly its any bodies guess what happens next.
Likewise, Ecora Resources (LON:ECOR) reported interims this morning but not on the list.
Looks to be benefiting from scale up in production through its base metals royalties which are up 80% vs last year. H2 will see final major revenue from Kestrel coal royalty. Sold non-core developmental gold royalty yesterday for large mark up on holding value and will reduce leverage.
From what i can make out you get NAV per share of £1.30 for a price of 76 pence today.
Chart looks good, firmly rebounding and would hope will continue through H2.
We'll get CRN into the table! Thanks guys.
Hi Graham, Cairn Homes (LON:CRN) reported this morning (not on the list) Guidance moved up slightly.
I suggest a writeup on CRN would make enjoyable reading in these difficult times. Graham has covered before. Tony