Daily Stock Market Report (Wed 4th March 2026) - Market Backdrop, SCE, GMS, VTY, SRT, CRN, MWE

Morning!
Market Backdrop
After a pretty tumultuous couple of days in response to the events in the Middle East, I am expecting some calmer waters today with the FTSE opening up 0.3% at around 10480. The moves in equity markets have been dominated by risk-off sentiment rather than necessarily companies with Middle Eastern exposure. For example, the spot oil price has responded understandably positively to the Straits of Hormuz being closed, as 20-30% of global oil supply typically passes through there. In response, companies heavily reliant on energy as a core input have sold off, but many oil producers haven’t really responded positively. That oil producers don't immediately soar may be logical; the market may be pricing a rapid resolution to the current war and a return to normal over a relatively short time. However, that makes the sell-off in oil consumers illogical. We can’t have both. Which leads me to conclude we have simply seen investors run for the hills.
Nowhere has this risk-off attitude been more obvious than in some of the smaller companies. Even companies with high StockRanks and no exposure to the ME or oil have had a pretty brutal sell-off. This leads me to conclude that stop-losses may have had a part. These can be an important part of an investor's risk management process. However, in times like these, they should probably be renamed “Guaranteed Losses” instead of “Stop Losses”, as they tend to get triggered at the worst possible times. This is especially true if investors choose to use them on smaller, more illiquid stocks. Ed looked at the question of applying stops to the NAPS portfolio recently. They were no panacea. While drawdowns were slightly reduced, so were returns. So if you have bought high-quality companies that are cheap and have improving fundamentals, there seems little reason to panic sell now.
08:00 Summary complete
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Weir (LON:WEIR) (£8.83bn | SR70) | Revenue +6% to £2.565bn, Adj. Op Profit +15% to £518m, Adj. PBT +4% to £447m, Adj, EPS +3% to 123.8p. Net Debt £1,274m (FY24: £535m). “Looking ahead to 2026, I am encouraged by the strength of our business. Our market‑leading hardware portfolio and growing suite of software solutions position us to benefit from the long‑term structural tailwinds across the mining industry. " | ||
Beazley (LON:BEZ) (£7.73bn | SR66) | Insurance Premiums written -1% to $6.1bn, PBT -19% to $1.146bn, EPS -17% to 113.4p, NTAV per share £5.84. | PINK | |
Barratt Redrow (LON:BTRW) (£4.83bn | SR43) | Appointment of Dean Banks as next Group Chief Executive. He will join the Group in the final quarter of 2026 and succeed David Thomas who has decided to retire from the business after 11 years as Group Chief Executive and 17 years with the Group. | ||
Quilter (LON:QLT) (£2.62bn | SR88) | AuMA +18% to £141.2 billion reflecting net inflows of £8.7 billion coupled with a positive contribution from markets. Revenue +5% to £701m, Adj. PBT +6% to £207m, Adj. EPS +4% to 11.0p, Dividend +7% to 6.3p for the FY. | ||
Vistry (LON:VTY) (£2.02bn | SR78) | Revenue - 4% to £4,155m, Adj. Op Profit -1% to £353.8m, Adj. EPS +6% to 59.3p, Net Debt £144.2m (FY24: £180.7m). “The Group expects to deliver good year-on-year revenue and volume growth, and an improvement in adjusted profit before tax in 2026, albeit with a lower overall margin reflecting the incentives offered during the current sales initiative.” | BLACK/AMBER = (Mark) While we don’t have access to broker coverage, it is clear that today’s outlook on margins represents a profits warning. Given this, the temptation is to now go for a reduced stance, instead of an improved one that we were previously mulling. However, the scale of today’s share price fall appears to exceed the size of the warning and puts the company trading well below tangible book value, despite them transitioning to an asset-light model where that tied up capital will be freed and eventually returned to shareholders. Today’s separate announcement that the Chairman & CEO (same person) will retire raises some questions about the speed and success of this strategic shift. However, I don’t see the fundamental tenets of this move being challenged. Hence I think it makes sense to keep our neutral stance. | |
Cairn Homes (LON:CRN) (£1.2bn | SR50) | Revenue +10% to €944.6m, Op Profit +12% to €168.6m, EPS +19% to 21.3c, Net debt €171.3m (FY24: €154.4m). Operating profit of c.€180 – €185 million (previously c.€175 – €180 million); | GREEN = (Graham) Consistent with Stockopedia’s methodology around profit warnings and earnings upgrades, it makes sense for me to stay positive on Cairn as it continues to enjoy very strong trading. There’s been a fantastic string of upgrades over the past year. This is a rare case when I’m happy to take a positive view on a housebuilder primarily for its earnings outlook, combined with a positive impression of management, and without much regard to its balance sheet support. | |
Metro Bank Holdings (LON:MTRO) (£769m | SR48) | Net Interest Income +22%, Revenue +16% to £585.1m, u/l PBT £98m (FY24: £14m LBT), RoTE 6.4% continues to increase in line with guidance (2028 guidance to deliver greater than 18% RoTE). CET1 flat at 12.5%. EPS 7.8p, TNAV/share £1.63. | ||
Allergy Therapeutics (LON:AGY) (£741m | SR20) | The comprehensive panel of biomarkers of efficacy demonstrated the strong immunomodulating response which was highly consistent in all peanut allergic subjects after treatment with VLP Peanut | ||
Galliford Try Holdings (LON:GFRD) (£536m | SR95) | H1 Revenue +1.3% to £934.9m, Adj. Op Profit +225 to £21.6m, Adj. EPS +18.5% to 18.6p, Avg Month-End Cash £189.9m (25H1: £176.4m) | ||
Capita (LON:CPI) (£406m | SR83) | Has been selected to deliver the Synergy Business Process Services contract worth £370 million over 10 years starting March 2026, to deliver tech-enabled back-office services for public servants across four major UK government departments. | ||
Gulf Marine Services (LON:GMS) (£262m | SR91) | Received instructions from a client in the Middle East, in response to the ongoing situation in the Gulf region, to immediately evacuate personnel from four vessels operating under its jurisdiction as a precautionary safety measure. | BLACK/AMBER ↓ (Mark) | |
SRT Marine Systems (LON:SRT) (£194m | SR36) | New contract with a new sovereign customer to supply a national SRT-MDA System with a total value of US$261 million. | AMBER = (Mark) [no section below] As others have pointed out, this is not a new contract, but confirmation of one previously announced being formally signed. This is combined with an uplift in value from $200m to $261m. As is always the case with SRT, the numbers are huge, but it is often difficult to work out exactly how these will look in the financials without broker help. In this case, Cavendish keeps forecasts the same. This makes the share price rise today look high. However, we also get confirmation that current events in the ME are more likely to strengthen their hand than weaken it, hence much of the rise is probably a relief rally. Overall, I struggle to get behind a company that has had so many false dawns in the past as an investment case, so I’ll keep our neutral view. However, I like the idea of a niche British tech company succeeding on a global scale, so I will be cheering it on from the sidelines. | |
Netcall (LON:NET) (£176m | SR51) | H1 Revenue +15% to £26.5m, Adj. EBITDA +13% to £6.45m, Adj. PBT +11% to £5.43m. Net Cash £14.8m (25H1: £20.9m). | ||
dotDigital (LON:DOTD) (£170m | SR56) | Alia, a US-based SaaS platform serving 2,700+ customers and forward-looking ARR in excess of $8m, acquired for an initial consideration of $30m, with a total maximum consideration of up to $60m dependent upon future performance. | ||
Pulsar Helium (LON:PLSR) (£148m | SR31) | Gas was encountered at 642m with a preliminary bottom-hole pressure of approximately 953 psi, indicating a robustly pressurized reservoir system at greater depth relative to previous wells. | ||
SIG (LON:SHI) (£115m | SR48) | LFL Sales flat at £2,591m, u/l Op Profit +28% to £32.1m, u/l LBT £20m (FY24: £14.3m loss), Net Debt £518.2m (FY24: £497.3m) | ||
Avation (LON:AVAP) (£85.7m | SR40) | Andrew Hiscock appointed as Chief Financial Officer, with immediate effect. | ||
MTI Wireless Edge (LON:MWE) (£49.1m | SR86) | Revenue +13% to $51.5m, PBT +12% to $5.41m, EPS +17% to 5.86c, Net Cash $9.4m (FY24: $6.0m). | AMBER/GREEN = (Mark) There’s nothing in these results that leads me to change my previously broadly positive view on the investment case, and recent world events are likely to strengthen that case, rather than diminish it. | |
Ondo InsurTech (LON:ONDO) (£24.7m | SR2) | Rollout of LeakBot across Selective Insurance's 15-state Personal Lines footprint. | ||
Eenergy (LON:EAAS) (£19.7m | SR27) | £1.1m contract for supply and installation of solar PV systems for Unity Schools Partnership & £0.7m for supply and installation of LED lighting. |
* Market caps at previous trading day’s close
Graham’s Section:
Mark’s Section:
Surface Transforms (LON:SCE)
Up 20% at 0.11p - Major Customer Update: Loss of Contract - Mark - BLACK/RED
Just a brief comment on this one as it appears on the most viewed list, but after a 95% fall in the share price yesterday, it is way below our £10m cut-off.
The share price fall yesterday tells you it is really bad news:
The Company has been informed by General Motors ("GM") that it is re-sourcing its supply of brake disks with effect from 31st March 2026.
We knew they had customer concentration but I’m not sure this was ever revealed how concentrated they were:
GM is the Company's most significant customer and in FY 2025 formed £15.3m (84%) of revenues and 85% of discs sold and was under contract until 2030.
It seems likely that GM have finally lost confidence in the company to deliver brake discs at the agreed timing and price, which means they will almost certainly want their money back instead of brake discs:
Additionally, since November 2024 GM has provided the Company with operational support and financial assistance including advance payments of £14.4m.
Their last trading update revealed that they had £1m of gross cash and had £13.3m of customer pre-payments outstanding. They also had £9.1m of current debt at 30 June 2025. There was £17.1m of PP&E and £6.9m of inventory. However, as these appear to be furnaces, brake discs and raw materials to make brake discs that are no longer wanted by their major customer, these should have a large haircut applied in any valuation.
This means that I don’t see a scenario where GM gets all the money they lent them back, let alone any return to shareholders. Indeed, the use the word “stakeholders” here suggests where this is going:
The Company has not yet had the opportunity to speak directly with GM about the termination, but the loss of this contract has a material impact on the Company's ability to trade and as a result the Directors intend to immediately engage corporate restructuring advisers to protect stakeholder's interests.
Given the history of production problems and missed deadlines, which has led to almost 20 equity raises during the company’s life as a listed business, perhaps the only ones truly sorry to see them go will be those who work for their broker.
Mark’s view
It goes without saying that the chances of the company avoiding insolvency are slim, and the chances of shareholders receiving anything in these proceedings is similarly remote. RED
Gulf Marine Services (LON:GMS)
Down 12% at 20p - Regional Events - Mark - BLACK/AMBER ↓
This news is perhaps understandable, given what is going on in the world:
…received instructions from a client in the Middle East, in response to the ongoing situation in the Gulf region, to immediately evacuate personnel from four vessels operating under its jurisdiction as a precautionary safety measure.
However, what is surprising is that their contracts don’t protect against this:
GMS is continuing to monitor the situation closely and is currently working to quantify the potential impact of the recent developments on its operational and financial performance.
That they need to quantify this suggests that this isn’t immaterial, or only a customer problem. Any disruption may impact the company’s cash flow profile and ability/willingness to start making the long-awaited shareholder returns.
Their broker Zeus add some useful colour:
GMS is currently assessing the implications of the vessel personnel evacuation for its revenues, and the rates it will be able to continue to charge the client during this period of operational cessation. We would expect this to be subject to discussions with the client. We are not making any updates to our forecasts today, and note that existing 2026 company guidance has not yet taken account of any benefit from the new vessel acquisition announced earlier this year, providing some element of potential mitigation for any revenues lost elsewhere. We await further updates on vessel activities, and any change to full-year 2026 guidance.
So it seems that they will likely still get paid, but the rates may be lower, and subject to negotiation. At the moment four out of their 14 (soon to be 15) boat fleet are impacted, but I don’t think we can rule out some of the rest of the fleet being affected. As their corporate name suggests, the bulk of the fleet is based in the Gulf.
Their NTAV is of course unaffected by these events. However, I can’t help feeling shareholders would actually prefer Iran to blast a few of the ships out of the water (assuming that all personnel are safely evacuated and they are suitably insured)! I have been unconvinced by their recent strategy of starting to expand the fleet again, before they have got the debt fully paid down or begin to make shareholder returns.
Mark’s view
The share price has been strong this year, with shareholders extrapolating recent contract wins and extensions into a brighter outlook. The only major upgrade has come from the additional ship being added to forecasts, and we await their formal guidance for FY26:
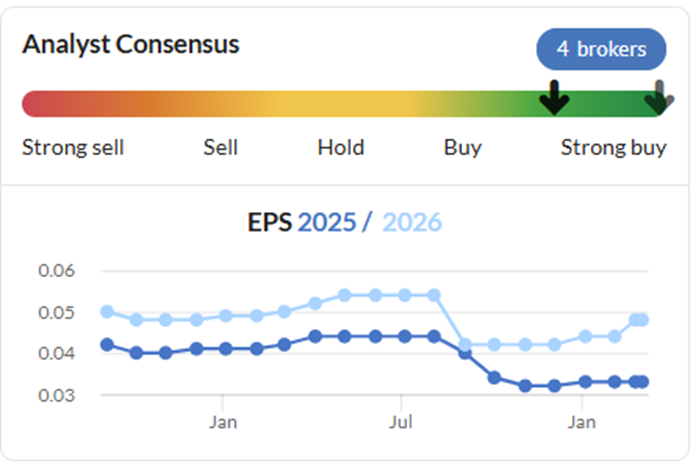
If I held, I think I’d be tempted to take profits at this point.Unlike many recent fallers, this appears to face a genuine risk to operations and the disruption could have a negative impact on 2026 outlook, especially if other contracts in the region end up being affected.
Balancing this, I expect them to be paid during suspension of operations, just at a potentially lower rate, so it won’t be a serious impact, unless operations are suspended beyond expiry of contracts. And this remains a SuperStock:
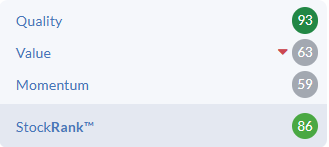
Overall, world events increase the risk here and I think it is probably right to reflect that in a more circumspect view, until it is clear that missiles are no longer flying around the Middle East. AMBER
Vistry (LON:VTY)
Down 17% at 522p - Full year results for the year ended 31 Dec 2025 - Mark - BLACK/AMBER =
These results aren’t anything to write home about, with revenue down 4%:
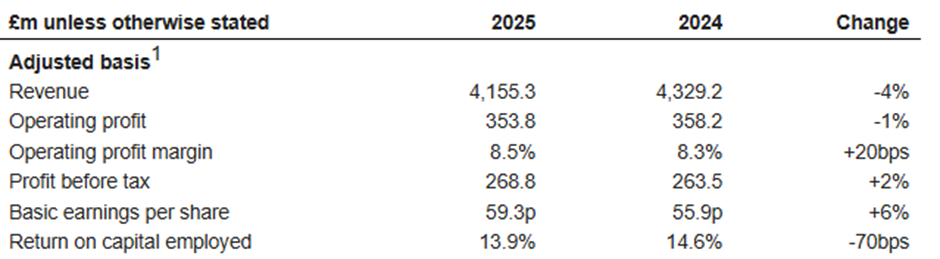
But they aren’t terrible either, with adjusted EPS rising 6% and coming in above the 55.7p consensus in Stockopedia. (Sadly companies of this size don’t tend to use brokers who make their research publicly available so we can’t check directly.)
Adjustments:
There remains a large gap between adjusted and statutory figures. Exceptional items have once again proven to be less exceptional than one would have hoped for:
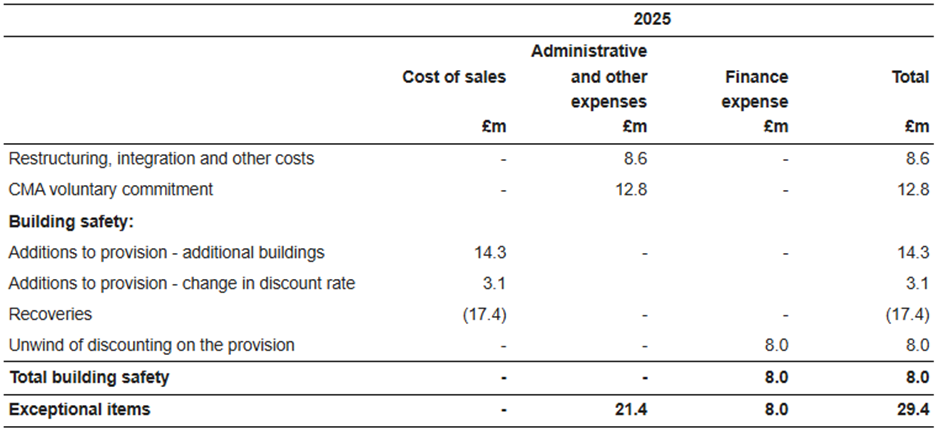
Building safety provisions appear to have netted off as they have already been provisioned for, but remain a cash drag. Restructuring costs are back, but perhaps less material than they would be elsewhere given the scale of the business. The CMA commitment at least seems one-off:
The Group, together with six other UK housebuilders, entered into a voluntary binding commitment in response to the potential concerns investigated by the UK Competition and Markets Authority (CMA). Under this commitment, the participating housebuilders will contribute £100m in aggregate to His Majesty's Government, to be allocated to programmes that fund and support the construction of affordable homes in England, Scotland, Wales and Northern Ireland. The Group's share of this contribution is £12.8m.
Outlook:
I don’t think any of these explain today’s share price weakness, which is focussed on the following guidance:
· The Group expects to deliver good year-on-year revenue and volume growth, and an improvement in adjusted profit before tax in 2026, albeit with a lower overall margin reflecting the incentives offered during the current sales initiative.
· The shape of profit delivery is expected to be similar to that in 2025. This is due to the greater margin impact of the sales initiative in the first half, and the step up in demand expected from the affordable housing stimulus in the second half.
Their focus on volume but at the cost of margin, means they expect profits to be flat on 2025. The StockReport shows expectations were for a 19% rise in EPS so this is undoubtedly a miss versus prior expectations, even if we can’t see the details. From secondary sources, it seems that Stifel expects this strategy to push down consensus profit forecasts by about 5-10%.
Balance sheet:
Things look better on this front with net debt declining to £144.2m from £180.7m the year before. However, as we find with an embarrassingly large number of companies, they shoot their buyback bolt prior to a profits warning, and then don’t have the capacity to renew it:
Remaining £29m of the current £130m share buyback programme to be completed, with no further capital distribution proposed on the back of the 2025 results in order to prioritise debt reduction. Future distributions to be reviewed at the half year.
This buyback is said to be in lieu of dividends, so the lack of extension perhaps means they don’t see any chance of a short-term improvement in trading.
Strategy:
Vestry has been undergoing a change of strategy over the last few years, with a focus on a partnership model. The idea is that it is moving away from traditional speculative housebuilding to focus on a high-volume, "capital-light" model centered on affordable, mixed-tenure housing. By removing the need to hold a large landbank, this should make the returns on capital much higher, and free capital for shareholder returns. That the buyback is not extended may be another sign that things aren’t moving as quickly as many would like in this area.
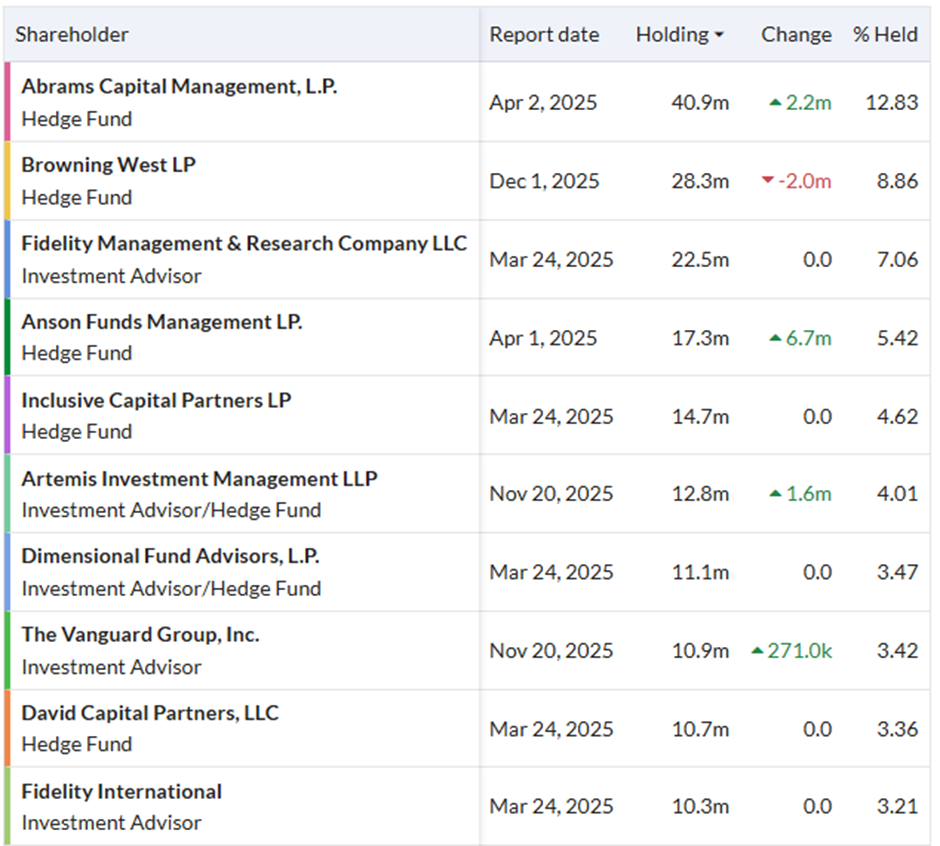
Vistry Group is trying to emulate the US-based homebuilder NVR, and its shareholder register is stacked with US funds that appear to have bought in to back this transition:
While progress is perhaps slower than many would like, there are signs that there may be progress, as they say:
In November 2025, Homes England issued bidding guidance under the £37bn 2026-2036 SAHP, confirming bids would be invited early in 2026. Vistry is well positioned to deliver at pace with Homes England, the Greater London Authority and our other partners, with the programme targeting 300,000 homes over its term. Bidding opened at the end of February for Homes England's part of the SAHP, and our bid is in the process of being submitted. We are hoping to have a high degree of visibility of Vistry's grant under the programme by the half year.
Vistry's current status as a Strategic Partner under the 2021–2026 programme suggests it is in a strong position to win significant business under the 2026–2036 successor programme. In September 2025, Vistry and Homes England launched Hestia, a £150 million joint venture designed to accelerate large-scale, mixed-tenure sites which aligns directly with the long-term goals of the new SAHP. So it would seem to be highly unusual for them not to play a major part in this programme.
CEO Retirement
The primary architect of the partnership strategy is Greg Fitzgerald, the Group's Executive Chair and CEO. He spearheaded the pivot in September 2023 to dismantle the group's traditional housebuilding arm and merge it into a single, partnerships-focused entity. So it is perhaps a little more worrying than usual that he:
...has informed the Board that he intends to retire from the Company. Greg's retirement will see the separation of the Chair and CEO roles.
This seems well planned with him remaining in the role “for up to 12 months, or until a successor is appointed.” However, you do have to wonder if he thought the strategy was about to really transform the company (and share price), why would he choose now to retire?
Mark’s view
When Roland reviewed the company’s trading update he made no change to our neutral view, saying:
Vistry’s move to a capital-light partnership model also has the potential to drive a re-rating as its capital requirements fall. With the shares now trading c.10% below tangible net asset value, I’m tempted to move up to AMBER/GREEN, but the group’s stubbornly daily net debt position means I’m going to maintain my previous neutral view for a little longer.
Given today’s profits warning, his caution looks warranted,and the temptation is now to go for a reduced stance, instead of an improved one. However, the scale of today’s share price fall appears to exceed the size of the warning and puts the company trading well below tangible book value, despite them transitioning to an asset-light model where that tied up capital will be freed and eventually returned to shareholders. Today’s separate announcement that the Chairman & CEO will retire raises some questions about the speed and success of this strategic shift. However, I don’t see the fundamental tenets of this move being challenged. Hence I think it makes sense to keep our neutral stance of AMBER.
MTI Wireless Edge (LON:MWE)
Up 4% at 57.5p - Final Results - Mark - AMBER/GREEN
I commented on this on the DSMR a couple of weeks ago, when the main headlines were revealed. Therefore, there is little surprise in these results:
· Revenues increased 13% to US$51.5m (2024: US$45.6m)
· Profit from operations increased 29% to US$5.81m (2024: US$4.51m)
· Profit before tax increased 12% to US$5.41m (2024: US$4.81m)
· Net Profit increased 11% to US$4.66m (2024: US$4.19m)
· Earnings per share increased 17% to 5.86 US cents (2024: 4.99 US cents)
· Net cash of US$9.4m at 31 December 2025 (31 December 2024: US$6.0m)
I felt they over-egged the language they used in the Trading Statement, but these were still good results. It is the breakdown between divisions that is the key thing for me:
Antennas
In 2025, revenues from this division increased by 11% reflecting a sharp increase in demand for higher margin military antenna solutions that led to a 15% rise in divisional operating profit. Military antenna sales increased 50% over 2024 and represented 55% of the antenna division's total revenue…
Water Control & Management
Mottech had another good year showing revenue growth of 10% over 2024 with recurring revenues from services and maintenance continuing to grow. Operational profit was lower than 2024 but met our internal forecasts as we invested more in development and marketing efforts, the fruits of which we expect to see come through in future years.
Distribution & Professional Consulting Services
2025 was a great year for MTI Summit, delivering 20% revenue growth compared to 2024 and moving PSK from a loss into profit, accelerating this division's operating profit to being over four times higher than 2024….For MTI Summit and PSK, the increased defence spending by governments globally creates a very positive market environment to operate in, as defence is over 80% of total revenue. This is also reflected in the backlog of orders and future pipeline with demand primarily coming from Israeli defence companies providing solutions for the International and the Israeli market.
So as I expected, this is really a story of increased defense spending, feeding through to improving results throughout the business. Mottech saw declining profits, but again this wasn’t bad, as they flag this as a period of increased marketing.
Balance sheet:
This looks strong, with current assets significantly exceeding current liabilities. There is a jump in unbilled receivables but this doesn’t look out of place for a company growing its project work. Plus credit quality on receivables appears to have improved:
As at 31 December 2025 trade receivables of $928,000 (2024 - $1,790,000) were past due but not impaired….They relate to the customers with no default history.
Outlook:
They see these positive trends, again driven by the macro position:
Overall, MTI is well positioned across all three divisions, each benefitting from strong macro trends underpinning future prosperity. The first two months of 2026 have been in line with internal expectations and judging from the pipeline of potential opportunities, the Group is well placed to continue to seek to expand through a mix of organic and acquisition-led growth, supported by a strong financial foundation.
With Israel starting a war with Iran this week, I don’t see those trends for defence spending in Israel diminishing any time soon!
Mark’s view
There’s nothing in these results that leads me to change my previously broadly positive view on the investment case, and recent world events are likely to strengthen that. AMBER/GREEN
Graham's Section
Cairn Homes (LON:CRN)
Up 3% at 201p (£1.25bn) - Preliminary Results - Graham - GREEN =
I upgraded our stance on this to fully positive in January on the back of another very positive trading update.
Today’s results are excellent, as expected:
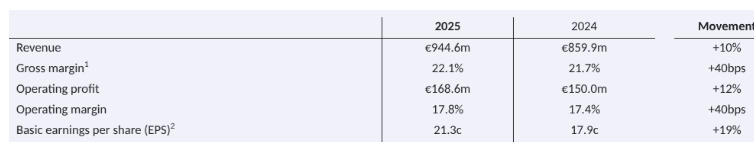
We were already given most of these numbers in January.
What really matters is the latest on the 2026 outlook, particularly as I’ve acknowledged that this is an unusual call for me: I tend to be nervous when it comes to housebuilders trading at a large premium to book value.
That remains the case here: today’s balance sheet shows net assets of €837 (nearly all tangible), as compared with a market cap that’s equivalent to €1.44 billion. That’s a 70%+ premium to book.
However, the particular conditions of the Irish property market - an extreme shortage of available properties relative to demand, combined with government policies that are designed to increase supply - suggest to me that this is a special case. In this very specific circumstance, I can get behind the idea that a well-managed housebuilder may deserve an unusually high valuation.
Fortunately, today’s outlook statement supports the idea that this stock deserves special leeway:
With exceptionally strong demand reflected in a record order book and a supportive policy and macro backdrop, Cairn continues to benefit from a fundamentally robust housing market characterised by structural undersupply. These conditions, combined with our disciplined capital allocation strategy and substantial investment in operational scaling, have created a platform for consistent volume growth and strong financial performance. As a result, the Group is now firmly positioned to achieve output of c.6,000 new homes between this year and next, including c.3,200 homes in 2027, resulting in a 35% increase in our output over this two-year period.
Cairn is upgrading guidance for FY26 as follows:
Revenue of c.€1.05 – €1.08 billion (previously c.€1.02 – €1.05 billion);
Operating profit of c.€180 – €185 million (previously c.€175 – €180 million); and
ROE of c.16.5%.
I would draw readers’ attention in particular to the very high and attractive ROE, and the company’s strong focus on those metrics as a KPI.
CEO comment:
“Cairn is now in its second decade in business. We are proud of the significant contribution we have made to housing in Ireland since we closed our first sale in December 2015, with over 12,000 new homes sold and 35,000 residents living in a Cairn-built community. Our commitment to growth is stronger than ever and we will accelerate our output to close to 18,000 new homes delivered by the end of 2027.
Graham’s view
Consistent with Stockopedia’s methodology around profit warnings and earnings upgrades, it makes sense for me to stay positive on Cairn as it continues to enjoy very strong trading.
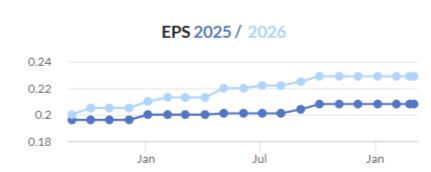
There’s been a fantastic string of upgrades over the past year:
One interesting feature of the results is that the company has achieved all of this without raising its average selling price by all that much: from €383k in 2024 to €392k in 2025. And gross margin has increased only marginally. What’s really driving performance are a) volumes and b) tightly managed overhead costs.
Operating expenses were €40m in 2025, up from €37m in 2024. Compared to revenues of €945m, this appears to be a very well-managed organisation (note to self: I should compare this against other housebuilders).
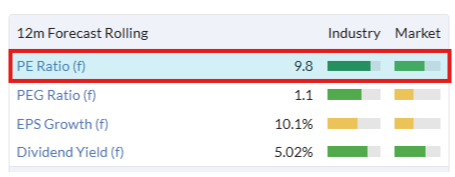
Overall then, it makes sense for me to stay positive on this. It’s a rare case when I’m happy to take a positive view on a housebuilder primarily for its earnings outlook, combined with a positive impression of management, and without much regard to its balance sheet support.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
SRT Marine Systems (LON:SRT)
I've received several replies to my post which deserve a response.
One of the reasons I have a large holding in SRT is that I have done considerable research including visits to Head Office to talk to whoever I can find. Simon Tucker has a well earned reputation for enthusiasm, it's a necessary attribute in my view. He has sometimes over promised and under delivered. This is a fact he accepts and in recent times he has become more circumspect, preferring to let events demonstrate SRT's qualities.
I have previously explained that I believe the corruption charges are trumped up. There are 5 large fishing companies operating in shallow waters which threatens the livelihood of artisan fishermen. They do not want a system that prevents this. The wife of the ombudsman who announced that there was corruption owns one of these companies. SRT's CFO was also implicated but that was quietly dropped. This is an attempt to persuade the President to back down. The senior member of BFAR who was jointly accused is out and about making his views known with no mention of outstanding charges.
https://archive.ph/E2ORD#selec...
"Former Fisheries Chief Warns Philippines “Nearing War,” Criticizes Coast Guard Shift from “Warrior” to “Savior”
MANILA — Eduardo Gongona, former director of the Bureau of Fisheries and Aquatic Resources (BFAR), has issued a stark warning that the Philippines is “nearing war” due to escalating tensions in the West Philippine Sea (WPS), while criticizing the Philippine Coast Guard’s (PCG) doctrinal shift away from its military roots.In a detailed social media post, the retired official and former PCG officer blended personal anecdote, operational history, and strategic analysis to voice deep concern over the current trajectory of maritime disputes."
Does anyone seriously think the UK Government UKEF department would be happy offering their support to SRT if this has any substance?
Yes it does take a long time to bring potential contracts to fruition because they require an enormous amount of customer alignment and physical change . No-one is surprised that our own government takes ages to approve a railway line, a runway or a power station, but somehow SRT must be at fault for not delivering faster. An additional hurdle is that fishermen in general don't want to be controlled if there's nothing in it for them. I spoke recently with SRT's COO who talked about adding functionality to the devices boats would carry which would help them locate fish and improve their catch. That should help align their interest with those of the government.
Despite my keen interest I don't only post about SRT and when I do, it coincides with news. I post about other shares I own, some are large, others small.
Mark has been good enough to respond too. I hope that today's news will help Stocko to recognise the jam tomorrow label belongs in the history drawer. I wish existing and prospective holders good fortune.
SRT Marine Systems (LON:SRT)
i think the main issue today is the lack of broker upgrades - once they start delivering this large contract should we not be expecting higher thna £11 mil pa profits ? - not sure how far broker forecasts go out in the future right now and when new year may come on stream ??- imho thats the game changing moment when there is tangible evidence brokers are happy to show us the bacon of extra profits ref this contract - imho i thought Mark's assessment was fair and reasonable bearing in theer are no expectations of higher profits now plus we cant expect deep dive when there are so many shares to review in one day.
none of the above is to take away from the fact the news today is excellent in itself
Happy to agree with you rmillaree. I’m sure the broker will be more forthcoming before long. Other SRT watchers over on ADVFN have posited their forecasts and it will be interesting to see how accurate they turn out to be.
SRT Marine Systems (LON:SRT)
Other SRT watchers over on ADVFN have posited their forecasts and it will be interesting to see how accurate they turn out to be.
ok cheers will go and have a gander - if there is a latent uptick awaiting if for example if $100 mill one off revenue might be recognised 2028 and that results in material uplift for that year - i would esxpect when the brokers releass that update for that year that thats the event that would perhaps trigger the rerate - or the swap to green if the p/w becomes more compelling.
Its quite interesting to see how accurate company and random internet predictions are - hey ho as contract has only been signed off fully today that might be coming along later but soonish perhaps ?
SRT Marine Systems (LON:SRT). I believe the brokers - Cavendish - have said they intend to issue new figures as soon a the outstanding financial details are finalised.
SRT Marine Systems (LON:SRT)
I believe the brokers - Cavendish - have said they intend to issue new figures as soon a the outstanding financial details are finalised.
Thanks for that - yes that makes sense that it might be time to fully take stock ref such big numbers - in the meantime i will have a looky over there
Excellent informed response ... thank you for taking the trouble. I do actually have a small position but have concerns as expressed below.
SRT Marine Systems (LON:SRT)
I'm somewhat disappointed that today's contract news hasn't warranted more coverage and is being labeled as Amber. The problem with small companies seems to be that Stocko isn't really bothered about looking into them. It's much easier to focus on the more obvious ones, like the companies where a long section has been posted, each of which is Black/Red or Black/Amber.
SRT is dismissed with "Overall, I struggle to get behind a company that has had so many false dawns in the past as an investment case, so I’ll keep our neutral view."
This is from Cavendish's morning note:
"Favourable medium to long-term prospects remains underpinned by c.£340m active multi-million-dollar decade-long contracts in delivery, excluding the $261m award, each with scope for expansion; pipeline growth to £1.8bn excluding the $261m award; and diversification of capabilities to support adjacent technologies and domains. Forecasts and target price of 122p is reiterated. At 77p, SRT trades on 1.3x FY27E sales, 14x PE excash and a 9% FCF yield."
With 5 active contracts in the ME, Asia and now a sixth in Africa, surely it is time to stop looking at the past and to recognise that there is a big opportunity here. These are not one off's. Each of these contracts is likely to remain in use with multiple upgrades over time and recurring revenue for data acquisition. These systems are critical to the customer's national security, coastguard operations and the prevention of illegal/ unreported fishing. Implementing them requires new laws to be passed and processes established which become deeply embedded are not undertaken on a whim.
For a company with a market cap of less than £250m, £1.8 bn of project work being lined up should spark a bit more interest in SRT. Don't forget that they also have a significant transceivers business which includes suppling OEMs, plus their own in house brand Emtrak, Aids to Navigation and they have begun shipping the new, flagship X100 codenamed Nexus which combines AIS and VHF radio.
I'm beginning to wonder if my subscription is really worthwhile.
rwh3ue
“I'm beginning to wonder if my subscription is really worthwhile.”
I hold SRT Marine Systems (LON:SRT) but I wouldn’t give up Stocko just because, in this instance Mark S, writes something I don’t accept about one of my holdings. We should know the company better than Mark who has to quickly review far more stocks than we hold. FWIW I plan to hold for the long term – or a takeover occurs which I would try to oppose.
I think you need to retain some perspective here, rwh3ue. I share your view that the emphasis of these reports has shifted away from small caps a little more than I would wish (although some of the large cap comments are useful and no doubt most of us have a blend of small and large caps in our portfolios).
However, I get the sense from your frequent posts about SRT Marine Systems (LON:SRT) that you are simply a bit miffed that others don't share your obvious enthusiasm for the stock. Clearly the recent contract wins and pipeline have the potential to make this stock a multi-bagger from here. The trouble for many of us is that this has been a 'jam tomorrow' stock for longer than almost anything on the UK market. It has raised fresh equity repeatedly and accumulated seriously large losses. Maybe this time really is different and I admit that the company finally looks much closer to a breakthrough moment. However, we literally have no idea about any of the following; 1. Contract execution risk 2. Contract cancellation risk 3. Expected operating margins 4. Product reliability 5. Product competition 6. Cashflow constraints 7. Cappex requirements etc, etc, etc.
Mark actually commented that it would be good to have a national champion in this space and I agree. I want to like SRT Marine Systems (LON:SRT) but personally I can't get past management's poor track record on overpromising and under-delivering. I wish you luck, but I can't see that this stock yet merits Stocko's full attention.
Perhaps the corruption charges in the Philippines against the CEO dampen enthusiasm.
Sorry, you feel I didn't cover this depth. I tend to match my coverage to the size of the news. So in this case, I didn't consider an already announced contract to add much more meat to the situation to do more than a nsb. Especially, as Roland covered this in some detail when it last had news on the DSMR.
I have owned SRT in the past, so I have a pretty good understanding of the core technology and the opportunity, having chatted to management in depth. However, my view on this is a little clouded by the fact that this was in 2014, and my (slightly patchy records) show I sold in the mid-high 30's, a level I probably could have bought back at during 2025 if I had so desired. At the time, the Validated Sales Pipeline was said to be over £200m, and it took them over a decade to get cumalitive sales over that level.
So while I do genuinely wish them (and shareholders) success, I also know that they have a history of taking a lot longer to deliver on these big order numbers than we would sometimes like. I recognise that I may be looking at this with a historical lens, but also history can be a useful guide, as those who forget it are often destined to repeat it.
I don't begrudge you your scepticism with regard to SRT Marine Systems (LON:SRT), especially since its broker shares it too.
The contract updated on today and rather misleadingly referred to as "new" was not allowed for in the broker forecasts when first announced and is still not in them after today, hence there is naturally no change to the forecasts.
The broker will include this contract once the project financing is finalised. That will take some months yet. When (although sceptics will say "if") that happens, forecasts will rise materially and the share will look cheap.
The SRT CEO has learnt from his history of over-promising. He no longer attempts to put timelines to the contract finalisation process but recent history has been that they always come through in the end.
Don't fall in love with shares ... we date them; not marry them. SRT Marine Systems (LON:SRT) has a mixed past and it is fair to say the CEO has something of a chequered past as well:
Two independent sources report that Simon Tucker, CEO of SRT Marine Systems, has been ordered to stand trial in the Philippines on multiple graft charges connected to a 2018 vessel‑monitoring contract:
In my humble opinion, The implications for valuation are material because they affect contract credibility, financing, and execution risk—all of which are core to SRT’s investment case.
One last wee point meant in the best possible taste and with the utmost courtesy: folks often say things I disagree with here and I dare say people sometimes view my ramblings as missing the point, or dare I say, just plain wrong. Alternative views make a market (or for every buyer there is a seller) and I certainly would not leave Stocko because someone disagreed with me. If I took that approach, I would have no friends , my wife would leave me, my dog avoid me and my family would give me a very wide berth. All I would be left with is a collection of 15-year old Glen Livet.
Alastair
References:
Philippine court demands SRT Marine chief executive faces corruption charges
Trial for ex-BFAR execs to continue
I was having the same thoughts about Vistry (LON:VTY). Results are inline (they claim), and the CEO departure is an orderly retirement. And yet the shares are currently down 18%. General investor nervousness? I'm talking myself into a top-up here...
Gulf Marine Services (LON:GMS) Re todays announcement - Another one to think about topping up - but at what point.
I was thinking the same thing. I don’t hold currently but I’ll take a position if we see 16s again.
The risk of a GMS boat being hit is low. Whilst there may be a small impact on the day rates in the very short term, this will be small, after all they've been asked to evacuate by the operating company. However, looking further out the day rates IMHO will go up substantially due to the increased operating risk, a similar thing happened in Iraq at the height of insurgency.
I plan to add small amounts over time.
The risk of a GMS boat being hit is low.
I agree, and just to be clear, I was joking about shareholders wanting the boats to be hit in order to improve the company's capital alloction strategy via an insurance claim.
What I am concerned about is the projects that they support being suspended or cancelled due to safety concerns or the uncertainty of getting oil out of the Gulf, not the chance of a direct hit on one of their vessels.
Day rates may strengthen due to operational risk increasing, but if fewer projects are undertaken, then utilisation and overall market dynamics may weaken.
It seems there are lots of moving parts based on many different scenarios. However, I do think the events in teh ME and the response of customers increases the risks overall.
Mark, a little humour is always to good to see.
The oil industry is a ruthless industry and operates in some of the most hazardous and cut throat environments in the world, as demonstrated by the current ME situation. The resources in the Persian Gulf have some of the lowest costs of recovery and often in shallow water, it's business as usual for most operating companies. They're well accustomed to operating in conflict zones, Iraq, Libya, Syria etc...
In these situations, governments normally act to provide extra security for the facilities, which I think will happen here. Future projects are unlikely to be delayed, the opposite is more probable.
In the current situation I would not be surprised if production is curtailed for a short duration as inventories build due to constraints in the strait of hormuz. However, this will be followed by an urgency to make up for lost production.
Also, I believe some of the existing platforms will need to be modified to accommodate new security equipment/facilities. In some cases new security platforms may need to be built, in light of the new reality.
In both of the above cases, GMS services will see increased demand and higher day rates.
Of course there are risks of operating in live war zones and there are many unknown unknowns. You're quite right to urge caution.
It's worth noting that a lot of the work that GMS undertakes is maintenance related and cannot be delayed easily if future production plans are to be met.
I WAS a holder of Gulf Marine Services (LON:GMS) but i would refer people to Mark's comments on 26.1.26 - there is an absence of detail from the company about the charter RATES about which GMS used to report, and the cost of the new vessel. Zeus do not appear to have access to these details, and say in their note of 28.1.26 that the ME market is very competitive.
I don't have access to Panmure's report of 28.1 but "Fleet addition boosts outlook" doesn't inspire me.
I will, however, acknowledge that Zeus express some optimism, but would rather wait for sustainable evidence of improved EPS and book value/share that would lift the sp after a flat 2 years
Vistry (LON:VTY) baffling market response to what looks like reasonable numbers. EPS is in line with expectations. Does the market not like the CEO leaving? Or is it that the news that first half margins for FY 26 will be lower due to sales incentives? Its not as if there was much of a run up in the shares beforehand..
Vistry (LON:VTY)
there has to be material downgrades to current/future earnings to cause this drop - so i would default to hatchet job on forecasts - lower margins. pretty shitty of the board if the bad news is being delivered by brokers rather than board themselves.
Or is it that the news that first half margins for FY 26 will be lower due to sales incentives?
I would say probbaly yes - full on profit warning without having the decency to say it looking at the drop today !! -
#VTY In a business where margins have been under pressure for many years an acknowledged further reduction will always be seen as a big negative. Plus a business where the MO is already based on large volumes and lower margins. I'm not too convinced on the business model either. Fitzgerald will always be connected with the previous profit warning linked to the lack of major cost control and his joint CEO and Chairman roles
Vistry (LON:VTY)
i agree with you to a certain degree - i have only a small stake here - it was a bit of a punt after all the bad news came out - with the already decent discount to ntav and decent profits being expected - there is perhaps some decent downside protection even if future profits dont hit levels currently expected (that though process has failed miserably today) - i was hoping it had bottomed out ref bad news and that the clear need for new housing at some stage should up volumes (perhaps labout have already given up the fight here which is annoying). so it probably serves me right for investing in company where i dont full trust mangement - so i wont argue with anyone who is skeptic here - if they have trollied expectations today without saying it in straight terms - thats another black mark. in some respects i think current mangement leaving may be a plus point (i was very unimpresed by them blaming one region for accounting issues when their job as the is to overseas making sure that cant happen )- albeit there is always chances stuff may be kitchen sinked by new bods with further bad news.
Bought a few this morning for a possible bounce........or not!
Stock Rank MTI Wireless Edge (LON:MWE) above says 86 but its detail page shows 91. Which is correct? It is important to me as I filter on SR...
Hi Greedo,
StockReport shows 86
Perhaps you have other regions active? When I have UK focus it matches the 86.
Mark
SRT Marine Systems (LON:SRT) announce signing of new $261m contract. CEO also added
"Given the current geo-political circumstances in the Middle East, we also take this opportunity to provide a brief update on our other existing projects and systems. Today, we have projects being successfully implemented and operated across Asia and the Middle East. The current challenges in the Middle East have highlighted the critical importance of sovereigns having their own independent civil defence and surveillance systems, and we continue to make good progress working alongside all our sovereign partners and their MDA programs and operations."
SRT Marine Systems (LON:SRT)
Note just to flag up that by the looks of it that this is the same $200 million contract (exact value not quantified at that time) they already announced back in september - so as far as i can see its just confirming that value has now been confirmed as being $261 mill rather $200 estimated previously.
From the 18 September 2025 announcement:
The award is subject to completion of the project contract and a project financing package: neither of which is guaranteed and is likely to take many months.
From today's announcement:
Today's announcement confirms that the formal project contract has now been signed, with a final value of US$261 million. The signing took place at a formal event at the customer's premises, attended by senior representatives from the customer, the UK Government, UKEF and SRT.
Activation of the project contract, and thus commencement of implementation, is subject to completion of a UKEF-supported project finance package, upon which work has now commenced.
So they have added $61m to the indicated contract value and passed the "completion of project contract" milestone.
Just the financing to go and, having already got UKEF support on a previous contract, this will hopefully be a quicker, slicker process this time round.
SRT Marine Systems (LON:SRT)
Not sure about it being quicker and slicker EC. UKEF are not known for rapidity so my guess is it will be some months before they formally comit to the loan guarantee. I do, however believe it is not in doubt so it leaves SRT in the happy position of having time to organise before having to start in earnest, unlike Kuwait where it was mad scramble owing to the customer wanting a very rapid start.
The longer term is looking very encouraging. I believe the £1.8bn pipeline doesn't include this $261m contract. More significantly so far as investors are concerned, SRT is starting to look much more credible and may soon start to attract institutional interest.
I think the phrase "carpe diem" is appropriate here. I certainly would if not for being fully loaded..... and some.
Why would you say that you don't think this contract is included in their pipeline? $200m of it almost certainly is in there already, since it was first announced back in September.
SRT Marine Systems (LON:SRT)
I quote from a post elsewhere
"The broker's note in January had this to say.
'In context of £1.8bn visible contract opportunities, <b> key near-term upgrade catalysts include: </b> 1) the contracting and financing agreement confirmation of the new $200m System project (notification of contract award received Sept-25)"
SRT Marine Systems (LON:SRT)
i was surprised by modest rise today initially hence why i looked backover , so i am guessing this was kinda factored in anyway - hopefully holders here are closer than ever to being rewarded. Its been a long hard slog towards the promised land. I would say with foreign governments and the like - until they have the cash in the bank i would always add an extra level of caution compared to your standard b2b or uk based contracts - often new person in charge can cancel anything they want and its just tough luck - or all projects casn be stopped if the easy moneyt stops rolling in. I think SRT Marine Systems (LON:SRT) have been stung in the dim and distant past in that regard.
Netcall (LON:NET) I hold
Excellent half year results today, all metrics showing positive improvement over same period last year. Please can you cover this?
good growth but at a lower margin, no economies of scale???
In response to Phoenix yesterday, I would say the Marco / positioning backdrop is incredibly difficult to ascertain at the moment.
Vix (equity volatility ) is 24 and Move (Bond volatility) is 78. The rate cut story has supported bond markets and allowed yields to fall but 78 is far from stretched ( >100). When equity volatility is above 20 I normally think buy....but in 2008/09 it spiked to 80 so some caution is always warranted. The market reaction so far would appear somewhat orderly and not a panic...and my impression would be overall hedging against market weakness may have been ok.
The Oil market however was enjoying a period of calm with lots of commentary that supply was adequate. Experts were highlighting concerns that there was less over supply than forecast. Still, the price reaction was more muted than fears at the weekend. If the straight of Hormuz is closed the pinch point will be gas and LNG, as some pipelines mitigate the oil price effect slightly....but it is still a risk. European Gas prices have spiked significantly ....in the UK from 75 to 140 but far less than 400 reached in 2022. So thus far the negative affect on GDP and spike to inflation should be lower....which perhaps explains the somewhat calm markets reaction . In the US, $ strength of 1.5% softens the inflation impact ....and has weakened Gold 3.8% and Silver 8.6%....so precious metals are not doing the traditional defensive job...which would have been expected.
What does all that mean? It goes without saying that weaker markets are offering opportunities....and I personally am trying to slip some capital back in - although cautiously. Reports suggest the military action will be forced to fall quite quickly but this is far from clear. How aggressive anyone chooses to be will very much depend on their starting point... I have held too much cash this year so far so it's important to reduce this.... but I will choose how, carefully. I was hoping for some housing and / or Oil measures yesterday in the Spring Statement but we didn't receive anything I have seen yet. As we know the UK energy position is delicate.
The S&P 500 fall so far is only down 2%, suggests plenty of scope for more weakness and in $ it's hardly changed....but the FTSE 100 down 4% - unusually suffering more but closer to a normal 10% correction. The issues remain within the indices where managers have the wrong positioning...which you can see with unusual share price moves. The standard macro analysis would be these periods of volatility are opportunities.... in my view it's too late to increase hedges.
Good luck out there.
The bond market also tells you that this is believed to be a short conflict. 10 year treasuries have been trading in a tight range since the rhino by of the year and you have not seen yields compress due to the ME conflict and therefore the flight to safety is (not) yet happening. If the bond market is correct, it might be a buying opportunity in equities…
Our position is similar RDHOWARTH. As FT Alphaville put it today when commenting on the Kospi - are markets bending or breaking? Imo it's too soon to buy but I'm tempted!
John Authers on Bloomberg also leans towards a short conflict.
“Thus the odds are that the war burns out after a matter of weeks, falling far short of the damage inflicted by the world wars or by the Yom Kippur War.”
“But even though this selloff looks like a buying opportunity, it’s not free money. If it’s an opportunity, it’s only because the risk is real. Those buying must hope to be compensated for that risk. Their chances are good but less than 100%.”
The Russian economy was and is much more important for the world economy than Iran.
The Russian / Ukraine war started on 24th February 2022:
FTSE100 bottoms out 8 days later with a fall of 7%. Recovers back to pre war level 21 days after that. In other words it takes 29 days for the market to ignore that war.
I expect the FTSE and other markets will recover faster than 29 days this time. I think this is a buying opportunity.
Hi Epitychia - Is it the comparison between the Russian and Iranian economy respective sizes that is important here? OR is it Irans ability particularly geographically, to target the straits of Hormuz and adjacent counties.? That disruption to world trade and travel security is surely much more influential
I have read today that the conflict duration will depend on who has more missiles or missile counter measures. The pace of War is apparently still all about logistical supplies!
I agree that closure of the Straits of Hormuz would have a huge impact. I assume that the Americans would not allow this to occur for very long.
The Chinese might have a say too as they take a chunk of Iranian oil. Probably quietly by back channels. And what of India?
My understanding is that India were recently encouraged to move away from Russian black fleet oil to Saudi & another state (can't remember sorry, but maybe UAE) and now they find that supply compromised
Wasn't it during the First Gulf War when the Netherlands refused to sell the UK howitzer shells?
Re Iran Conflict - This is not about geographical land grab as Russia / Ukraine, so conflict will NOT be localised on a front line
Energean (LON:ENOG) have 70% of their production via a single FPSO located approx 90Km off Israel in the Med. They shut it down immediately as it could be a natural missile target for Iran, yet the share price to date has had limited damage. One would assume that is because of the rise in Selling price of Gas and Oi. yet 70% of their production has been halted.
The key recovery to markets is for how long as you suggest the conflict continues. Will Iran look to longer distant "targets" over the next few weeks? Mid East Airport Hubs have already disrupted long distance air travel such as UK - Australia. Container vessels will be going the long way as well and that will be reflected in rising cost and longer supply times This is a different conflict than Russia / Ukraine
The irony ATM is that America is reduced in the impact compared to Europe and Asia!
To be fair FTSE 100 was a bit of an outlier as it is very commodity weighted, from memory most asset classes bar commodities had a torrid 2022 long bonds in particular.
Thanks RD always appreciate your measured macro views.
SRT Marine Systems (LON:SRT) I Hold, (quite a few)
This $261m contract is not unexpected; it was flagged up last year as awaiting signature. Today's news says that UKEF will now have to guarantee the loan which will come from a bank and I expect this to take some months. Given UKEF were at the signing event and the prior work that has been done, this will have been agreed already.
I have consistently pointed out here, that SRT is the only game in town when it comes to providing these complex systems. Anyone who still thinks SRT is a jam tomorrow stock should think about these words in the RNS
"Following today's new contract signing, SRT has approximately £340 million of active projects under implementation, a further US$261 million contract now signed and pending commencement, and a new-contract prospects pipeline with an estimated value of up to £1.8 billion. This pipeline of active and pending contracts reflects growing demand for independent sovereign MDA capabilities, our national scale integrated MDA technologies and SRT's successful project delivery track record."
Hi Graham, I hope your going to cover the excellent results at CRN. I've held this since it sieved on many of my growth screens, and Slater to @ about 97p , it is a main holding ,so rather pleased. Note upgrades for 2026 . Of course Ireland is in a sweet spot financially with first time buyer backing from govt. there ,a very different situation ,from the sorry state here . Tony
Hello, would you be able to add CRN Cairn Homes to the list if you have time?
Cairn Homes' annual results look excellent. together with an upgrade for the current year. The market and level of government support are much more positive in Ireland that in the UK. € exchange rate risk, but looks a good investment. I hold. Don't have time to write more.
Hi Perry, now added.
We tend to leave out companies headquartered in Ireland that report in Euro on the first pass (we have to draw a line somehere to keep the news list as relavent as possible), but are always hapy to add them in if there is demand from subscribers.
Thank you Mark