Daily Stock Market Report (Wed 7th Oct 2026) - BOWL, HSW, CAML, AVON, LIKE/HEAD

Good morning!
It was a tough day for Asos (LON:ASC) (down 7%) and its customers yesterday with a hacking incident that saw some ASOS app users receiving a copy of the extortion note sent to the ASOS data protection officer and IT teams.
In an announcement published shortly after 3pm yesterday, ASOS said:
Basic personal information including name and contact details may have been accessed. We do not believe that payment-card information or account passwords, were impacted.
Hopefully that’s the case - no payment or password info accessed. But it’s still a potentially serious data breach. And what makes the case unusual, and troubling, is that the hackers also managed to communicate to customers via app notification, on top of the data breach.
Cyber attacks are often costly in terms of short-term customer sentiment and in terms of remediation, but the affected companies usually recover quite quickly, in my experience. I suppose the major exception to that statement is Marks and Spencer (LON:MKS) but even in that case, the company has pulled through.
Overnight market movements:
The FTSE is down 0.3% at 10,510
S&P 500 is flat at 7,820
Brent crude (December) is up 1% at $101.60/bbl
Gold is down 0.7% at $4,135/oz
Bitcoin is down 1.5% at $84,350
Finished for today, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£209bn | SR99) | Gas production is expected to be 740-780 kboe/d in Q3, up from 631 kboe/d in Q2 and ahead of previous expectations for 570-630 kboe/d. Other guidance is broadly unchanged. | ||
IMI (LON:IMI) (£7.4bn | SR76) | iSMA CONTROLLI, a leading provider of intelligent building automation systems, will become part of IMI’s Climate Control sector. iSMA is expected to generate revenue of €40m and operating profit of c.€4.5m in 2026. | ||
Bridgepoint (LON:BPT) (£3.1bn | SR45) | The ECP V fund is delivering “exceptional performance”. As a result, 2026 EBITDA and performance-related earnings are now expected to be “materially ahead” of consensus. 2027 EBITDA margin guidance is also upgraded. Shareholder distributions will be increased to reflect an expected uplift in cash receipts to £2.4bn over the next five years (versus £500m over the last five years). The FY26 dividend will be increased from c.10p to 15p per share. | ||
Pennon (LON:PNN) (£2.13bn | SR38) | New CEO Keith Haslett has identified “areas where we need to improve”. Planned capex over AMP8 is now expected to be c.£3.6bn, around £1bn more than previously planned. To help fund this, Pennon has cut its dividend and is carrying out a £550m rights issue. Rights issue: 7 new shares for every 15 existing shares, at a price of 250p per new share (a discount of 35.5% to the theoretical ex-rights price). | ||
Galliford Try Holdings (LON:GFRD) (£699m | SR96) | Appointed to Oxford Inspire framework for construction services on behalf of the University of Oxford. Galliford has been selected for Lot 2, which is worth up to £1.6bn over eight years, for projects in excess of £15m in value. | ||
Dr. Martens (LON:DOCS) (£641m | SR94) | The company has published historical financial data in its new reporting structure “to aid investor understanding”. Dr Martens has switched from regional reporting to market-based reporting and now only reports two segments, US and Global Markets (ex US). | ||
Avon Technologies (LON:AVON) (£577m | SR45) | Trading has been strong in recent months and FY26 results are now expected to be ahead of market expectations, with revenue growth of 12.5% (previously c.9%) and an adjusted operating margin “comfortably above” our guided range of 14-16% - albeit this includes “some beneficial one-offs”. | AMBER ↑ (Roland) While I don’t want to dismiss our previous concerns around valuation and quality, Avon has generated a string of EPS upgrades over the last year and appears to have confidence in the medium-term outlook. To reflect the combination of improving momentum and a low StockRank, I’m moving our view up by one notch to neutral today. | |
Acceler8 Ventures (LON:AC8) (£516m | SR19) | Hui10 (a Chinese lottery) has seen total registered users rise by 113% to 1.7m over the last year. Connected shops are up 277% to 13,651. Outlook: the “current outlook assumes a significant acceleration in commercial activity during 2027, driven by continued network expansion, increasing customer conversion and the development of additional revenue streams.” | ||
VAALCO Energy (LON:EGY) (£458m | SR63) | The offshore Gabon Phase 3 drilling program has been completed successfully, with “encouraging initial well results on the ETSEM-3H well”. Stabilised initial flow rate of c.2,000 bopd has been achieved, with 1,140 bopd net to Vaalco. | ||
Hollywood Bowl (LON:BOWL) (£411m | SR66) | FY revenue +4.3% to £261.6m, with UK LFL -1.4% and Canada LFL +1.5%. Canada strengthened in H2 but the UK weakened. FY26 adj pre-tax profit is expected to be in line with expectations (consensus: £48.0m to £53.2m). | AMBER/GREEN = (Roland) Today’s share price gain suggests to me that investors were concerned Hollywood Bowl might have missed forecasts for FY26. That now seems unlikely, although the range of forecasts remains quite wide, leaving some uncertainty. At current levels I think the valuation looks undemanding, so I’m happy to maintain our broadly-positive view today. | |
Central Asia Metals (LON:CAML) (£268m | SR94) | Q3 copper production -4.5% to 3,454 tonnes. Zinc production +18.2% to 4,968 tonnes. Lead production +21.4% to 7,255 tonnes. Average realised prices for copper and zinc were respectively 43% and 34% higher than during the same period of 2025. Kounrad and Sasa both firmly on track to meet FY26 production guidance. | AMBER/GREEN = (Roland) This looks like a solid update with production on track to meet guidance. Elevated copper and zinc prices are expected to support a near-50% increase in earnings this year. CAML’s low P/E and high yield are tempting, but I think it’s important for potential investors to also consider the risk factors. In addition to the usual risks around commodity prices and fundamentals, I think shareholders need to be aware of the earnings dilution that is likely to result from the Cygnus acquisition, in addition to the execution and financing risk of developing a new mine. I think there’s a risk that shareholder returns could suffer as CAML directs cash into its new project, although the longer-term rewards could make this worthwhile. | |
Netcall (LON:NET) (£213m | SR52) | FY26 revenue +20% to £57.7m with adj pre-tax profit +19% to £9.9m. Adj EPS +17% to 4.39p. FY27 outlook: strong momentum and improved revenue visibility. Currently trading in line with management expectations. | ||
Savannah Resources (LON:SAV) (£166m | SR29) | Barroso Lithium Project certified as compliant with the ISO 14001 standard. Has appointed a FEED (Processing Plant Front-End Engineering Design) contractor. | ||
Likewise (LON:LIKE) (£131m | SR62) | Buys assets from the administrators of Headlam for total consideration of £14.9m in cash. These include: 90,000 sq. ft. freehold Thatcham Distribution Centre, with its operating assets, and inventory on premises; Crucial Trading; Concept Flooring. | GREEN ↑ (Graham) It seems to me that Likewise is only going to take a small fraction of Headlam’s lost revenue. I’d like to know what Headlam’s expected capacity is in pound terms. I think it is still shy of their £300m revenue target, although it may be close. But revenue is less interesting than profitability and Likewise should enjoy a significant boost to its pricing power, now that its rival has been absorbed and dismantled. I’m going to boost our stance on Likewise by two notches today, to fully GREEN, because this seems like a dream scenario for the company: the dismantling of a major competitor, the purchase of its most useful assets from administrators, and control of its leftover inventory. | |
Hostelworld (LON:HSW) (£127m | SR34) | Mid East conflict to continue to weigh on volumes for the remainder of the year and into 2027. Now expects FY 2026 revenue growth of approximately 10%, and an adjusted EBITDA in the range of €20.0m to €21.0m (FY 2025: €19.9m). FY27 net revenue growth in the mid-single digits. (GN note - I have a long position in HSW. FY26 revenue growth was previously expected at c. 12% with EBITDA of c. €23m. FY27 revenue growth was previously expected at c. 11%.) | PROFIT WARNING (AMBER/GREEN ↓) (Graham - I hold) This is not a blue-sky share that was trading at a sky-high valuation before this warning. As of last night, it was trading at a P/E ratio of less than 8x. The market has been very sceptical about this one - and based on today's profit warning, one can easily argue that the market has been right so far. I still think this company is seriously undervalued, but I appear to be in a minority position - and the company’s actions don’t seem to be convincing anyone thus far. | |
Roadside Real Estate (LON:ROAD) (£98m | SR12) | Operational Update and Maiden Dividend Declaration | Following the £1.25m acquisition of the former Sainsbury's site in Coventry last year, the redevelopment is now complete, and the site has reopened after a further £1.7m of capital investment. Maiden final dividend in respect of FY26 of at least 0.36 pence per share. | |
Brave Bison (LON:BBSN) (£87m | SR36) / System1 (LON:SYS1) (£43m | SR72) | Brave Bison has increased its offer to 180p in cash and 2.394 new Brave Bison shares, with a contingent value right that may deliver 20p per share in cash. Implied total value is 405p for each System1 share. | TAKEOVER | |
Helix Exploration (LON:HEX) (£70m | SR5) | “We are delighted to complete Ollie #1 under budget and in record time - a benefit of the Company owning its own drilling equipment.” | ||
Colefax (LON:CFX) (£68m | SR98) | Tender offer to purchase up to 12% of shares. Price will be the lower of 1350p and 105% of the average share price (last night’s close: 1345p). | ||
Manolete Partners (LON:MANO) (£18m | SR54) | H1 realised revenue +23% to £17.4m, “underpins the Board’s confidence in achieving market consensus expectations for the full year of £30.6m realised revenue and adjusted realised profit before tax of £1.5m.” | ||
RC365 Holding (LON:RCGH) (£15m | SR20) | Target International Trustee Limited becomes the second subscriber to RCGH’s Wealth Management System. SaaS fees of $10k per month. | ||
Oriole Resources (LON:ORR) (£13.5m | SR33) | Maiden JORC Inferred MRE for the Project of 32.2Mt… indicating the potential to support a multi-decade limestone mining operation. OOR is “ultimately looking to achieve a royalty-based income that could be used as additional funding for Oriole's gold-focused exploration work in Cameroon.” | ||
Headlam (LON:HEAD) (£8m | SR n/a) | “...a sale of certain parts of the business and assets of the Group represents the best and most deliverable outcome for creditors… It is unlikely that there will be any return of capital to the shareholders of the Company.” | Shares already suspended from trading. NO COLOUR (in administration) - see comments on Likewise. |
Graham's Section
Hostelworld (LON:HSW)
Down 8% at 93.8p (£112m) - Trading Statement - Graham - PROFIT WARNING (AMBER/GREEN ↓)
[At the time of writing, Graham has a long position in HSW]
It’s been a poor week for my portfolio, with another profit warning hitting me today.
However, unlike IG group (LON:IGG), this is a tiny position for me. Which is just as well.
New guidance
The Board now expects to deliver FY 2026 revenue growth of approximately 10%, and an adjusted EBITDA in the range of €20.0m to €21.0m (FY 2025: €19.9m), representing an adjusted EBITDA margin of c. 20%.
For FY 2027… the Board now expects net revenue growth in the mid-single digits.
These numbers are hardly disastrous, but they are a downgrade compared to what the market previously pencilled in.
For FY26, revenue growth had previously been expected at around 12% (to €105m). New guidance: 10%.
For FY27, revenue growth had previously been expected at over 10% (to €117m). New guidance: mid single digits.
All told, I think this leaves the new FY27 revenue forecast at only around €108m, almost €10m lower than previously expected.
In terms of profitability, the new EBITDA forecast for 2026 is €2-3m lower than previously expected. The new EBITDA margin guidance (c. 20%) is a couple of percentage points lower than previously expected.
So I’m afraid there is no bright spot in this guidance: lower revenues, and lower profitability on those revenues.
Explanation?
The Mid East conflict is blamed for dampening long-haul volumes.
In Q3, Hostelworld’s net transactions fell 2% year-on-year. 30% of their bookings are on routes between Europe and Asia/Oceania. They estimate that the conflict has hurt volumes by 4%.
Furthermore:
The softness in long-haul demand has since extended beyond those routes, with higher travel costs and stronger destination currencies weighing particularly on demand between Europe and the Americas.
So it’s not just the Mid East Conflict that’s to blame. Hostel-based travel generally is suffering, due to what I’d describe as affordability issues.
Net cash: €3m, after a dividend worth about €1m was paid last month.
CEO comment talks positively about the company’s strategic progress:
The platform continued to strengthen. Almost two-thirds of our bed-nights are now booked in the app, where the social network lives, and engagement accelerated, with chat users up 37% and messages up 77%. The higher commission rate funded increased investment in paid social to grow the member base.
Graham’s view
I’m not panicking here, partly because I don’t own many Hostelworld shares, and also because the company remains profitable and is still growing. It’s just a shame that growth is now expected to be noticeably lower than we previously thought.
This is not a blue-sky share that was trading at a sky-high valuation before this warning. As of last night, it was trading at a P/E ratio of less than 8x:
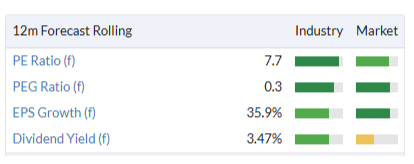
To my eyes, this is bargain territory for a successful online travel agent with a well-defined niche. The market has been very sceptical about this one - and based on today's profit warning, one could easily argue that the market has been right so far.
My comments on this stock in July still ring true: I argue that the shares were attractively priced, while also acknowledging that there was “every chance of a minor profit warning if Middle East disruption continues.”
We’ve now had that profit warning, and for 2026 it is fairly minor: €2-3m lower EBITDA, and revenue growth that’s 2% below expectations.
What bothers me more than the 2026 downgrade is the 2027 downgrade. Mid-single digit expected revenue growth seems rather weak to me, especially considering the company’s strategic progress when it comes to building its own social network and various other new features for its users.
I’m downgrading our stance on this to moderately positive, as it appears that I was overly optimistic here. It still strikes me as a bargain in P/E terms, and the company should have excellent reinvestment options with all the cash flow it’s generating.
So I’ll be watching carefully to see what they do with this cash flow. Over the past year, I’ve questioned their capital allocation: they spent €10m on a tiny events discovery business which the CEO insists was a good deal. They also spent £4m on a share buyback at higher prices than the current level.
Hopefully, it’s more obvious that their use of cash over the next year is working out well for shareholders. I still think this company is seriously undervalued, but I appear to be in a minority position - and the company’s actions don’t seem to be convincing anyone thus far.
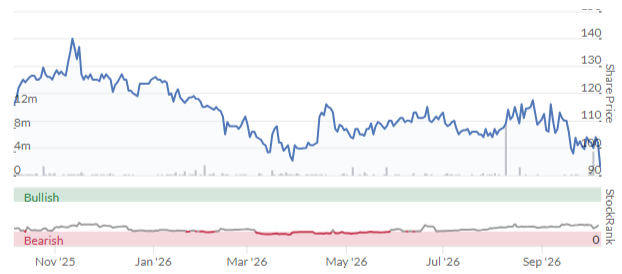
Likewise (LON:LIKE) (and Headlam (LON:HEAD) - suspended)
Up 7% at 38.5p (£136m) - Strategic Acquisition - Graham - GREEN ↑
Let’s do some financial archaeology: here’s a Headlam RNS from September 2016, almost exactly 10 years ago.
Headlam (LSE: HEAD), Europe's leading floorcoverings distributor, announces that, after more than 25 years with the business, Tony Brewer is stepping down as Group Chief Executive. Tony, who was Group Chief Executive for 16 years, has been instrumental in building the group, and the board would like to place on record its thanks and appreciation for all that he has achieved.
Mr. Brewer was replaced by the Finance Director, who offered “not only an in depth knowledge of the group's operations and financials but also a strong skillset for the future development of the business.”
But things haven’t worked out well for Headlam over the past ten years. For eight of those years, it has been competing with Likewise.
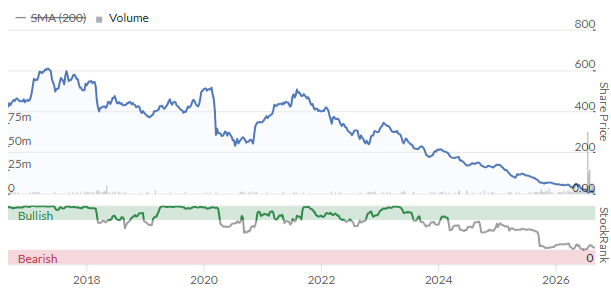
Today, Headlam says that “it has become clear that a sale of certain parts of the business and assets of the Group represents the best and most deliverable outcome for creditors”. Furthermore:
…it is unlikely that the funds secured from the Disposal and any further realisation event(s) will be sufficient to meet the claims of the unsecured creditors in full. Consequently, it is unlikely that there will be any return of capital to the shareholders of the Company.
Headlam’s net debt as of June 2026 was £36m.
This might not seem very large compared with expected annual revenues of over £500m, but it is when the company is unprofitable and illiquid.
The buyer of Headlam’s businesses and assets is… Likewise. Under Tony Brewer..
For £14.9m, Likewise is buying:
The 90,000 sq. ft. freehold Thatcham Distribution Centre, with its operating assets, and inventory on premises
The trade and assets of Crucial Trading
The trade and assets of Concept Flooring in West Bromwich and Stoke-on-Trent
Principal intellectual property
…and probably a few smaller assets, too.
110 employees will transfer over.
And this is nice:
The Company has also entered into an agency agreement to assist the joint administrators during the next nine months to sell Headlam's remaining inventory in an orderly manner as to not disrupt the UK floorcoverings market.
“Disruption” (cheap, firesale prices) would be unhelpful for Likewise and for Headlam's creditors. So it’s nice for them to be able to “assist” the administrators in preventing that.
Comment by Likewise CEO Tony Brewer:
The Acquisition is a key milestone for the Group as it now becomes the leading distributor of floor coverings in the UK. The acquisition of the Thatcham Distribution Centre adds significant capacity to the growing Likewise distribution network and the purchase of well-known brands together with the Crucial Trading and Concept Floors businesses are very welcome additions.
Estimates
As noted by iwright in the comments under this report, Likewise’s house broker Zeus (many thanks to them) have been looking at this deal.
They note that Likewise has “acquired selected assets rather than the whole revenue base”, i.e. Likewise have not suddenly purchased £500m of revenue - far from it. But they are “well placed to capture a meaningful share as customers seek continuity of supply”.
In terms of capacity, Zeus says that Thatcham centre adds 17% to capacity and that together with other sites, capacity is set to rise to 728,000 square feet, up 37%. But earnings forecasts have not yet been updated for the assets that have been acquired.
The 2027 forecasts as they stand are for revenue of £210m, EBIT of £8.2m, and adjusted EPS of 1.4p.
Graham’s view
It seems to me that Likewise is only going to take a small fraction of Headlam’s lost revenue. I’d like to know what Headlam’s expected capacity is in pound terms. I think it is still shy of their £300m revenue target, although it may be close.
But revenue is less interesting than profitability and Likewise should enjoy a significant boost to its pricing power, now that its rival has been absorbed and dismantled.
I’m going to boost our stance on Likewise by two notches today, to fully GREEN, because this seems like a dream scenario for the company: the loss of a major competitor, the purchase of its most useful assets from administrators, and control of its leftover inventory.
It doesn’t get much better than that in terms of a boost to competitive positioning.
Likewise diluted its shareholders in July but the resulting cash boost means that it can easily afford this acquisition. Almost like they saw this coming.
Bravo, Tony Brewer.
Likewise shares are not cheap in P/E terms, but this is a low-margin business and I think a small increase in profitability on revenues approaching £300m could quickly change this picture. The market cap is <£140m.
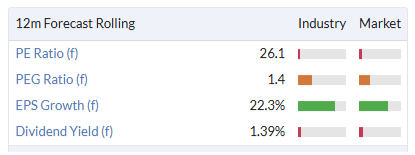
This isn’t the type of business that I’d be inclined to stay GREEN on long-term. But when news flow is as positive as it is today, I think it makes sense. Zeus were forecasting after-tax profits of £5m in 2027, before this happened. Surely there will have to be substantial upgrades here in due course, stretching out to 2028 and beyond
Roland's Section
Hollywood Bowl (LON:BOWL)
Up 7% at 264p (£444m) - Full Year Trading Statement - Roland - AMBER/GREEN =
Share price movements are often triggered by a mismatch between investor expectations and reality. Shares can fall on good news and may rise on bad news.
When I covered Hollywood Bowl’s half-year results in May, I suggested that the positive market response suggested “investors were expecting much worse”. I have a similar feeling today.
Hollywood Bowl’s share price is up by 7% in early trading this morning, despite today’s full-year update revealing a marked slow-down in UK trading during the second half of the year, which ended on 30 September.
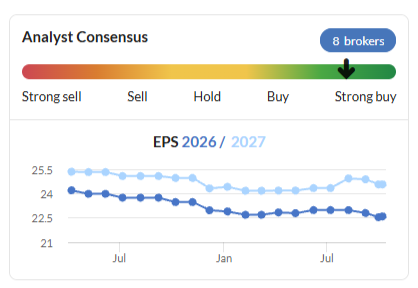
Fortunately, the first half of the year was strong enough to allow Hollywood Bowl to maintain guidance for profits to be in line with expectations. Given the downward drift to consensus this year, this may be better than some market participants were expecting:
Full-year update - key points
I think it reflects well on companies when they present good and bad news with equal clarity, as Hollywood Bowl has done today.
Management has provided a full breakdown of revenue for H1, H2 and the full year, split by geography and including LFL figures – all the numbers investors want to see:
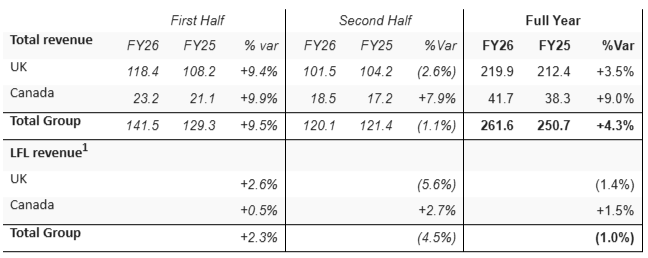
The contrast between total revenue and like-for-like figures makes it clear that Hollywood Bowl has continued to expand over the last year, building out its Canadian business and expanding its UK footprint:
Four new centres opened, taking group estate to 95 centres
Remains on track for 130 centres by 2033
Ongoing investment in the group’s Canadian operations also appears to have driven improved LFL performance in H2.
Unfortunately, LFL growth was still negative last year, with particular weakness in the UK:
UK revenue fell by 2.6% in H2, with like-for-like revenue down by 5.6%
Full-year LFL revenue fell by 1%, suggesting that existing centres may have seen lower volumes and/or seen pressure on pricing.
Outlook & Guidance: FY27 remains a mystery at this stage, but the company does provide in line guidance for FY26 profits today:
Expected to deliver Group Adjusted PBT growth for FY26 in line with expectations
Management says that “disciplined cost controls and dynamic pricing” helped to mitigate the impact from the weather. Profit expectations are unchanged with respect to consensus forecasts, details of which are given as:
FY26 adj pre-tax profit consensus range: £48m to £53.2m
Mean of analysts’ forecasts: £51.0m
In H1, adjusted PBT was £32.1m, so the consensus range implies a figure of £16m to £21m for H2.
Hollywood Bowl doesn’t indicate where in the range pre-tax profit is expected to fall, but for context I think the equivalent figure last year was £49.4m (given as adjusted pre-tax profit pre-IFRS 16).
Based on these figures, it’s possible that profits could fall this year while remaining technically in line. However, my guess is that a small increase in profits is more likely.
Broker consensus EPS estimates on the StockReport support this view with a FY26E estimate of 22.6p, 5% ahead of the 21.5p reported last year.
Roland’s view
UK consumer spending is under pressure and a scorching UK summer meant that indoor attractions were likely to suffer. The company admits that UK performance was “heavily impacted” by the weather.
Growth in Canada remains promising and the group’s margins appear to have remained broadly stable last year, although we can’t be exactly sure yet.
Overall, I think this is a respectable performance. I don’t see any reason why Hollywood Bowl can’t continue its gradual expansion in the UK and Canada.
The StockRanks view Hollywood Bowl as a Contrarian stock, with strong value and quality but uncertain momentum. That seems fair to me. While growth is currently quite weak, I think the valuation already reflects this, with a P/E of 11 and 5%+ dividend yield.
My view remains broadly positive, so I’m staying at AMBER/GREEN today.
Central Asia Metals (LON:CAML)
Up 1.6% at 153p (£269m) - Q3 2026 Operations Update - Roland - AMBER/GREEN =
CAML owns the Kounrad copper operation in Kazakhstan and the Sasa zinc-lead mine in North Macedonia. The company is also in the process of acquiring Australian firm Cygnus Metals, which owns a copper-gold mine in Canada.
Today’s operational update looks broadly positive to me and appears to support full-year production guidance:
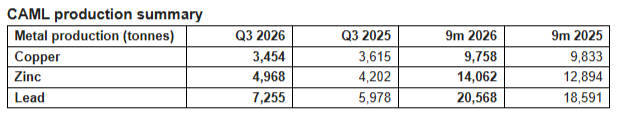
The increase in zinc and lead production at the Sasa mine is attributed to “a significant improvement in head grades plus greater tonnes mined and processed”.
Assuming similar levels of production during the final quarter of the year, it seems fair to assume CAML will meet full-year production guidance, which is unchanged today:
Copper: 12,000 to 13,000 tonnes
Zinc in-concentrate: 18,000 to 20,000 tonnes
Lead in-concentrate: 26,000 to 28,000 tonnes
The company is also keen to highlight the positive impact of high metal prices in Q3:
Average realised copper price was $14,218 per tonne (+43% vs Q3 25)
Average realised zinc price was $3,841 per tonne (+34% vs Q3 25)
Average realised lead price was $1,859 per tonne (-5% vs Q3 25)
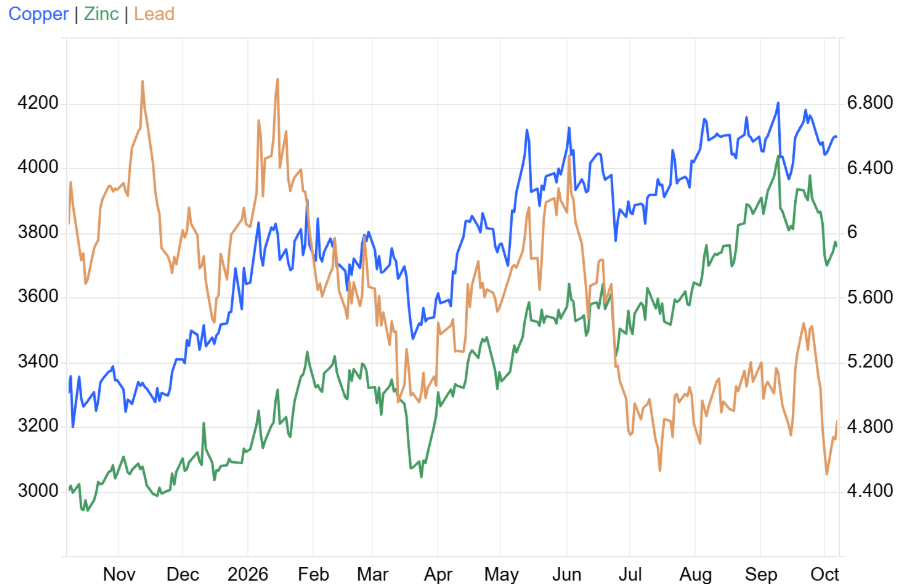
Source: TradingEconomics.com
Outlook & Broker Estimates: high commodity prices are reflected in forecasts for what could be record profits this year (I’m not completely sure).
With thanks to house broker Cavendish, we can see that earnings per share are expected to be nearly 50% higher than in 2025. Cavendish forecasts are unchanged today:
FY25 actual adj EPS: 29.2p
FY26E adj EPS: 42.3p
FY27E adj EPS: 38.3p
FY28E adj EPS: 28.5p
Earnings are expected to fall from 2027 onwards, although this is probably a little speculative at this stage – no one knows what will happen to commodity prices.
Cygnus dilution: what we do know is that there will be a significant increase in the number of shares in issue when the all-share acquisition of Cygnus Metals (ASX:CY5) is completed, which is expected in late October.
Cygnus shareholders are expected to own around 30% of CAML’s enlarged share capital, which I expect to increase from 177m to c.250m CAML shares.
Cygnus is pre-revenue, so there will be some initial dilution to CAML earnings per share and to the company’s dividend.
As far as I can see, this dilution is not yet reflected in broker forecasts for CAML. When broker estimates are updated, we could see forward earnings fall by c.30%, if I’ve understood correctly.
The flipside to this is that Cygnus provides a growth opportunity for CAML, to offset the maturity of its current assets.
Roland’s view
Without looking in detail at CAML’s existing assets or those of Cygnus, I can see some potential risks here.
Dilution: see my comments above. I estimate that adjusting 2027 EPS estimates to allow for the Cygnus shares increases CAML’s FY27E P/E to around 8x. The dividend yield may also fall, assuming the same total payout is split across the increased number of shares.
Commodity price risk: it’s common to see commodity producers trade on low earnings multiples when prices are high. This reflects the likelihood that prices will fall at some point in the future. I think that’s relevant here, even though it seems possible that copper prices could remain elevated for an extended period due to growing demand.
Execution risk: CAML is acquiring Cygnus with the intention of developing its Chibougamau copper-gold project in Canada. We have to trust that the company has studied the project and understood its likely development cost correctly. Even if they have, CAML will likely need to divert free cash flow from its producing assets to fund Chibougamau. This may reduce the amounts available for shareholder returns (or result in an increase in indebtedness).
Empire-building risk: as I’ve commented before, we have to hope that management’s acquisition decisions (Cygnus and previously Sasa) are actually creating value for shareholders rather than just adding size for the sake of size. It is not uncommon for miners to acquire assets that prove less productive or more costly than originally expected.
Taken together, I think these factors help to explain CAML’s seemingly low valuation:
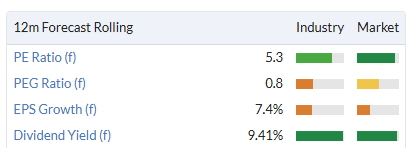
Having said all of that, I do think CAML remains reasonably valued and is a fairly decent business. The StockRanks suggest a similar view and apply Super Stock styling:
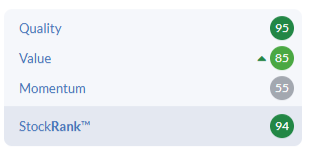
I’m happy to leave our AMBER/GREEN view unchanged today, with the caveat that investors need to consider commodity pricing as well as company performance when considering this stock.
Avon Technologies (LON:AVON)
Up 15% at 2,190p (£660m) - Strategy Teach-in and FY26 Trading Update - Roland - AMBER ↑
Teach-In: the first part of today’s announcement from protective equipment specialist Avon deals with new financial targets being shared with analysts at a presentation today. In short, the company will target annual EPS growth of “greater than 10%”, supported by modest organic growth and selective acquisitions.
That’s all in the future, however.
FY26 update: what is more concrete today is that Avon now expects FY26 results to be materially ahead of expectations, following a strong close to the year:
The Group has seen strong momentum in recent months, with the order book rising significantly since the half year results.
Highlights mentioned include new US Air Force orders and the renewal of the Australian Defence Force programme.
Upgraded guidance:
FY26 revenue growth of approximately 12.5% (previously c.9%)
FY26 adjusted operating margin of 14% to 16%, albeit this includes the effect of some beneficial one-offs in the year. The FY25 operating margin was 12.8%.
Return on Invested Capital (ROIC) to be “significantly above” previous guidance of >17%.
Broker estimates: with thanks to broker Zeus and Research Tree, we have access to updated forecasts today.
FY26E adj EPS: 142.4c (+18% vs 121c previously)
FY27E adj EPS: 157.6c (+21% vs 130.6c previously)
FY28E adj EPS: 174.0c (+17% vs 148.7c previously)
Zeus appears to have confidence in the increased size and visibility of Avon’s order book for future years.
Roland’s view
We’ve been cautious about Avon, with Mark maintaining an AMBER/RED view in July, citing the stock’s low ValueRank and declining momentum.
I share Mark’s concerns about valuation, especially as reported (not adjusted) profitability metrics have been very average in recent years:
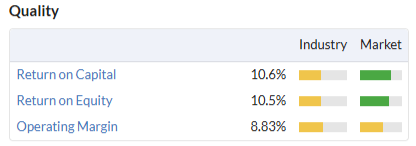
However, momentum appears to have recovered and Avon has now generated a string of broker upgrades over the last 18 months:
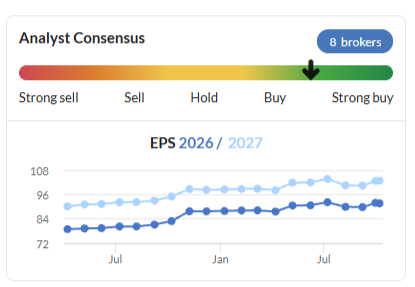
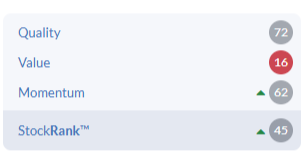
Against this backdrop, the valuation isn’t necessarily unreasonable. I think it’s fair to move up to a neutral view today, despite the indifferent StockRank:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Hostelworld (LON:HSW) There are so many OTAs. I don’t see the incentive to book via Hostelworld when the big players like Trip and Agoda have generous points reward schemes along with plenty of listings for budget accommodation. Add the rise of ChatGPT and Meta‘s Muse for agentic bookings, and it’s a long way to go before Hostelworld can offer anything different (apart from a catchy name).
On Hostelworld (LON:HSW) the social network is a conundrum.
Usage stats are up massively, which implies that its working as a unique feature that distinguishes booking on HSW vs other platforms vs direct to hostel.
And the company believes that it does drive more transactions per customer - 10% more.
However, with already 67% of bookings already from social members... is this a growth driver anymore going forwards?
More worryingly, "non social member bookers" who presumably are first time customers, declined. Which is bad news. HSW is unable to attract growing numbers of new customers to add to their base of social members.
So it looks like HSW have built something that is useful for customers, but not really driving amazing commercial outcomes (only +10% uplift from the stickiness) and on top of that isn't really good at acquiring new customers either.
I think the PE ratio pricing at less than 10x is about right.
Central Asia Metals (LON:CAML)
thanks for the update. I invested and hold for the dividend yield. I am on the edge in terms of the future as the company has used a lot of Revenue to invest in the likes of Aberdeen and other exploration in Kaz without this producing anything worthy of mention. Were the copper price to come back at a time when the company needed to spend heavily to bring Cygnus into prduction then I can see the dividend being rebased ( nobody says ' cut ' these days do they) which would undermine the investment case for me. The need for the investment clearly increases the risks here although acknowledging if these goes well the shares would deserve a higher rating.
I previously posted after the update that I had doubts over the management for reasons detailed and I see nothing here that changes that view. I do not generally invest in small mining stocks so changing the modus operandi as Cygnus does makes me wary. What we would term a ' weak hold' in analyst parlance.........
Avon Technologies (LON:AVON) Mr Rebel shows leadership again. So I suggest you check out his work on Hilton Food (LON:HFG)
Isn't Hostelworld (LON:HSW) a good example of the benefits of the stock rank tools. Excellent projected revenues and earnings growth but terrible stock rank scores - only for the brave. Not a stock for me...unless the stock ranks suggest otherwise at some point.
I just stayed in a hostel listed on HW in Corfu town. I bought via booking.con. I would normally have bought direct. B must have been cheaper. Hw is getting worse! Bus Opp. There is only 1 hostel in CT! and it's a 15min bus from the centre. Crazy
Central Asia Metals (LON:CAML) is on a forward PE of under 5 with a yield of 10%? Cheap? Appreciate any insight from the team.
Revs, (I hold) Grahams last view was the firm was fairly valued and is thus a play on commodity prices. I wish I had listened as I am at a loss. But I added a little today
BT (LON:BT.A) Further comment on the Talk Talk deal suggests that even with higher churn which could be expected given TT was always seen as a lower cost operator than BT, the total expected synergies amount to something like £150m next year which in the context of paying £400 m is peanuts. Assuming this deal goes ahead ( bad for BT if it does not given they supply the BB infrastructure for TT so a material hit from losing a big customer) Mr Market may be undervaluing
The half-expected Pre-emptive Action Order has been applied today. I'll continue to hold BT (LON:BT.A) .
Just seen a summary of a note from JPM who I think are still broker.... they maintain Buy and comment they expect the deal to be high single digit cash flow accretive to BT (LON:BT.A) which I "guess" is £2-300m which I also guess is not a stretching target. I don't want to get carried away with my rubber calculator but there can't be much cost from TalkTalk that BT (LON:BT.A) can't cut... so I expect the revenue of TalkTalk to be very accretive. Of course customers that leave for a sweeter deal will hurt this so it's important that BT (LON:BT.A) can speak to them and keep them as quickly as possible. JPM seem to think the regulatory issues are manageable and market share isn't a problem. All good from JPM then which is nice....
BT (LON:BT.A) was sitting pretty on a low valuation and a FCF yield set to double... although a stretched balance sheet. This deal potentially increases income and FCF so that's a double win ...if it goes through. Assuming it does all go through .... this could be that rare gem that ticks all boxes with earnings and FCF moving in the right direction and defensive earnings should the market run out of steam. If more of the competitors are now swallowed up in a round of consolidation - all good. Openreach long term value will only be enhanced and the decision to build fibre vindicated.
re BT (LON:BT.A) I can also add that JPM say the £400m reported cost includes the £100m TalkTalk owes BT (LON:BT.A) Openreach and the £60m forecast loss for 2026.... so hmmm .... the real cost to BT (LON:BT.A) is very low indeed. Fingers crossed this makes it.
You make a number of valid points and I cannot see the deal being thrown out becuase you have a lot of homes and businesses that would need to transition to another supplier quickly and we are talking large numbers here. I am not sure you can draw parallels with the energy market where there are 5 big players but even the less than smart Nandy cannot fail to see that a smooth transition is vital given messing about is not a vote winner. There are not a lot of alternatives given BT supply the TT infrastructure. The report on the acquisition is due very quickly and it is hard to see how this really has time other than to accept the principal but maybe call for a longer term review of the market which BT would further dominate ( commission ' get out of jail free' card)
I do think this will go ahead but there are going to be caveats to a straightforward acquisition or at least this seems to be what the muted reaction of Mr Market indicates. As I said before hard not to rule out future anti monopolistic action because that is the type of socialist thinking that prevails.
A fairly good day for Nuclear followers yesterday as Google signed a huge deal with Constellation Energy (NSQ:CEG) for a long term power purchase agreement sending the latter shares up 13%. The power of the AI $ - excuse the pun! The follow through to others like Cameco (NYQ:CCJ) was decent enough and Uranium caught a bid. I have largely dismissed the AI part of the Uranium story but having certainty of power contracts is exactly what the industry needs to kick Strat plants into action. So I continue to hope that the tight market feeds into spot prices soon and propels Yellow Cake (LON:YCA) and Geiger Counter (LON:GCL) forward. The spot price has done ok in a correction and finely poised at the moment but renewed strength in $ is unhelpful ...as Gold and silver retreat and show a strange correlation to Uranium at times. Fingers crossed for decent final quarter.
Hollywood Bowl (LON:BOWL)
Chapeau to Stephen Burns and the management team to deliver a trading in-line update given the summer heatwaves. I was anticipating a profit warning.
As a long term shareholder with a good sized position I am more than happy to continue with my investment. Growth may not be stunning, but it is steady and there is plenty to go for in Canada. Given its cash generation and as the only listed ‘player’ in its field I would anticipate that at some point it will be subject to a bid.
Would welcome the thoughts of Graham and the team.
Hollywood Bowl (LON:BOWL)
trading update today is inline
Expected to deliver Group Adjusted PBT growth for FY26 in line with expectations2
they have blamed exceptionally hot weather in uk for poor second half with uk lfl sales down 5.6% in H2 - so its easy to see why shareprice has been weak (does money that matters have insight into their trending sales?)
They have done so well last few years with lfl increases it was perhaps only a matter of time before they hit a poor trading period - was it all about the weather perhaps not. They have managed to come in on expectations as promised though despite that so overall its fine and dandy - albeit i can see some would be cautious with those negative lfl numbers.
They seemed chipper about the new year - but i think we will have to wait for brokers comments to see if there is any tweak to new years expectations - if i had to guess i dont think much will change.
I have this as a pretty defensive share - its uber simple business model and they are expanding from their own resources each year. I might worry if uber low cost competitor entered the market - but i dont see any real sign of anyone wanting to compete on price in this sector - compared to other pastimes its p;robably still very decent value for money.
we had 8% expected growth in profit penned in - dividend yield of 5.7% - p/e of 10.000 before the open - net cash of £13 mill at year end - presming no material downgrades ref expectations for the new year there is nothing really not to like here other than lack of lfl growth in last 6 months - personally over medium term i have no reason to believe they should not be able to put up prices in line with cost of living to maintain margins - ignoring any material government big changes which are beyond their control.
Easy hold for me - infact i bought a bit more yesterday (if i realised trading update for today i would probably have waited for update)
Likewise (LON:LIKE) CEO Tony Brewer spent years building Headlam into the UK's dominant floor coverings distributor, then left to found Likewise in 2018 and spent the next 8 years systematically dismantling it. Today's announcement is the confirmation, not the beginning.
Headlam generated ~£500m of revenue in its final year. A meaningful chunk of that spend is now effectively homeless. Likewise, with 728,000 square feet of capacity post-acquisition and a national network built in part by Headlam's own former staff and their client relationships, is the obvious home for most of it.
The margin story may be the under-appreciated angle. Likewise built its distribution network, fleet and sales team — infrastructure now sized for £250–300m of revenue. As orphaned Headlam volume flows in, incremental revenue drops through at margins far above the group's current sub-4% EBIT margin. At £280–300m revenue, a 7–9% EBIT margin is not impossible.
The Likewise (LON:LIKE) structural setup has never been better.
What EPS do you estimate in this scenario Ian?
Good question because their broker is being coy!
Layering in Headlam, here's how I see EPS developing:
FY2026E
~1.3p Zeus published
FY2027E
~2.3p Zeus 1.4p base + ~0.9p Headlam (£32m revenue at high incremental margins)
FY2028E
~3.0–3.5p Headlam fully absorbed, organic growth continuing. These are my estimates — no broker coverage beyond FY2027
FY2029/30E
~4.0–4.5p
£290–310m revenue, 7%+ EBIT margin, overhead largely fixed
The critical assumptions are: overhead growing modestly as volume scales, and EBIT margins expanding toward 7% by FY2029.
None of those feel heroic given the competitive void Headlam has left.
Bravo to Graham for bumping Likewise (LON:LIKE) 2 notches up to Green, because, "this seems like a dream scenario for the company."
Graham wonders what Headlam's capacity translates to in £revenue terms. No revenue translation from Zeus, but the new 728k sq ft figure gives a clue. Likewise's existing network was generating ~£163m from ~530k sq ft — roughly £308 per sq ft of revenue. At 728k sq ft and a similar utilisation rate that implies capacity for ~£225m of revenue before Headlam customer migration adds anything on top.
But expanded distribution centres are not the binding constraint — the sales team, fleet and cutting capacity are. Likewise has been investing heavily in all three. The £300m Likewise (LON:LIKE) sales target looks achievable on current infrastructure, which is maybe the point Zeus is making when they called 0.8x EV/Sales "too cheap", in their previous note just over a week ago.
Needless to say I topped up today.
As someone who has lost his investment on Headlam, the maxim about only buying businesses that a fool could run because one will run it soon enough comes to mind. Can there be a simpler business than buying, cutting and selling carpet once you could claim to have x6 the market share of its nearest competitor as Headlam did a few years ago.
I haven't seen a deep dive financial analysis but it must have come from losing focus on their profitable small end user market to chase low margin national accounts and open a trade counters. The strategy wasn't bad. The (sales) execution must have been terrible.
@Zipmanpeter,
Firstly, sorry for your loss on Headlam (LON:HEAD) . It's never nice losing money in this game, we have all been there. It hurts and frustrates. You have my sympathies.
If you don't mind me asking, and please don't feel obliged to answer, why were you still holding? To my mind Headlam have been a basket case for a few years. This outcome has looked the most likely for quite a while. Why did you not sell?
I don't ask to gloat or say 'I told you so' (neither are my style, nor should they have any place on here) more from genuine intrigue as to why you wouldn't have sold. I know I have held onto losing positions for longer than I should, so I'm far from the perfect investor, if he/she even exists, but Headlam (LON:HEAD) have looked doomed for a while. What made you continue to hold?
Thanks for your great comments, Ian. G
Good morning Graham - Bridgepoint (LON:BPT) has good reading in their results - worthy of a deep dive ??
I bought after previous comments here and from the firm. V glad today!
I'm afraid I'm not too familiar with this one, Green Adder. Thanks for pointing it out, though - looks like something I should try to study. G
Central Asia Metals (LON:CAML) ops update thoughts appreciated