Daily Stock Market Report (Wed 8th April 2026) - HSP, CBG, SOLI, MOTR, GGP, DFCH, KOO

Good morning!
And a truly good morning it is, with a US-Iran ceasefire having been agreed for the next two weeks.
The ceasefire is conditional on "the complete, immediate, and safe opening of the Strait of Hormuz".
- The FTSE is currently set to open up 300 points at 10,660.
- The German DAX is up 5.4%
- The S&P 500 is up 2.7% in overnight trading.
In commodities, Brent crude has fallen $14 to $92. US Crude oil is down by a similar amount.
Some of the biggest moves are in London Gas Oil (Diesel) (down 20%), UK Natural Gas (down 17%) and Heating Oil (down 17.5%).
Iran will reportedly charge fees for safe passage through the Strait of Hormuz. It will be possible for vessels to travel through it "via coordination with Iran’s Armed Forces and with due consideration of technical limitations".
It's excellent news, but markets are likely to remain on edge until we have confirmation that this two-week ceasefire is the start of a lasting peace.
Finished for today, thanks everyone. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£201bn | SR88) | Gas production is expected to be lower as events in the Middle East have affected Qatari production. Trading profits are expected to be “significantly higher than Q4’25”. | ||
GSK (LON:GSK) (£85bn | SR93) | Exdensur (depemokimab) approved in China for the treatment of chronic rhinosinusitis with nasal polyps (CRSwNP). Trials have shown “clinically meaningful” improvements in polyp size and nasal obstruction. | ||
| Greatland Resources (LON:GGP) (£5.2bn | SR89) | March 2026 Quarter Production Update | Quarterly production of 82.7koz Au and 4.1kt Cu (prior quarter: 86.3koz AU & 3.5kt Cu). Greatland currently expects full-year FY26 production around, or slightly above, the upper end of the production guidance range of 260,000 - 310,000oz Au. | AMBER = (Roland) [no section below] The main takeaways from today’s update are that gold production is expected to be at the upper end of guidance this year and that Greatland’s cash position rose by $260m to $1,208m during the quarter. Although the company says it will now start making regular cash tax payments, this cash pile adds credibility to the company’s plans to self-fund $1,065m of pre-production capex on the Havieron project. The mature Telfer mine appears to be performing well and management note that it has some protection from energy market disruption due to long-term supply agreements for gas and diesel. As always, the wildcard here is what could happen to gold prices in the period between now and when Havieron moves into production. Greatland could still be cheap at current levels – or it might not be at all. I’ve no idea so I am remaining neutral – as are our algorithms. |
Renishaw (LON:RSW) (£2.6bn | SR61) | John Shipsey has been appointed CFO with effect from 13 April 2026. Previous experience includes Dyson Limited and Smiths Group. Interim Chair Sir David Grant has been appointed Chair for up to two years. | ||
Close Brothers (LON:CBG) (£587m | SR47) | Close estimates cost of FCA redress scheme at c.£320m, “broadly similar” to the existing provision of £294m. This would reduce the group’s CET1 capital ratio by 0.25% to 14.0%. | GREEN = (Graham) It's a relief that no major increase to the provision is likely to be needed. Checking the half-year results, I see that there was tangible net asset value per share of £8.70, far above the current share price. So this remains a GREEN for me, on value grounds. I admit that I’m out of line with the StockRanks (the StockRank is only 47), and it’s a complex situation. However, the new CEO has been in the job for only a year and seems determined to reinvigorate performance. Given the strength of the balance sheet, there is the potential for shareholders to see some serious returns if he succeeds. | |
Young & Cos Brewery (LON:YNGA) (£470m | SR91) | Acquired Cubitt House London Pubs comprising eight pubs in West London plus one under development. | ||
Tungsten West (LON:TUN) (£455m | SR36) | Targeting restart of phase one in Q3 2026; market conditions have “further strengthened project economics”. In the final stage of due diligence relating to the remaining project debt package of up to $85m. Reached settlement with Hargreaves Services and concluded a £22m equipment financing deal with McHale Komatsu. | ||
Intuitive Investments (LON:IIG) (£413m | SR58) | Acceler8 Ventures (LON:AC8) has made a possible all-share offer for IIG of 2.6052 new AC8 shares per IIG share. Based on yesterday’s AC8 closing price of 80p, this values IIG at c.£600m, a 50% premium to yesterday’s close. IIG’s board is minded to recommend an offer at this level. | PINK | |
Hargreaves Services (LON:HSP) (£254m | SR97) | Hargreaves has now received the final £3m due from Tungsten relating to the 2019 sale of its mining lease. Tungsten has also notified the company of its intention to terminate the mining services contract and will pay £7m compensation to Hargreaves by 15 May 2027. | AMBER/GREEN = (Roland) [no section below] Under the 10-year mining services agreement with Tungsten, Hargreaves was originally expected to handle 100m of ore and crush 30mt of granite after the mine began operating. The company never put a value on this contract publicly, but COO Simon Hicks describes the £7m payment as “representing the acceleration and de-risking of several years of trading activity”. This suggests to me that the company will end up adequately compensated for the lost business. While not all that large, these numbers are not insignificant for a business that generated £23m of operating profit last year. In my view they demonstrate this company’s usual thorough and careful approach to contracts. I’m leaving our broadly positive view unchanged today. | |
Capricorn Energy (LON:CNE) (£222m | SR97) | Further to the announcement on 11 March 2026, the PUSU date has been extended to 5pm on 6 May 26 to allow Alamadiyaf al-Masiyyah additional time to progress funding arrangements. There is no certainty any firm offer will be made. | PINK | |
Aptitude Software (LON:APTD) (£119m | SR36) | Audited Results for Year Ended 31 Dec 25 & Synapse New Logo Wins & Strategic Review and Formal Sale Process | 2025 revenue down 7%, ARR -1%. Adj operating profit up 1% to £10m, EPS -17% to 7.3p. Have launched a strategic review to “assess the optimal path to accelerate the Group’s strategy”. This will consider options including a sale, raising additional equity capital and seeking a strategic partner. | |
Motorpoint (LON:MOTR) (£109m | SR36) | Retail volumes up 8% to c.65k in FY26m, a record level. Pre-tax profit expected to be +83% at c.£7.5m, with ROCE of c.70%. New store opening in Leeds in Summer 2026. | BLACK (AMBER/RED ↓) (Roland) I was ready to turn more positive on this used car supermarket group until I realised that the company’s house broker has cut FY27 EPS forecasts by 30% today due to higher interest rate expectations than previously forecast. Disappointingly, today’s RNS didn’t make this clear at all – only investors with access to broker notes are likely to realise the scale of this change in outlook. Today’s revised forecasts leave Motorpoint trading on a forward P/E of 17, which looks high enough to me. To reflect my concerns about valuation and today’s downgrade, I’ve moved my view down by one notch to be moderately negative, in line with Motorpoint’s low-ish StockRank. | |
Distribution Finance Capital Holdings (LON:DFCH) (£92m | SR67) | Loan book up c. 26%, including recently launched asset finance product. Stock days in the core inventory finance product extended “slightly” to 141 days (previously 129 days). Portfolio quality “strong and well within credit appetite”. “Whilst the macro-economic and geo-political landscape remains uncertain, the Group has not observed any immediate systemic or supply chain impact across its manufacturer, dealer and distributor customers.” | GREEN = (Graham) | |
Solid State (LON:SOLI) (£79m | SR57) | Strong trading, revenue and adjusted PBT for FY March 2026 ahead of consensus expectations. Open orderbook c. £106.5m, up from £97m four months ago, “primarily as a result of strong order intake in the Power division”. Order book to be mostly delivered over the next 18 months, subject to supply chain availability. Supply chain lead times “have started to extend significantly for certain components”. | AMBER/GREEN = (Roland) There’s evidence of improving momentum here, benefiting from defence-related demand. But the company also flags up the risk of supply chain disruption that could push back the completion of orders. It’s too soon to know whether this issue will recede following today’s ceasefire. Earnings forecasts for FY27 have been left unchanged and are now broadly flat versus FY26. On balance I’m encouraged by progress and am happy to remain broadly positive ahead of Solid State’s full-year results and FY27 outlook guidance. | |
Kooth (LON:KOO) (£39m | SR59) | SP +4% Revenue falls 5%, or 2.7% at constant currencies, after doubling in the prior year. Results are “broadly in line” with market expectations. Adj, EBITDA falls 28% to £11.3m. PBT £4.4m (prior year: £9.9m). Outlook: in line. | AMBER/GREEN = (Graham) [no section below] Mark has been moderately positive on this one (see here) and I'm happy to leave that unchanged after today's "broadly" in line results and an "in line" outlook statement. They express some disappointment that revenue fell in 2025 , even if this is partly due to currency movements against them. The main US contracts are still intact but they saw lower US revenue from "contractual product development activity". UK revenue also fell by a few percentage points, and the combination of softer revenue with higher marketing expenses resulted in a sharp drop-off in profitability. I also note that management enjoyed £1.1m of share-based payments (last year: £1.2m) despite the company only generating an operating profit of £3.3m. But what really stands out to me is net cash of £21.6m, with no debt. Given that cash backing relative to the market cap, I'm happy to leave our moderately positive stance unchanged today. | |
Coiled Therapeutics (LON:COIL) (£36m | SR5) | Clinical trial update for AO-252, “a first-in-class TACC3 inhibitor”. TACC3 is a protein found in cancer. 80% Clinical Benefit Rate for twice-daily dosing, vs. 40% Clinical Benefit Rate for once-daily. 80% achieved tumour stabilisation or regression, with treatment durations exceeding six months. | ||
Solvonis Therapeutics (LON:SVNS) (£18m | SR19) | Granted a second U.S. patent by the US Patent and Trademark Office covering a further monoamine modulator compound series arising from its proprietary PTSD discovery programme. | ||
Sunda Energy (LON:SNDA) (£11m | SR22) | Agrees to buy Matahio NZ which owns and operates a group of production and exploration permits within the onshore area of the Taranaki Basin on the west coast of New Zealand's North Island. Has conditionally raised up to £6.7m to fund the acquisition. |
Graham's Section
Close Brothers (LON:CBG)
Up 17% at 456p (£688m) - Update in relation to motor finance commissions - Graham - GREEN =
In addition to the general market euphoria today, there is some positive company-specific news at Close Brothers:
As set out below, the estimated cost of the scheme as published is c.£320 million, broadly similar to the group's existing provision, and can be comfortably absorbed by existing capital resources, leaving the group well positioned to continue delivering its strategy.
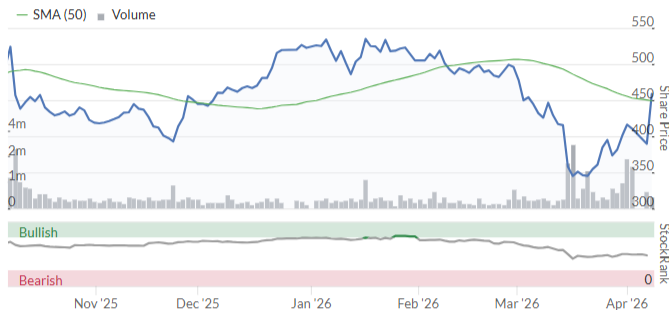
I gambled on this one on October 14th, marking it “GREEN” when the company updated its provision for motor finance redress to £300m.
My reasoning was pretty simple: tangible NAV per share was £9.10, and the increased provision would only reduce that by about 90p. The share price was about 450p.
Given that the FCA had already provided quite a lot of detail on the proposed redress scheme, it seemed there was a good chance that the provision might be reasonably accurate.
The CBG share price has unsurprisingly been rather volatile since then:
Today’s announcement in a little more detail:
The redress scheme as currently proposed would result in a c. £320m provision, vs. the actual provision of £294m.
The CET1 safety cushion would reduce by 0.25% to 14%, comfortably ahead of the group's medium-term target of 12-13%.
It’s assumed there are c. 720k loans written from 2007 to 2024 under which are likely to qualify for redress.
Average redress payment per customer assumed to be c. £500 including interest.
Estimated claim rate of 75%. For every 5% change in the claim rate, this changes the provision by £18m.
So if the claim rate was somehow 100%, the provision would increase by £90m. But a 75% claim rate is what the FCA has assumed and there must be historical precedent for this.
Conclusion:
The group is well positioned and remains confident in its ability to deliver against its strategy, as outlined at the Half Year Results and business update on 17 March 2026, underpinned by a resilient business model, a strong capital position and a clear focus on execution to deliver long-term value for shareholders.
Graham’s view
I think I’ll stay positive on this. The half-year results show tangible net asset value per share of £8.70, far above the current share price.
In terms of profitability, H1 adjusted operating profit of £65m was down 19% as the business repositioned itself; it’s cutting 600 jobs and massively simplifying itself.
The statutory pre-tax loss was £65m but this included the additional motor finance provision (£135m) which I’m happy to treat as a one-off event.
Therefore, this remains a GREEN for me, on value grounds. I admit that I’m out of line with the StockRanks (the StockRank is only 47), and it’s a complex situation.
However, the new CEO has been in the job for only a year and seems determined to reinvigorate performance. Given the strength of the balance sheet, there is the potential for shareholders to see some serious returns if he succeeds.
Distribution Finance Capital Holdings (LON:DFCH)
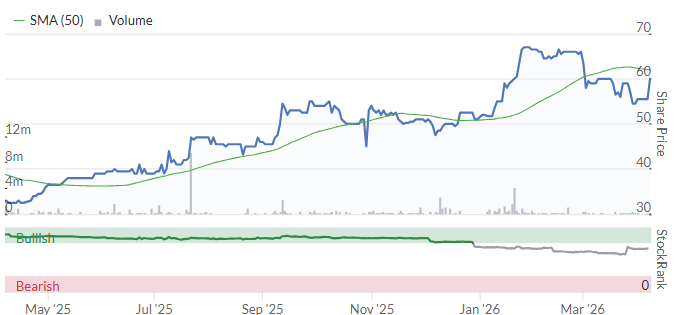
Up 6% at 59p (£99m) - Q1 Trading Update - Graham - GREEN =
Distribution Finance Capital Holdings plc (AIM: DFCH), a specialist bank providing financial solutions that support manufacturers, dealers and distributors across the UK, provides a trading update for the first quarter ended 31 March 2026.
We had full-year results from DFCH recently, which I covered here.
In addition to providing inventory finance for dealers and manufacturers, the company now offers loans to individual buyers of caravans and motorhomes. Funding comes from retail deposits (website: dfcapital.bank).
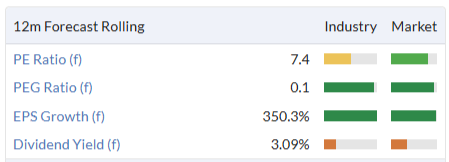
I’ve been positive on this stock due to its perceived cheapness (PE less than 7x, tangible NAV 75.9p per share).
Today’s brief update confirms that it remains on track. Highlights:
Loan book up 26% year-on-year (it was up 27% at the full-year results). Now c. £895m.
Retail deposits over £1bn (sharp increase from £841m at the full-year results).
Portfolio quality “strong and well within credit appetite”.
Some data is provided on portfolio quality and none of it seems particularly concerning (e.g. 0.6% of the loan book is now in legal recovery, vs. 0.9% at the end of 2025).
There’s a possible warning light in the form of an increase in the average age of loans outstanding in the core inventory finance product - from 129 days to 141 days. But DFCH says this is “well within sector tolerances as the Group closes the traditional dealer re-stocking period”.
Trading conditions are ok:
Whilst the macro-economic and geo-political landscape remains uncertain, the Group has not observed any immediate systemic or supply chain impact across its manufacturer, dealer and distributor customers. The Group remains vigilant and considered in its approach to managing credit risk and its lending portfolio.
CEO comment:
It is pleasing to report strong ongoing momentum in lending since the start of the year, demonstrating continued progress against our 2028 and 2030 targets. Whilst the macro-economic and geo-political environment remains uncertain, we are well positioned to navigate this, providing appropriate support - where needed - to our diversified customer base, whilst also drawing on our deep expertise and strong credit stewardship as demonstrated through the economic cycle and most relevantly since authorisation as a bank in 2020.
Graham’s view
I see no need to change my positive stance here.
The discount to tangible NAV is 22% - not huge, but enough to keep me interested. And the growth rates remain impressive.
The usual disclaimers apply: all small lenders are risky.
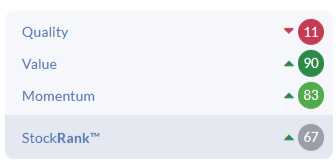
Checking the StockReport, I see favourable scores for Value and Momentum, although not yet for Quality:
If 2030 targets are hit, I trust that Quality will improve:
Loan book in excess of £1.5bn
Cost to income ratio in the range of 45%-48%
Return on required equity of c.20%
Roland's Section
Solid State (LON:SOLI)
Up 17% at 163p (£92m) - Trading Update - Roland - AMBER/GREEN =
Solid State plc (AIM: SOLI), the specialist value added component supplier and design-in manufacturer of computing, power, and communications products, announces a trading update for the year ended 31 March 2026 (FY25/26) and provides an update on its trading outlook.
This small-cap electronics business has been out of favour since a big profit warning in late 2024. But today’s year-end update is ahead of expectations, suggesting the outlook may be improving.
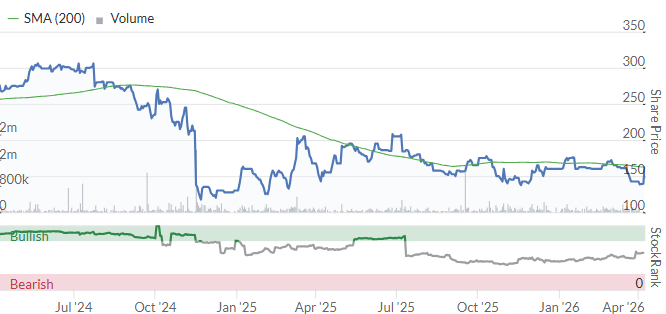
Reading the company’s trading commentary suggests to me that Solid State is benefiting from increased demand for some defence-related products.
Let’s take a look.
FY26 trading update - key points:
A strong end to FY26, “building on the positive momentum achieved in the first three quarters”.
FY26 revenue is expected to be “not less than £150m” (previous consensus: £145m).
FY26 adjusted pre-tax profit is expected to be “ahead of consensus market expectations” of £7.2m.
Open order book at 31 March 2026 of c.£106.5m (30 Nov 25: £97.0m, 30 March 2025: £108.5m)
The order book has grown since November, but remains below the level seen one year ago. Recent growth has been driven by c.$20m of order intake for the Power division since December. The company expects “the majority” of the open order book to be delivered over the next 18 months, but notes potential supply chain constraints:
In recent weeks lead times have started to extend significantly for certain components due to the demand arising from the adoption of AI and the impact of geopolitical instability. The Group is pro-actively engaged with customers to manage any potential impact going forward.
All three divisions have “performed strongly”:
Components: year-on-year improvement benefiting from new design wins in the UK/US.
Power: improvements following restructuring and investment in capabilities – “strong demand from the drone and other autonomous technology applications with significant new and emerging defence opportunities.”
Systems: “continuing strong demand for communications products”, combined with “building opportunities for its antenna and integrated systems capabilities”. These underpin the expected improvement in sales mix going forwards.
Outlook & Updated Estimates
With thanks to Cavendish and Zeus for sharing today’s updates on Research Tree, we have updated earnings estimates for FY26 and FY27 today.
Cavendish:
FY26E adj EPS: 10.3p (+8% vs 9.5p previously)
FY27E adj EPS: 10.5p (unchanged)
Zeus:
FY26E adj EPS: 10.2p (+6.8% vs 9.6p previously)
FY27E adj EPS: 10.3p (unchanged)
There’s no comment from the company today about the outlook for FY27, so I expect forecasts will be refreshed when Solid State publishes its full-year results, which I expect in early July.
Today’s update leaves the stock trading on a forward P/E of around 15.
Roland’s view
I’m relieved to see that I upgraded our view on Solid State to AMBER/GREEN in December following a confident-sounding set of half-year results.
Today’s commentary highlights the risk that supply chain disruption could affect trading this year. I think it’s too soon to say whether the likelihood of this has receded following today’s ceasefire. As things stand, earnings are expected to be flat in FY27, with no growth, which could limit further near-term gains.
However, Solid State has maintained stable expectations since March last year and has upgraded them today.
I think it’s reasonable to assume the company’s 2024 issues are now in the past and would speculate that we could see upgrades to FY27 guidance as the year unfolds, assuming supply chain conditions remain manageable:
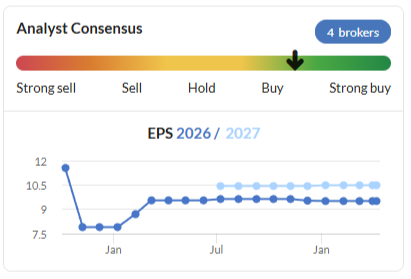
I’m comfortable maintaining my AMBER/GREEN view today ahead of the company’s full-year results.
Motorpoint (LON:MOTR)
Up 4% at 136p (£114m) - Full Year Trading Update and New Store Opening - Roland - BLACK (AMBER/RED ↓)
We’ve been neutral on this leading used car supermarket chain over the last year (here & here) and this has proved to be an appropriate view – today’s share price is almost unchanged on one year ago:
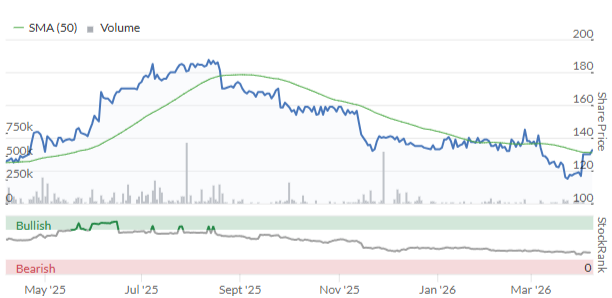
The tone of today’s update is bullish and highlights an impressive recovery in profits last year.
Unfortunately, it turns out that today’s update is our least-favourite type of RNS – the hidden profit warning.
While FY26 looks likely to be in line with expectations, broker earnings forecasts for FY27 have been cut by c.30%.
Full-year trading update
Demand for Motorpoint’s competitively-priced used cars was strong last year:
“Record retail volumes”, up 8% to c.65,000 units, outperforming the market;
Motorpoint achieved 6% volume growth in calendar 2025, compared to 2.2% for the overall used car market (SMMT figures).
The company says that market dynamics are returning to normal, allowing more bulk purchases. Use of data and AI is supporting record margin performance and aiding sales from reactivated historic quotes.
New store: no new stores were opened last year, but one is planned – in Leeds – for this summer.
The financial performance reported today is expected to drive much-improved results for FY26:
Profit before taxation is expected to be c.£7.5m, up 83% (FY25: £4.1m), aided by record metal margin performance, which helped offset inflationary pressures.
This appears to be in line with expectations. With thanks to Shore Capital for providing an updated note today, I can see that Motorpoint’s house broker has left its FY26 adj EPS forecasts unchanged at 6.6p (Stockopedia consensus: 6.8p).
Profitability
CEO (and 10% shareholder) Mark Carpenter expects to report a return on capital employed of c.70% for FY26, “demonstrating the continued effectiveness of our capital light model”.
This would represent a significant improvement compared to the trailing 12-month figures:
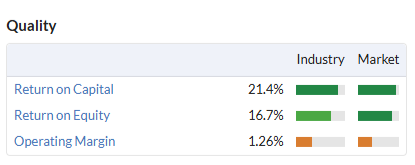
I’m not sure if the company’s methodology for calculating ROCE is the same as Stockopedia’s, but it is certainly true that Motorpoint can be fantastically profitable when conditions are good. The reason for this is that its stockholdings are largely funded using a finance facility, most of which is included under current liabilities on the balance sheet.
Apart from some long-term leases on its sites, the company doesn’t have any other structural debt or significant assets. This results in a very capital-light business; the half-year accounts show £1.3bn of annual sales supported by around £75m of capital employed.
ROCE has previously topped 50%:
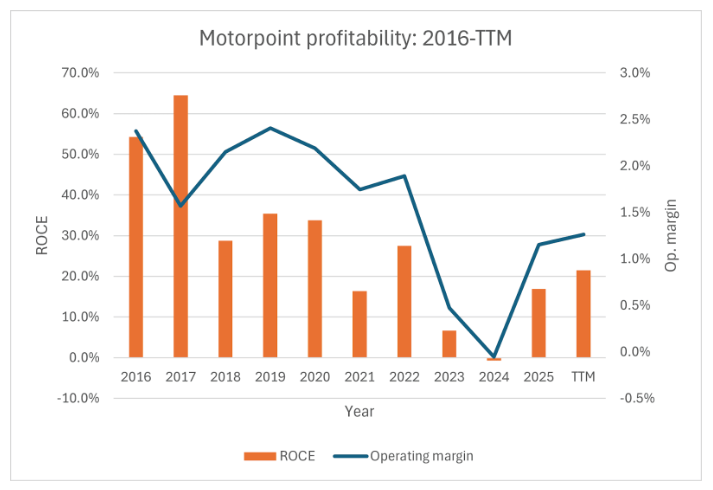
The flipside to this is evident from the chart above. Margins are extremely slim and profitability can be very volatile. Used car price volatility, fluctuating volumes and rising interest costs have all put pressure on margins and ROCE in the post-pandemic period.
Unfortunately the issue of rising interest rates has resurfaced today.
Outlook: FY27 profit warning!
I had thought that the negative impact of higher interest rates on Motorpoint’s business might now have passed. But the war in the Middle East appears to have changed this, as house broker Shore Capital explains today:
Whilst current trading momentum remains unaffected, we do have to consider our expectations for the UK interest rate environment, with even the most dovish of forecasters now anticipating rate increases through the next 12 months rather than the previous 25-50bp reduction baked into forecasts.
As a result, ShoreCap has cut its FY27 and FY28 forecasts significantly today:
FY27E adj EPS: 7.8p (-28% vs 10.8p previously)
FY28E adj EPS: 12.1p (-13% vs 13.9p previously)
This is a big downgrade and appears to be wholly-related to expectations for higher interest rates. Perhaps this highlights a key risk in the business model – and the reason why Motorpoint did so well during the post-2009 period, when interest rates only ever really moved downwards.
Roland’s view
While I think Motorpoint is operating well, today’s cut to FY27 forecasts continues the negative trend seen over the last year:
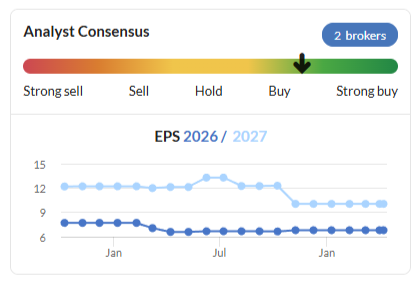
Only investors with access to broker coverage are likely to realise the scale of today’s downgrade to expectations for the current year. I would argue that today’s comment on this topic from CEO Mark Carpenter was far too vague to indicate a c.30% cut to FY27 earnings expectations (my bold):
Whilst the macroeconomic uncertainty in recent weeks leads to a degree of caution due to the risks of increased inflation and interest rates, our superior customer service, omnichannel business model and exciting growth plans mean we are well placed to take advantage of opportunities to further increase market share and build long term value for shareholders.
The path of interest rate rises this year seems likely to depend on events in the Middle East.
As things stand, this cut to forecasts leaves Motorpoint trading on a FY27E P/E of 17, compared to c.13x prior to today.
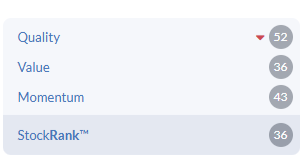
For a business of this kind – whose profits are volatile and sensitive to macroeconomic conditions – I think the share price looks up with events. Our algorithms appear to agree, with a Neutral styling and somewhat low StockRank:
I was originally going to leave my previous neutral view unchanged today, but on reflection I’ve decided to downgrade one notch to AMBER/RED. I think this better reflects the size of the cut to FY27 forecasts, my view on valuation and what I see as poor shareholder communication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Feel like getting out of equities at the moment it’s too volatile- companies announcing great results that go negative on what Trump says / does suspect there will be many more to come
Hang in there. Results do drive stock appreciation eventually just need to be very patient
Graham/Roland,
Gamma Communications (LON:GAMA) put out an RNS at 6pm last night confirming they have been contacted by unnamed parties who may, or may not, wish to make an offer for the company. I've attached a link to the RNS on the LSE website.
https://www.londonstockexchang...
Gamma are up 18% today in response.
I did hold previously, and thought they looked good value at c£7 but obviously in my infinite wisdom I decided not to invest.
I think with the swift movement away from oil and gas, that really interesting opportunities will arise in this sector…oil for a variety of reasons is unlikely to go anywhere near the $65 seen at the start to the year, and wherever it gets to by yearend will take time to unfold…on top of that LNG production is likely famed for 3 plus years.
I imagine the Middle East countries will be looking to maximise output, if they can, to build income and strengthen defences. Will be interesting to see more on the damage caused so far.
Some of you may have seen the RNS at RTC Group and wondered what is happening...
RTC Group Plc
("RTC", "the Company" or "the Group")
Shareholder notification
The Company has today received a formal notification from Mr David Stredder, a 5% shareholder in the Company. Mr Stredder has requested that the Company include the two resolutions set out below (the "Stredder Resolutions") at the forthcoming Annual General Meeting scheduled for 27 May 2026 (the "AGM").
1. To elect Paul Hooper as a director of the Company
2. To elect Gerard Oates as a director of the Company
In accordance with the Companies Act by virtue of Mr Stredder's shareholding he is entitled to either requisition an EGM for shareholders to consider resolutions he considers appropriate or requisition the Company to include resolutions at its forthcoming AGM. The Company by abiding by Mr Stredder's instructions is fulfilling its legal responsibilities under the Companies Act.
The Board of RTC will outline a full response to the Stredder Resolutions in the notice of AGM to be circulated to shareholders in due course. At this time the Board wishes to inform shareholders that the Stredder Resolutions have been proposed by Mr Stredder without prior consultation with the Board. Despite being informed of the process being followed by the Board to appoint a further non-executive director, Mr Stredder has chosen to continue with the Stredder Resolutions.
It is the Board's view that by virtue of the candidates being known to and proposed by Mr Stredder, they cannot be considered independent, rather proxies for Mr Stredder.
The Board believe the Stredder Resolutions to be without merit, and an unnecessary and inappropriate distraction as they anticipate appointing a further independent non-executive director who has significant relevant experience within a measurable timeframe.
On 23 March 2026 the Company announced record equalling results for the year ended 31 December 2025 and a 10% increase in dividends for shareholders, and the Board will remain focussed on continuing to deliver increased value for all shareholders rather than serving a specific interest group.
Further announcements will be made in due course.
Ends
I am proposing the new directors, one of whom is the very highly respected Paul Hooper who last week retired from being the CEO of Alumasc plc, because in my view corporate governance has been an issue especially in the last few years. The company is performing well, it has a stockrank of 99 but that should not be a green light for directors remuneration to be off the scale in a £12m market cap company with a board costing almost £1.75 million.
There were ZERO non executive directors at all for three years just after Covid and even though no dividends were paid in 2020, 2021 and 2022 the directors still took out huge bonuses in 2020 and 2021. In fact in 2021 the bonuses were almost identical to the profit before tax reported by the company and that is on top of good salaries considering the market cap fell to just £2.5m in the aftermath of the pandemic.
There are currently three exec directors including an executive chair/ceo in a combined role and just one NED who frankly needs support in creating a much more investor friendly company where the board are rewarded sensibly and there is a strategy that shareholders can relate to.
At present and for the last nearly ten years there have been...
No broker research notes
No forecasts for investors to see and so no price targets
No presentations to investors (until the IMC last week)
No independent chairperson (combined role with CEO)
No results roadshows
No institutional money invested
The company is doing well especially in the current climate but if you are running a public listed company then directors have a fiduciary duty to engage with market participants and should be meeting with shareholders and not just offering an AGM in Derby once a year. I was the only attendee last year btw. There will be lots more shareholders this year as every vote and in person communication will count.
If any of you want to join the huge support group (we currently hold 24% of the shareholding) or have any previous experience to pass on then do contact me David @ Melloevents.com
Investors need a fair return for their capital invested
A shareholder win here will help investors in many more companies across the market
Many thanks for reading and any support you offer
David
Good luck David …you make some excellent points re RTC (LON:RTC)
The latest TACO avoids BOGNOR (boots on ground - no off ramp).
Hopefully oil, gas, aluminium, helium, sulphur, fertiliser shipments now resume and help avoid the cliff edge which was days away for some countries and industries. The question is how quickly and what volumes, subject to insurance, Iran's transit tax and payment sanction considerations.
All progress to resolve this ill-considered and poorly planned conflict welcome but 2 week ceasefire and the lack of progress on Gaza equivalent point to need for cautious view as we enjoy today's relief rally.
Looking forward, will the government finally publish the defence investment plan, revisit the decisions on UK O&G (taxation, licences, storage and refining capacity)? Will they also find solutions to accelerate their green energy agenda by accelerating the review of using gas generation cost to price electricity and use of battery storage and hydrogen solutions?
Separately, the announcement of a cap on student loans is a step in the right direction, but seems to be too little too late. The margin (collar) should have been set lower (say 2.5%) and it is notable that the Treasury have effectively opted for the highest possible rate by using RPI, when they have been retrospectively amending other agreements to CPI to cut UK Gov interest and other costs (pensions, renewables (RO + FiT) and even gilts). Reducing this burden on working graduates not only improves the government's electoral prospects, but should reduce loss of skilled workers and their taxes due to migration and help stimulate the house buying market.
Hargreaves Services (LON:HSP) tender offer looks a little less generous after today's ceasefire bounce and news of the Tungsten West settlement. I hold and wondered if anyone had run the numbers to assess the impact ahead of the 23 April acceptance deadline (ii)
Hargreaves Services (LON:HSP) if you added 7-8% to your holding on Jan 28 when the Tender Offer was first announced you could have bought at 714p or better, got the 19.5 dividend and then sold those shares in the tender for 850p netting yourself > 20% 'arbitrage' in 4 months.
For all you house builders you may be interested in purchasing Bill Blain's book The Battle for Hamble. New out. Gives a good view of the planning situation in UK.
Having been an 'expert witness' in an aggregates planning app I found the synopsis interesting. We lost. The local need for and cost of the material were fully examined. It was very stressful.
For those with an interest in construction, the March S&P Global UK Construction PMI report was released today. Similar to previous months, although the overall decline was not as great as expected.
Residential housing is the weakest area. Cost inflation affecting all construction..
"The month-on month acceleration in cost inflation since February was
the largest recorded in nearly three decades of data collection."
Full report - link below..
https://www.pmi.spglobal.com/P...
Today's uplift has provided some amazing price increases - but why Serica Energy (LON:SQZ) down by a thumping 15% plus ? I'm guessing its largely due government taxation ?
Price of oil is down around 15%.
its a good question, Brent Oil is up still over the month, as is Gas yet Serica Energy (LON:SQZ) is actually down a little.... ultimately share prices go where demand meets supply....and little demand for oil stocks today. Net net no need to panic IMO and obviously Serica Energy (LON:SQZ) is unusually volatile due to Gas exposure I think although this is reduced. I will be keeping mine because I think prices average out higher and a decent chance of some better North Sea news.
It will be interesting to compare what Serica Energy (LON:SQZ) have to say in their upcoming capital markets day presentation against their recent YE IMC comments. I hold
Various reports give the list of Iran's ten point peace plan upon which the US has agreed a ceasefire. Some reports suggest that the points differ slightly in different languages, but the main points are quite interesting.
The Mail reports that Iran would want continued control of the Straits of Hormuz, continued Uranium enrichment, lifting of sanctions etc etc. In short, Iran don't seem to have moved much from their initial stance.
https://www.dailymail.co.uk/ne...
I am surprised that the US has accepted this as a base for negotiation - but it probably wants out. I wouldn't be surprised if Iran does keep control of the Straits and as speculated, charges some sort of tariff or fee for safe passage. Tariffs, I wonder where Iran got the idea from?
I suspect that the Americans take the view that once a ceasefire is in place it’s harder for Iran to want to restart it…even hardcore IRG types will probably enjoy not worrying about being target by various US and Israeli bombs, etc!
I think the toll on Hormuz demand is a good bargaining point for Iran to get economic sanctions removed…which from Iran perspective would probably be far more valuable…still, interesting times!
The weak link there is Israel. They've shown themselves very happy to break ceasefires, and I doubt this one suits Netanyahu. Can the US force them to keep it?
Maybe this is just a Trump head-fake. He's done it before. Agreed something and gone back on his words.
The US is building up troops in the Middle East. Maybe they're not quite ready yet for the ground invasion. In the meantime, Trump's 10 day / extension / 2 day ultimatum / his sworn oath on his grandmother's dead body.... all has passed.
So in order to lull the Iranians into a false sense of security, it would make sense to appear "weak" and "accept" a ceasefire on their terms.
While in the meantime.... continue getting the last few pieces in place for a major, spectacular invasion.
Telling that Israel hasn't raised a much bigger fuss about this "ceasefire" and gone along with it? Maybe they know the Trump plan and are playing along...
All just conjecture in my head IMO!
Iran did not open the Persian Gulf, freely and to all as it is still supporting Hezbollah in Lebanon.
Suez, where France and the UK chickened out.
Hargreaves Lansdown platform down again ! Not a good look, obviously their tech is not sufficient to cope with any sort of volume.
I can log in OK (08:20)
I can log i but cannot trade in any of the stocks that I have tried. I get varying error messages from 'Technical error' to 'trade cannot proceed'. plus the response time to any request is ridiculously slow!
Must be variable, I managed to trade a couple of things without problem this morning.
I’ve had log in problems too and trouble trading- they’re struggling with the fast market
Vote with your feet. Been very good cash back deals recently to switch away.
I have in a sense voted with my feet, Just running down an old 1 year funded ISA to top up pension as and when for the "jam" now I have retired.. Then that will be it with HL, due as many have said - to PPP in recent times
Ceasefire day looks likely to reverse most of the moves of the last few weeks, so $ down, Gold up, Oil down and Bonds up...lastly equities rally strongly reversing losses. VIX and MOVE will likely fall and in theory pave the way for increased risk in portfolios. As usual and like previous events lots of people will call for a retest of previous lows but it has been clear from markets strength of the last few days this was coming. BUT obvious risks remain in place.
Where the AI boom increased economic confidence, events of the last few weeks will likely reduce this. For companies that have faced deferred orders, these orders will take time to return. My confidence in the next reporting schedule from May to September is lower. Whether the market chooses to look through it all will depend on what else is going on. International trade will continue to suffer IMO.
We have to remember last year was good and in many ways anticipating a strong 2026 backdrop. I think that outlook is now worse and so think a different mix and shape of portfolio is needed. This rally is a great opportunity to rebalance and reassess portfolio risk. On a personal level I don't envisage doing much but it goes without saying that if anything I hold moves too far I'll be happy to let it go. I bought quite significant 1 & 1.5 year bonds with my 25% SIPP lump sum the other day which I expect to benefit but I plan to hold to maturity anyway - I am locked in at 4% and happy enough with that.
Enjoy the rally.
Hi Graham, any chance of a look at Greatland Resources (LON:GGP) quarterly update please?
I think it's a fantastic update, but always looking for opinions from those less enamoured than me! :)
https://www.stockopedia.com/sh...
re: GGP, that has been added to the table, TheRaven! I'm not sure if we'll be covering it yet. G
I'm more hopeful, Ive put a few limit orders on the house builders at some point they must pick up bank balances are generally good and sp rock bottom many at covid levels
"No one has commented here yet! Why not be the first one?"
OK. First of all - Good morning!
From a totally unprofessional opinion - my hunch is. ....
Two weeks cease fire is time for the Iranians to stock up on drones (Hormus Strait weaponary) and missiles.
When and if the cease fire ends (most likely) it will start again with a big bang from the Iranian side. Most probably sinking a huge oil tanker or two in the Strait.
That will send the markets crashing. So what I am saying and to the point is that I don't think it time to pile back in to the market if one is sitting on cash. Maybe day trade for a while!
Only saying.
Yeah maybe, but there’s nothing special about the 2week deadline for them. They can do this in 5 years, now they know they can. Nukes aren’t as necessary anymore perhaps?
I don't like the Iranian regime, but it wasn't them that started all this. What makes you think it'll be them that kick off again and it won't be Trump who finds some excuse to start again? Maybe under pressure from his trading mates or perhaps Israel?
But I agree that it's still too soon to think things are settled.
I think Iran will start to assert its 'rights' (debatable) over Hormuz - and start to collect tolls on ships
China, India and a couple of others are probably already paying. Countries that respect the US sanctions on Iran may not find it that easy. This may be interesting (not in a good way).
Iran doesn't have to actually blow up a tanker, it has the capacity and if it announces it, insurance cover will be withdrawn and shipping will stop.
Trump may well threaten the apocalypse on Iran, but Iran has demonstrated the ability to actually deliver the apocalypse to all the gulf states and possibly Israel by destroying the industrial plant and the desalination plants - there isn't much natural water.
It doesn't require great insight to see that those Chinese ships going towards Iran contain parts for drones. Whilst the gulf states are running out of (expensive) interceptors, Iran is building (many) more (cheap) drones.
Unless the US removes sanctions Iran has no other way of funding the $billions of damage Israel and the US have inflicted on it - never mind the thousands of deaths and tens of thousands of injuries - the 'surgical strikes' on military targets did destroy ~25 major hospitals, ~400 health centres and 2 major pharmaceutical plants.
Unless Hormuz opens the gulf states will have difficulty in repairing the $billions (10-30 or more) of damage and paying for it.
Almost all the gulf states - Iran included - have a lot of reasons to want peace. One or two countries do not - and that is their undeniable leverage. And it looks like the US has decided that Europe & the UK are going to help clean up the mess. Yay.