DFS share price down 3% on uncertain outlook statement

Analyst’s view:
We've been neutral on this one, primarily due to a) the sector and b) the balance sheet. It could be argued that the stock deserves an upgrade at a single-digit earnings multiple. However, I tend to be extremely selective when it comes to retailers, looking for net cash, high pricing power and margins, and/or an extremely strong track record. DFS only scores one out of three on that scorecard: it has a great track record of profitability in recent years, but it remains a low-margin business carrying a substantial amount of bank debt relative to net profits. On top of that, today's outlook statement confirms that visibility is poor and that the consumer remains weak.
Down 3% at 129.5p (£306m) - AGM Trading Statement
Some negative news here re: the UK consumer. The last 7 weeks have been difficult for the furniture market:
Over the subsequent seven weeks (GN note: since full-year results on 24th Sep), upholstery market demand has softened further, reflecting continued pressure on household budgets and reduced consumer confidence. The Group has not been immune to this climate, but proprietary banking data1 indicates that our core retail brands, DFS and Sofology, have continued to outperform the wider sector, reflecting the strength and resilience of the Group.
The upshot is that "Against a backdrop of fluctuating footfall, fragile consumer confidence, and the early stage of our financial year, full-year profit expectations naturally carry a wider range of potential outcomes".
Expansion strategy: DFS has been expanding into the adjacent market of non-upholstery Home products, using mezzanine store levels. A new mezzanine level has launched in Leeds Birstall and is trading in line with expectations, providing "further validation" for this strategy.
CEO comment:
“While the consumer environment has remained challenging through the autumn, DFS is well placed within it as the clear market leader with unmatched scale, brand resonance and operational strength. As we enter the important upcoming trading periods, we are focused on what we can control; taking proactive commercial actions to drive cash margins while maintaining tight control of our costs. Our proven model and strategic progress give us confidence in the Group’s resilience through the cycle and our ability to deliver long term value for all shareholders.”
Graham's view
We've been neutral on this one, primarily due to a) the sector and b) the balance sheet.
The most recent full-year results did show a very nice improvement in the balance sheet, as net bank debt fell by £38m to £69m. The leverage multiple reduced from 1.4x to 0.9x, which for many companies would be considered very manageable.
The profit result was also very robust: underlying PBT improved year-on-year from £30m to £45m, and actual statutory PBT improved from £33m to nearly £44m.
It could be argued that the stock deserves an upgrade at a single-digit earnings multiple:
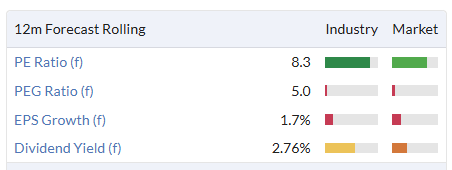
However, I find it difficult not to take a cautious stance in this sector. I tend to be extremely selective when it comes to retailers, looking for net cash, high pricing power and margins, and/or an extremely strong track record.
DFS only scores one out of three on that scorecard: it has a great track record of profitability in recent years, but it remains a low-margin business carrying a substantial amount of bank debt relative to net profits.
On top of that, today's outlook statement confirms that visibility is poor and that the consumer remains weak. The bearish counterargument is that it's exactly businesses like this that should trade on single-digit earnings multiples.
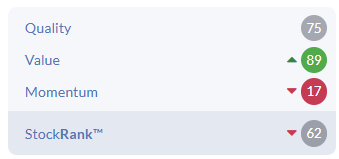
I'm therefore staying neutral on this, which is pretty consistent with the StockRank of 62:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on DFS Furniture (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?