Dividend Strategies Review 2016 - What worked in a year of turmoil?

In September 2016, the value of dividends paid out by UK quoted companies since 2000 broke the £1 trillion barrier. Back in 2000, £42bn found its way back into the pockets of investors, and that’s expected to rise to £82.5bn in 2016. As a result, the second trillion barrier will probably be broken within the next 10 years. But that doesn’t mean life will be easy for income hunters. If anything, 2016 showed just how sensitive dividend stocks can be to political and economic forces.
Factors that impacted on dividend stocks
A handful of factors had a big influence on the dividend landscape in 2016. The first - which has been a constant since the financial crisis - was that low interest rates and low bond yields kept high yielding equities in demand. With nowhere else to go, investors in search of yield turned to dividend stocks.
Big, predictable, high yielding defensives have been a popular target for yield-starved investors in recent years. But given that some believe they’re now over priced, we saw more debate about whether these so-called ‘bond proxies’ (especially consumer staples and utilities) are actually an accident waiting to happen. Time will tell.
Meanwhile, the second development for dividends was a modest improvement in the outlook for commodity stocks… and banks. Some of the UK’s biggest dividend payers have traditionally been found in these sectors. Count among them, BP, Royal Dutch Shell, BHP Billiton, HSBC and Lloyds.
Pressure on commodity prices has called into question the sustainability of these dividends in recent years - indeed, BHP did cut its payout in 2016. Yet the rising price of oil and precious metals had a positive impact on share prices. It was enough for some to suggest that these sectors are turning a corner. As far as the banks were concerned, the big news was the re-introduction this year of a meaningful payout by Lloyds, but the sector still encountered turbulence...
The third and arguably most important influence on dividends this year was the UK’s decision to leave the EU. At a stroke, the vote for Brexit refocused attention on stocks that were less sensitive to the sudden devaluation of sterling and less exposed to the UK economy, where the outlook is now unknown.
The June 23 referendum result was a massive instant boost to commodity stocks and miners and to defensive-like companies with broad international exposure. By contrast, mid- and small-cap dividend stocks were suddenly attracting a lot more scrutiny. It’s still too early to know how many of these firms will respond to the changing outlook, so investors have throttled-back their enthusiasm in some areas.
Dividend strategy performances
With all the mixed sentiment in the market, it was hardly surprising that we saw some very varied performances among the dividend strategies tracked by Stockopedia.
Leading the pack by a considerable distance in 2016 is the high yield focused Dividend Dogs of the FTSE strategy. This has returned an impressive 50.4% before dividends (see chart below). It’s a 10-stock strategy that picks the highest yielders in the FTSE 100, which has put it in a sweet spot all year. In a complete reversal from 2015, it has done well from exposure to large-cap commodity shares like BP and BHP Billiton.
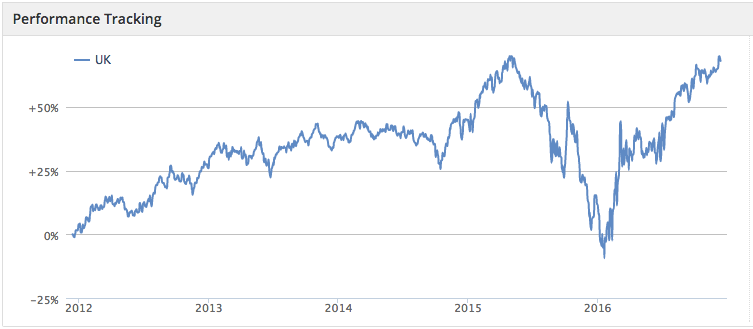
It’s worth noting that it was also holding stocks like Glencore and Anglo American at times during the year. In both cases the dividends were subsequently cut (although their share prices were very strong). It’s a reminder that the Dividend Dogs strategy makes no allowances for the sorts of sector downturns that we’ve seen in mining in recent years.
There are echoes of the same problem of over-exposure in the Forecast Dividend Dogs of the FTSE strategy, which uses forecast yields (rather than current). This strategy has returned just 1.9% in 2016 and the problems really stem from the holdings in the portfolio at the time of the EU referendum. Exposure to several housebuilders, banks and insurance stocks led to some heavy losses in the summer, and it hasn’t recovered. That performance really presses the need for sector diversification and how the highest yields in the market can be bunched together in just a few sectors.
In terms of consistency, the Best Dividends strategy scores well, with a return this year of 7.8% before dividends. This is very much a dividend growth strategy that prioritises a track record of dividend growth, above average yield, low debt and payouts that are well covered by earnings. Those rules tend to pick up mid- and small-cap companies and it’s a very similar strategy to the better known Dividend Achievers, which also held up reasonably well. Despite a sharp dip on the Brexit vote, the performance of both strategies have more than recovered since.
On the flip-side of the successes, strategies that performed badly in 2016 included Quality Income and Large Cap Dividend Attraction, both of which were down over 8.0%. The former strategy has suffered in the past 18 months because of too much focus on UK mid-cap cyclicals and industrials, which have endured patchy performance. The Large Cap Dividend strategy simply hasn’t been diversified enough. It looks for well priced, growing companies with rising dividends and earning upgrades - and that’s been a tall order in the current environment.
What’s the outlook for dividends?
If you listen to commentators, the growth outlook for dividends in 2017 is somewhere between zero and 10 percent. After such a rollercoaster year, it would have to be a brave person to be making predictions about how things will go. One of the big lessons from what we’ve seen from the income strategies in 2016 is that if you’re very lucky, high sector concentration can result in an impressive performance. But for the most part, those strategies weren’t lucky and, at worst, they were over-concentrated in sectors that underperformed. With so many unknowns - from the value of sterling to how Brexit negotiations might unfold - diversification across size and sectors could be more important than ever for dividend investors in 2017.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
...With so many unknowns - from the value of sterling to how Brexit negotiations might unfold - diversification across size and sectors could be more important than ever for dividend investors in 2017.
In my High Yield Portfolio version of dividend investing, sector diversification has always been absolutely fundamental, right from the launch back in 2000. I don't see it as more important now because of Brexit etc., it has always been so.
I recognised from the outset that income investors intending to hold very long term (forever in my version) cannot possibly have any idea of how individual sectors or shares will perform across such timescales, neither their dividends nor the capital values, though a lot of naive investors think they can make such predictions, as do a lot of "experts" who also do this. I learned long ago that predictions, especially about the future, are worthless and dangerous. The only known is the unknown.
The defence against this unavoidable ignorance is wide diversification, turning that compulsory ignorance into what I call Strategic Ignorance, building the lack of knowledge of the distant future into the strategy by diversifying and deliberately avoiding any weighting of the portfolio towards or away from any sector based upon long term forecasts.
Wise washy. No commitment.
Eh? Who? Ben? the strategies?