Don't let a Greek drama become an investing tragedy - perform a portfolio audit

European stock markets have raced ahead this year, helped in part by monetary stimulus and a view that Continental shares looked good value at the turn of 2015. To an extent it seems that investors were prepared to bet that the European economy was finally on the mend. As a result, the FTSE Eurofirst 300 climbed by more than 20% in the first four months of the year.
Yet for the past six years, any investment in Europe has come with the nagging caveat that Greece could cause havoc in the market by going bust, defaulting on its debts and quitting the Euro. In recent days that’s started to look increasingly likely - and markets are pulling back in response. While the outcome for Greece - and stock markets generally - is unclear, these periods of uncertainty are a reminder about how crucial it is to keep on top of portfolio housekeeping. There could be volatility ahead… it’s time to buckle up.
Diversification - the risks of too few stocks
Walter Schloss, the late American bargain share investor who trained under Benjamin Graham, used to diversify his deep-value strategy by holding as many as 100 different shares. In reality, this level of diversification is too costly and far too cumbersome for most investors. Yet the risks of owning too few stocks - or stocks that are too closely correlated - can be considerable.
An examination of 60,000 individual accounts at a US retail brokerage between 1991 and 1996 found that investors were generally under-diversified. The average portfolio consisted of between four and seven holdings. But even those with more stocks weren’t necessarily better diversified. The researchers found that more holdings often meant greater correlation because investors simply picked companies in the same sectors. From the perspective of returns, they found that the least diversified 10% of investors earned 2.40% less annually than the best diversified 10% in the group on a risk-adjusted basis.
But how many stocks is enough? Another study - this time by American professors Gary Newbould and Percy Poon - found that the oft-recommended portfolio size of eight to 20 stocks actually produced a very volatile performance. So they suggested thinking about things another way. Rather than select a specific number of stocks, investors should select a probability of success they are comfortable with and then figure out how many stocks are required to achieve it.
As Ed wrote here, a useful rule of thumb from their study is that to target a return within 20% of an average decile return and risk then it’s wise to have a minimum of 25 stocks in a portfolio.
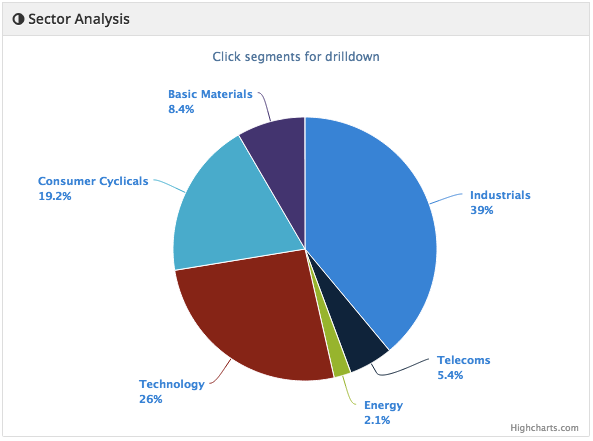
Subscribers can take this further, by creating a Folio on the Stockopedia site, which shows allocation exposures in the stock market without even entering position sizes. It’s a quick way to find over-exposure to various sector types.
Red flags - are there hidden problems?
At Stockopedia, we rank every company in the market according to how well it scores against a range of measures that fit onto the three categories of Quality, Value and Momentum. Historically, portfolios of shares that rank well against these factors have tended to outperform.
Since we began tracking StockRanks in April 2013, portfolios of shares in the bottom 30% of the market have consistently underperformed the FTSE All Share. Shares with a StockRank of less than 10 out of 100 have slumped to a negative 40% loss (see chart). These are shares that are expensive, poor quality and with failing price and earnings momentum.
Typically, the very lowest ranking stocks tend to be small-cap natural resources companies, as well as speculative, unprofitable and often unproven businesses. Even so, they can still be popular among unsuspecting investors. While some will inevitably do well, they have generally been a statistically bad bet in aggregate.
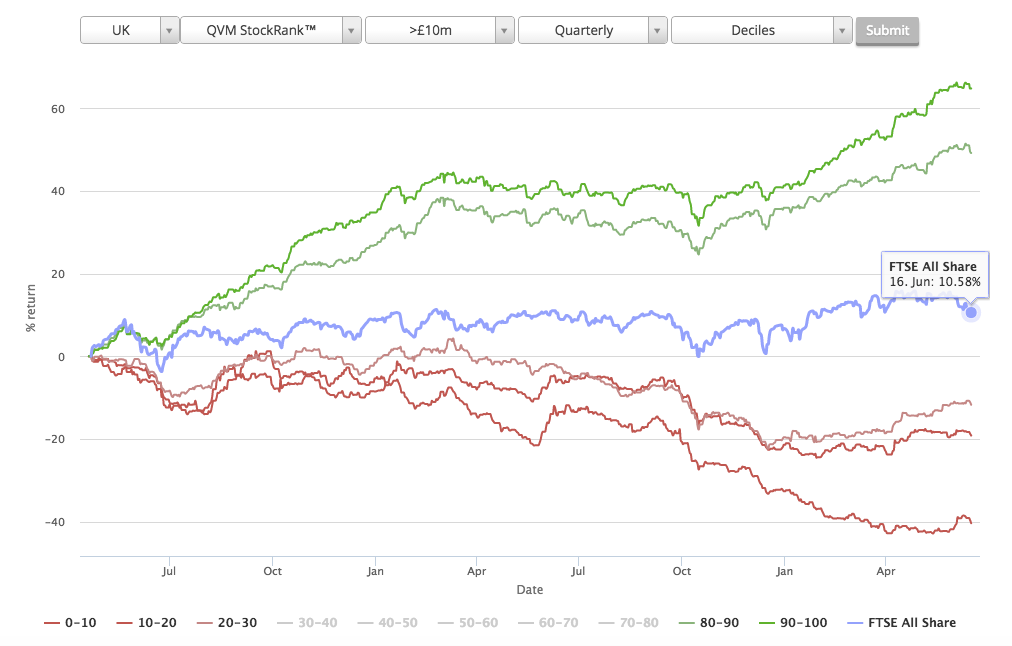
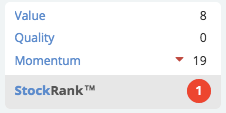
Subscribers can check the StockRank performance using the StockRank portal. Don’t forget, a company’s StockRank can be found at the top of its StockReport - such as this one for Fitbug Holdings.
Low Volatility - does it surf or sink in the stock market?
Low volatility has been a hot topic in investment research since the 2008 stock market crash. But the observation that low volatility shares actually outperform high volatility shares dates back to research by Robert Haugen in the 1960s.
In simple terms, the low volatility ‘anomaly’ is the polar opposite of the traditional investment truism that high risk equals high returns. It turns out that low risk shares (as measured by volatility) have a tendency to outperform their high risk counterparts. And while low volatility shares rise slower in bull markets, they don’t fall as far in bear markets.
Part of the reason for this is believed to be down to the fact that investors are often overconfident in their stock-picking abilities and end up attracted to riskier shares. These shares then become overpriced and underperform, while lower-risk and potentially underpriced shares perform much better.
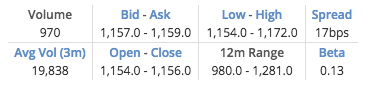
There are several ways of measuring volatility, one of which is something called Beta. Beta is a long term calculation of how much a share price moves in relation to the movement of the market. A Beta of 1 or more suggests that it moves more than the market on up-days and down-days. While a Beta of less than 1 suggests that it is less sensitive to what the market is doing.
Beta isn’t the only measure of volatility but it does offer some insight into stocks that might be sensitive to market price action and could be better placed to withstand a dip. But care, as always is needed. You can find the Beta of any company on its Stock Report page.
Stockopedia Subscribers can click to see some example FTSE 350 Low Volatility and High Volatility screens.
Portfolio housekeeping
Some UK indices have performed well this year but the potential for increasing uncertainty amid the debacle over Greece means a spot of portfolio housekeeping could be in order. Appropriate diversification and the quality, value and momentum strengths of individual shares could be worth reviewing as markets start to get bumpy. If you are interested in portfolio pruning you can always read more Stockopedia Portfolio Management articles here. Next up we’ll take a look at hedging strategies to minimise equity market risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Hi, Really like your thoughts on diversification. Is there any research on optimal holding numbers for various size portfolios? I have 30 holdings in my main portfolio, but am increasing the size of the portfolio every month, so I think that the holdings number should increase as the overall size increases. Does that logic stand up to scrutiny?
Thanks
Paul
Did you see Edward's articles on number of stocks? Here is a link: http://www.stockopedia.com/content/how-many-stocks-should-you-own-in-your-portfolio-86323/
I would say 30 is a good number, 40+ gets a bit difficult to manage and keep track of everything. I would not always increase the number of holdings but maybe average up on the better companies, top up on dips.
Fortunately,my portfolio is well-diversified.The poorest performer in absolute terms is Aegean Airlines.Excellent financials,but based in Greece !
I did do that allocation on my folio. I have 36% in Industrials and market average is only 9%. But then I see the breakdown and find Industrials is wide ranging sector which includes Passenger Transport, Professional & Commercial Services, Construction and Engineering and Industrial, so very diverse sector. I find some listings misleading for instance some housebuilders are in Financial sector and others are in Customer Cyclicals.