Dr Martens share price falls 17% on poor H1 results and uncertain outlook

Analyst’s view:
Although today's announcement doesn't explicitly guide expectations lower, it's clear that meeting consensus expectations will be extremely difficult. I've been taking a more positive view on Dr. Martens this year, as I thought that its earnings forecasts may have stabilised and the modest earnings multiple might offer a reasonable entry point. However, today's results and outlook statement have rocked my confidence in the stability of those earnings forecasts. The downtrend in EPS forecasts appears likely to resume.
Down 17% at 52.8p (£511m) - H1 FY27 Results
Today's interim results and outlook statement from Dr. Martens have proved to be a great disappointment, with the company unable to offer any confidence that this financial year is going to turn out well.
Let's start with the interim results themselves:
Revenue down 9.2% at constant currency (for context, market consensus suggests that revenue for FY March 2027 will increase by 1.7%).
Adjusted PBT is a loss of £13.7m (H1 last year: loss of £9.4m).
Net debt has increased slightly year-on-year to £310.8m.
What went wrong in H1? The explanation is that the performance was "impacted by the hot summer and continued boots decline, particularly in our European markets."
With boots being the flagship product and the foundation of their identity, a continued decline in that product must be seen as worrying.
Also, the company says that B2B was stronger than DTC: given the poor overall result, this suggests that direct-to-consumer sales were really poor. The financial review confirms that DTC sales fell by 12.8% at constant currencies (but are still responsible for the majority of overall sales).
It's important to bear in mind that the peak trading months are still ahead. Last year, only 42% of full-year revenues were generated in H1.
Geographic breakdown: the UK was the standout poor performer, falling 21.3% at constant currencies. This was "below our plans, impacted by the continued challenging market backdrop and a weak performance in both DTC and boots."
But it wasn't just the UK that struggled during H1: all regions declined.
This brings me to an important point: the second derivative of sales. If we break down H1 into Q1 and Q2, we see how much worse Q2 was than Q1:
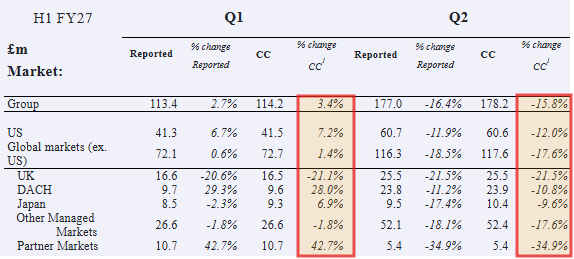
Even regions that had managed to achieve modest growth in Q1 swung to a decline in Q2.
It's fair to accept the explanation that the weather played a role. But even that explanation leaves us with the (best-case) conclusion that the company is extremely sensitive to factors beyond its control.
Gross margin was flat at a very respectable 65.3%.
Analysis of the loss: the company generated an impressive EBITDA figure, but it's flattered by lease accounting. Lease costs are included within depreciation and interest:
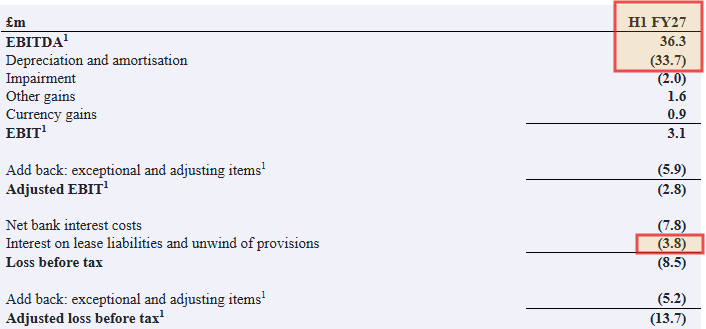
Net debt: the lease liabilities are heavy enough, and they are exacerbated by bank loans of £250m offset by only £91m of cash, for total net debt of £310.8m
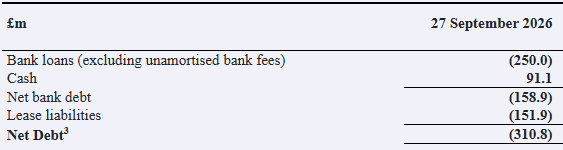
The company says that this is the seasonal high point. Comparing like with like, net debt has increased from £302m in September 2025. It was only £213.5m at March 2026, which would have been a seasonal low point.
The leverage multiple is 2.2x, including lease liabilities. My rule of thumb is to treat anything over 3x as high-risk.
Current trading and outlook: this statement provides no reassurance. Some excerpts:
We continue to navigate a challenging trading environment.... DTC remains challenging, however, with the decline in October continuing to be driven by boots....
We are focused on execution in the weeks ahead with strengthened trading plans. November, December and early January, particularly the key trading events of Black Friday weekend, the run up to Christmas and the post-Christmas sale period, are crucial for the full year outturn. At this point, therefore, there is a wide range of outcomes in both revenue and PBT terms for the year as a whole.
Consensus revenue is £777m, with adjusted PBT of £65.7m.
Graham's view
Last year, the company generated an adjusted PBT of minus £9.4m in H1, but then a positive full-year adjusted PBT of £55m. So the H2 result was plus £64.4m.
The problem, however, is that even if the company matched that result in H2 of this year, it would still fall far short of current market expectations. And it has failed to even match last year's H1 performance.
Although today's announcement doesn't explicitly guide expectations lower, it's clear that meeting consensus expectations will be extremely difficult.
Wise investors often avoid fashion stocks on the basis that they can't predict what styles will be in fashion or out of fashion.
I don't entirely agree with that - I think some brands are evergreen. And I've been taking a more positive view on Dr. Martens this year, as I thought that its earnings forecasts may have stabilised and the modest earnings multiple might offer a reasonable entry point. The share price had already fallen by 80% from its IPO valuation. See my comments in July.
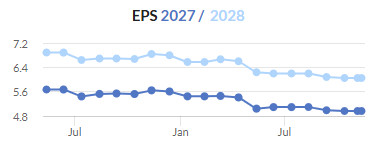
However, today's results and outlook statement have rocked my confidence in the stability of those earnings forecasts. It now looks extremely difficult for the company to meet them. The downtrend in EPS forecasts appears likely to resume:
I'm therefore going to remove my short-lived, moderately positive view on this stock. I will simply revert to neutral, hoping that its offering clicks with the target audience during the all-important peak trading periods.
Also, the fact that the company is carrying so much bank debt doesn't give it much wiggle room, and means that we need to be ready to take a negative view here much faster than we would if it was sitting on net cash.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Dr. Martens (10)
Comments here are also visible in the Daily Stock Market Report
Dr. Martens (LON:DOCS)
sensible comments Metalmaid
everyone seems to be knocking what the company does - but for a "one trick pony company" they are expecting £800 mill of sales and £60 net profit next year - is that not overall actually a pretty decent company.
i would kinda get that there are two things
1 the size of their TAM - if they kinda have the same target audience they always had should we expect any growth
2 whether you are in fashion or out fashion - time passing will likely change whether you are in or out.
Ok they were obviously doing uber well just the remnants of covid time - i think they are not the only uk fashion brand thats isnt perhaps quite as desired as it temporarily was.
Obviously some brands wil branch out and continue to grow to infinity and beyond - thats not a given though.
In summary is that not just fashion - in the good peak times everyone wants your brand and will pay top dollar - however when they move onto next fad p what do you do if sales ebb downward do you try and cut prices to genrfate sales - its a tricky balance.
clealy this isnt a bad company - but not sure why investors would presume they could easily double their TAM ?
shareprice kinda looks about right to me - how confident are ibvestors though that the currentlyu penciled ion numbers for 2028 arent justa work of fiction - would holders have 80% plus confidence that it ont be easy peasy up profits 20% plus in 2028 on top of 2027 - they seem glass rammed full expectations. I gues when your job is fashion sales - if you aint gonna be uber confident what you are gonna sell next year is great - well yuuou probbaly wouldnt be ain a job - and perhaps thats the worry ?
Yep you make some good points. I agree with the fads involved in the fashion sector, and brands will come in and out of fashion. I just think this is too competitive a sector for them to grow meaningfully and hold that growth when imo their product has a fairly niche appeal - they have joined the flavour of the month fashion sector that is highly unpredictable.
I think if they concentrated back on the quality and the workers market, stuck with higher quality British made products and centre their marketing around that, then there is a huge workers market to go after (globally) and have a decent share of. This market would also be far more stable imo. I know they do market for this to some extent, but the product seems to have moved too far into a fashion product and the quality has sunk. So I personally feel they are not maximising the brands potential, just my opinion.
Dr. Martens (LON:DOCS) Profit warning.
I’ve been in 3 shopping centres in Australia (Sydney & Melbourne) over the last year and made a point of checking out the Doc Martin stores. I have not seen a single customer in any of them, whilst the neighbouring sports shoe stores are busy. (Admittedly a non-scientific survey and not Europe).
Given they are prime locations it must be costing a fortune to keep them open. I can’t see a turnaround until the brand becomes fashionable again.
They're so expensive as well! I wanted some recently and couldn't believe how much for a pair (£170+). Have spoken to other middle-aged parents and they were also put off by the price.
DOCS boots used to have broad appeal (5 yrs ago). Its private equity backers cleverly floated at peak popularity. They are no longer fashionable outside a loyal hardcore. Perhaps they might become fashionable again in 20 years.
I have had my pair for over 30 years and they are still going strong, apart from being re-soled they are great. Maybe this is the problem.....they are too well made.
I think Docs use to be a very well made workman's boot. They cost more than a standard boot, but lasted a lot lot longer and were of a much higher quality.
Then in the early 2000s Docs moved manufacturing to Asia and the customer profile has changed dramatically. They are now no longer a high quality boot. By most accounts they fall apart within a couple of years of standard wear.
So the buyer profile has also changed. Now they are just a cheaply made fashion item - one that is fairly niche in style and doesn't appeal to the masses.
Fashion wise, they use to have a cult following with the anti authority types, like the mods and rockers types etc. These days they still have a certain amount of that appeal, they are for instance popular with goth type fashion. But overall it is just a cheap fashion product.
The days of them producing a quality workmen boot are gone and I am not surprised to see it has hurt the company considerably. I actually think they should revert back to British made, charge more money, and focus on delivering the best quality boot they can. I don't think the space they are in will ever be easy, too much competition. Reverting back to quality and maximising their brand name and history imo is the only way this will return to being a great company again.
Dr. Martens (LON:DOCS)
sensible comments Metalmaid
everyone seems to be knocking what the company does - but for a "one trick pony company" they are expecting £800 mill of sales and £60 net profit next year - is that not overall actually a pretty decent company.
i would kinda get that there are two things
1 the size of their TAM - if they kinda have the same target audience they always had should we expect any growth
2 whether you are in fashion or out fashion - time passing will likely change whether you are in or out.
Ok they were obviously doing uber well just the remnants of covid time - i think they are not the only uk fashion brand thats isnt perhaps quite as desired as it temporarily was.
Obviously some brands wil branch out and continue to grow to infinity and beyond - thats not a given though.
In summary is that not just fashion - in the good peak times everyone wants your brand and will pay top dollar - however when they move onto next fad p what do you do if sales ebb downward do you try and cut prices to genrfate sales - its a tricky balance.
clealy this isnt a bad company - but not sure why investors would presume they could easily double their TAM ?
shareprice kinda looks about right to me - how confident are ibvestors though that the currentlyu penciled ion numbers for 2028 arent justa work of fiction - would holders have 80% plus confidence that it ont be easy peasy up profits 20% plus in 2028 on top of 2027 - they seem glass rammed full expectations. I gues when your job is fashion sales - if you aint gonna be uber confident what you are gonna sell next year is great - well yuuou probbaly wouldnt be ain a job - and perhaps thats the worry ?
Yep you make some good points. I agree with the fads involved in the fashion sector, and brands will come in and out of fashion. I just think this is too competitive a sector for them to grow meaningfully and hold that growth when imo their product has a fairly niche appeal - they have joined the flavour of the month fashion sector that is highly unpredictable.
I think if they concentrated back on the quality and the workers market, stuck with higher quality British made products and centre their marketing around that, then there is a huge workers market to go after (globally) and have a decent share of. This market would also be far more stable imo. I know they do market for this to some extent, but the product seems to have moved too far into a fashion product and the quality has sunk. So I personally feel they are not maximising the brands potential, just my opinion.
What is surprising is how today's downbeat tone compares to its upbeat note few months ago. Stocko has been fooled by it giving it a super stock rank. Hopeless. I am going to sell my holding which i bought since Ed's talk about jump in ranks.
Don’t think accurate to say the ranks were fooled as they can only go off the information available.
Dr. Martens (LON:DOCS) were over-taken by solovair boots a long time ago
they also outsourced their factories/production to china and south-east asia ~20 years ago. so you are paying more and more, for worse and worse quality
simply put, they are still living on a rep from the 80s and 90s that doesn't exist anymore
as a final note: they are one of the worst IPO's i have ever seen tbh, and that's not an exaggeration