Dr Martens: StockRank Jump points to growing momentum

This week I’m continuing our review of companies that were flagged up in Ed’s recent StockRank Jumps research (if you haven’t seen this yet, you can check our Ed’s article here - don’t forget to sign up for this week’s webinar).
The company I’m covering today will be a familiar brand to many. Footwear brand Dr Martens (LON:DOCS) has achieved the relatively rare feat of building a fanbase across multiple generations.
Although the company’s 2021 IPO bombed badly, the investment case (and valuation) today looks far more tempting to me. The company has also recently become a textbook example of a StockRank Jumper:
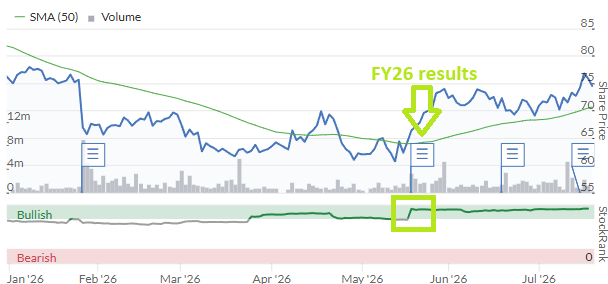
Reassuringly, this upgrade and subsequent momentum was grounded in the group’s financial results, suggesting it could have solid foundations.
Share price at the time of publication: 74p
Market cap: £718m
Disclosure: at the time of publication, Roland has no position in DOCS.
The Pitch
Dr Martens was founded in 1960 when UK shoemaker Griggs purchased the rights to manufacture shoes based on the iconic air-cushioned sole. This had been invented by German solider Dr Klaus Maertens in 1945, to aid his recovery from a skiing accident.
What started out as a £2 work boot quickly gained counter-culture appeal, and the brand’s popularity grew steadily.
The company now claims to be one of the “most recognised footwear brands in the world”. While this may be open to debate, Dr Martens sold £765m of footwear last year, including £378m in the EMEA region and £278m in the Americas. I think it’s fair to suggest this is a brand with scale and depth.
Source: Dr Martens FY26 presentation
After a difficult post-pandemic period – made worse by the supply chain crisis and a mismanaged expansion drive in the US – the fundamentals now seem to be improving. Our DSMR commentary has highlighted the following progression in recent months, adding context to the StockRank Jump:
19 May 26 (FY26 results): Graham upgrades our view to neutral, citing “signs of a real recovery” in results which show a 60% rise in adjusted pre-tax profit. He noted that gross margins rose by 1.2% to 66.2% last year – high gross margins are a classic hallmark of strong consumer brands. The StockRanks Contrarian view “makes sense”.
15 July 26 (AGM Trading Update): management confirms that trading so far during FY27 has been in line with expectations and leaves guidance unchanged. Graham highlights that DOCS now enjoys Super Stock styling and upgrades our view to AMBER/GREEN, noting improved momentum and durable brand quality.
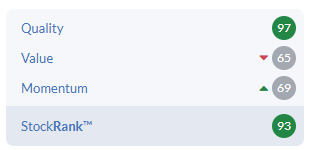
Dr Martens’ Super Stock styling is unchanged at the time of writing, while its StockRank has continued to edge higher:
The Big Picture
Taking a broader view on this business highlights a number of factors that could support continued growth and a valuation re-rating:
Strong operational execution: since CEO Ije Nwokorie took charge in early 2025, the company’s operational execution and financial performance has improved steadily. Nwokorie has resolved the group’s supply chain and inventory issues, rebalanced US sales from wholesale towards direct-to-consumer channels, cut costs and improved margins.
Return to growth: sales are expected to return to growth this year, aided by new products, geographic expansion and stronger full-price sales. The group is also refining its store strategy as part of its focus on building stronger consumer engagement.
Brand strength: Dr Martens remains a remarkably strong brand with UK consumers, at least. According to YouGov, it’s currently the 10th most popular fashion and clothing brand among UK adults. This improves to #2 among GenX (b.1965-1980) shoppers, ahead of stalwarts including Levi Strauss & Co (NYQ:LEVI) and The North Face (owned by VF (NYQ:VFC)).
Going Deeper
Looking more closely at the financials and ownership structure of the group suggests some other reasons for optimism:
Balance sheet: the group’s net debt/EBITDA leverage ratio dropped below 2x last year, reducing the risk of any financial discomfort. Reassuringly, this was achieved primarily through a reduction in net debt, rather than solely through an increase in profit. In my view this is a good indicator of genuine cash generation.
Ownership: Dr Martens was floated by its former private equity owner Permira in 2021. The IPO bombed and Permira still owned c.38% of DOCS in 2024, when the PE company’s remaining position was moved into a new five-year continuation fund with fresh investors. I think this is probably good news. My guess is that the new fund will remain a supportive partner for the business for the next few years, with the aim of being able to sell for a decent profit in c.2028-29.
Valuation: at current levels the shares trade on just 12x FY28 forecast earnings. That looks a little low to me for a mid-market fashion brand. Looking ahead to FY29, forecasts I can see suggest earnings could rise to c.7.2p per share. Applying a P/E of 14 to this estimate would give a share price of 100p. That doesn’t seem too demanding.
What The Brokers Say
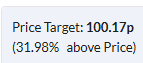
Brokers covering the stock appear to have reached a similar conclusion. The average price target for Dr Martens is currently just over 100p:
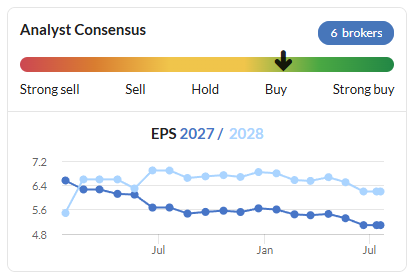
I think there’s scope for upgrades to this target if the business can return to sustainable growth. The risk is that this isn’t yet certain. Analysts’ earnings forecasts have trended somewhat lower over the last 12 months:
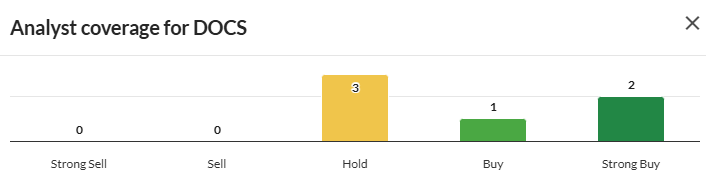
The spread of ratings across individual analysts also suggests mixed views:
The Bear Case
As with any turnaround situation, there are some risks:
No return to past glories? Operating margins topped 25% during the lockdown shopping boom of 2021/22. I am not convinced Dr Martens will be able to return to that kind of profitability anytime soon.
Lack of earnings upgrades: the weak EPS forecast trend I highlighted above is a concern. Our research has repeatedly found that earnings upgrades are one of the most reliable drivers of share price gains and valuation re-ratings.
Consumer spending is under pressure in the UK and many other global markets, as inflation continues to bite. Dr Martens’ mainstream appeal means that some of its customers may be cutting back on discretionary spending.
Will millennials embrace the brand? Earlier, I highlighted the apparent strong appeal of Dr Martens to GenX shoppers. What I didn’t say was that the same YouGov survey of popular fashion brands placed Dr Martens in 32nd place among UK millennials (b.1981-1996). For some contrast, Levi’s was listed as a top three brand for all age cohorts. If Dr Martens’ low profile with millennials is reflected in other international markets, then the business may have some work to do to raise its profile among this important cohort of buyers. Failure could mean sales growth tails off again in a few years’ time.
The Bottom Line
Dr Martens is a well-known fashion footwear brand with mid-market appeal and a record of engaging successfully with successive generations of younger buyers.
Whether that can continue as prices creep higher and fashions evolve remains to be seen, but the company’s strengthened focus on its direct-to-consumer business appears to be protecting margins and maintaining the brand’s value.
In my view, CEO Ije Nwokorie has made good progress since taking charge 18 months ago. I imagine he has the support of the group’s private equity shareholders and will be keen to restore some of the shareholder value lost since the 2021 IPO.
With Super Stock styling, a high StockRank and a recent Jump, I think Dr Martens stock could be offering an attractive entry point for investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Advice from a wise man - "Never invest in fashion."
I think Dr Martens (LON:DOCS) looks interesting. But note that, based on the precedent of recent years, there is probably now no trading update/results due until November which is a long time to wait. So I think there's a risk of share price drift before then which might present a better buying opportunity.
Excellent analysis Mr Head. I'm almost tempted to go try a pair!
my attention to Dr Martens was primarily encouraged by my god daughter who liked the movie Wednesday several months ago. I remember them in my younger days in the 80s and they are clearly a time served brand. I should have invested then.