Duke Capital: shares fall nearly 20% on bulletin board chatter, while cash revenue holds at £7.0m

Analyst’s view:
Duke tends to invest in businesses that are not of the highest-quality, but I've been impressed by its ability (so far) to dodge any serious losses. It has done this by successfully exiting some troubled investments. It also frequently ploughs money into its existing portfolio. On balance, I'm going to leave us on neutral here. I don't see the need to take a negative stance when the share price has already taken such a heavy hit.
Up 4.5% at 22.48p (£115m) - Response re. Share Price: Operational Update
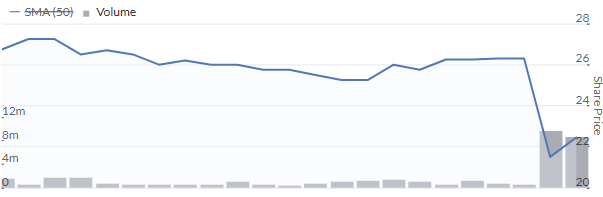
The DUKE share price has seen some drama this week, on above-average volume. It fell nearly 20% yesterday, on no official news:
This is how Duke responds:
Total cash revenue for the quarter ending September 30th was £7.0m, in line with the previous quarter
H1 dividends were covered by free cashflow
This bit seems more substantive:
The portfolio reorganisations referred to in FY26 accounts have made substantial progress, with materially loss-making divisions in two Duke investments now exited. As the UK market continues to be challenging, we do expect lower recurring revenue to be generated within our UK portfolio in H2 with the key focus of the investment team currently being on improving the performance of the UK portfolio into next year.
There are also two capital partners (a fancy word for borrowers) who are "in late-stage processes for exits which, if concluded, could have a material positive impact on market expectations for FY27 total cash revenue."
Finally: "The Directors believe that the current share price sits at a material discount to the current NAV."
Graham's view
The only explanation for the fall that I can find is on the well-known bulletin board ADVFN. A poster there yesterday morning said that they had sold their shares, and they highlighted losses at inTEC, an IT managed services company based in Manchester.
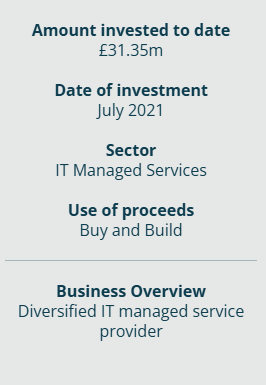
inTEC is still listed as a "current" investment on Duke's website, with £31m+ invested.
The latest accounts for inTEC Business Holdings were published about a week ago. They do not include a going concern warning from the auditors. They do show the company making an operating loss in 2025 of £7.8m, on revenues of £21.7m. They were loss-making the prior year, too.
The loss in 2025 included less than £2m of goodwill amortisation, so this is not a situation where the company was loss-making but cash flow was strong - operating cash flow was in fact negative.
Also, the balance sheet was deeply in the red with negative tangible equity of £38m. The main item here is Duke's loan which is shown with a value of £31.5m, charging an interest rate of 13.5%. Duke is also the "ultimate controlling party" - I think it owns 100% of inTEC.
As this is a "buy-and-build" situation, it's not so unusual to see highly negative balance sheet equity (due to high levels of goodwill).
However, it's always important to check that acquisitions are followed by profitability before too long, particularly where there is leverage involved.
We can only hope that inTec has had a much better 2026, and/or that it has been successfully reorganised (it has sold some of its subsidiaries in 2026), and/or that Duke is exiting it completely, without making a loss.
Last year, Mark did some digging into another Duke investment, and concluded by taking our stance on the company down by one notch to neutral.
I have some history here, as a former shareholder. I've not been tempted back in. I've accepted that Duke tends to invest in businesses that are not of the highest-quality, but I've been impressed by its ability (so far) to dodge any serious losses.
It has done this by successfully exiting some troubled investments. It also frequently ploughs money into its existing portfolio.
Duke's total investment portfolio at the end of FY March 2026 had an accounting value of £263m. After taking Duke's own leverage into account, net assets were £175m.
So if Duke's £32m position inTEC was worthless, it would cut Duke's net assets by 18%, to £143m.
The Duke market cap is at a c. 20% discount even to that low figure.
I'm going to leave us on neutral here. I don't see the need to take a negative stance when the share price has already taken such a heavy hit.
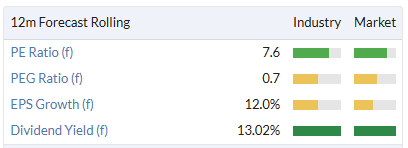
The share price is saying to us that there are likely to be multiple problem parts to the Duke portfolio. It might well be right about that. I'm still not tempted to buy back in here, even at a 13% yield.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Duke Capital (6)
Comments here are also visible in the Daily Stock Market Report
A question for anyone re Duke Capital (LON:DUKE) :
I owned this as a basket buy during the covid panic (i.e., a 'dumb' buy of a bit of many washed out micro caps). But it got cleared out after not long as I concentrated the basket as felt it both a bit meh and was never motivated to do more detailed work.
They are moaning about share price being unfair today. Not a good look IMO.
At a quick glance I feel concerned by the extent to which they have grown debt inline to ahead of direct operating cash flow AND (!!!) significantly increased the share count since FY21. This makes it look like a mildly distressed business that needs to recapitalise (and/or returns are leaking away somewhere from the shareholders).
Additionally the high but flat for years dividend is weird.
Views? Counterpoints?
Re Duke Capital (LON:DUKE) , it was commented on in the daily report of 19/06/26. Two of there investments look to be/gone bad. Today, in the RNS, they say that re the 2 investments, they have now "exited"
Big question is, how much (if any) £££ has been written-off on a £110m MC company regarding these 2 investments ?. And how risky are the rest of the investments ?
IMO REITS are great for their big dividends but not if the SP slides by more than the divis. EG, Ive held Primary Health Properties (LON:PHP) for just over 3 years and taken very nice dividends along the way. But even including dividends, my PHP overall value is slightly down over that time. Over that same 3 years, FTSE 100 is up c40%. GL if you continue to hold
Correction: DUKE is NOT a REIT, It comes under Investment Banking & Investment Services. My point re big divi payers still applies
It is very difficult to understand and has never delivered for shareholders. I still hold a little for the div. Journalists have repeadedly said it's model is successful in other countries!
I've spoken with the CEO and EDR a couple of times at these Investor meet company events. Seems to me that they keep issuing purely to make the company bigger not because of distress. However the issuance was too scary for me as like you I also jump in around covid and was then pleased to get out without losing money (or too much). Also have a stake in Twenty Four Income fund whose divi a year ago looked too good to be true but in actual terms it doesnt seem to be delivering does anyone have a view on this company.
Duke Royalty / Capital that was!