Daily Stock Market Report (Wed 21st Oct 2026) - HDD, HFD, SRB, DUKE

The largest merger of all time is currently being considered by special committees at two companies: Space Exploration Technologies (NSQ:SPCX) and Tesla (NSQ:TSLA).
The SpaceX share price is up 8% in after-hours trading to nearly $160, well above its IPO price of $135, after Elon Musk’s comments yesterday in favour of a merger between the two companies.
By market cap, SpaceX is the larger of the two, and the terms of any possible merger have not yet been determined or agreed.
Bloomberg suggests today that the rationale for a merger "lies in their shared ambitions to leverage artificial intelligence for data centers in space, driverless cars and humanoid robots.”
Overnight market movements:
The FTSE is up 0.1% at 10,740
S&P 500 is up 0.2% at 7,730
Brent crude (December) is up 1.5% at $110.40/bbl
Gold is down 0.2% at $4,120oz
Bitcoin is down 0.1% at $82,600
Ed Sheldon jons me today.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£75.6bn | SR79) | US Food and Drug Administration has approved Hibsago (bepirovirsen) for the treatment of chronic hepatitis B virus infection. GSK continues to advance regulatory submissions for bepirovirsen across multiple geographies with regulatory decisions anticipated in the coming months. | ||
Fresnillo (LON:FRES) (£19.8bn | SR50) | “Production of gold and silver was in line with expectations in the third quarter and we remain on track to meet our full- year guidance.” Expressed in silver equivalent ounces, total production is expected to be 82 -91 million ounces. | ||
SEGRO (LON:SGRO) (£12.2bn | SR67) | Year-to-date average 43 per cent uplift on UK rent reviews, renewals and regears. Occupancy increased 20bps to 94.7 per cent since HY 2026. LTV of 33%. | TAKEOVER is expected to conclude in H1 2027. | |
Aberdeen (LON:ABDN) (£4.3bn | SR84) | Q3 net flows: ii £9.3bn, Adviser minus £2bn, Investments minus £10.4bn. Total net outflow minus £3.3bn. AUMA £579bn. “We remain confident in delivering our FY 2026 Group targets of adjusted operating profit of at least £300m and net capital generation of c.£300m.” | ||
Hochschild Mining (LON:HOC) (£2.6bn | SR47) | “We have delivered a strong operational performance during Q3 and remain on track to meet our full-year production and cost forecasts.” | ||
Quilter (LON:QLT) (£2.4bn | SR88) | Assets under Management and Administration increased to £160.5 billion, up 19% year-on-year. Q3 core net inflows £2.9bn. | ||
HUTCHMED (China) (LON:HCM) (£1.9bn | SR28) | The agreement between HUTCHMED Limited and a subsidiary of GSK has closed. The agreement grants the GSK subsidiary worldwide rights excluding Mainland China, Hong Kong, Macau and Taiwan to develop and commercialize HMPL-A830. | ||
Savills (LON:SVS) (£1.8bn | SR84) | Refinancing of bridge facility for Eastdil Secured acquisition completed | Has agreed to issue US$350 million of new unsecured fixed rate US private placement notes. Will repay the remaining US$350m drawn under the US$800m bridge facility entered into in March 2026 to fund the acquisition of Eastdil Secured. | |
Sigmaroc (LON:SRC) (£1.4bn | SR87) | 9-month period. Revenue +2.5%. Underlying EBITDA +7.5% (£207m). The Board remains confident in full year expectations. | ||
Great Portland Estates (LON:GPE) (£1.3bn | SR38) | GPE has committed to the redevelopment of its Soho Square Estate, W1, which is set to deliver a best-in-class HQ building. 90,000 sq ft development will include 75,000 sq ft of Grade A offices and 15,000 sq ft of prime retail space fronting Oxford Street. | ||
Domino's Pizza (LON:DOM) (£912m | SR95) | Total system sales +3.5%. Like-for-like growth 2.3%. The Board remains confident of achieving our earnings expectations for the full year, in line with market expectations. | ||
Halfords (LON:HFD) (£609m | SR99) | H1 like-for-like sales +7.1%, “supporting the FY27 profit upgrade communicated in our trading update on 27 August 2026.” Continues to expect FY27 underlying profit before tax of between £55m and £65m. | AMBER/GREEN↓ (Ed S) | |
Metals Exploration (LON:MTL) (£504m | SR76) | Following the incident on 19 October 2026, construction activities at its La India project in Nicaragua resumed on 21 October 2026. The Company is not aware of any material impact on the La India project associated with the incident. | Following the incident on 19 October 2026, construction activities at its La India project in Nicaragua resumed on 21 October 2026. The Company is not aware of any material impact on the La India project associated with the incident. | |
ME International (LON:MEGP) (£447m | SR57) | CFO has taken a temporary medical leave of absence from the business. Group Deputy FD is interim CFO. | ||
Ashtead Technology Holdings (LON:AT.). (£429m | SR42) | Recommended cash offer of 615p per share. 80.9% premium to price on 22nd Sep (last day prior to Offer Period). | TAKEOVER | |
MS International (LON:MSI) (£238m | SR55) | MSI-Defence Systems Ltd has been awarded a contract to supply twelve MSI-DS DS30M naval gun systems for the German Navy's F128 frigate programme. The contract has a total value of £29.7m. | ||
Guardian Metal Resources (LON:GMET) (£190m | SR10) | Has appointed Mr. David Hendriks as Chief Operating Officer and Mr. Ron Espell as Vice-President, Environment & Permitting to support project development. | ||
Liontrust Asset Management (LON:LIO) (£186m | SR97) | Assets under management and advice were £24.1bn as at 30 September 2026. Net outflows of £459m in the period. The proposed acquisition of the fund management and model portfolio services business of Hawksmoor Fund Management and Hawksmoor Investment Services will add approximately £1.9bn of AuMA. | ||
Serabi Gold (LON:SRB) (£172m | SR82) | Quarterly gold production of 11,008 ounces, a 9% decrease from Q3 2025. Cash as at 30 September 2026 of $63.2m. Due to permitting delays, FY2026 gold production is now expected to be at similar levels to FY2025, compared with previous guidance of over 53,000 ounces. | PROFIT WARNING (AMBER ↓) (Graham) | |
Andrada Mining (LON:ATM) (£150m | SR37) | Revenue increased 80% to £20.6m, with contained tin production increasing by 13% to 576 tonnes. Profit after tax of £2.5m compared with a £3.0m loss, and EBITDA increased to £4.5m. Cash balance increased to £15.6m. Fully funded ore-sorting expansion project on track, targeting a substantial increase in tin production. | ||
Duke Capital (LON:DUKE) (£110m | SR78) | Total cash revenue for the quarter ending September 30th was £7.0m, in line with the previous quarter. H1 interim dividends totalling 1.4p were covered by free cashflow. The Directors believe that the current share price sits at a material discount to the current NAV. The company expects lower recurring revenue to be generated within the UK portfolio in H2. | AMBER= (Graham) | |
SDI (LON:SDI) (£102m | SR80) | Non-Executive Chairman, Ken Ford, will be stepping down. Ben Stocks will be appointed independent Non-Executive Chairman designate. Ben was previously Non-Executive Chairman of Xaar plc, and prior to this was CEO of Porvair plc. | ||
Hardide (LON:HDD) (£82m | SR50) | Revenues for the year more than doubled to £13.5m. EBITDA is expected to be £5.8m (FY25: £1.0m) and profit before tax £4.9m (FY25: £0.2m), both ahead of market expectations. Trading momentum continues to be strong, underpinning market expectations and positioning Hardide for further significant growth in FY27. | GREEN = (Ed S - I hold) | |
MTI Wireless Edge (LON:MWE) (£54m | SR87) | MTI Wireless Edge is acquiring Interspec, a Mottech Water Solutions Ltd distributor headquartered in Texas, for a maximum consideration of up to approx. $2.6m. For the 12 months to 31 December 2025, Interspec generated revenue of approx. $2.9m and PBT of approx. US$0.4m. | ||
Gelion (LON:GELN) (£37m | SR4) | Total income of £2.5m (FY25: £2.7m), 17.1% better than analyst consensus. Adjusted EBITDA loss of £4.4m (FY25: £4.1m). Strong balance sheet with pro forma cash and cash equivalents of £9.6m. The company enters the coming year with strong technical momentum. | ||
Cobra Resources (LON:COBR) (£35m | SR6) | 32m at 0.7% copper from 52m in strong porphyry-style alteration and 42m at 0.56% copper from 22m in a newly discovered mineralised skarn. The company believes its recent discoveries materially upgrade the copper and gold mineral potential of the Manna Hill Project area. | ||
Hercules (LON:HERC) (£27m | SR40) | Expects to deliver a financial performance ahead of current market expectations on revenue, underlying EBITDA and statutory PBT. Group revenue is expected to exceed £130m, representing growth of approx 7.3% compared, and ahead of market expectations of £127m. | ||
Vianet (LON:VNET) (£19m | SR84) | Group revenue increased 2.6% to £7.86m, adjusted operating profit up 14% to £1.80m, net cash was £0.75m. Proposed interim dividend doubled to 0.8p per share. The Board continues to anticipate full year results in line with its expectations. |
Edward's Section
Hardide (LON:HDD)
Up 7% at 111p (£82m) - Year End Trading Update - Ed S - GREEN =
[At the time of writing, Ed S had a long position in HDD]
Hardide, a provider of advanced surface coating technology, has provided a trading update for its financial year ended 30 September 2026 (FY26).
Highlights:
Revenues for the year more than doubled to £13.5m (FY25: £6.0m).
EBITDA is expected to be £5.8m (FY25: £1.0m) and profit before tax £4.9m (FY25: £0.2m), both ahead of market expectations*, as a result of improved cost management and continuous improvement initiatives.
Final quarter revenues were £4.6m, generating EBITDA of approximately £1.9m.
Gross cash at 30 September 2026 was £3.2m (after making a £1.5m investment in working capital).
Operational news:
Trading momentum continues to be strong.
The company successfully delivered the first shipments of coatings for a new generation of parts for its major North American customer, leading to a further US$1.9m sales order covering the period to November 2026, as announced on 14 September 2026.
The group has recently won further production work in the aerospace sector, together with new customer wins in the energy and industrials sectors, all of which will contribute to revenues in FY27.
Testing continues across a number of applications with a potential major energy sector customer in the Middle East, as well as customers in the semiconductor sector, with results to date proving encouraging.
A deposit of £0.7m has been paid for coating reactors with a total expected cost of £3.5m which, as previously announced, is expected to double Hardide’s operational capacity to approximately £40m of annual sales. The new capacity is scheduled to come on stream during the second half of FY27.
Outlook:
The combination of strong current trading momentum and encouraging recent order intake underpins market expectations and positions Hardide for further significant growth in FY27, consistent with the company’s strategic objective of more than doubling revenues again over the next two to three years.
* Hardide provides current FY26 market expectations of: revenue of £13.5m, EBITDA of £5.5m, and PBT of £4.6m and FY27 market expectations of: revenue of £18.8m, EBITDA of £8.0m, and PBT of £6.6m.
Ed S’s view:
I initiated a very small position in Hardide back in mid-September at 91.7p, despite the fact that the stock was already up 400% year to date at the time (it started 2026 at 18.5p). I was attracted to the prolific revenue growth, surge in profitability, talk of expansion into other industries, and reasonable valuation.
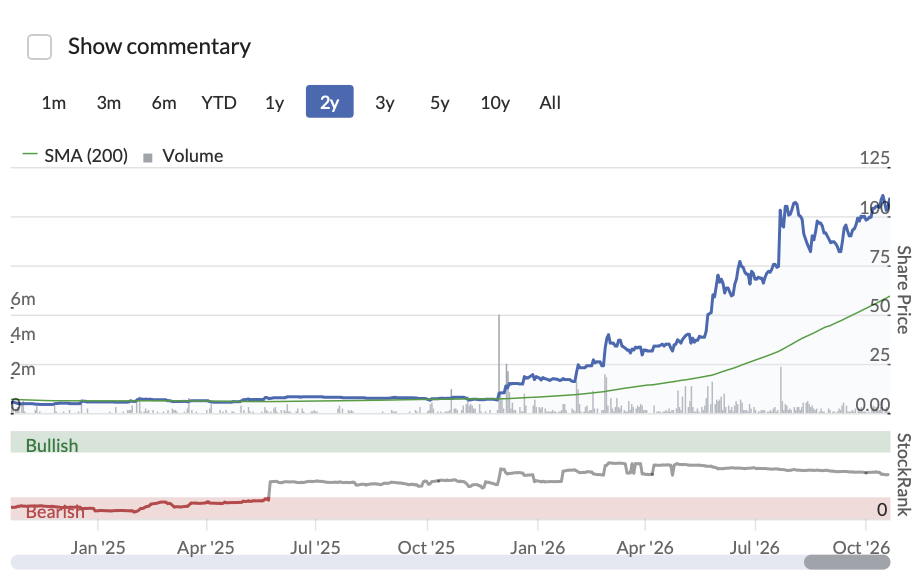
Today’s trading update vindicates my investment decision. This is a company with significant momentum at present.
For the year ended 30 September, revenue more than doubled to £13.5m. Meanwhile, EBITDA and profit before tax are expected to be £5.8m (FY25: £1.0m) and £4.9m (FY25: £0.2m) respectively, both ahead of market expectations, thanks to improved cost management and continuous improvement initiatives.
Looking ahead, the company plans to more than double revenues again over the next two to three years. It’s worth noting here that revenue in Q4 was £4.6m (34% of full-year revenue).
One thing I was concerned about when I invested here was customer concentration risk – a lot of the top-line growth over the last year has come from a North American customer in the energy space. So it's encouraging to hear that the group has recently won further production work in the aerospace sector, along with work in the energy and industrials sectors.
The company also notes that testing continues with a potential major energy sector customer in the Middle East as well as customers in the semiconductor sector. So, it’s definitely trying to diversify its customer base.
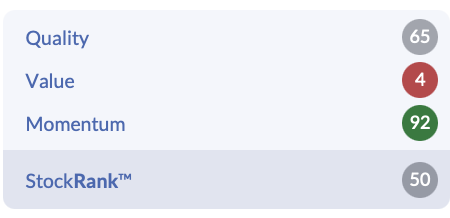
Now, the Stockopedia StockRank system doesn’t like Hardide so much – its score is only 50. But I think that will change.
In the past, revenues have been up and down and the company has consistently lost money. This has most likely weighed on its Quality score.
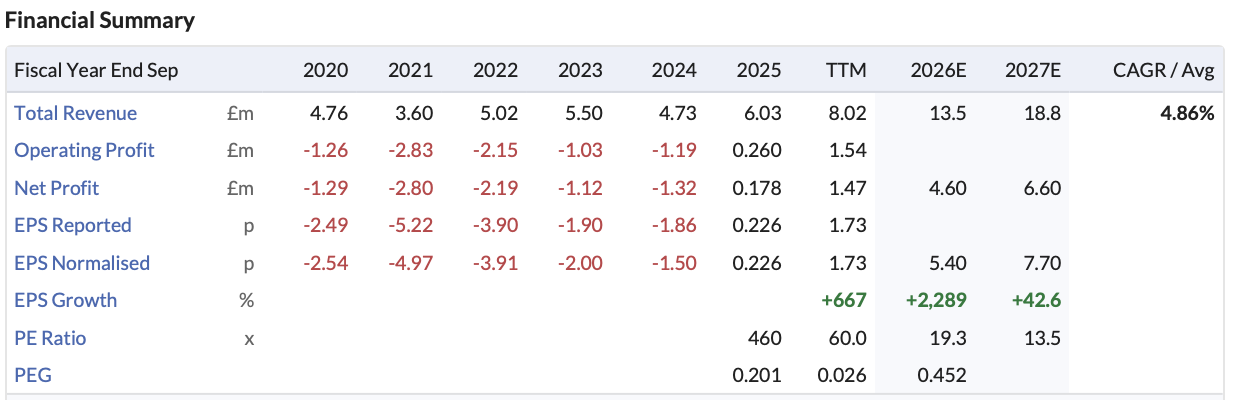
As for the Value score of 4, this is most likely down to the fact that earnings per share in FY25 were just 0.2p. With earnings of 7.7p forecast for the current financial year, the valuation is starting to look a lot more attractive (forward-looking P/E ratio of around 14) so we should see the Value score rise.
The Momentum score is already high at 92. You’d expect that after a 500% year-to-date gain.
Overall, I remain quite bullish on Hardide, despite its big move higher in 2026. After today’s update, I’m happy to keep the stock on a GREEN rating.
Halfords (LON:HFD)
Down 7% at 256p (£609m) - Trading update for the 26 weeks to 2 October 2026 - Ed S - AMBER/GREEN ↓
Halfords has provided us with a short trading update for the 26 weeks to 2 October 2026 (H1 FY27):
Highlights:
Strong trading in H1 supports previously upgraded FY27 guidance.
Group like-for-like sales grew 7.1%, supporting the FY27 profit upgrade communicated in the trading update on 27 August 2026.
Retail LfL sales grew 7.7%, with Motoring LfL sales up 7.3% and Cycling LfL sales up 8.3%.
Autocentres (ex-Avayler) LfL sales grew 6.1%.
“The business continued to perform positively through the first half as we benefited from good execution against our strategic priorities and strong sales of seasonal categories through the warm summer weather. We move into the second half with confidence and look forward to sharing more detail on our progress at our interim results announcement later next month.”
Outlook:
Continues to expect FY27 underlying profit before tax of between £55m and £65m. The strong H1 performance combined with accelerated investments in marketing and technology in H2 will result in underlying profit before tax being weighted towards H1.
Ed S’s view:
When Graham covered Halfords on 27 August, he gave the stock a GREEN rating. However, he said at the time that if the retailer doesn’t pull another rabbit out of the hat in the next six months with another upgrade, he’d be inclined to take the rating back to AMBER/GREEN.
Looking at today’s update, I think now is the time to take it back to AMBER/GREEN. There are a few reasons why.
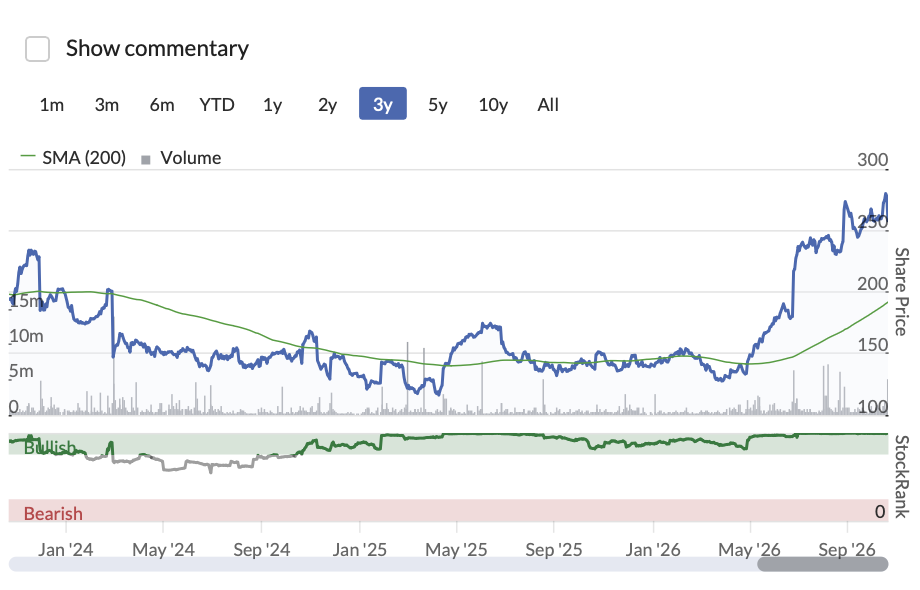
For a start, there’s no upgrade to guidance today. The company is still expecting FY27 underlying profit before tax of between £55m and £65m.
Second, accelerated investments in marketing and technology in H2 are expected to result in underlying PBT being weighted towards H1. In other words, H2 PBT could be soft and we could be looking at the lower end of that £55m to £65m forecast.
Third, I suspect that a lot of the recent sales growth has been driven by the incredible weather we had in the UK this summer. I imagine that this significantly boosted demand for bikes, cycling equipment, and camping equipment.
Finally, the valuation looks relatively full, to my mind. With analysts expecting EPS of 20.4p for FY27, we are looking at a P/E ratio of about 12.5 (note that the average analyst price target was only a few percentage points higher than the share price before today’s drop).
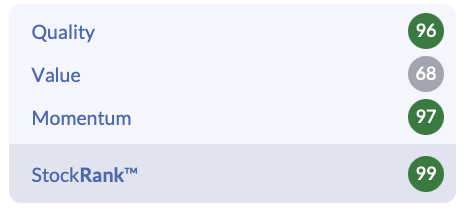
Now, the StockRank system does still like Halfords – it has a score of 99 at present (note that the Value score isn’t that high). Another positive is that there’s a near-4% dividend yield on offer at the moment.
I’m just not convinced that the share price momentum here will remain as strong as it has been lately. So, I’m taking the stock down a notch to AMBER/GREEN.
Graham's Section
Serabi Gold (LON:SRB)
Down 14% at 193.55p (£148m) - Reports Q3-2026 Production & Operational Highlights - Graham - AMBER ↓
Mark covered Serabi's H1 results last month. There were significant cost increases in Q2, leading to a decline in profitability ($9.1m of after-tax profit in Q2 vs. $21m in Q1). There were also some question marks over mine licences.
Today's Q3 update includes a reduction in production guidance for FY26, relating to these licences.
Q3 production was 11,008 oz, the same as Q2 this year, and lower than the level that Mark expected (13,000oz). This was due to "lower-than-expected grades from Palito Complex".
Palito has had a new ball mill installed, now in final commissioning, in anticipation of higher volumes.
Licences: Serabi's Coringa Mine "operates under a 3-year GUIA licence which expires on January 29, 2027... Discussion are ongoing... regarding continuation of the current GUIA". This is from Brazil's federal mining agency.
Under the GUIA, Serabi has permission to transport 100,000 tonnes of ore annually from Coringa to Palito, for processing. 85,600 tonnes out of this allowance had been transported by the end of September, and they now have to stop transporting to Palito - until the GUIA limit is increased, or they get an operating licence.
Two other government agencies are involved when it comes to getting an operating licence. One of them is needed to provide change of land use approval. The other one is the protection agency for indigenous groups. Both of these approvals are "progressing", with the land use approval said to be in the final stage. Inidigenous groups are said to have given their approval.
However:
Due to permitting delays affecting planned production ramp up, FY2026 gold production is now expected to be at similar levels to FY2025, compared with previous guidance of over 53,000 ounces.
It's not clear to me exactly which government agency is responsible for the delay - I would presume all of them that have not yet signed off on Serabi's plans.
The company's gold production last year was 44,169 ounces, so the new guidance is a very large downgrade (17%).
Low grades have kept quarterly production at 11,000 ounces, and it looks like the delay in permit will cap production at that level until it is resolved.
CEO comment:
Our immediate priority during FY2026 has been, to secure the outstanding approvals at Coringa, primarily the LO [operating licence] and in the near-term the continuation to operate under the GUIA trial mining license. These approvals would have enabled us to process additional Coringa material through the expanded Palito plant in the fourth quarter. As these approvals have still not been received, we are unable to deliver the previously anticipated increase in Q4-2026 production
Cash is strong at $63m, but there's a wide gap to reach the $100m that Mark estimated by year-end (on the basis of prior production guidance, which is no longer in force).
A word on dividends/buybacks:
The Board announces the 2026 shareholder return policy will be a targeted return of up to 20 - 30% of the Group’s free cash flow to shareholders through dividends or buy-backs.
Graham's view
As a rule I don't invest in miners, so perhaps I'm not the right person to talk about this stock. But it seems to me that the risks faced here are rather inscrutable: how long might it take various Brazilian federal agencies to provide their approval for Serabi's plans? I have no idea!
One particular risk that I'm wondering about is the potential for production at Coringo to come to a complete standstill, if the GUIA doesn't get extended before it expires in January, and if there is still no operating licence by then. I'd hope that the risk of that happening is almost nil.
The good news is that the company has the $64m cash balance to protect it.
In terms of profitability, today's update doesn't provide AISC (all-in sustaining cost) information but for context, AISC in H1 was $2,682. Even if it's a high-cost producer, it does still have a margin against the current gold price of $4,100.
We were moderately positive on this last time, after Mark studied the effect of higher costs on profitability.
With the addiition of permitting delays into the mix, I'm going to take us down another notch, to neutral.
This might still be a bargain - assuming high gold prices and the rapid receipt of permits. It had previously been forecast to generate net income of $95m and then $110m, this year and next year. But for today, I'm going to sit on the fence.
Duke Capital (LON:DUKE)
Up 4.5% at 22.48p (£115m) - Response re. Share Price: Operational Update - Graham - AMBER =
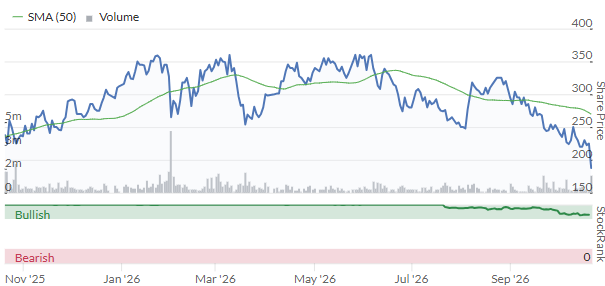
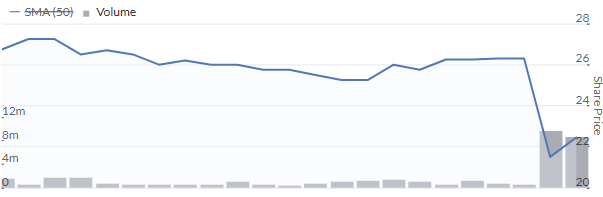
The DUKE share price has seen some drama this week, on above-average volume. It fell nearly 20% yesterday, on no official news:
This is how Duke responds:
Total cash revenue for the quarter ending September 30th was £7.0m, in line with the previous quarter
H1 dividends were covered by free cashflow
This bit seems more substantive:
The portfolio reorganisations referred to in FY26 accounts have made substantial progress, with materially loss-making divisions in two Duke investments now exited. As the UK market continues to be challenging, we do expect lower recurring revenue to be generated within our UK portfolio in H2 with the key focus of the investment team currently being on improving the performance of the UK portfolio into next year.
There are also two capital partners (a fancy word for borrowiers) who are "in late-stage processes for exits which, if concluded, could have a material positive impact on market expectations for FY27 total cash revenue."
Finally: "The Directors believe that the current share price sits at a material discount to the current NAV."
Graham's view
The only explanation for the fall that I can find is on the well-known bulletin board ADVFN. A poster there yesterday morning said that they had sold their shares, and they highlighted losses at inTEC, an IT managed services company based in Manchester.
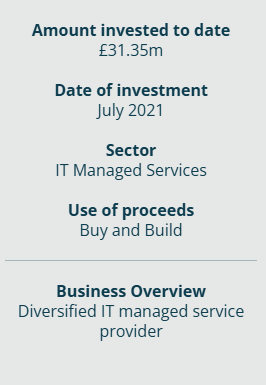
inTEC is still listed as a "current" investment on Duke's website, with £31m+ invested.
The latest accounts for inTEC Business Holdings were published about a week ago. They do not include a going concern warning from the auditors. They do show the company making an operating loss in 2025 of £7.8m, on revenues of £21.7m. They were loss-making the prior year, too.
The loss in 2025 included less than £2m of goodwill amortisation, so this is not a situation where the company was loss-making but cash flow was strong - operating cash flow was in fact negative.
Also, the balance sheet was deeply in the red with negative tangible equity of £38m. The main item here is Duke's loan which is shown with a value of £31.5m, charging an interest rate of 13.5%. Duke is also the "ultimate controlling party" - I think it owns 100% of inTEC.
As this is a "buy-and-build" situation, it's not so unusual to see highly negative balance sheet equity (due to high levels of goodwill).
However, it's always important to check that acquisitions are followed by profitability before too long, particularly where there is leverage involved.
We can only hope that inTec has had a much better 2026, and/or that it has been successfully reorganised (it has sold some of its subsidiaries in 2026), and/or that Duke is exiting it completely, without making a loss.
Last year, Mark did some digging into another Duke investment, and concluded by taking our stance on the company down by one notch to neutral.
I have some history here, as a former shareholder. I've not been tempted back in. I've accepted that Duke tends to invest in businesses that are not of the highest-quality, but I've been impressed by its ability (so far) to dodge any serious losses.
It has done this by successfully exiting some troubled investments. It also frequently ploughs money into its existing portfolio.
Duke's total investment portfolio at the end of FY March 2026 had an accounting value of £263m. After taking Duke's own leverage into account, net assets were £175m.
So if Duke's £32m position inTEC was worthless, it would cut Duke's net assets by 18%, to £143m.
The Duke market cap is at a c. 20% discount even to that low figure.
I'm going to leave us on neutral here. I don't see the need to take a negative stance when the share price has already taken such a heavy hit.
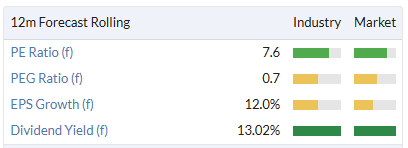
The share price is saying to us that there are likely to be multiple problem parts to the Duke portfolio. It might well be right about that. I'm still not tempted to buy back in here, even at a 13% yield.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Well done to Stocko for immediately doing their “ planned maintenance “ on a Wednesday afternoon ( website) in the face of today’s panic stations.
And well done to their app for describing it as “essential maintenance” which sounded much more appropriate !
Cannot be easy when these things come out of nowhere
Not one of the companies reported today, but does anyone have a point on the Brave Bison (LON:BBSN) offer for System1 (LON:SYS1)?
Shareholders are being offered £1.80 per Sys1 share in cash, plus 1 Brave Bison Group plc Contingent Value Right (CVR) worth up to 20p plus 2.394 new Brave Bison Group plc shares for each share held. £1.80 + 2.394(£0.74) =£3.57 which is a premium of 5% per share (excluding the CVR, which isn't guaranteed).
Why would shareholders accept that?! Am I missing something?
Shareholders aren't accepting it. They have barely anyone backing the deal, based on the announcements.
And the 20p contingency payment is only calculated and paid in 2028? Mid or end I believe. That's some time away.
I don't think Brave Bison (LON:BBSN) will get the votes before the voting ends in a week's time.
The question is what happens next? Do they quietly sit out their 6 month cool down period? Can they try something else?
I note that Lord Ashcroft, largest BBSN shareholder, has been hoovering up System1 (LON:SYS1) shares.
Between him and BBSN, they might own 50% of System1 soon. Will they seek to change the board? Management?
And System1 is trading very well. I wouldn't be surprised with a broker forecast upgrade coming soon, given their strong recovery and huge operational gearing. Without this bid, I have a value of 500p+ for the company. It was there before the whole setback with Trumps tariffs.
(I hold in the Boon Fund)
Interesting - thank you. I hold too - and have rejected the offer. As you say, it will be interesting to see what happens next.
Absolutely first class piece on Serabi Gold thank you Graham, combined with your advice to read the Stockopedia Academy article about appropriate action to take if you should find your stock affected by a Profit Warning. Although lucky enough to have been transferring funds from SRB to Goldplat during weeks leading up to this mornings news, I must have been asleep to miss the rapidly falling stock rank and share price over the previous 4 weeks that the excellent Profit Warning survival guide highlights.
Hercules Hercules (LON:HERC) I hold. Good to see an uptick with this national specialised labour/trade contractor with a performance 'ahead of market expectations'. With longer term contracts secured for the next few years, and operating in the more buoyant service & civil engineering sectors, (HS2, Water Sector & expanding into Power, Utilities & Civil Engineering), rather than the moribund residential housing sector, the future looks positive. Hercules are a preferred contractor/supplier for Balfour Beatty, one of the main contractors involved with the major upgrades of the Electricity Grid in the UK. Although there were issues with the late submission of accounts during this last financial year, which didn't give a great impression of the company, these problems appear to be in the past.
Agreed. Good update.
As a counter to Graham's excellent write-up on Serabi Gold (LON:SRB), I'll put forward the following.
Today's announcement was certainly disappointing, particularly the lower grades at Palito, but that said, the medium/long-term picture still looks very promising to me. I've spoken to Serabi a couple of times over the last few months and, to be fair to them, they've been pretty straightforward about the licensing situation.
Things move slowly at government level in Brazil (don't they everywhere!), but there is significant motivation to get this sorted. The Palito mine employs c.500 people from the local town, a significant proportion of the local workforce, and nobody wants to see those jobs put at risk.
From our conversations, management were still hopeful of securing either the GUIA extension or the full operating licence by year-end. They attach essentially zero probability to the licences not being granted eventually, believing it's in everyone's interests to get this done. Of course, that doesn't mean there can't be further delays, but even if it spills into Q1 2027, for a long-term holder, does it really matter?
After today's fall, the market cap sits at around $199m, and with $63m of net cash, the EV is just $136m. In a year with multiple headwinds (permitting delays, skyrocketing diesel prices, a strongly appreciating real and now lower grades at Palito), they still look set to make c.$50m in net profit, with potentially significantly more to come over the next two years.
The resource base is heading towards their target of 1.5–2.0m oz, they've made money in six of the past seven years (2022 being the sole exception, when they were bringing Coringa online), have a rock-solid balance sheet and have been operating in Brazil, a relatively established and stable mining jurisdiction, for well over a decade. They also have a long-standing management team who strike me as sensible.
None of this is to dismiss the permitting risk, particularly with the January GUIA expiry approaching, but I think it's important to distinguish between a delay to production and a permanent impairment of the underlying business. The market increasingly seems to be pricing in the latter, whereas I suspect we're dealing with the former.
Today is certainly a little irritating, but at an EV of just $136m, against the cash generation potential over the next few years, the medium/long-term asymmetry still looks pretty attractive to me.
I felt uncomfortable holding it when insiders sold large holdings back in 2025
Greenstone Resources II LP ("Greenstone") and Fratelli Investments Limited ("Fratelli") (the "Sellers") announce their intention to sell up to 15,689,395 ordinary shares in aggregate (the "Placing Shares") in the capital of Serabi Gold plc ("Serabi") to eligible institutional investors (the "Placing").
The Placing Shares will comprise Greenstone's entire holding of 3,936,492 ordinary shares and 11,752,903 ordinary shares currently held by Fratelli, corresponding in aggregate to approximately 20.7 per cent. of Serabi's entire issued share capital. It is expected that following the Placing, Fratelli will retain a holding of 7,565,882 ordinary shares, representing 10.0 per cent. of Serabi's entire issued share capital.
Of course it went higher afterwards but I still mulibaged it.
Re: Serabi
Serabi has been quite a Stockrank favourite for some time now. but the momentum has steadily been weakening since June/July. I am interested if any subscribers had a screen in place which flagged up a weak momentum sell point during this period?
Also it would appear that since approx the end of August, Serabi has moved from Superstock to Neutral to Contrarian? Again, were these useful at any time to trigger a sale?
I would guess that a sale using either of the above would have been at about 290/300 - which in light of today's announcement would have been a good time to exit.
No position
Hi Intuitive,
I tend to pull the trigger when stocks fall below the simple 200 day moving average. I can't recall who said it but a well known investor was quoted as saying "nothing good happens below the 200 day moving average" and I've often found that to be the case when I haven't heeded the signal.
Following that maxim would have given several opportunities to exit at around the 300p mark - in late June at about 298p, again in early July when the price failed to hold above the 200 day moving average and again in early September just above 300p when it fell through the moving average again.
I also use the 20 Day RSI indicator as a sort of canary in the coal mine and that was flagging warning signals around mid June as it fell below 50.
I'm no expert but adopting this strategy has certainly saved me a few pennies over the years.
I hope that's some help / food for thought.
Richard
I think most people quote Paul Tudor Jones as stating that nothing good happens below the 200d MA
Hi Richard,
Sounds like a good safety net. Apologies if a stupid question but where do you find the 200 day moving average on Stockopedia? (I can see it shows the 50 day moving average on the Stockreport chart). Can you set an alert so that it notifies you when one of your stocks falls below the 200 day moving average?
If you switch to the 3 year view (or greater) on the chart the MA shown automatically switches to the 200dMa if you want a quick graphical view.
Quantitatively its reported right next to the 50dMa in the section Price v's (%) at the top of any stockreport.
Thank you Revs8
I think you can also add it from under the Overlays option on the Stockopedia charts.
I tend to use Sharescope for my charting and other analysis but I am looking forward to future Stocko developments in this area to see if I can cut it down to one subscription - Stockopedia !
If you set a price alert, it is under technical indicators. You can alarm if the price goes below (or above) the 200d MA.
Thank you cheeky_minnows
Also...if you click on "Charts" just under header for stock you can add 200 DMA and 50 DMA together for a good view and it stays as default for all stocks when you select "Charts". I find this a really useful quick reference.
Thank you for the response Richard - and all the other subscribers who have in turn responded to Richard.
Serabi Gold (LON:SRB).
A SELL signal for me is when the Momentum Rank drops below 70, confirmed by the price below the Kumo.
The 200d MA gives a slower signal but helps reduce whipsaws.
A 20d RSI below 50 gives a similar signal to the Kumo but is slightly faster.
In the SRB case, all three strategies would’ve given a similar SELL point at around 265p. The difference would've been if the Momentum Rank cutoff point was different.
Coincidentally (or not), today’s fall was preceded by the falling Momentum Rank.
hi GenX,
I never really have managed to get to grips with the Ichimoku cloud - I wish I could - but I know fellow subscriber Phil Hough of Grow Your Dough is a big fan too.
I think the Simple 200 Day MA would have given multiple signals above the 265p you mention.
The first would have been around the 24th of June at 296p, the second on the 8th of July at about 300p and the third at the beginning of September at about 305p.
The 20 Day RSI on a 1D chart would have given an even higher sell flag in the 330p's a little earlier on the 8th of June as it fell through the 50 level.
I guess it just depends upon how quickly you pull the trigger or wait for further confirmation.
I would use two indicators to confirm a signal. For a momentum strategy, for example, I would use the Momentum Rank and another indicator like Kumo, RSI, or MA. But be clear why you’re selecting these indicators. Remember, Kumo and MAs confirm trends, while RSI is a momentum indicator. You don’t have to use Kumo. RSI (20) above/below 50 works well too. And, yes, it depends on how quickly you want to pull the trigger.
I set up a NAPs portfolio at the start of 2026 and this more or less automatically included Serabi Gold (LON:SRB) . The transactions were a BUY on 29/01/26 at 350.75p and SELL on 6/2/26 at 283p.
As it was a formula based portfolio the sell trigger was a 20% or more stop loss. I don't normally use Stop Losses but in this case it turned out to be a good decision.
Halfords (LON:HFD) I hold
A significant plus point in my book is that the Tour de France mens and women's events are kicking off with 3 stages each in the UK in 2027. As the largest cycling retailer, HFD should get a boost and will be well aware of how to exploit the opportunity I think.
nobody has mentioned the bid approach for Mobico (LON:MCG) (46 pence per MCG share in cash) so thought I would.
Bought some this morning before the open as indicated using the StockRank Jump effect screening filters
Mobico (LON:MCG)
(46 pence per MCG share in cash)
Just my luck i was literally looking at this like last month at 24p thinking things looked on the up a bit but didnt have the kahunas to take the plunge (the debt kinda made it potentially a binary bet) - such is life.
It was a Stockrank jump of more than 10 this morning so a rules based buy for me at the open. Very lucky that rns didn’t appear till 10am.
Hi, Barbara. If you don't mind me asking, are you running a screen using all of the criteria in Stocko's "StockRanks Jump Effect" report/webinar? If so, how long have you been running it and how's it been going? Many thanks, Neil2025
Follow them here. I think the answer is "very well"
https://substack.com/@zerogravitygraham
Many thanks for the link, Revs8 :-)
A question for anyone re Duke Capital (LON:DUKE) :
I owned this as a basket buy during the covid panic (i.e., a 'dumb' buy of a bit of many washed out micro caps). But it got cleared out after not long as I concentrated the basket as felt it both a bit meh and was never motivated to do more detailed work.
They are moaning about share price being unfair today. Not a good look IMO.
At a quick glance I feel concerned by the extent to which they have grown debt inline to ahead of direct operating cash flow AND (!!!) significantly increased the share count since FY21. This makes it look like a mildly distressed business that needs to recapitalise (and/or returns are leaking away somewhere from the shareholders).
Additionally the high but flat for years dividend is weird.
Views? Counterpoints?
Re Duke Capital (LON:DUKE) , it was commented on in the daily report of 19/06/26. Two of there investments look to be/gone bad. Today, in the RNS, they say that re the 2 investments, they have now "exited"
Big question is, how much (if any) £££ has been written-off on a £110m MC company regarding these 2 investments ?. And how risky are the rest of the investments ?
IMO REITS are great for their big dividends but not if the SP slides by more than the divis. EG, Ive held Primary Health Properties (LON:PHP) for just over 3 years and taken very nice dividends along the way. But even including dividends, my PHP overall value is slightly down over that time. Over that same 3 years, FTSE 100 is up c40%. GL if you continue to hold
Correction: DUKE is NOT a REIT, It comes under Investment Banking & Investment Services. My point re big divi payers still applies
It is very difficult to understand and has never delivered for shareholders. I still hold a little for the div. Journalists have repeadedly said it's model is successful in other countries!
I've spoken with the CEO and EDR a couple of times at these Investor meet company events. Seems to me that they keep issuing purely to make the company bigger not because of distress. However the issuance was too scary for me as like you I also jump in around covid and was then pleased to get out without losing money (or too much). Also have a stake in Twenty Four Income fund whose divi a year ago looked too good to be true but in actual terms it doesnt seem to be delivering does anyone have a view on this company.
Duke Royalty / Capital that was!
SThree (LON:STEM) reminder: The deadline for Circle8 (NMQ:CIRC) to make a firm offer is 5:00pm today.
See we have another "Stock Jumper" yesterday in James Cropper (LON:CRPR) - after an "ahead" RNS, SR of 93 and jumping price on day of 14%. Qualifies for Ed's trend theory? Substantial rise in recent months and as usual looks a challenging buy given this recent progress..... but the theory does has form....
I noticed yesterday that an old friend, Bioventix (LON:BVXP) , was making a move in advance of their final accounts.
For old times sake I bought a small stake to see how this pans out - big note on Researchtree on altzheimers antibodies so you never know - its way above my paygrade.
A.
I bought some Bioventix (LON:BVXP) about 6 months ago and have just moved into profit! Good run - up about a third in last 3 months and highest for almost a year. Nice bowl forming. See FY results are out on Monday ......... Fingers crossed for some good news!
Be great if you get a chance to have an update on Aberdeen (LON:ABDN) Graham , they have cashed out part of their stake in Phoenix and the II platform is doing well counter acted by their own main platform which is dire, plus their is that huge db pension scheme surplus of £800 mil or so from memory that could be unlocked.
It is nice to see Aberdeen is still pleased with its takeover of ii. Its half million investors aren't complaining either or they'd be walking away.
Hardide (LON:HDD) revenues more than doubled year on year, expected to double again over the next two to three years.
And importantly PBT comes in 6.5% above consensus.
Hardide (LON:HDD) jumped 9% at the open after its FY26 update, hitting a new 52-week high. If the gain holds, that’s 11 positive share-price reactions in a row.
Revenue matched forecasts; the beat came from margins. Hardide is at a clear financial inflection after years of losses, but whether this is transformational is unproven. The real tests come next: a significant follow-on North American order and the 10 December results. I hold.
Hardide (LON:HDD)
I try to resist being impulsive nowadays but must admit i have bought in today - i dont really know enough about the company to say if jumping straight in is sensible or paying peak price - normally after a nice pop on good news many companies draft back lower ref price once the dust settles. Looks like this company has some secret sauce as they are making great margins - great margins and sales growing at decent lick can be a good combo.
Hardide (LON:HDD) - not very often we have a 15 bagger in 12 months to fawn over - I wish I'd acted earlier, but still very tempted to add today...
I don't think that's too impulsive; there is enough in today's update that alludes to the potential for more contract wins which could see further eps upgrades.
Hardide (LON:HDD) I try too not to be impulsive however it does back fire sometimes and I need to shrug my shoulders and move on. I set up a price alert way back in May at a SP 60p. And took no action!
Hardide (LON:HDD)
I Guess my main doubt this morning was is this a real step change in fortunes or just a purple patch due to some orders that might dry up at some stage. kinda the same questions Ed was asking - ignoring the price rise above targets from months ago the pe in the year just starting is only 15 - aligned with trend in numbers that just seems cheap putting any shareprice increase to the side.
there is some extra commentary on the other place (advfn) - and that text uses the phrase step-change which is kinda what i was wanting to hear some sort of indication that its not simply a flash in the pan period of good numbers.
text on other place taken from wealth orcacle originally.
reflecting operational gearing on higher volumes alongside tangible benefits from cost management and continuous improvement work. The final quarter alone generated £4.6m of revenue and £1.9m of EBITDA, pointing to a genuine step-change in run-rate rather than one-off phasing. Momentum appears durable
Hi Graham.... if possible can we get a deep dive into Serabi Gold (LON:SRB) following today's statement. If I'm reading right looks like production below expectation, cash position positive, longer term view positive. Are we in for some short term pain (I hold) or will brokers take the side of future horizon. Cheers
I'll see what we can do!
I have had a watching eye on Serabi Gold (LON:SRB) for sometime as a previous holder....ofcourse they do well when the gold price is strong but they have a fairly strong record of missing all their ambitious production targets. Id say this is a worry and getting your head round permitting etc is always a headache and confirmed today. So at best you get positive cashflow after a gold rise and some head scratching - and I don't like head scratching especially when you are mining in Brazil.... I suspect the shares won't react well today to this news.
It's time to grit one teeth and hold on.
With Trump under-mining the Dollar so rapidly, gold is due a rise in price in the near future, but with the recent fall in SRB momentum and licensing questions, I have been reducing my own holdings to buy into Goldplat and transferred the remaining shares after this mornings profit warning, at which point Goldplat was the only mining stock I noticed with a slight daily increase.
They didn't react well. I'll admit to adding regularly as the share price lowered regularly and this poor situation led me to a taking a final snatch at the falling knife. I'm back to where I started price per share -wise but with a much larger holding. To fund this I sold four good investments, oh dear, I'm not really into gambling but October has been so quiet.
Talk about gambling - how much lower is Volex (LON:VLX) a favourite on here - going to fall?
Still higher than what it was at end of August with Volex (LON:VLX) ?
With shares that attract lots of retail interest and volumes, that are more fleety in and out than institutions, its par for course to see volatility. Only about 20% off the peak price. But maybe could be that the peak overshot the real value by 20%.
Always a risk when investing in a share that has lots of private investor interest, like Volex... so much ink spilled in the comments section on Stockopedia over the past few months.
I still hold this one too. Considering it a hedge of sorts. I'm not rushing to exit this morning but as a reflection, volume (OBV) has been declining since Q2 2025. This was my main reservation on this one as it's not a comfortable confirmation pattern. Perhaps I should have been more cautious.
I sold 2/3rds of my stake a while back to bank some decent profit; fortunately inside my ISA. I sold 50% of what I have left on this mornings news. Disappointing but it happens. Especially in this Sector. I will hold the remaining through whatever lies ahead but I’m not holding my breath. I still think things will eventually be resolved. The profit I have made will be reinvested in the only other small cap mining interest I have left - AAZ.
2 massively over valued companies become one massively over valued company, brilliant.
For those few of us lacking mental accuity, intelligence and time; what are you referring to?
Graham's comment "The largest merger of all time is currently being considered by special committees at two companies: Space Exploration Technologies (NSQ:SPCX) and Tesla (NSQ:TSLA)."
Space X & Tesla merger - no surprise from what I read at the time of the SpaceX float, they have a somewhat incestuous relationship! What will be more interesting is:
I cannot see Musk wanting to downgrade his voting power by much. On the other hand: passing the merger requires a 50% approval vote from all outstanding Tesla shares (believe Musk has around 19.8% of the o/s). Expect a bit of a soap / space opera!
Probably Space Exploration Technologies (NSQ:SPCX) and Tesla (NSQ:TSLA) referred to in the intro.
I caught on straight away as no doubt did most readers of Graham's introduction.