Hardide: revenue more than doubles to £13.5m and profit beats forecasts
Analyst’s view:
Hardide has provided us with another strong update today. For the year ended 30 September, revenue more than doubled while EBITDA and PBT are both expected to be ahead of market expectations. Encouragingly, the company has been winning work in the aerospace industry as well as the energy and industrial sectors. Looking ahead, it is hoping to double revenues again over the next two to three years. Overall, a very positive update so I’m keeping Hardide at GREEN.
Up 7% at 111p (£82m) - Year End Trading Update
Hardide, a provider of advanced surface coating technology, has provided a trading update for its financial year ended 30 September 2026 (FY26).
Highlights:
Revenues for the year more than doubled to £13.5m (FY25: £6.0m).
EBITDA is expected to be £5.8m (FY25: £1.0m) and profit before tax £4.9m (FY25: £0.2m), both ahead of market expectations*, as a result of improved cost management and continuous improvement initiatives.
Final quarter revenues were £4.6m, generating EBITDA of approximately £1.9m.
Gross cash at 30 September 2026 was £3.2m (after making a £1.5m investment in working capital).
Operational news:
Trading momentum continues to be strong.
The company successfully delivered the first shipments of coatings for a new generation of parts for its major North American customer, leading to a further US$1.9m sales order covering the period to November 2026, as announced on 14 September 2026.
The group has recently won further production work in the aerospace sector, together with new customer wins in the energy and industrials sectors, all of which will contribute to revenues in FY27.
Testing continues across a number of applications with a potential major energy sector customer in the Middle East, as well as customers in the semiconductor sector, with results to date proving encouraging.
A deposit of £0.7m has been paid for coating reactors with a total expected cost of £3.5m which, as previously announced, is expected to double Hardide’s operational capacity to approximately £40m of annual sales. The new capacity is scheduled to come on stream during the second half of FY27.
Outlook:
The combination of strong current trading momentum and encouraging recent order intake underpins market expectations and positions Hardide for further significant growth in FY27, consistent with the company’s strategic objective of more than doubling revenues again over the next two to three years.
* Hardide provides current FY26 market expectations of: revenue of £13.5m, EBITDA of £5.5m, and PBT of £4.6m and FY27 market expectations of: revenue of £18.8m, EBITDA of £8.0m, and PBT of £6.6m.
Ed S’s view:
I initiated a very small position in Hardide back in mid-September at 91.7p, despite the fact that the stock was already up 400% year to date at the time (it started 2026 at 18.5p). I was attracted to the prolific revenue growth, surge in profitability, talk of expansion into other industries, and reasonable valuation.
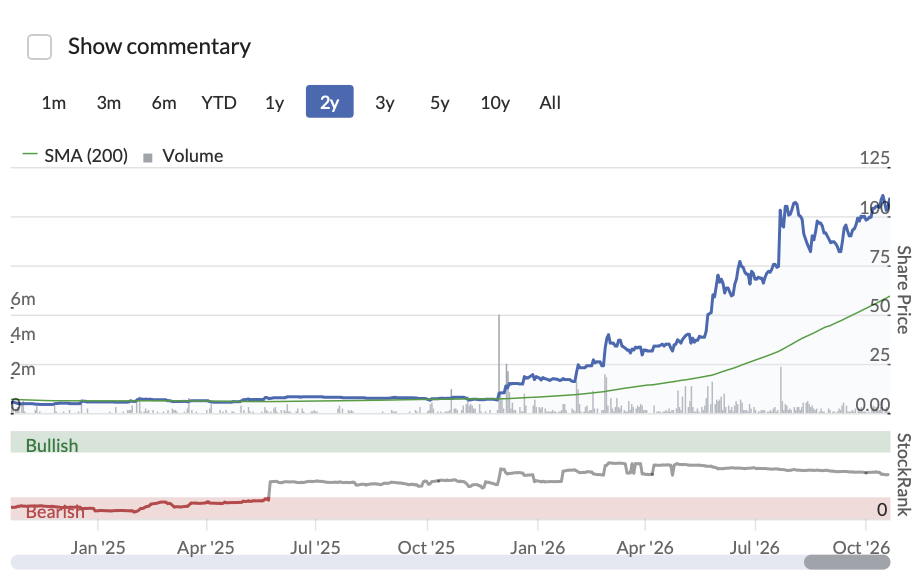
Today’s trading update vindicates my investment decision. This is a company with significant momentum at present.
For the year ended 30 September, revenue more than doubled to £13.5m. Meanwhile, EBITDA and profit before tax are expected to be £5.8m (FY25: £1.0m) and £4.9m (FY25: £0.2m) respectively, both ahead of market expectations, thanks to improved cost management and continuous improvement initiatives.
Looking ahead, the company plans to more than double revenues again over the next two to three years. It’s worth noting here that revenue in Q4 was £4.6m (34% of full-year revenue).
One thing I was concerned about when I invested here was customer concentration risk – a lot of the top-line growth over the last year has come from a North American customer in the energy space. So it's encouraging to hear that the group has recently won further production work in the aerospace sector, along with work in the energy and industrials sectors.
The company also notes that testing continues with a potential major energy sector customer in the Middle East as well as customers in the semiconductor sector. So, it’s definitely trying to diversify its customer base.
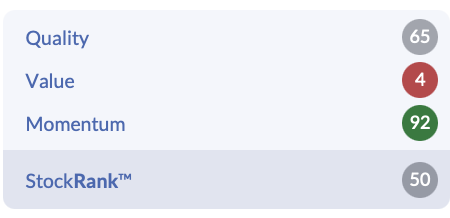
Now, the Stockopedia StockRank system doesn’t like Hardide so much – its score is only 50. But I think that will change.
In the past, revenues have been up and down and the company has consistently lost money. This has most likely weighed on its Quality score.
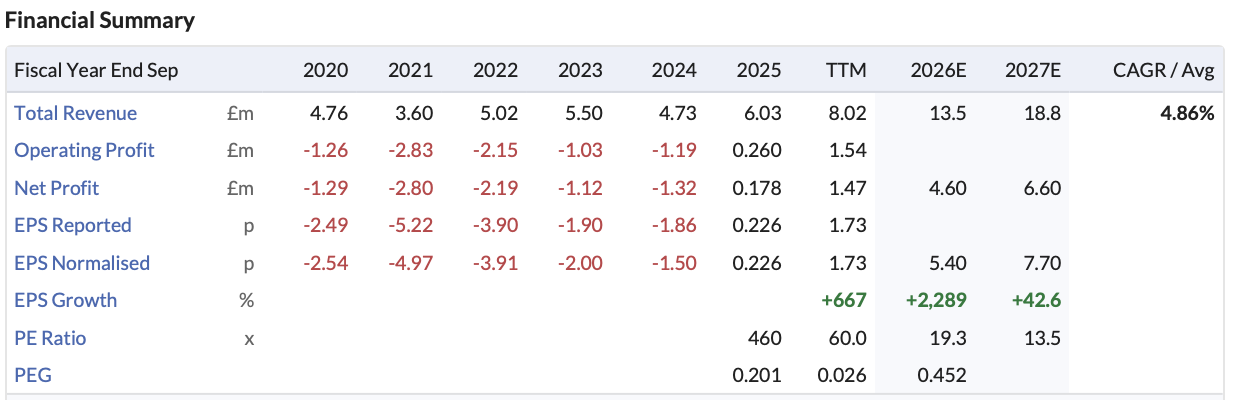
As for the Value score of 4, this is most likely down to the fact that earnings per share in FY25 were just 0.2p. With earnings of 7.7p forecast for the current financial year, the valuation is starting to look a lot more attractive (forward-looking P/E ratio of around 14) so we should see the Value score rise.
The Momentum score is already high at 92. You’d expect that after a 500% year-to-date gain.
Overall, I remain quite bullish on Hardide, despite its big move higher in 2026. After today’s update, I’m happy to keep the stock on a GREEN rating.
At the time of writing, Ed S had a long position in HDD
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Hardide (8)
Comments here are also visible in the Daily Stock Market Report
Hardide (LON:HDD) jumped 9% at the open after its FY26 update, hitting a new 52-week high. If the gain holds, that’s 11 positive share-price reactions in a row.
Revenue matched forecasts; the beat came from margins. Hardide is at a clear financial inflection after years of losses, but whether this is transformational is unproven. The real tests come next: a significant follow-on North American order and the 10 December results. I hold.
Hardide (LON:HDD) revenues more than doubled year on year, expected to double again over the next two to three years.
And importantly PBT comes in 6.5% above consensus.
Hardide (LON:HDD) jumped 9% at the open after its FY26 update, hitting a new 52-week high. If the gain holds, that’s 11 positive share-price reactions in a row.
Revenue matched forecasts; the beat came from margins. Hardide is at a clear financial inflection after years of losses, but whether this is transformational is unproven. The real tests come next: a significant follow-on North American order and the 10 December results. I hold.
Hardide (LON:HDD)
I try to resist being impulsive nowadays but must admit i have bought in today - i dont really know enough about the company to say if jumping straight in is sensible or paying peak price - normally after a nice pop on good news many companies draft back lower ref price once the dust settles. Looks like this company has some secret sauce as they are making great margins - great margins and sales growing at decent lick can be a good combo.
Hardide (LON:HDD) - not very often we have a 15 bagger in 12 months to fawn over - I wish I'd acted earlier, but still very tempted to add today...
I don't think that's too impulsive; there is enough in today's update that alludes to the potential for more contract wins which could see further eps upgrades.
Hardide (LON:HDD) I try too not to be impulsive however it does back fire sometimes and I need to shrug my shoulders and move on. I set up a price alert way back in May at a SP 60p. And took no action!
Hardide (LON:HDD)
I Guess my main doubt this morning was is this a real step change in fortunes or just a purple patch due to some orders that might dry up at some stage. kinda the same questions Ed was asking - ignoring the price rise above targets from months ago the pe in the year just starting is only 15 - aligned with trend in numbers that just seems cheap putting any shareprice increase to the side.
there is some extra commentary on the other place (advfn) - and that text uses the phrase step-change which is kinda what i was wanting to hear some sort of indication that its not simply a flash in the pan period of good numbers.
text on other place taken from wealth orcacle originally.
reflecting operational gearing on higher volumes alongside tangible benefits from cost management and continuous improvement work. The final quarter alone generated £4.6m of revenue and £1.9m of EBITDA, pointing to a genuine step-change in run-rate rather than one-off phasing. Momentum appears durable