Serabi Gold: permit delays cut gold output guidance by about 17%, and we turn neutral

Analyst’s view:
We were moderately positive on this last time, after Mark studied the effect of higher costs on profitability. With the addiition of permitting delays into the mix, I'm going to take us down another notch, to neutral. This might still be a bargain - assuming high gold prices and the rapid receipt of permits. It had previously been forecast to generate net income of $95m and then $110m, this year and next year. But for today, I'm going to sit on the fence.
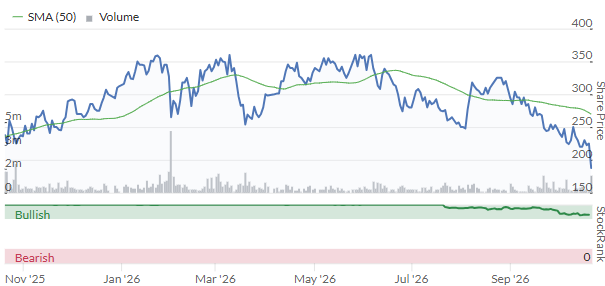
Down 14% at 193.55p (£148m) - Reports Q3-2026 Production & Operational Highlights
Mark covered Serabi's H1 results last month. There were significant cost increases in Q2, leading to a decline in profitability ($9.1m of after-tax profit in Q2 vs. $21m in Q1). There were also some question marks over mine licences.
Today's Q3 update includes a reduction in production guidance for FY26, relating to these licences.
Q3 production was 11,008 oz, the same as Q2 this year, and lower than the level that Mark expected (13,000oz). This was due to "lower-than-expected grades from Palito Complex".
Palito has had a new ball mill installed, now in final commissioning, in anticipation of higher volumes.
Licences: Serabi's Coringa Mine "operates under a 3-year GUIA licence which expires on January 29, 2027... Discussion are ongoing... regarding continuation of the current GUIA". This is from Brazil's federal mining agency.
Under the GUIA, Serabi has permission to transport 100,000 tonnes of ore annually from Coringa to Palito, for processing. 85,600 tonnes out of this allowance had been transported by the end of September, and they now have to stop transporting to Palito - until the GUIA limit is increased, or they get an operating licence.
Two other government agencies are involved when it comes to getting an operating licence. One of them is needed to provide change of land use approval. The other one is the protection agency for indigenous groups. Both of these approvals are "progressing", with the land use approval said to be in the final stage. Inidigenous groups are said to have given their approval.
However:
Due to permitting delays affecting planned production ramp up, FY2026 gold production is now expected to be at similar levels to FY2025, compared with previous guidance of over 53,000 ounces.
It's not clear to me exactly which government agency is responsible for the delay - I would presume all of them that have not yet signed off on Serabi's plans.
The company's gold production last year was 44,169 ounces, so the new guidance is a very large downgrade (17%).
Low grades have kept quarterly production at 11,000 ounces, and it looks like the delay in permit will cap production at that level until it is resolved.
CEO comment:
Our immediate priority during FY2026 has been, to secure the outstanding approvals at Coringa, primarily the LO [operating licence] and in the near-term the continuation to operate under the GUIA trial mining license. These approvals would have enabled us to process additional Coringa material through the expanded Palito plant in the fourth quarter. As these approvals have still not been received, we are unable to deliver the previously anticipated increase in Q4-2026 production
Cash is strong at $63m, but there's a wide gap to reach the $100m that Mark estimated by year-end (on the basis of prior production guidance, which is no longer in force).
A word on dividends/buybacks:
The Board announces the 2026 shareholder return policy will be a targeted return of up to 20 - 30% of the Group’s free cash flow to shareholders through dividends or buy-backs.
Graham's view
As a rule I don't invest in miners, so perhaps I'm not the right person to talk about this stock. But it seems to me that the risks faced here are rather inscrutable: how long might it take various Brazilian federal agencies to provide their approval for Serabi's plans? I have no idea!
One particular risk that I'm wondering about is the potential for production at Coringa to come to a complete standstill, if the GUIA doesn't get extended before it expires in January, and if there is still no operating licence by then. I'd hope that the risk of that happening is almost nil.
The good news is that the company has the $64m cash balance to protect it.
In terms of profitability, today's update doesn't provide AISC (all-in sustaining cost) information but for context, AISC in H1 was $2,682. Even if it's a high-cost producer, it does still have a margin against the current gold price of $4,100.
We were moderately positive on this last time, after Mark studied the effect of higher costs on profitability.
With the addiition of permitting delays into the mix, I'm going to take us down another notch, to neutral.
This might still be a bargain - assuming high gold prices and the rapid receipt of permits. It had previously been forecast to generate net income of $95m and then $110m, this year and next year. But for today, I'm going to sit on the fence.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Serabi Gold (17)
Comments here are also visible in the Daily Stock Market Report
Serabi Gold (LON:SRB) is in the 2026 NAPS and has had a profit warning but interestingly is an example of a stock that has a very high stock rank for quality (99). On reading the very informative Stockopedia guide to profit warnings it was noted that stocks over 50 and preferably above 75 on quality rank appear to recovery better than the value and momentum ranks. Interesting to see how Serbi Gold performs from here.
Serabi Gold (LON:SRB).
A SELL signal for me is when the Momentum Rank drops below 70, confirmed by the price below the Kumo.
The 200d MA gives a slower signal but helps reduce whipsaws.
A 20d RSI below 50 gives a similar signal to the Kumo but is slightly faster.
In the SRB case, all three strategies would’ve given a similar SELL point at around 265p. The difference would've been if the Momentum Rank cutoff point was different.
Coincidentally (or not), today’s fall was preceded by the falling Momentum Rank.
hi GenX,
I never really have managed to get to grips with the Ichimoku cloud - I wish I could - but I know fellow subscriber Phil Hough of Grow Your Dough is a big fan too.
I think the Simple 200 Day MA would have given multiple signals above the 265p you mention.
The first would have been around the 24th of June at 296p, the second on the 8th of July at about 300p and the third at the beginning of September at about 305p.
The 20 Day RSI on a 1D chart would have given an even higher sell flag in the 330p's a little earlier on the 8th of June as it fell through the 50 level.
I guess it just depends upon how quickly you pull the trigger or wait for further confirmation.
I would use two indicators to confirm a signal. For a momentum strategy, for example, I would use the Momentum Rank and another indicator like Kumo, RSI, or MA. But be clear why you’re selecting these indicators. Remember, Kumo and MAs confirm trends, while RSI is a momentum indicator. You don’t have to use Kumo. RSI (20) above/below 50 works well too. And, yes, it depends on how quickly you want to pull the trigger.
I set up a NAPs portfolio at the start of 2026 and this more or less automatically included Serabi Gold (LON:SRB) . The transactions were a BUY on 29/01/26 at 350.75p and SELL on 6/2/26 at 283p.
As it was a formula based portfolio the sell trigger was a 20% or more stop loss. I don't normally use Stop Losses but in this case it turned out to be a good decision.
As a counter to Graham's excellent write-up on Serabi Gold (LON:SRB), I'll put forward the following.
Today's announcement was certainly disappointing, particularly the lower grades at Palito, but that said, the medium/long-term picture still looks very promising to me. I've spoken to Serabi a couple of times over the last few months and, to be fair to them, they've been pretty straightforward about the licensing situation.
Things move slowly at government level in Brazil (don't they everywhere!), but there is significant motivation to get this sorted. The Palito mine employs c.500 people from the local town, a significant proportion of the local workforce, and nobody wants to see those jobs put at risk.
From our conversations, management were still hopeful of securing either the GUIA extension or the full operating licence by year-end. They attach essentially zero probability to the licences not being granted eventually, believing it's in everyone's interests to get this done. Of course, that doesn't mean there can't be further delays, but even if it spills into Q1 2027, for a long-term holder, does it really matter?
After today's fall, the market cap sits at around $199m, and with $63m of net cash, the EV is just $136m. In a year with multiple headwinds (permitting delays, skyrocketing diesel prices, a strongly appreciating real and now lower grades at Palito), they still look set to make c.$50m in net profit, with potentially significantly more to come over the next two years.
The resource base is heading towards their target of 1.5–2.0m oz, they've made money in six of the past seven years (2022 being the sole exception, when they were bringing Coringa online), have a rock-solid balance sheet and have been operating in Brazil, a relatively established and stable mining jurisdiction, for well over a decade. They also have a long-standing management team who strike me as sensible.
None of this is to dismiss the permitting risk, particularly with the January GUIA expiry approaching, but I think it's important to distinguish between a delay to production and a permanent impairment of the underlying business. The market increasingly seems to be pricing in the latter, whereas I suspect we're dealing with the former.
Today is certainly a little irritating, but at an EV of just $136m, against the cash generation potential over the next few years, the medium/long-term asymmetry still looks pretty attractive to me.
I felt uncomfortable holding it when insiders sold large holdings back in 2025
Greenstone Resources II LP ("Greenstone") and Fratelli Investments Limited ("Fratelli") (the "Sellers") announce their intention to sell up to 15,689,395 ordinary shares in aggregate (the "Placing Shares") in the capital of Serabi Gold plc ("Serabi") to eligible institutional investors (the "Placing").
The Placing Shares will comprise Greenstone's entire holding of 3,936,492 ordinary shares and 11,752,903 ordinary shares currently held by Fratelli, corresponding in aggregate to approximately 20.7 per cent. of Serabi's entire issued share capital. It is expected that following the Placing, Fratelli will retain a holding of 7,565,882 ordinary shares, representing 10.0 per cent. of Serabi's entire issued share capital.
Of course it went higher afterwards but I still mulibaged it.
Hi Graham.... if possible can we get a deep dive into Serabi Gold (LON:SRB) following today's statement. If I'm reading right looks like production below expectation, cash position positive, longer term view positive. Are we in for some short term pain (I hold) or will brokers take the side of future horizon. Cheers
I'll see what we can do!
I have had a watching eye on Serabi Gold (LON:SRB) for sometime as a previous holder....ofcourse they do well when the gold price is strong but they have a fairly strong record of missing all their ambitious production targets. Id say this is a worry and getting your head round permitting etc is always a headache and confirmed today. So at best you get positive cashflow after a gold rise and some head scratching - and I don't like head scratching especially when you are mining in Brazil.... I suspect the shares won't react well today to this news.
It's time to grit one teeth and hold on.
With Trump under-mining the Dollar so rapidly, gold is due a rise in price in the near future, but with the recent fall in SRB momentum and licensing questions, I have been reducing my own holdings to buy into Goldplat and transferred the remaining shares after this mornings profit warning, at which point Goldplat was the only mining stock I noticed with a slight daily increase.
They didn't react well. I'll admit to adding regularly as the share price lowered regularly and this poor situation led me to a taking a final snatch at the falling knife. I'm back to where I started price per share -wise but with a much larger holding. To fund this I sold four good investments, oh dear, I'm not really into gambling but October has been so quiet.
Talk about gambling - how much lower is Volex (LON:VLX) a favourite on here - going to fall?
Still higher than what it was at end of August with Volex (LON:VLX) ?
With shares that attract lots of retail interest and volumes, that are more fleety in and out than institutions, its par for course to see volatility. Only about 20% off the peak price. But maybe could be that the peak overshot the real value by 20%.
Always a risk when investing in a share that has lots of private investor interest, like Volex... so much ink spilled in the comments section on Stockopedia over the past few months.
I still hold this one too. Considering it a hedge of sorts. I'm not rushing to exit this morning but as a reflection, volume (OBV) has been declining since Q2 2025. This was my main reservation on this one as it's not a comfortable confirmation pattern. Perhaps I should have been more cautious.
I sold 2/3rds of my stake a while back to bank some decent profit; fortunately inside my ISA. I sold 50% of what I have left on this mornings news. Disappointing but it happens. Especially in this Sector. I will hold the remaining through whatever lies ahead but I’m not holding my breath. I still think things will eventually be resolved. The profit I have made will be reinvested in the only other small cap mining interest I have left - AAZ.