Halfords: like-for-like sales up 7.1%, but no upgrade and a full valuation cut our view
Analyst’s view:
Today’s half-year update from Halfords is a little mixed. On one hand, like-for-like sales growth over the period was decent at 7.1%. On the other hand, there’s no upgrade to full-year guidance and the company says that underlying PBT for the year will be weighted towards H1. Given the fact that the valuation looks pretty full, I’m going to take the stock down a peg to AMBER/GREEN.
Down 7% at 256p (£609m) - Trading update for the 26 weeks to 2 October 2026
Halfords has provided us with a short trading update for the 26 weeks to 2 October 2026 (H1 FY27):
Highlights:
Strong trading in H1 supports previously upgraded FY27 guidance.
Group like-for-like sales grew 7.1%, supporting the FY27 profit upgrade communicated in the trading update on 27 August 2026.
Retail LfL sales grew 7.7%, with Motoring LfL sales up 7.3% and Cycling LfL sales up 8.3%.
Autocentres (ex-Avayler) LfL sales grew 6.1%.
“The business continued to perform positively through the first half as we benefited from good execution against our strategic priorities and strong sales of seasonal categories through the warm summer weather. We move into the second half with confidence and look forward to sharing more detail on our progress at our interim results announcement later next month.”
Outlook:
Continues to expect FY27 underlying profit before tax of between £55m and £65m. The strong H1 performance combined with accelerated investments in marketing and technology in H2 will result in underlying profit before tax being weighted towards H1.
Ed S’s view:
When Graham covered Halfords on 27 August, he gave the stock a GREEN rating. However, he said at the time that if the retailer doesn’t pull another rabbit out of the hat in the next six months with another upgrade, he’d be inclined to take the rating back to AMBER/GREEN.
Looking at today’s update, I think now is the time to take it back to AMBER/GREEN. There are a few reasons why.
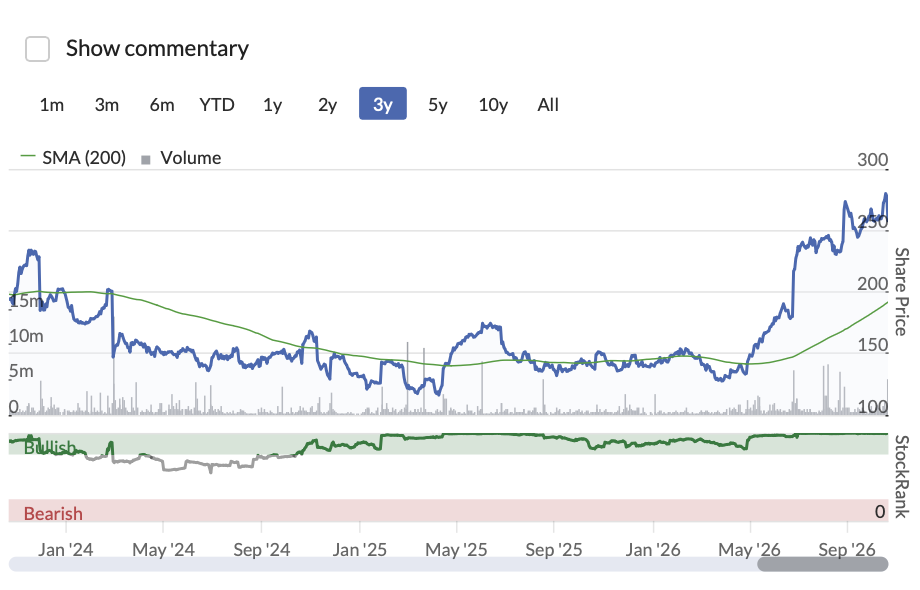
For a start, there’s no upgrade to guidance today. The company is still expecting FY27 underlying profit before tax of between £55m and £65m.
Second, accelerated investments in marketing and technology in H2 are expected to result in underlying PBT being weighted towards H1. In other words, H2 PBT could be soft and we could be looking at the lower end of that £55m to £65m forecast.
Third, I suspect that a lot of the recent sales growth has been driven by the incredible weather we had in the UK this summer. I imagine that this significantly boosted demand for bikes, cycling equipment, and camping equipment.
Finally, the valuation looks relatively full, to my mind. With analysts expecting EPS of 20.4p for FY27, we are looking at a P/E ratio of about 12.5 (note that the average analyst price target was only a few percentage points higher than the share price before today’s drop).
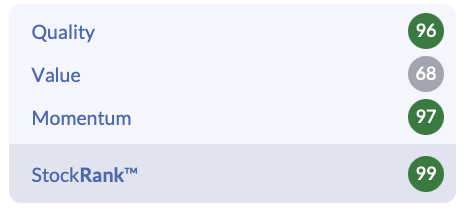
Now, the StockRank system does still like Halfords – it has a score of 99 at present (note that the Value score isn’t that high). Another positive is that there’s a near-4% dividend yield on offer at the moment.
I’m just not convinced that the share price momentum here will remain as strong as it has been lately. So, I’m taking the stock down a notch to AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Halfords (1)
Comments here are also visible in the Daily Stock Market Report
Halfords (LON:HFD) I hold
A significant plus point in my book is that the Tour de France mens and women's events are kicking off with 3 stages each in the UK in 2027. As the largest cycling retailer, HFD should get a boost and will be well aware of how to exploit the opportunity I think.