Dunelm: Q1 sales up 1.1% and profit forecasts hold after September's warning

Analyst’s view:
Roland was neutral on this last month and I'm leaving that unchanged today. The stock has suffered from a series of profit warnings, with the most recent one being in September. Normally I try to take a positive stance on a stock when it looks like forecasts have stabilised. But I tend to think that investors need to be extremely selective when it comes to retailers. And so I'd rather wait until firmer evidence that earnings forecasts have bottomed out, before upgrading our stance here.
Up 9% at 873p (£1.76bn) - First Quarter Trading Statement
Dunelm Group plc (“Dunelm” or “the Group”), the UK’s leading homewares retailer, updates on trading for the 13-week period ended 26 September 2026.
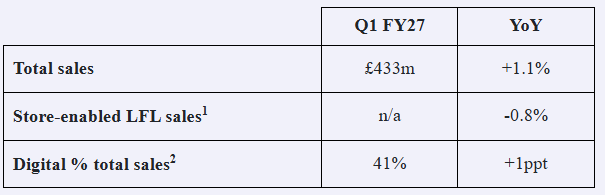
The market really liked this update, even if "store-enabled LFL sales" were negative:
Selected highlights:
Q1 sales up 1.1% "with stronger trading in the second half of the quarter, following a soft start impacted by hot weather" (Q1 is roughly July, August and September).
Gross margin up 10 basis points year-on-year, helped by FX rates.
Expectations for FY27 adjusted PBT unchanged and broadly in line with FY26
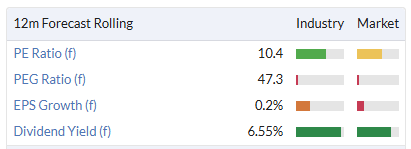
The market was (rightly) sceptical going into this update, meaning that the stock could rally on unchanged, flat expectations!
And last night's valuation was indeed fairly modest:
Markets can also be very sensitive to the second derivative of growth, i.e. the direction of travel of growth. Dunelm tells us that sales were down 3% in the first half of the quarter, but then were up 4% in the second half. That ought to bode well for Q2.
Retail conditions do remain tough:
Despite the challenging trading backdrop, we believe we continued to outperform an overall soft market.
Strategy: nothing unusual here. Two store openings are imminent, to accompany five renovations. Anything more ambitious than that would be a red flag, given the soft trading conditions.
Outlook:
Whilst the consumer backdrop remains uncertain, we are encouraged by the improvement in trading through the latter part of the quarter as we enter our peak trading period...
At this early stage in the year, our expectations for FY27 adjusted PBT remain unchanged and broadly in line with FY26. As our plans gather momentum, and with benefits weighted towards the second half of the year, we currently expect adjusted PBT to be lower than the prior year for the first half.
Let's add some context. Adjusted PBT was £114m in H1 last year, and £211m for the full-year (FY June 2026). Peak trading is in Q2.
Graham's view
Roland was neutral on this last month and I'm going to leave that unchanged today.
The stock has suffered from a series of profit warnings, with the most recent one being in September:
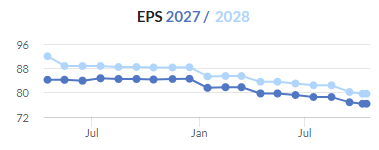
Normally I try to take a positive stance on a stock when it looks like forecasts have stabilised.
However, in the case of Dunelm, the last profit warning was still very recent - only last month. FY27 earnings were supposed to be higher than FY26, prior to that update, and the guidance now is that that they will be "broadly in line".
Perhaps in a less economically sensitive sector, I could take a sunnier outlook. But I tend to think that investors need to be extremely selective when it comes to retailers. And so I'd rather wait until firmer evidence that earnings have bottomed out, before upgrading our stance here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Dunelm (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?