Daily Stock Market Report (Thur 15th Oct 2026) - TPX, JNEO, JUP, PMI, XPS, THG, DNLM

Good morning! Markets are a little weaker overnight after US inflation came in higher than expected.
The annual inflation rate was 3.7%, versus consensus expectations of 3.6%.
The result was driven by a sharp rise in petrol prices. According to the US Bureau of Labour Statistics, “the index for gasoline rose 9.1 percent in September, accounting for over half of the monthly all items increase.”
This helps to give context for President Trump’s sudden decision to import Russian diesel, and his announcement of an unconfirmed “energy ceasefire” between Russia and Ukraine.
Even excluding food and energy, the annual core inflation rate (2.6%) was higher than the consensus forecast of 2.5%.
The news had an immediate impact on interest rate expectations. From Bloomberg:
"Markets are now pricing in about 40 basis points of Fed hikes by the end of January, with the odds of an October move also edging up."
The next Fed interest rate decision will be announced on Wednesday, October 28th.
Overnight market movements:
The FTSE is down 0.2% at 10,710
S&P 500 is down 0.4% at 7,690
Brent crude (December) is down 1.6% at $104.35/bbl
Gold is up 0.8% at $4,140oz
Bitcoin is down 1.4% at $80,500
Mark Simpson joins me today.
All done for today, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary (Author) | Our view (Author) |
|---|---|---|---|
Antofagasta (LON:ANTO) (£35.2bn | SR65) | Production guidance for 2026 remains unchanged (copper production 625,000–655,000 tonnes). Group-level guidance for cash costs before by-product credits has been raised to $2.60–2.70/lb (from $2.40–2.60/lb). Total Group copper production in 2027 is expected to be in the range of 630,000–690,000. | ||
British Land Public (LON:BLND) (£4.18bn | SR56) | Expect HY27 Underlying EPS of 16.1p, up 5% year on year. Reiterating FY27 Underlying EPS guidance of at least 30.5p (6% growth year on year). | ||
Mondi (LON:MNDI) (£3.61bn | SR54) | Q3 Underlying EBITDA €196m. “Excluding forestry fair value, underlying EBITDA was lower sequentially, primarily reflecting the impact of planned maintenance shuts.” CEO comment: “As we enter the fourth quarter, higher packaging paper prices are expected to support performance, notwithstanding ongoing input cost pressures.” | ||
Entain (LON:ENT) (£2.84bn | SR25) | .Q3 Net Gaming Revenue +2%. FY26 guidance reiterated: Online NGR growth of 4-6%, on a constant currency basis, with Underlying EBITDA at the lower end of £910m to £960m range. | ||
Big Yellow (LON:BYG) (£1.66bn | SR49) | Notes recent media coverage that a shareholder, who the Company met with recently, is encouraging Big Yellow to explore a sale. Confirms that it held some meetings in Oct 2025 and in December 2025 “received an indication from an interested party of a valuation level at which it could make a proposal.” The Board concluded the level was too low and discussions were terminated. Continues to focus on executing strategy and continually evaluates all options for maximising shareholder value. | TAKEOVER (speculation) | |
Dunelm (LON:DNLM) (£1.62bn | SR73) | Sales +1.1%. Store-enabled LfL sales down 0.8%. Expectations for FY27 adjusted PBT unchanged and broadly in line with FY26. | AMBER = (Graham) | |
Atalaya Mining Copper SA (LON:ATYM) (£1.58bn | SR87) | “For FY2026, Atalaya continues to expect production to be at the low end of the original guidance ranges of 50,000 – 54,000 tonnes of copper and 0.9 – 1.1 million ounces of silver contained in copper concentrate, respectively.” Continues to expect FY2026 Cash Costs and AISC to remain within the previously announced guidance ranges. | ||
Travis Perkins (LON:TPK) (£1.26bn | SR82) | Revenues down 1.6%. Merchanting businesses continue to actively manage transaction mix, prioritising higher margin trade and protecting against credit risk…” CEO comment: “In challenging market conditions we remain focused on what we can control.” | ||
Jupiter Fund Management (LON:JUP) (£889m | SR97) | Net positive flows of £0.7bn. AUM up 3% to £75.9 billion. | GREEN = (Graham) | |
Workspace (LON:WKP) (£706m | SR51) | 18 deals completed at 8% above estimated rental value. 18 deals under offer at 14% above estimated rental value. Net debt £754m. Proforma loan to value 36%. | ||
XPS Pensions (LON:XPS) (£646m | SR66) | H1 revenues +12% (11% organic). Austin Professional Resourcing integrating well and performing in line. Pensions Act 2025 expected to increase demand for advice. | AMBER/GREEN = (Graham) | |
Anglo Asian Mining (LON:AAZ) (£479m | SR88) | Q3 Copper Production +140% YoY to 5,514 tonnes as Demirli production continues to ramp-up in line with expectations. Gold production flat at 6,781oz. Silver production +27% to 52,969oz. | ||
Seraphim Space Investment Trust (LON:SSIT) (£472m | SR85) | NAV up 150.6% to £704.4m. NAV per ordinary share up 102.9% to 240.49p. NAV per C share 98.11p. "...substantial fair value gains across the portfolio, underpinned by strengthening defence tailwinds and major funding rounds, particularly from the Company's largest holding, ICEYE…” As at 13 October 2026, £72.5m of the C share proceeds deployed in five existing portfolio companies and one new company. | ||
THG (LON:THG) (£467m | SR38) | Q3 continuing CCY revenue +1.5% to £408.8m. | RED ↓ (Mark) | |
Gulf Keystone Petroleum (LON:GKP) (£433m | SR73) | First top-up barrels reconciling Q4 2025 export sales to international prices | A first cargo was recently lifted following the allocation of additional barrels by Iraq’s State Oil Marketing Organisation to compensate the Company and other IOCs party to the tripartite interim export agreements. The top-up barrels reconcile export sales during Q4 2025 to international prices and begin to repay the Company’s outstanding top-up receivables. | |
Tharisa (LON:THS) (£353m | SR99) | Valterra Platinum will purchase 50% of the PGM concentrate produced by the Tharisa Mine on comparable terms, replacing Sibanye-Stillwater Limited as an offtake partner. Northam Platinum retains its existing offtake arrangement for the remaining 50% of the Tharisa Mine's PGM concentrate production. | ||
Rank (LON:RNK) (£346m | SR66) | Q1 Group LFL Net Gaming Revenue +5% YoY to £216.1m. | ||
Capital (LON:CAPD) (£275m | SR88) | Q3 revenue -1.4% vs Q2 to $115.7m (drilling -5.1%, Mining -1.2%, MSALABS +9.2%). Fleet Utilisation 72% (Q2 72%). “Drilling revenue was lower in the quarter as we redeployed equipment from NGM and Sadiola to higher-returning contracts across our existing portfolio and into new contract wins.” FY Revenue Guidance maintained (after recent acquisition-driven increase). | ||
Norcros (LON:NXR) (£260m | SR76) | H1 Revenue +19% (LFL CCY +1.5%) to £220m. u/l Op Profit +12% to at least £24.6m. Net Debt excl leases £55m (5 Apr: £65.8m) | ||
Eagle Eye Solutions (LON:EYE) (£141m | SR53) | Multi-year contracts with Stater Bros, a leading Southern California supermarket chain, and Auto Mercado, Costa Rica's premier supermarket chain, expected to generate initial base ARR of c.£0.8m. Reinforce the commercial momentum delivered in FY26 and provide a strong start to FY27. | RNS Reach. | |
Pulsar Helium (LON:PLSR) (£106m | SR11) | The Two Harbors City Council has approved a Purchase and Development Agreement for Pulsar MN's proposed acquisition. | ||
Journeo (LON:JNEO) (£96.1m | SR75) | Renewal of its framework agreement with Transport UK London Bus expected to generate £6m in revenues over a 5-year period. | AMBER/GREEN = (Mark) | |
4Basebio (LON:4BB) (£87.4m | SR7) | Intention to raise gross proceeds of not less than £15 million at a fixed issue price of 515 pence per share (an 8.4% discount). | ||
Tpximpact Holdings (LON:TPX) (£77.2m | SR77) | Revenue +57% to at least £57.0m, Ad. EBITDA +134% to at least £7.5m. Net Cash £1.0m (31 Mar: £4.2m net debt). | GREEN = (Mark) | |
Seascape Energy Asia (LON:SEA) (£69m | SR32) | Received a Letter of Agreement from PETRONAS via Malaysia Petroleum Management in respect of a large areal extension to the north and east of its Temaris Cluster Small Field Asset PSC, which increases the Temaris SFA PSC to ~1,770 sq km, a 45% uplift in the overall PSC area. | ||
Premier Miton (LON:PMI) (£55.1m | SR52) | Net AuM Flows -£428m (-5%), Performance -£102m, (-1.2%). “Improving investment performance and lower redemption levels provide a more encouraging backdrop for flows.” | AMBER/RED = (Mark) | |
Town Centre Securities (LON:TOWN) (£53.1m | SR45) | LFL portfolio valuation -1.5% yoy. NTA per share 255p. EPRA PAT +64% to £2.9m. Resilient trading performance has continued into the first half of FY27. | ||
Kr1 (LON:KR1) (£48.8m | SR28) | Launch of its own dedicated Ethereum (“ETH”) validators, with an initial set of 10 validators, with plans to scale beyond 100 validators and stake a large majority of the Company’s 6,200 ETH position over time. | ||
PROCOOK (LON:PROC) (£45.8m | SR77) | Q2 Revenue +13.2% yoy to £24.1m (LFL +6.2%, Retail LFL flat). HY 27 Net Debt £3.7m (HY26: £4.1m). Confident in delivering a strong full year performance, in line with market expectations. | ||
Medpal AI (LON:MPAL) (£24.6m | SR8) | Eli Lilly, the exclusive supplier of GLP-1 Mounjaro, has confirmed that New Health has risen from 3,048th to 29th place in its supplier list (by volume supplied). | ||
Quadrise (LON:QED) (£22.2m | SR6) | A representative heavy sweet oil sample from Valkor's pilot plant has been received at the Quadrise Research Facility. Testing has commenced and both MSAR® and bioMSAR™ emulsions have been successfully formulated using the sample. Valkor has further advised the Company that it expects to pay US$300,000 of the outstanding US$950,000 site licence fee balance by the end of October 2026. | ||
Gana Media (LON:GANA) (£19.5m | SR2) | Gross Gaming Revenue $2.0m (26Q2: $0.14m). “The Board's priorities for the remainder of the year are to sustain acquisition efficiency, deepen engagement among the September cohort, and continue to lift GGR margin through product and content localisation.” | ||
Energypathways (LON:EPP) (£14.5m | SR4) | Fast-tracking development of its low-carbon hydrogen and graphite production facility at Barrow-in-Furness, Cumbria, with the aim of becoming revenue generative by 2029. | ||
Fusion Antibodies (LON:FAB) (£12.2m | SR3) | “The Company continues to manage its cash resources carefully and, in light of the lower than anticipated trading in H1 FY27, has implemented cost reduction measures, including a temporary recruitment freeze. The Board is actively reviewing the Company’s working capital requirements taking into account the expected timing and conversion of opportunities in the H2 commercial pipeline and will provide a further update as appropriate.” | ||
Southern Energy (LON:SOUC) (£11.7m | SR52) | Completion and initial flow-test results from the Terrible Creek 21-2 #2 Cotton Valley vertical well stabilised at a rate of 2.3 MMcf/d of natural gas plus 50 barrels of condensate per day (50° API). | ||
Newmark Security (LON:NWT) (£10.1m | SR77) | Revenue cont. ops +15% to £26.4m, EBITDA +19% to £3.5m, PAT +20% to £1.3m. Net Debt ex leases £4.8m (FY25: £2.1m). |
Mark's Section
Tpximpact Holdings (LON:TPX)
Up 13% at 91p (£77.2m) - First Half Trading Update - Mark - GREEN =
TPX Impact continues to compound my error in selling when the share price rose 40% on an in-line trading statement accompanying their interim results last December. The rise itself seemed excessive. However, I missed that it marked a turning point for both trading momentum and the market's perception of the company, shifting from one that misses expectations to one that hits or exceeds them.
As I wrote recently when reviewing competitor MadeTech, companies in this space find themselves at the confluence of three positive factors:
Drive to improve public sector efficiency: IT projects are seen as a key pillar of that aim.
Catch-up from the delayed Spending Review: This created a long freeze followed by a release of pent-up demand.
Shift to SMEs: This deliberate policy shift structurally favours firms exactly like TPX and Made Tech that are digital-native, agile-delivery consultancies built to sell into frameworks.
This positive momentum shows no sign of slowing down as of today, TPX say; their H1 delivered:
- Revenue of at least £57.0m (H1 FY26: £36.2m), representing at least 57% year-on-year growth;
- Adjusted EBITDA* of at least £7.5m (H1 FY26: £3.2m), representing at least 134% year-on-year growth;
I'm not really a fan of Adj. EBITDA as a metric, but there are signs that this is turning into cash:
Strengthened balance sheet with net cash as at 30 September 2026 of £1.0m (vs FY27 opening position of £4.2m net debt) - a significant acceleration against the previous guidance of eliminating net debt by the end of FY27.
Given this strength, it is perhaps unsurprising that they up their FY guidance:
- Revenue of at least £105m (previous guidance was for healthy double-digit revenue growth year-on-year)
- Adjusted EBITDA* of at least £14m (previous guidance was for adjusted EBITDA of not less than £12m)
This is a 17% upgrade to adjusted EBITDA, so it is a reasonable increase. They also appear to have delivered 54% of revenue and EBITDA guidance in H1. Historically, TPX has had a H2 Weighting, but since much of its delivery is project work subject to revenue-recognition timing, this doesn't automatically mean it's on for another beat. However, it does suggest they may still be guiding conservatively if past trends hold.
Cavendish upgrades their FY27E Adj. EPS figure from 8.3p to 9.8p, a 19% upgrade. They helpfully give a summary table of all of their recent forecast changes:
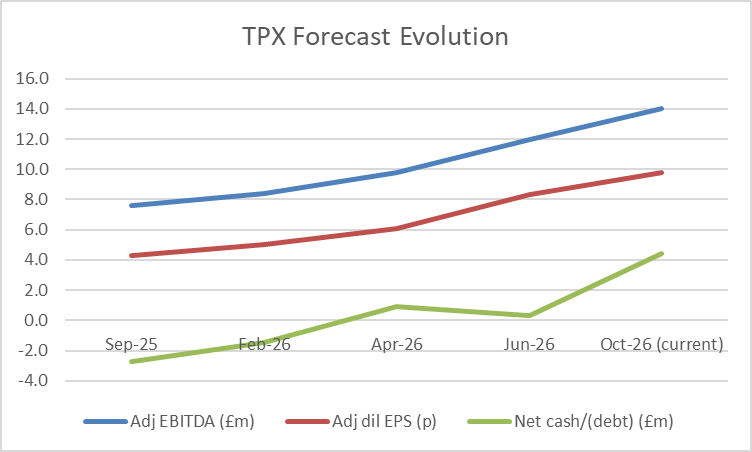
EPS has more than doubled in this time.
However, it is worth noting that the rating the shared trade on has increased over this time, too:
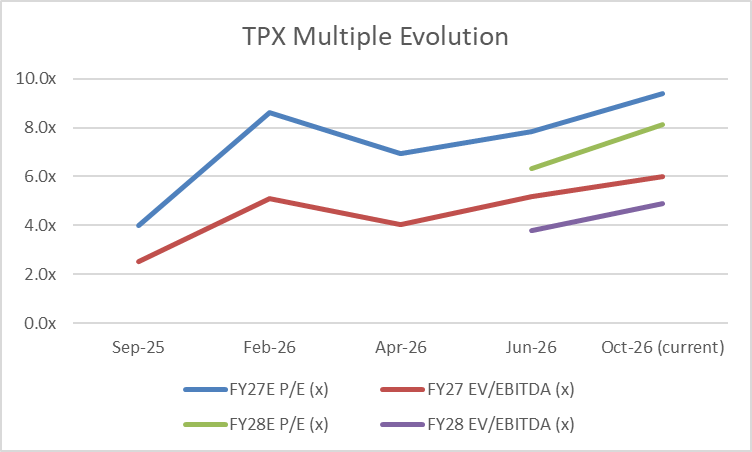
The shares were incredibly cheap at the end of 2025, and while a forward EV/EBITDA of 6 for a company performing this strongly still seems good value, it is not quite the bargain it once was.
This effect is seen more strongly in the FY28 numbers, where forecasts were only introduced in June. FY28E EPS was only increased by 9.7% to 11.3p today. The FY28 P/E goes from 6.3x in June to 8.1x today. Again, not expensive, but this assumes that the current business momentum continues into FY29 and beyond to continue to look cheap.
Mark's View
With the share price today rising roughly in line with the average upgrades to future years, the shares stay on roughly the same multiples. Share price strength over the summer means that the multiple has expanded and this is no longer as cheap as it once was.
However, strong H1 trading and a typical H2 weighting mean the company may still be guiding investors conservatively. On an absolute basis, the stock continues to look like good value.
The biggest risk remains that the current trading strength has less to do with company-level execution and more with recent industry trends that are "floating all boats". This means that if the tide of favourable conditions starts to go out, they may be left high and dry where they started. After all, the company had been loss-making for the last four years.
As today's update shows, there appears to be no sign of that tide reversing in the near term, and the company is cheaper than competitor Madetech on forward metrics, so we should remain positive. GREEN
Journeo (LON:JNEO)
Flat at 542p (£96.1m) - Framework Agreement - Mark - AMBER/GREEN =
Journeo announce a new Framework agreement:
...the renewal of its framework agreement with Transport UK London Bus...The Agreement is expected to generate £6m in revenues over a 5-year period and will run through to October 2031.
This means roughly £1.2m a year. However, this is just 1.7% of their forecast £72m revenue for the current year, and is a renewal rather than an additional win.
This seems in keeping with their typical behaviour, which is to RNS any contract for greater than £1m, or that looks strategic.
When they released H1 results, they said:
Revenue for the full year is expected to be marginally ahead of current market expectations, with adjusted profit before tax remaining in line with market expectations.
H1 group revenue was £37.6m, up 53% from £24.5m. FY26 market expectations are revenue of £72m. That implies H2 revenue of about £35–36m, slightly below H1.
I asked Claude to look at all recent contract announcements and estimate the revenue from these that would land in H1 and H2:
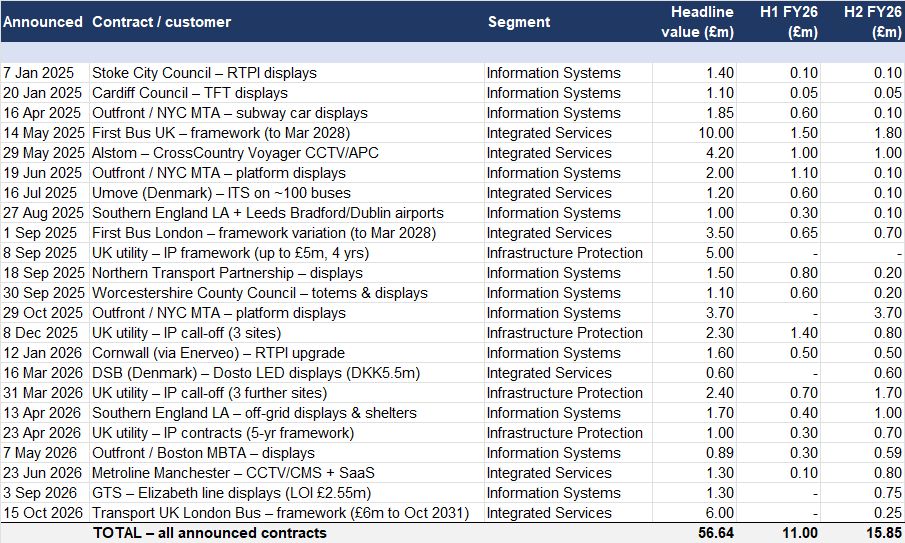
This is actually better than I thought, as Claude estimates about £11m of known contract revenue would have landed in H1, and they delivered almost £38m of revenue. H2 has £16m of estimated known contracted revenue versus £35-36m to deliver.
So while I share Roland's previously voiced concerns that revenue from known RNSed contracts is looking a little light, I'm not sure there is currently a huge risk for FY26.
Their broker, Cavendish, also included FY27 forecasts for the first time, which show revenue of £80m but EPS rising only 3% to 33.4p, suggesting a growth in lower-margin work. This is where I start to feel concerned.
We already know the company has many smaller contracts that don't get RNSed, and that there is still 14.5 months to go to the end of that reporting period. However, my Claude summary only has a £9.3m estimate for known RNSed revenue at this point versus an £80m forecast. This is how Claude puts the risks here:
About 60% of FY27 cover is framework run-rate.
First Bus (£3.3m), First Bus London (£1.35m) and Transport UK (£1.2m) make up about £5.9m. These are expected values so that actual call-off volumes could differ.
Alstom is the only large project still running into FY27.
The company says most of its revenue falls across FY26 and FY27, with installation completing in 2027. About £2m of SaaS revenue then follows over five years.
The recurring tails are small.
Umove, Cornwall, Metroline and the maintenance contracts add up to about £0.7m. For context, group recurring revenue in FY25 was £7.7m, so some of these lines already overlap with that base.
The gap to fill is large.
FY26 is tracking at about £72m+, and announced contracts cover only about £9m of FY27. FY27 growth therefore depends on new orders: further utility call-offs, US repeat business, new local-authority work and the £200m pipeline.
Mark’s view
When Roland reviewed this last, the company was trading on a forward P/E of 14.2 in FY27, and he commented that "this doesn’t seem excessive to me for a business with a net cash balance sheet and decent quality metrics."
This multiple has risen to 16.2x on a strong share price, and even accounting for net cash, this multiple suggests the company should grow EPS in the mid-teens over the medium term. They've achieved this in the past. However, forward EPS growth is forecast to be below inflation; I think we need to start seeing higher contract newsflow soon to give any confidence of hitting that figure. When a company on a growth multiple starts to decline, even temporarily, the market reaction can often be brutal.
I'm not going to change our previously mostly positive view today. After all, FY26 looks more achievable than I'd previously assumed, and this contract renewal helps the FY27 numbers. Just that personally, I'm struggling to build confidence that FY27 estimates can be hit or even beaten, and therefore that the current rating can be justified.
Premier Miton (LON:PMI)
Down 6% at 32p (£m) - Q4 AuM update - Mark - AMBER/RED =
This is another weak quarter for this asset manager. Pretty much all their strategies saw outflows and negative performance:
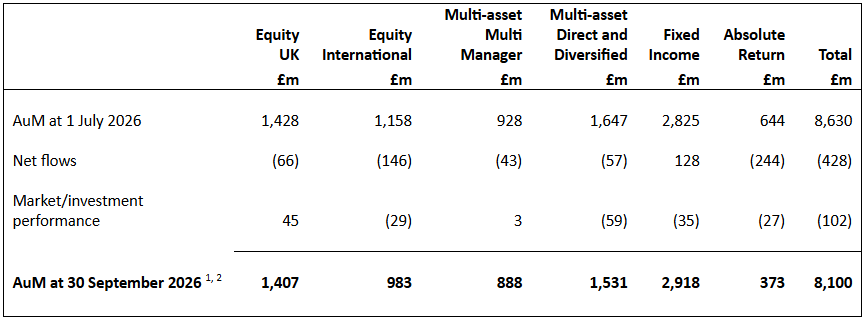
Although, interstingly UK equities is a bright spot (well, less-dim-than-the-others spot, to be precise).
The company says that:
Improving investment performance and lower redemption levels provide a more encouraging backdrop for flows
However, these numbers don't show much of that. A simple trend line suggests that, if anything, outflows are increasing:
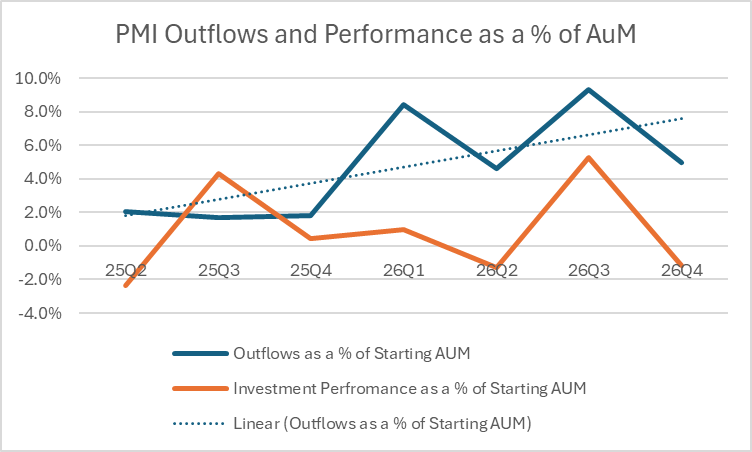
The improvement seems to be limited to the month of September:
Following the elevated outflows in July and August, net outflows reduced significantly in September as redemption levels materially reduced across several strategies, while fixed income and macro thematic multi-asset funds continued to see good demand.
So that may be a sign of things bottoming. It's hard to tell from a single month.
There seems to be a recognition that performance in certain strategies is a problem:
However, there are areas where further progress is required. We continue to focus on improving shorter-term performance across our diversified multi-asset strategies. Absolute return has also experienced a challenging period for performance, reflecting a difficult backdrop for long-short strategies. More recent investment performance has been stable, and we retain confidence in the team and its ability to deliver the investment outcomes required to support greater stability in assets.
Like many companies in a similar situation, an increased focus on cost-cutting may be the only short-term lever they have:
Following a review over the summer, we have identified a further £1.5 million of annualised cost savings which are expected to be delivered over the next 12 months with an estimated one-off cost of £0.3 million.
This is a quick payback and looks necessary, so it is good that they are grasping the nettle.
Forecasts:
I can't see any updated coverage from Cavendish. But their £50.3m revenue and 3p of EPS were based on £8.6bn of AuM. One quarter alone doesn't make much of an impact, but with AuM ending at £8.1bn, it suggests they may miss slightly.
The impact on FY27E looks the most severe, as ending next year with £9.6bn in AuM now looks like a heroic assumption. The £49.3m revenue currently forecast (presumably due to pressure on fees) and hence the 3.2p forecast look unrealistic, although that £1.5m of cost-savings may help, as it would be around a quarter of PBT as things stand.
Cash:
It is better news on cash flow as they say this stands at £26m, which is up from the £24.6m at the year end, despite a £2.4m dividend paid in the period.
This is half the current market cap. However, some of this will be required for regulatory capital. The requirement stood at £13.4m at the half-year, and they wouldn't want to get too close to that, so we can assume around £10m is genuinely free cash that could be used for acquisitions or similar. They do say:
Our strong balance sheet and position as a listed business provide us with strategic and financial flexibility to pursue inorganic opportunities that can add scale, enhance our investment capabilities and broaden our access to attractive client segments.
The market has liked it recently when companies such as Liontrust have done small bolt-ons, adding more to the market cap than teh companies have spent.
Valuation:
It is perhaps unsurprising that the market hasn't liked this update this morning.
Without updates from their broker, it is hard to arrive at an accurate valuation multiple. If I assume, say, a 10% miss on FY26/27 EPS, then we get something like an 11x P/E falling to 10x for FY27. This would be closer to 8 if we adjust for free cash.
Cavendish are forecasting 3p dividend for this year from an additional 1.5p final dividend beofre this being cut to 2.4p for the full year next year. This is still a pretty decent yield of 10%->8%. However, if this ends up uncovered, the company may cut it further in the short term.
This doesn't make the company expensive, and there is the chance of cost-cutting improving some of these estimates.
Mark's View
The multiples here aren't demanding, especially if investors think the cyclical downturn in smaller active asset managers is about to turn.
However, there is no sign of slowing outflows in the recent quarterly numbers, and the company doesn't stand out as particularly cheap in the sector. Something the middling Value Rank picks out:
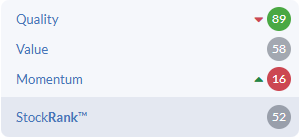
The very low Momentum Rank should also give us pause (although the example of recruiters recently shows that this figure can change rapidly if the share price starts rising).
It's hard to consider this company an investment until the numbers clearly show outflows have become inflows again. Until then, I'll keep my previously broad negative view.
THG (LON:THG)
Up 17% at 32p (£467m) - Q3 2026 Trading Statement - Mark - RED ↓
From the title of the RNS, THG management appears to be excited by these results:
Strong profitability momentum drives upgrade of FY26 Adjusted EBITDA expectations to £103m
However, a quick look at the details leaves a far less-favourable impression:
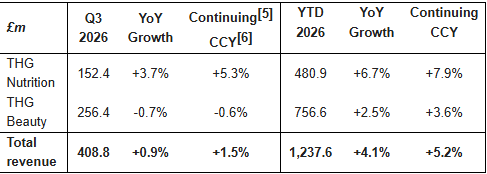
THG Beauty seems to be continuing CCY revenue decline in absolute terms, not just after inflation. THG Nutrition had a much better quarter; however, one that grew below recent trends from H1. Myprotein continues to do the heavy lifting (as do presumably the consumers of this product!) But it is the drop in whey prices that really makes a difference:
Improving whey commodity pricing: WPC80 prices continue to decline through September and early October, as supply increases and growing product substitution, with the external index falling c.20% since the Group’s Interim Results. Q4 requirements have been secured at more favourable pricing than Q3, while Q1 2027 coverage is now being secured below prevailing market rates.
Doing a few quick estimates:
- Whey-based powders are still the core of Myprotein, but a growing share of sales is creatine, activewear, hydration and licensing. Assuming Nutrition’s cost of goods is about £400m and whey is 40–50% of it, THG buys about £150–200m of whey a year.
- A 20% drop in price for Q4 would £7.5-£10m gross savings, perhaps £3-6m net EBITDA gain as some of that is passed through to customers.
So, all things being equal, we can expect this factor alone to have added at least £3m to EBITDA, and to be behind some of today's upgrade. So how big was it?
After much scrolling, I get to:
Consensus being revenue £1,802.2m, Adjusted EBITDA £101.7m
So this turns out to be only a £1.3m EBITDA upgrade, i.e. 1.3%, and below what we should probably expect from the benefit of lower whey prices alone.
This minor upgrade is nowhere near enough to bring the company to profitability based on current forecasts.
Mark’s view
I can only assume most investors have forgotten how to scroll and only read the headline, which seems to bear little resemblance to the actual figures released, as the share price is up 17% today.
This still seems a remarkable market cap for a company that has never made an accounting profit, never paid a dividend and has £0.5bn of debt (including leases).
Graham upgraded this to AMBER/RED last August, expecting the sale of Claremont Ingredients to rebuild the balance sheet. Since it doesn't appear to have done that, I'm taking this back down to RED.
Graham's Section
Jupiter Fund Management (LON:JUP)
Up 1% at 174.8p (£896m) - Trading Update and Notice of Results - Graham - GREEN
It's been a little while since we've checked in here. In April I was positive at a share price of 156.8p. Indeed, I've been fully positive on this once for a year.
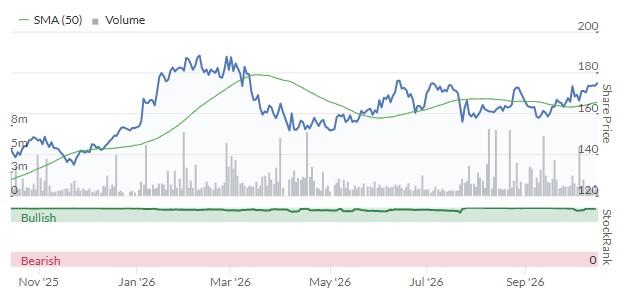
Today we have news of positive flows: £0.7 billion in Q3, bringing year-to-date flows to £1.4 billion.
The sequence of flows year-to-date is therefore like this:
Q1: positive £1.5 billion
Q2: negative £0.8 billion
Q3: positive £0.7 billion.
In 2025, net flows were positive £1.3 billion - the first year of
positive flows since 2017!
So we look to be edging closer to the second consecutive year of positive flows. A fine achievement for a business the market had been pricing for extinction. The share price has more than double since early 2025.
Q3 would have been even stronger if not for the acquired business, CCLA, which saw outflows:
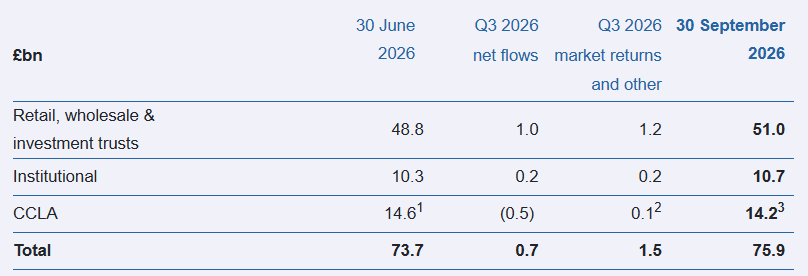
With the help of positive market returns, AUM increased by 3% in the quarter.
Excluding CCLA, I calculate that AUM has increased by 14% in 2026 year-to-date, or in total by 36% since early 2025 (from £45.3 billion to £61.7 billion).
That enormous increase in AUM has been driven mostly by market returns, but flows have also made a meaningful contribution (£3.9 billion).
It's a very favourable scenario for a fund manager: positive net new business, combined with strongly rising markets. Jupiter shareholders had to wait a long time to experience that - I don't recommend looking at the 10 year chart!
Including CCLA, headline AUM has now surged to a level that is 67% higher than what Jupiter was managing in early 2025.
We get an update on how CCLA is doing:
Following a period of weaker investment performance, the CCLA investment team has continued to make changes to the investment process and strengthen collaboration across the wider Group. We are now seeing early signs of improvement, with a number of CCLA funds outperforming relevant comparators over shorter periods.
CCLA historically catered for churches, charities and local authorities. I wouldn't expect much growth or high margins at this division, but this was reflected in the cheap price paid by Jupiter (£100m).
Graham's view
This is a Super Stock with a StockRank of 97:
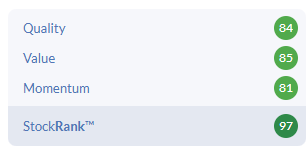
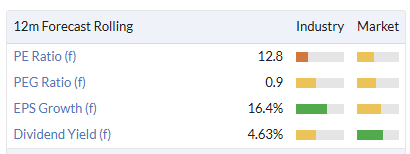
After another quarter of positive flows, I'm inclined to stay positive here. The shares are still not particularly expensive at 11x earnings, with a yield of 4.6%.
In AUM terms, each £1 invested in Jupiter shares at the current price buys you nearly £85 of AUM. That's not as depressed as we can find elsewhere in the fund management sector right now, but it's not bad. According to my sums, it's actually better value than what Jupiter shares offered at the start of this year: £80 of AUM per £1 of market cap, including the £15 billion that was bought in from CCLA.
XPS Pensions (LON:XPS)
Up 7% at 331p (£690m) - Post-close Trading Update - Graham - AMBER/GREEN =
This pensions consultancy/administration business has enjoyed a remarkable few years of growth:
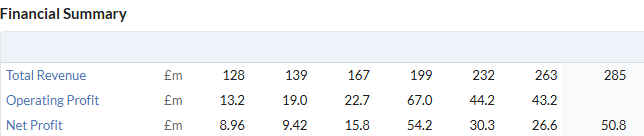
FY March 2027 is shaping up to be another good year: today's update says that they are "confident of achieving full year results slightly ahead of its expectations".
Key points:
Total H1 revenues +12% (11% organic)
Advisory revenues +14% (12% organic)
Administration revenues +10%
Self-invested pensions (SIP) +7% (XPS is a SIPP/SSAS pension provider, trustee, and administrator.)
Changes to the pension landscape provide fertile environment in which it can sell its advice and services: "We have seen strong demand arising from ongoing regulatory change, including from pension schemes seeking advice about running-on for surplus extraction."
You've probably noticed that many pension schemes we've covered in this report have recovered from deficit into surplus. When a defined benefit pension fund reaches such a healthy state, the employer will very often sell the whole thing to an insurance company.
However, where there is a large surplus, there is also the choice to run it on. The Pension Schemes Act 2026 "allows, with strict safeguards, for surplus to be shared between sponsoring employers and members".
In other words it should soon be possible, subject to many conditions and safeguards, for employers to share in the surplus value that their pension funds have created. This additional value is no longer "trapped".
Figuring out how to execute this means a new source of work for the likes of XPS:
Pensions Act 2025 received Royal Assent in April 2026, and DB surplus release is set to begin from 6 April 2027. This is expected to increase demand for advice as well-funded defined benefit schemes consider whether to run on for surplus or pursue an insurer buyout. XPS is well placed to support either route by providing expert consultancy every step along the way, following the members and providing award-winning pensions administration services either directly or on behalf of insurers.
And a comment from the CEO of XPS:
"The pensions industry continues to be very busy, and our clients have a wide range of opportunities in front of them, particularly with the new surplus release regulations coming in April next year. We are really well placed to help them whether running on is on their agenda, or if they want to access one of the many options emerging in the risk transfer market.
Graham's view
We've been AMBER/GREEN on this and I'm content to leave that unchanged today.
It continues to surprise me how much work is being generated by defined benefit schemes.
One risk that I do wonder about is what will happen when the complex questions about what to do with these DB pension schemes have finally been answered. XPS will always be challenged to evolve with the changing pension landscape, and it strikes me that simpler DC pensions may (in general) not require such complex consultancy as DB pensions.
In the short-term and medium-term, however, XPS is an example of a very successful financial consultancy and administration outfit, and there is every chance that it will continue to find new ways to serve its customers, e.g. by focusing more on insurance. At this moderate valuation, let's keep our moderately positive view.
Dunelm (LON:DNLM)
Up 9% at 873p (£1.76bn) - First Quarter Trading Statement - Graham - AMBER =
Dunelm Group plc (“Dunelm” or “the Group”), the UK’s leading homewares retailer, updates on trading for the 13-week period ended 26 September 2026.
The market really liked this update, even if "store-enabled LFL sales" were negative:
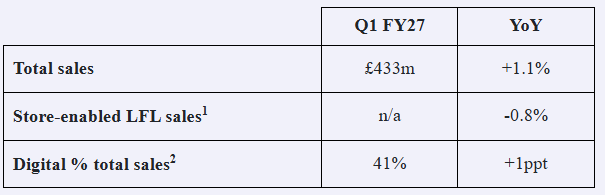
Selected highlights:
Q1 sales up 1.1% "with stronger trading in the second half of the quarter, following a soft start impacted by hot weather" (Q1 is roughly July, August and September).
Gross margin up 10 basis points year-on-year, helped by FX rates.
Expectations for FY27 adjusted PBT unchanged and broadly in line with FY26
The market was (rightly) sceptical going into this update, meaning that the stock could rally on unchanged, flat expectations!
And last night's valuation was indeed fairly modest:
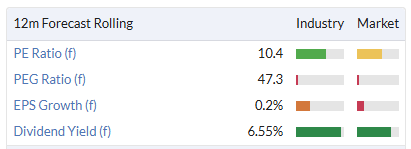
Markets can also be very sensitive to the second derivative of growth, i.e. the direction of travel of growth. Dunelm tells us that sales were down 3% in the first half of the quarter, but then were up 4% in the second half. That ought to bode well for Q2.
Retail conditions do remain tough:
Despite the challenging trading backdrop, we believe we continued to outperform an overall soft market.
Strategy: nothing unusual here. Two store openings are imminent, to accompany five renovations. Anything more ambitious than that would be a red flag, given the soft trading conditions.
Outlook:
Whilst the consumer backdrop remains uncertain, we are encouraged by the improvement in trading through the latter part of the quarter as we enter our peak trading period...
At this early stage in the year, our expectations for FY27 adjusted PBT remain unchanged and broadly in line with FY26. As our plans gather momentum, and with benefits weighted towards the second half of the year, we currently expect adjusted PBT to be lower than the prior year for the first half.
Let's add some context. Adjusted PBT was £114m in H1 last year, and £211m for the full-year (FY June 2026). Peak trading is in Q2.
Graham's view
Roland was neutral on this last month and I'm going to leave that unchanged today.
The stock has suffered from a series of profit warnings, with the most recent one being in September:
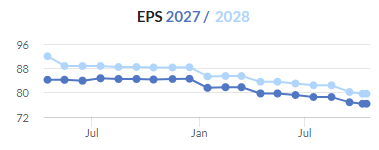
Normally I try to take a positive stance on a stock when it looks like forecasts have stabilised.
However, in the case of Dunelm, the last profit warning was still very recent - only last month. FY27 earnings were supposed to be higher than FY26, prior to that update, and the guidance now is that that they will be "broadly in line".
Perhaps in a less economically sensitive sector, I could take a sunnier outlook. But I tend to think that investors need to be extremely selective when it comes to retailers. And so I'd rather wait until firmer evidence that earnings have bottomed out, before upgrading our stance here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Norcros (LON:NXR)
shoutout to Equity developmnets again for providing an update ref Norcros (LON:NXR) - main takeaway is that reduction in debt seems to be ahead of schedulke reading betwen teh lines.
Whats brilliant about the ED stuff is its full on info up 2029 - gold standard stuff when there is no hiding place with regard to all the numbers
they havent updated all the stuff from today in yet - even with current figures they have debt which started this year at £66 mill coming down to £23 mill by 31/3/2029 - that may go out the window with anotyher acquisition but thast one of the benefits of low pe company if they can make forward progress ref profits. Note there isa few different pe metrics here and recently they have had chunky exceptionals - imho thats stuff all related to moving the business forward rather than puling wool over ones eyes.
Market seems happy with the update today - might not be tomorrow though :)
https://www.equitydevelopment.co.uk/research/strong-execution-and-generating-cash
News on ITV (LON:ITV) which I hold. Lisa Nandy Culture Secretary "inclined to intervene" in deal by ITV to sell part of business to Sky. Daily Mail story in feature on Money.
Journeo (LON:JNEO) Very interesting commentary Mark. However, to me (and I hold) this illustrates relying on AI will often give a wrong/incomplete answer! No reference at all that I can see is made as to the massive increase in the qualified pipeline which I’d have thought pretty fundamental in evaluating forecasts, together with a strong track record.
The problem is we have no sight of that. If you believe that a good chunk of that pipeline will appear in contract RNSes over the next six months, or that most of that will be multiple small orders that won't be RNSed, then you will come to a different conclusion.
I don't think AI is wrong in this case; it gave me what I asked for - what are the known contracts and an estimate of what revenue will land from those in FY27.
The big gap is a risk IMO, but others may be more sanguine given the mention of a large pipeline. As I say, it may be no issue whatsoever, and these contracts may keep arriving; I'll just be eagle-eyed for them over the next few months.
If lots of contracts arrive and they actually upgrade the £ 80m, 33p EPS number for FY27, then they will look undervalued again. However, the current valuation doesn't contain much scope for a miss, and weak halves have been severely punished in the past. So I'm not convinced about the risk-reward at the current price, especially compared to when the P/E was single-digit, and the EPS growth was forecast to be double-digit forward. But then that's what makes a market right, and others see far less risk of contracts arriving in time.
There has been a mid-morning announcement from Smiths News (LON:SNWS) with details of another national contract win.
yes I’m a happy holder of Smiths News (LON:SNWS) . This “cigar butt” stock keeps coming out with positive news. My investment is currently 67% up and I’ve enjoyed some good dividends along the way so I’m happy to continue to hold.
If they can keep winning share in a gradually slowing market then they should be well placed to deliver further growth over the medium term. They should also have strong pricing power as they become the only operator able to provide their services.
Tpximpact Holdings (LON:TPX) outstanding, made share price drop a mockery
Would be helpful to get your view on the latest Gulf Keystone (LON:GKP) news. It appears to be good news, but it is premiere league in the confusing press release tables!
Tpximpact Holdings (LON:TPX) - very good trading update and earlier than expected move to net cash. Cavendish lifts adj. eps for current year by 19% to 9.8p. At present sp up 13% to 91/2 so forward p/e still less than 10.
150 fair value
Any information about Volex (LON:VLX) today?
Nothing on rns or reach.
the pull back likely linked to the US AI sell off as they supply a lot of data centre build outs
Yes I agree - it happened during the last two AI sell-offs even though this is quite a broad based business now.
I'm expecting a trading update tomorrow which could reassure.
Volex (LON:VLX) Is it likely to be connected to down day in us yestteday ref nasdaq i think nvidia was down 3% ? - as ever its only a matter of time before any stock heads back to that green line on the chart - perhaps that green line may provide support? - the momentum numbers on stocky still look sound its had a great run the last 18 months more than doubling in value so no surprise to me there would be some natural pullback when it hits new highs.
<<whispers>> I bought the dip of a few of the shares I hold like this. Don't tell anyone though - Renishaw (LON:RSW) Computacenter (LON:CCC) Volex (LON:VLX)
Yesterday's high CPI number did cause some equity weakness but perhaps not the reaction some would expect .... US yields remain below highs and MOVE at 99 is lower than a week or so ago. So although CPI is uncomfortably high I don't think it's any great shock and expected inflation - the difference between conventional bonds and TIPS in the US remains anchored at 2.23-2-32% ....so the one asset designed to benefit from rising inflation is doing very little. This says to me the market is happy to look through the Oil and Energy shock ....probably because Oil future curves point back down. Will this transpire ? that's the call but the market is behaving quite sticky...ie staying higher. In theory bad for bonds yet it was equities that reacted badly .... I assume because of the implication for rate rises.....higher CPI = more rate rises....apparently. If all this sounds confusing, it is a little.... but the net net is the market is desperate for rate cuts not rises and this suggests to me! we are running out of runway .... so be careful but don't panic because strong evidence of a slow down isn't there yet.
Missed out in the table above... System1 (LON:SYS1)
Buried in their latest rejection of BBSN's final offer...
There was a profit upgrade by management. They expect PBT to be +19% higher for FY Mar27. A very nice meaningful upgrade, based off the back of a full recovery of trading (impacted by USA tariffs last year) and continued growth momentum.
Shares have not moved this morning.
I expect Lord Ashcroft (largest shareholder in BBSN and large shareholder in SYS1) to continue hoovering up shares. He has bought 15% of System1 since the takeover offer, and latest buy of £2.5m at 360p (current share price) and this is before the latest trading update. So there is quite some bid price floor here.
(I hold in the Boon Fund)
The profits upgrade was announced on 24/9/26, the announcement today just reiterates this.
Ah! You're right. My bad on this. Scanned through the announcement too quickly and mis-interpreted that management was upgrading forecasts further to the 5 month trading update....
Morning Graham,
Both Jupiter Fund Management (LON:JUP) and Journeo (LON:JNEO) made it into my NAPS portfolio this year, so any commentary you can offer on those will be much appreciated.
Thanks!
Now I pay closer attention to the Journeo (LON:JNEO) RNS myself I can see it's a framework agreement with TFL, not a results announcement. So, it's positive news, but probably not worthy of much comment...
Mark and I covered both of them, Richard! Thanks. G
Thank you! Much appreciated.
Norcros (LON:NXR)
On track update today - very anemic figures today but the key is that they are on target to hit forecasts . Overall they are making small progress each year on average probably mostly due to acquisitions. Good news is that in a quiet year with no acquisitions they should be making good progress paying down debt - overall I think they have done a good job moving from stuff that is more hard work to stuff that is less hard work - out with the tiles and in the panels - replace south Africa with Europe. Still ongoing stuff to sort ref as but hopefully they are reasonably fighting fit and the pension scheme liabilities are on average decreasing each year.
Hi Graham, can you include Seraphim Space Investment Trust (LON:SSIT) report out today. Thanks
That's done! Cheers.
Good performance and with post year end actions looks like NAV in the mid 260p's. Probably be some discussion on the Investment Trust October discussion board.
thanks Charles - would it be possible to get a link to this ?
SSIT have a meeting at 11:00 AM on the Investor Meet Company platform.
Trust board here
thanks very much
Whilst the result headlines read well nothing quite matches the hype around the fund raise, the price of the ord and the C have failed to keep pace with that hype.... which "may" be the opportunity.... the discount of the C whilst quite predictable isn t a great omen here.... and todays results don't look any better than expected - even though rather spectacular.