THG: shares jump 17% on a 1.3% EBITDA upgrade, and we turn negative

Analyst’s view:
I can only assume most investors have forgotten how to scroll and only read the headline, as a 17% rise in share price looks incongruent with a 1.3% EBITDA upgrade, and one that appears to be less than what we should expect from lower whey prices alone. This still seems a remarkable market cap for a company that has never made an accounting profit, never paid a dividend and has £0.5bn of debt (including leases). Graham upgraded this to AMBER/RED last August, expecting the sale of Claremont Ingredients to rebuild the balance sheet. Since it doesn't appear to have done that, I'm taking this back down.
Up 17% at 32p (£467m) - Q3 2026 Trading Statement
From the title of the RNS, THG management appears to be excited by these results:
Strong profitability momentum drives upgrade of FY26 Adjusted EBITDA expectations to £103m
However, a quick look at the details leaves a far less-favourable impression:
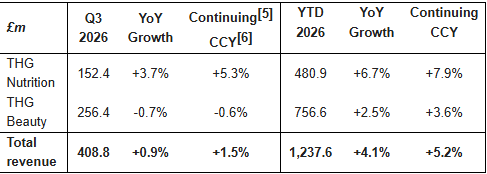
THG Beauty seems to be continuing CCY revenue decline in absolute terms, not just after inflation. THG Nutrition had a much better quarter; however, one that grew below recent trends from H1. Myprotein continues to do the heavy lifting (as do presumably the consumers of this product!) But it is the drop in whey prices that really makes a difference:
Improving whey commodity pricing: WPC80 prices continue to decline through September and early October, as supply increases and growing product substitution, with the external index falling c.20% since the Group’s Interim Results. Q4 requirements have been secured at more favourable pricing than Q3, while Q1 2027 coverage is now being secured below prevailing market rates.
Doing a few quick estimates:
- Whey-based powders are still the core of Myprotein, but a growing share of sales is creatine, activewear, hydration and licensing. Assuming Nutrition’s cost of goods is about £400m and whey is 40–50% of it, THG buys about £150–200m of whey a year.
- A 20% drop in price for Q4 would £7.5-£10m gross savings, perhaps £3-6m net EBITDA gain as some of that is passed through to customers.
So, all things being equal, we can expect this factor alone to have added at least £3m to EBITDA, and to be behind some of today's upgrade. So how big was it?
After much scrolling, I get to:
Consensus being revenue £1,802.2m, Adjusted EBITDA £101.7m
So this turns out to be only a £1.3m EBITDA upgrade, i.e. 1.3%, and below what we should probably expect from the benefit of lower whey prices alone.
This minor upgrade is nowhere near enough to bring the company to profitability based on current forecasts.
Mark’s view
I can only assume most investors have forgotten how to scroll and only read the headline, which seems to bear little resemblance to the actual figures released, as the share price is up 17% today.
This still seems a remarkable market cap for a company that has never made an accounting profit, never paid a dividend and has £0.5bn of debt (including leases).
Graham upgraded this to AMBER/RED last August, expecting the sale of Claremont Ingredients to rebuild the balance sheet. Since it doesn't appear to have done that, I'm taking this back down to RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on THG (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?