Premier Miton: outflows continue as assets fall to £8.1bn

Analyst’s view:
Another quarter of outflows, mean that AuM at the year end come in below broker's forecasts. I can't see any updated numbers today, and one quarter doesn't have a huge impact. However, the most likely outcome is a small miss for FY26. The bigger issue is FY27 where the broker's AuM assumptions (and hence revenue forecasts) now look unrealistic. Offsetting this is a new cost-cutting exercise which may save the bottom line. However, it's hard to consider this company an investment until the numbers clearly show outflows have become inflows again. Until then, I'll keep my previously broad negative view.
Down 6% at 32p (£m) - Q4 AuM update
This is another weak quarter for this asset manager. Pretty much all their strategies saw outflows and negative performance:
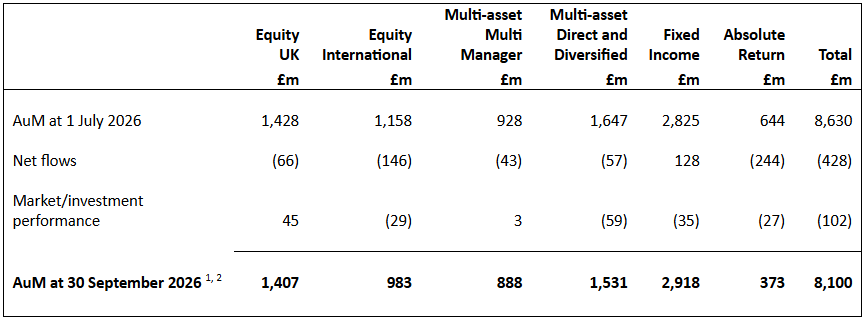
Although, interstingly UK equities is a bright spot (well, less-dim-than-the-others spot, to be precise).
The company says that:
Improving investment performance and lower redemption levels provide a more encouraging backdrop for flows
However, these numbers don't show much of that. A simple trend line suggests that, if anything, outflows are increasing:
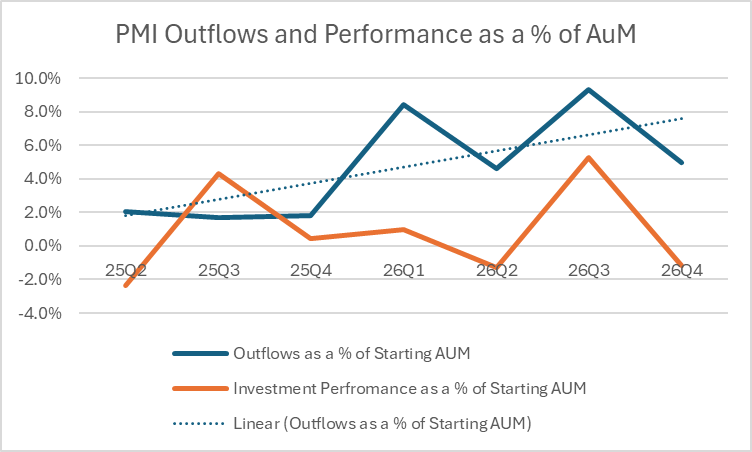
The improvement seems to be limited to the month of September:
Following the elevated outflows in July and August, net outflows reduced significantly in September as redemption levels materially reduced across several strategies, while fixed income and macro thematic multi-asset funds continued to see good demand.
So that may be a sign of things bottoming. It's hard to tell from a single month.
There seems to be a recognition that performance in certain strategies is a problem:
However, there are areas where further progress is required. We continue to focus on improving shorter-term performance across our diversified multi-asset strategies. Absolute return has also experienced a challenging period for performance, reflecting a difficult backdrop for long-short strategies. More recent investment performance has been stable, and we retain confidence in the team and its ability to deliver the investment outcomes required to support greater stability in assets.
Like many companies in a similar situation, an increased focus on cost-cutting may be the only short-term lever they have:
Following a review over the summer, we have identified a further £1.5 million of annualised cost savings which are expected to be delivered over the next 12 months with an estimated one-off cost of £0.3 million.
This is a quick payback and looks necessary, so it is good that they are grasping the nettle.
Forecasts:
I can't see any updated coverage from Cavendish. But their £50.3m revenue and 3p of EPS were based on £8.6bn of AuM. One quarter alone doesn't make much of an impact, but with AuM ending at £8.1bn, it suggests they may miss slightly.
The impact on FY27E looks the most severe, as ending next year with £9.6bn in AuM now looks like a heroic assumption. The £49.3m revenue currently forecast (presumably due to pressure on fees) and hence the 3.2p forecast look unrealistic, although that £1.5m of cost-savings may help, as it would be around a quarter of PBT as things stand.
Cash:
It is better news on cash flow as they say this stands at £26m, which is up from the £24.6m at the year end, despite a £2.4m dividend paid in the period.
This is half the current market cap. However, some of this will be required for regulatory capital. The requirement stood at £13.4m at the half-year, and they wouldn't want to get too close to that, so we can assume around £10m is genuinely free cash that could be used for acquisitions or similar. They do say:
Our strong balance sheet and position as a listed business provide us with strategic and financial flexibility to pursue inorganic opportunities that can add scale, enhance our investment capabilities and broaden our access to attractive client segments.
The market has liked it recently when companies such as Liontrust have done small bolt-ons, adding more to the market cap than teh companies have spent.
Valuation:
It is perhaps unsurprising that the market hasn't liked this update this morning.
Without updates from their broker, it is hard to arrive at an accurate valuation multiple. If I assume, say, a 10% miss on FY26/27 EPS, then we get something like an 11x P/E falling to 10x for FY27. This would be closer to 8 if we adjust for free cash.
Cavendish are forecasting 3p dividend for this year from an additional 1.5p final dividend beofre this being cut to 2.4p for the full year next year. This is still a pretty decent yield of 10%->8%. However, if this ends up uncovered, the company may cut it further in the short term.
This doesn't make the company expensive, and there is the chance of cost-cutting improving some of these estimates.
Mark's View
The multiples here aren't demanding, especially if investors think the cyclical downturn in smaller active asset managers is about to turn.
However, there is no sign of slowing outflows in the recent quarterly numbers, and the company doesn't stand out as particularly cheap in the sector. Something the middling Value Rank picks out:
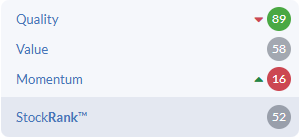
The very low Momentum Rank should also give us pause (although the example of recruiters recently shows that this figure can change rapidly if the share price starts rising).
It's hard to consider this company an investment until the numbers clearly show outflows have become inflows again. Until then, I'll keep my previously broad negative view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Premier Miton (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?