TPX Impact: first-half revenue up at least 57%, and the shares still look good value
Analyst’s view:
This is a decent upgrade, with Cavendish increasing FY27 EPS estimates by 18%, and year-end net cash by £4.1m. However, FY28E EPS is only increased by 10% and given the recent share price strength the forward multiples are higher than they have been in the recent past. However, the company remains modestly valued on a absolute basis and continues to trade at a discount to listed peers on forward multiples. Plus, there are signs that they may still be guiding investors conservatively given the strength of H1 and the typical H2-weighting. The major risk remains that these positive trends are less to do with company execution and more to do with a favourable backdrop, and this could change. However, with no sign of this in today's update, I keep our positive view.
Up 13% at 91p (£77.2m) - First Half Trading Update
TPX Impact continues to compound my error in selling when the share price rose 40% on an in-line trading statement accompanying their interim results last December. The rise itself seemed excessive. However, I missed that it marked a turning point for both trading momentum and the market's perception of the company, shifting from one that misses expectations to one that hits or exceeds them.
As I wrote recently when reviewing competitor MadeTech, companies in this space find themselves at the confluence of three positive factors:
Drive to improve public sector efficiency: IT projects are seen as a key pillar of that aim.
Catch-up from the delayed Spending Review: This created a long freeze followed by a release of pent-up demand.
Shift to SMEs: This deliberate policy shift structurally favours firms exactly like TPX and Made Tech that are digital-native, agile-delivery consultancies built to sell into frameworks.
This positive momentum shows no sign of slowing down as of today, TPX say; their H1 delivered:
- Revenue of at least £57.0m (H1 FY26: £36.2m), representing at least 57% year-on-year growth;
- Adjusted EBITDA* of at least £7.5m (H1 FY26: £3.2m), representing at least 134% year-on-year growth;
I'm not really a fan of Adj. EBITDA as a metric, but there are signs that this is turning into cash:
Strengthened balance sheet with net cash as at 30 September 2026 of £1.0m (vs FY27 opening position of £4.2m net debt) - a significant acceleration against the previous guidance of eliminating net debt by the end of FY27.
Given this strength, it is perhaps unsurprising that they up their FY guidance:
- Revenue of at least £105m (previous guidance was for healthy double-digit revenue growth year-on-year)
- Adjusted EBITDA* of at least £14m (previous guidance was for adjusted EBITDA of not less than £12m)
This is a 17% upgrade to adjusted EBITDA, so it is a reasonable increase. They also appear to have delivered 54% of revenue and EBITDA guidance in H1. Historically, TPX has had a H2 Weighting, but since much of its delivery is project work subject to revenue-recognition timing, this doesn't automatically mean it's on for another beat. However, it does suggest they may still be guiding conservatively if past trends hold.
Cavendish upgrades their FY27E Adj. EPS figure from 8.3p to 9.8p, a 19% upgrade. They helpfully give a summary table of all of their recent forecast changes:
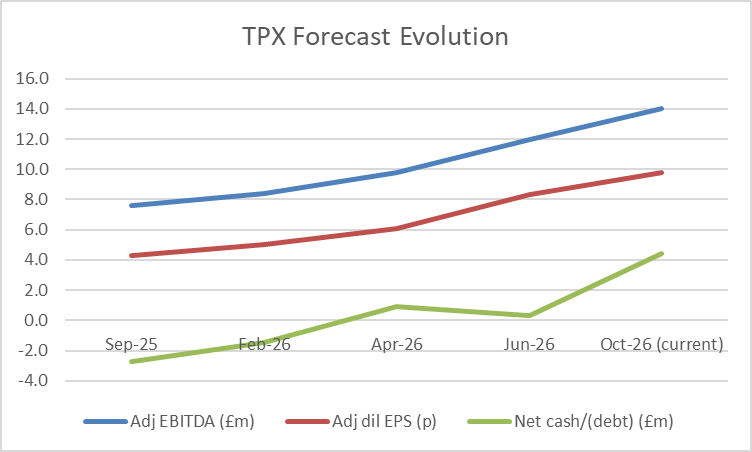
EPS has more than doubled in this time.
However, it is worth noting that the rating the shared trade on has increased over this time, too:
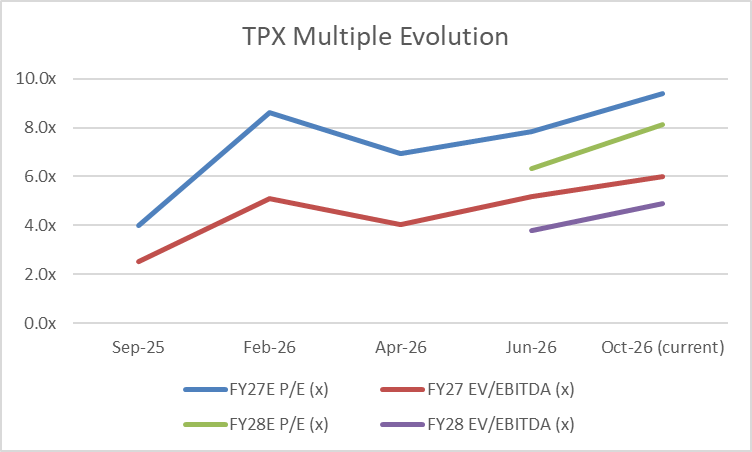
The shares were incredibly cheap at the end of 2025, and while a forward EV/EBITDA of 6 for a company performing this strongly still seems good value, it is not quite the bargain it once was.
This effect is seen more strongly in the FY28 numbers, where forecasts were only introduced in June. FY28E EPS was only increased by 9.7% to 11.3p today. The FY28 P/E goes from 6.3x in June to 8.1x today. Again, not expensive, but this assumes that the current business momentum continues into FY29 and beyond to continue to look cheap.
Mark's View
With the share price today rising roughly in line with the average upgrades to future years, the shares stay on roughly the same multiples. Share price strength over the summer means that the multiple has expanded and this is no longer as cheap as it once was.
However, strong H1 trading and a typical H2 weighting mean the company may still be guiding investors conservatively. On an absolute basis, the stock continues to look like good value.
The biggest risk remains that the current trading strength has less to do with company-level execution and more with recent industry trends that are "floating all boats". This means that if the tide of favourable conditions starts to go out, they may be left high and dry where they started. After all, the company had been loss-making for the last four years.
As today's update shows, there appears to be no sign of that tide reversing in the near term, and the company is cheaper than competitor Madetech on forward metrics, so we should remain positive. GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Tpximpact Holdings (3)
Comments here are also visible in the Daily Stock Market Report
Tpximpact Holdings (LON:TPX) outstanding, made share price drop a mockery
Tpximpact Holdings (LON:TPX) - very good trading update and earlier than expected move to net cash. Cavendish lifts adj. eps for current year by 19% to 9.8p. At present sp up 13% to 91/2 so forward p/e still less than 10.
150 fair value