Dusk - Is it a Buffett worthy stock

By: Chris Batchelor
My last two blog posts have focused on stocks that meet the criteria for the screen developed by Stockopedia contributor Roland Head, as outlined in his recent article titled “Screening for Warren Buffett stocks: the ultimate strategy?”, Roland created a screen that he believes would closely mimic the approach Warren Buffett uses to choose stocks that are likely to be great compounders. When that screen is applied to the Australian and New Zealand market today, only 10 stocks make the cut. So far I have written about Universal Store Holdings (ASX:UNI) (read here) and NZE listed Mainfreight (NZE:MFT) (read here). Today I will take a look at candlestick maker Dusk (ASX:DSK).
Dusk is a retailer of candles and other home fragrance products. They design their own products and sell them through their network of stores as well as online. They are not sold through other stores or market places. Candles are their biggest product however 64% of sales come from other products with diffusers and scented consumable refills rapidly catching up to candles.
Dusk underwent an IPO in November 2020. The price soared from $2 to $4 in the first eight months but then began a steady decline. The driver of this initial growth was strong sales during the pandemic which resulted in four trading updates during their first six months as a listed company, each revealing a further improvement in results.
Revenue hit $149 million in 2021. It is anticipated that revenue will be $140 million in 2023, a decline of 6% from the peak, but still 40% higher than in 2020. The pandemic led to a trend where people were spending more money sprucing up their homes. Things have largely normalised now with travel and entertainment now back on the agenda, but Dusk have managed to lock in a large portion of the gains made during that unusual time.
They are continuing to grow their store network which numbered 141 as at December 2022. They opened nine stores in the first half of FY23 and are aiming for six more in the second half. Online sales accelerated during the pandemic to 8.3% of total sales but have now retracted to 5.6%.
Dusk is a profitable business. Profits grew very strongly until 2021. In 2022 they eased back a bit and the first half FY23 results revealed they have come under more pressure this year. Gross margins declined by 1% due to increased promotional intensity and unfavourable currency movements. General overheads, referred to as Cost of Doing Business (CODB) by retailers, rose 16% driven by new store openings, higher wages and inflation. This was distorted somewhat by lower than usual CODB in 1H FY22 when stores in NSW, VIC and QLD were closed for extended periods and staff stood down. Net profit for the half declined by 9.5% to $13.3m but that still represents a very healthy net profit margin of 15.5%.
The downturn in sales continued into the first seven weeks of 2023. The softening macro environment is creating uncertainty, with ‘outside store traffic’ noted to be 6% lower than the previous corresponding period. Don’t forget that the same period last year was when the Omnicron variant of Covid was ripping through the land, so that was a quieter than usual period itself.
The fact that Dusk have managed to maintain strong profit margins despite the cost pressures contributes to their excellent Quality score of 91. The returns on equity and capital are very high and they are being achieved without the use of leverage. The Health Trend, Bankruptcy risk and Earnings Manipulation Risk are all in the green zones.
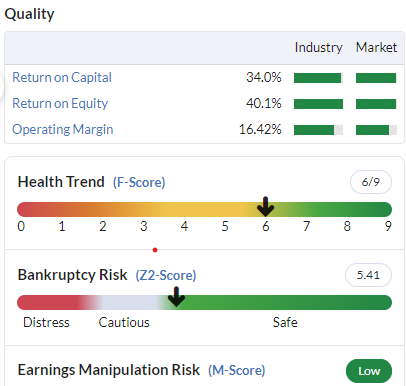
Like most retailers, Dusk receives cash at the point of sales, so sales and profits translate directly into strong cash flow.
They also have a very healthy balance sheet and at the end of December they had cash of $32 million and no bank debt.
In the short term, the current macro environment may see pressure on sales and margins. However we have seen whilst revenue and profits have declined from the bumper levels witnessed during the pandemic, they are still very healthy. Looking to the long term we can try and assess a company’s likely sustainable growth. To do this we focus on retained earnings and a company’s ability to fund long-term growth from retained earnings. Such a business is more likely to have a competitive advantage.
Stockopedia has an Expected Return metric which is calculated by looking at the company's 10 year average ROE and its typical dividend payout ratio. It is then possible to calculate an expected sustainable growth rate, based on retained earnings. Roland Head set a minimum threshold of 6% for this metric in his screen. Dusk’s expected return is 19.8%.
Dusks funds its growth from retained earnings rather than using debt or raising additional equity capital. Shares on issue have remained constant for the last six years and that includes their IPO where existing shareholders sold down their stake but new capital was not raised. The company now has a broad base of shareholders with no one shareholder having more than 5% of the stock.
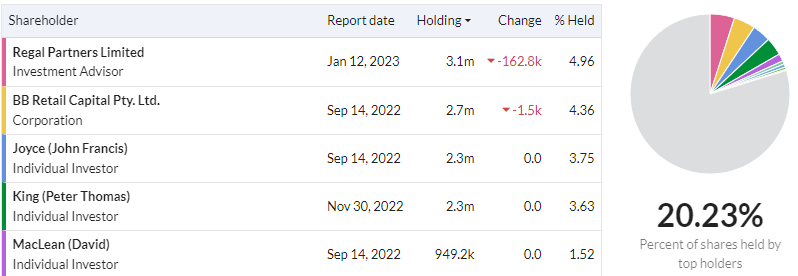
CEO Peter King, has steered the ship since 2014. He has announced his intention to step down in August 2023 and the process to find a replacement is underway.
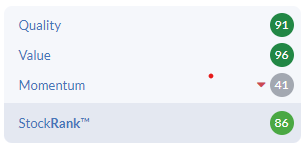
In addition to the high quality score, Dusk represents a strong value opportunity. The forecast PE ratio is only 7.2 and the forecast dividend yield is 9.4%, fully franked. The other value metrics are also strong including Price to Free Cash flow and EV to EBITDA.
The overall StockRank is pulled down by the Momentum Rank which is clearly suffering from the declining earnings and falling share price resulting in the price trading near 52 week lows.
Dusk is currently classed as a Contrarian stock. This means that an investor needs to be mindful of the near term headwinds, but for those who see a bright future on the other side of those then dusk may represent a sweet smelling value opportunity.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
9 comments
Great article Chris.
My concerns with DUSK are:
1. It broke below a support level about a week ago
2. Long term CEO resigned in Jan this year (he listed the company)
Fundementals all look GOOD, however DSK has not been listed long and we have no idea of the resilience (obviously CEO didn't demonstrate much ). The stores look great adn I always see people in there, it is an ideal destination for mothersday.
I like the GP>60%. Even though we all know scented candles are expensive, we still buy them!!!
I will wait for a. trading update, no points in trying to pick the bottom, I would like to see it above it's 50dma at least...
As for the comments on discretionary businesses, don't forget BRK legendary purchase of Sees Candy!!!
Hi Evan,
Both very valid concerns regarding the trend and CEO retiring as pointed out in this morning's Momentum Monday article. I too would prefer to see positive momentum... But I suppose it is often hard to find value once a price has gone up 100% - so absolute conviction is needed at this point.
Thank goodness this is not investment advice. Making candles you have to be joking. By the way Tesla has $23 billion in cash, no debt and it costs them $2 billion to make a Giga Factory. Candles?
Suggest it’s click bate to use the Buffet name. But if you do research on Mr Buffet you will find he claims his best year was 1954, the same year it look for the US market to return to the level it was in 1929. He also suggests that $1 he made in 1954 is now worth 6 cents. Click bate.
Expected Return metric; and expected sustainable growth rate; with Dusk’s expected return is 19.8%; are mentioned. I am having trouble finding these on the DSK stock report,,, are they there?
Great question. It is a very specific "Buffettology" calculation and because of that specificness it is off the main playing field. You will find it as a Screener criteria and as a column you can display in a folio.
Here is some more info onit. https://www.stockopedia.com/ra...
No, as per my study of Graham and Buffett he would not have invested in candles.
Buffett is quite strict about investing in things that humans "NEED" ( my interpretation of this is that things that people cannot forgo and need during crisis as well ) . Candles would be clearly discretionary. However, the business is simple and may meet manyr criterias of Buffettology.
Good point.
But while I am unable to speak for the great men themselves (either Ben, Warren or Chris) I will point to this article where there are some examples which would not have met the brief of what I would view as a Buffett/Graham stock.
There is a history of counter buffett-isms in action... NetJets for example is owned by Berkshire Hathaway. They are a fractional Private Jet company, where clients buy a fraction of a Jet, for use when they need it. If that is not the tip of Discretionary, I don't know what is...
Warren once said, "buy the commodity, sell the brand." While some may point to candle wax as being on a limited time frame, it "could" evolve in time, provided they have the right management team. And hence why Chris pointed to the fact that Peter King will be leaving the business. Who his replacement is will govern much of its Buffett status as any.
Yes, that would be a contradiction, it may be so cheap or some economic position ( just my assumption) they may have overwritten their own rules. I think Mr Buffett argued he does not like airlines as they are too capital-intensive. They also highly prioritise the economic position of the company. They invest in great businesses that they think will be great businesses in say 10 years as well. I think the abovementioned businesses are great prospects for buyouts as well.
The economic position of UNI is supported by both wealthy parents and the Australian economy's high minimum wage ( for young workers). Definitely young, dumb and "not broke". Unfortunately for me, the stock is not provided by my CFD provider, else would have owned it.
Those points are excellent!