Essentra: like-for-like revenue up 10.8%, but 16x earnings keeps us neutral

Analyst’s view:
I think there is an argument to be made that earnings here are on a recovery trajectory, driven by cost-cutting and delays in passing on inflationary cost rises to customers. However, I struggle to get behind a 16x forward earnings multiple, even if earnings are forecast to grow in future years, when these are heavily adjusted, and there is reasonable net debt to factor into any valuation. The middling Stock Rank confirms that we should probably stick with a neutral view.
Up 6% to 120p (£320m) - Q3 2026 Trading Update
These are decent revenue growth rates for Q3:
Essentra delivered strong Q3 revenue growth, supported by increased volumes and disciplined pricing. Revenue increased by 14.6% at constant currency on a working day adjusted basis, comprising like-for-like revenue growth of 10.8% and a 3.8% contribution from the acquisitions of Device Technologies and Boteco.
Acquisitions have played their part, but almost 11% LFL revenue growth remains strong in the current global macro environment. This has led to:
The Group's underlying performance continues to improve, and revenue growth for the full year is now expected to exceed previous guidance, reflecting increased volume growth and disciplined pricing actions, which are expected to recover elevated inflationary costs.
It seems cost-cutting and price increases are playing their part:
Execution of the Growth and Simplification programme, as outlined at Essentra's HY26 results in July, continues to sharpen the Group's commercial focus and is beginning to deliver results.
This may make this growth less sustainable than pure volume growth, although you sometimes get a lag effect where inflationary price increases lag costs and lead to gains once inflation subsides.
It hasn't all been plain sailing, as these pressures have led to some significant downgrades at the end of last year, and recent performance strength hasn't yet recovered from this:
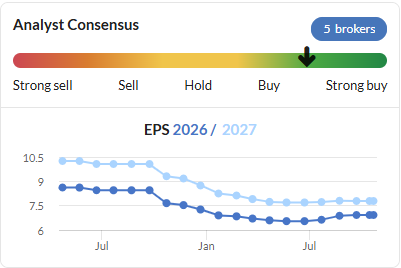
The helpfully quantify the range of forecasts:
The Company-compiled range of market expectations for FY26 adjusted operating profit, as at 21 October 2026, is £32.3m to £34.3m.
But this is a tight range, so the shift from the middle to the upper end of forecasts is just a 3% upgrade. Assuming this feeds into a similar EPS rise, the FY26 consensus will still be 15% below where it was when the downgrades began last year. The share price is 20% higher than then, making it look about 30% more expensive.
Adding to the feeling that the rating may have got ahead of itself is a quick look at the half-year results, which show some fairly chunky adjustments required to hit the numbers:
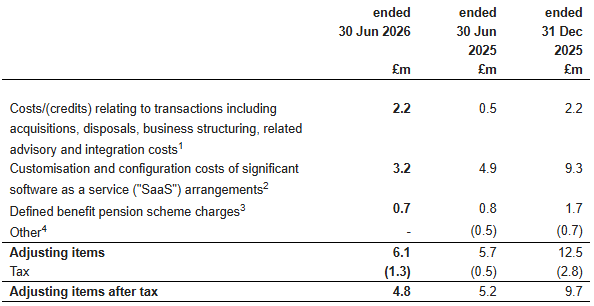
None of these I personally consider exceptional, and it is perhaps easy to be trading at the upper end of expectations if you choose to exclude some key costs that appear to be ongoing.
Then the Half Year results reveal that the company has net debt:
Net debt of £70.7m excluding IFRS16 lease liabilities (30 June 2025 £68.7m), representing leverage of 1.6x adjusted EBITDA following the completion of the acquisition of Boteco
While 1.6x leverage isn't high enough to worry about solvency, it should make us adjust down the earnings multiple we are willing to pay. A TTM EV/EBITDA of 10 doesn't scream value in the current UK markets.

Mark's view
I think there is an argument to be made that earnings here are on a recovery trajectory, driven by cost-cutting and delays in passing on inflationary cost rises to customers. However, I struggle to get behind a 16x forward earnings multiple, even if earnings are forecast to grow in future years, when earnings are heavily adjusted, and there is reasonable net debt to factor into any valuation.
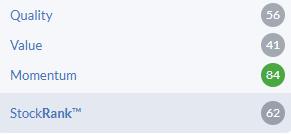
Roland called this AMBER after the H1 results in the summer, and the middling Stock Rank suggests I should stick with this view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Essentra (1)
Comments here are also visible in the Daily Stock Market Report
Graham, can you please have a look at Essentra (LON:ESNT) as I believe the turnaround is in full swing here and significant upside to be realized. I hold.