Focusrite share price up 7% as marketing strategy in tune with customers

Analyst’s view:
I'm comfortable raising our stance on this by one notch today. There are plenty of positives to consider: stable/rising earnings forecasts in recent months, good cash flow performance leading to debt reduction, and a successful route-to-market strategy raising margins. The valuation remains modest with a PE ratio of 10x, and the StockReport likes it too, calling it a Super Stock.
Up 7.3% at 235p (£139m) - Interim Results
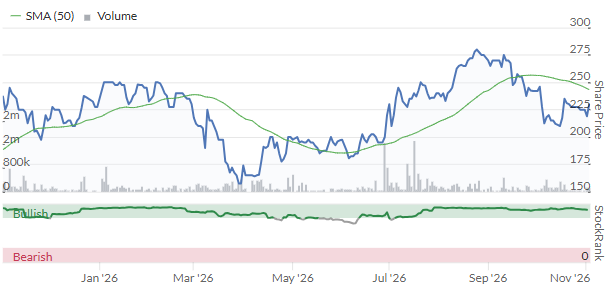
We've been fairly cautious on this stock in 2026. See my comments in March (share price at the time: 195p) and Roland in June (at 200p).
The share price is firmly within its range for the year:
What bothered me back in March was that FY February 2027 estimates seemed to be under pressure. This was borne out with some weakness in the chart below (dark blue line):
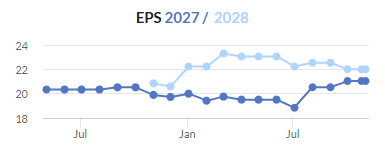
The chart also shows forecasts recovering in more recent months, so perhaps we can start to look at this one a touch more optimistically?
What it does:
Content Creation - audio interfaces and other products for music studios.
Audio Reproduction - live sound and permanent installations.
Here are some of the highlights from today's interim results:
Revenue +2.7% at slightly higher gross margin (46.6% vs. 44.9% last year)
Adjusted EBITDA up 10.9% to £15.8m
Operating profit +67.6% to £10.9m
Adjustments are reassuringly low, with barely any gap between statutory operating profit (£10.9m) and the adjusted figure (£11.1m).
Net debt has shrunk considerably, from £10.9m a year previously to only £1.5m this time.
Outlook: confident in meeting market expectations for FY February 2027, with these expectations being revenue of £170.1m to £173.7m and adjusted EBITDA of £25.2m to £27.4m:
As previously indicated, revenue and profitability are expected to be more heavily weighted towards the first half of the financial year, reflecting the phasing of sales into distribution channels ahead of the winter holiday season.
The company has already generated 52% of full-year revenue expectations, backing up the company's statement that there is an H1-weighting.
Remember that the company itself chose this. Back in October 2024, they announced the change in accounting reference date, so that the year-end would be in February rather than August. This would "align better with industry cycles, especially around the key holiday season sales".
I do find this a little curious. Many consumer-facing companies choose to arrange their year-end so that they have a quieter H1 and then a heavier H2. Focusrite, on the other hand, appears to have set itself up to have a heavier H1 and then a quieter H2. There's nothing inherently wrong with that, and they're entitled to have whatever year-end they choose - but I can't shrug off the sense that most changes of accounting year-end dates are totally unnecessary.
Let's move on to focus on a few more elements of this interim report.
Revenue by division
Content Creation grew 5.2%, led by strong growth in the EMEA and APAC regions.
"Our leading brands topped sales rankings with the largest retailers in our industry while our challenger brands continued to gain share and momentum. "
They are moving "ever closer to our end users", having previously started selling directly to resellers, which is said to be improving product margins.
Audio Reproduction shrank by 4%:
Audio Reproduction is a project-based business, with a pipeline and order book extending six to 24 months forward. As previously reported, the market has continued to normalise following a period of exceptional post COVID driven demand in 2024. Industry data indicates that the market declined by a mid-to-high single-digit percentage over the past 12 months. However, there are signs of an improving outlook, with growth expected to return within the next six to 12 months.
Balance sheet: some tangible support here, with the balance sheet having a net asset value of around £45m even after excluding goodwill and other intangibles.
Cash flow: strong cash performance in the period, in my view. £5.6m of capitalised R&D cash costs (benefiting profitability) are offset by a £5.5m non-cash amortisation charge (hurting profitability). The company calculates an adjusted free cash flow of nearly £8m which sounds about right to me. Loans and borrowings were reduced by nearly £5m, while the gross cash pile grew to £23m.
Estimates: Cavendish leave their forecasts unchanged today, including an adj. EPS forecast of 17.8p this year (FY Feb 2027) and 22.7p next year.
Graham's view
I'm comfortable raising our stance on this by one notch today.
There are plenty of positives to consider:
Stable/rising earnings forecasts in recent months
Good cash flow performance leading to debt reduction
Successful route-to-market strategy raising margins
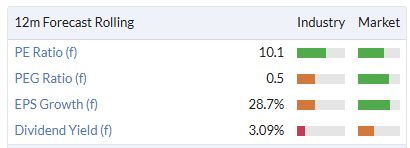
The valuation remains modest with a PE ratio of 10x:
The StockReport likes it too, calling it a Super Stock:
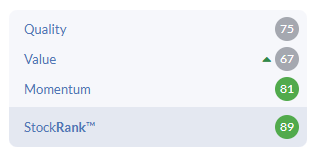
I'm not quite as enthusiastic as that, but I do think that a moderately positive stance makes sense for us now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Focusrite (4)
Comments here are also visible in the Daily Stock Market Report
Graham, you didn’t mention their custom silicon chip (FAESIC) is now in production , with the first product incorporating this new tech is expected to ship in early 2027. Gibberish to me I’m afraid, but is it meaningful?
good question Crusty. I'd prefer not to speculate on things I don't understand!
Could people on these discussions please say which share they are talking about otherwise it is utterly frustrating for the rest of us.
In this case I presume it is Focusrite (LON:TUNE) because I hold and so know it is bringing out its own silicon chip.
For those who want to know more about that chip we have been told that a lot will be said about it on the Capital Markets Day 25/11/26
I think this may be a result of how the new report is structured with the individual companies having their own analysis page. So, if the comment above was made on the Focusrite (LON:TUNE) page then it's obvious which company it relates to but not so clear when the comment is added to the overall daily report page.