Daily Stock Market Report (Tue 3rd Nov 2026) - LIKE, GATC, TUNE, TCAP

US midterm elections are happening today with Americans voting for the House of Representatives, the Senate, and governorships.
About $12 billion has been invested in the campaign, including $450m by Elon Musk in support of the Republican Party.
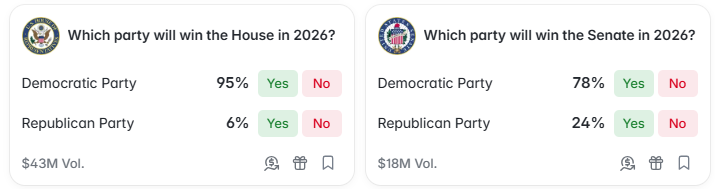
While both parties have spent heavily, there is good reason for heavy Republican spending on this election. With voters disenchanted by inflation - inflation that can be traced back to decisions on tariffs and Iran - there is every chance that voters will hand control of both the House and Senate back to the Democrats.
The Wall Street Journal puts President Trump’s approval rating at 40%, only a little higher than his recent record low of 37%. So if voters treat these elections as a referendum on Trump, the Democrats should be confident of victory. Here are the latest odds on Polymarket:
Overnight market movements:
The FTSE is down 0.6% at 10,705
S&P 500 is down 0.4% at 7,520
Brent crude (January) is up 2.2% at $107.10/bbl
Gold is down 0.9% at $3,910/oz
Bitcoin is down 0.4% at $76,400
Roland Head joins me today.
Leaving it there for today, thanks everyone!
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Coca-Cola Europacific Partners (LON:CCEP) (£38bn | SR85) | FY26 guidance reaffirmed. “Outlook for FY26 unchanged & reflects our current assessment of market conditions.” Revenue growth of 3% to 4%, operating profit growth of 7%. | ||
Hiscox (LON:HSX) (£6.0bn | SR65) | Nine months: insurance contract written premiums grew 9.5%. Loss experience was within expectations for the quarter. On track to deliver 9% constant currency growth for the full-year. | ||
ConvaTec (LON:CTEC) (£4.7bn | SR46) | New CFO will start on 1st March 2027. Was most recently CFO of Fortrea, a US-listed global contract research organisation. | ||
Drax (LON:DRX) (£2.7bn | SR95) | Signed an agreement to develop a strategic partnership with Brookfield to jointly develop, deliver and operate a >1GW AI data centre on the Drax Power Station estate in the north of England. | ||
TP Icap (LON:TCAP) (£2.3bn | SR88) | The Board remains comfortable with full year 2026 market expectations for adjusted EBIT, subject to foreign exchange movements. Group year-to-date growth of 9% at constant currencies. | GREEN= (Graham) | |
International Workplace (LON:IWG) (£1.84bn | SR22) | Quarterly system-wide revenue of $1.26bn, growth of 12% year-on-year, representing over $5bn on an annualised run-rate basis. 2026 Adjusted EBITDA range of $585m-$625m tightened, with expectation to trade above current consensus of $599m. Leverage to be slightly elevated compared to Dec 2025. | ||
Supermarket Income REIT (LON:SUPR) (£1.15bn | SR75) | Proposed equity issue to fund transaction pipeline & Retail Offer | £50 million to fund an accretive transaction pipeline. Proceeds will be used for six earnings enhancing transactions, comprising twelve quality assets across convenience stores and supermarkets and a distribution centre. | |
Target Healthcare Reit (LON:THRL) (£742m | SR87) | EPRA Net Tangible Assets per share increased by 0.9% in the quarter to 123.2p (30 June 2026: 122.1p), “reflecting mainly a like-for-like valuation uplift of 0.6% driven primarily by inflation-linked rent reviews”. | ||
ACG Metals (LON:ACG) (£330m | SR29) | ACG to acquire 100% of Blue Moon Norway AS including its 94.52% interest in the construction-stage Nussir copper mine and other Norwegian development interests, for US$220 million in shares. “...a transformational transaction that creates a fast-growing European copper champion with industry-leading free cash flow margins”. | ||
Franchise Brands (LON:FRAN) (£303m | SR69) | “The improved performance of the business through Q3 2026 and the momentum we are building across the Group continues to underpin our confidence that our full-year Adjusted EBITDA performance will be in line with market expectations.” | ||
Allergy Therapeutics (LON:AGY) (£222m | SR6) | “…the challenging financial market conditions in recent years, combined with a limited free float and lack of liquidity of its ordinary shares, has negatively impacted the market capitalisation, which the Directors believe does not accurately reflect the Company’s value.” Intends to continue to explore a primary listing on The Stock Exchange of Hong Kong Limited in due course. | DELISTING | |
Jadestone Energy (LON:JSE) (£213m | SR69) | Following the resumption of production at CWLH, Group production has risen to ~19,000 boepd, with the Stag field remaining offline. 2026 Group production guidance of 16-18,000 boepd is unchanged. | ||
dotDigital (LON:DOTD) (£161m | SR72) | Revenue +8% to £90.9m with ARR +18% to £85.4m. Adj pre-tax profit +2% to £19.4m with adj EPS +3% to 4.94p. Closing cash of £17.1m. FY27 outlook: trading remains in line with expectations. | ||
Likewise (LON:LIKE) (£153m | SR63) | Strong sales momentum has continued with October revenue +36.7%, taking year-to-date sales growth to 22.8%. Integration of Headlam assets is underway. FY26 outlook: 2026 performance to be “materially ahead” of expectations with pre-tax profit of at least £6.0m (previously >£5.0m). | GREEN = (Roland) | |
Focusrite (LON:TUNE) (£130m | SR89) | H1 revenue +2.7% to £90.3m with operating profit +67.6% to £10.9m. Adj EPS +25.5% to 12.8p. Content Creation saw growth, Audio Reproduction remained subdued. FY27 outlook in line with expectations. | AMBER/GREEN ↑ (Graham) | |
Shield Therapeutics (LON:STX) (£59m | SR20) | Q3 net revenue of $11.3m, a 2% increase excluding the previous quarter’s one-off revenue milestone. US ACCRUFeR net revenue +5% to $10.8m, average revenue per prescription +4% to $217. FY26 outlook: the company no longer expects the group to achieve operating profitability in 2026 due primarily to the costs of taking full US control of ACCRUFeR from 1 October. A single-digit US $m loss is now expected for 2026. | PROFIT WARNING | |
Trufin (LON:TRU) (£55m | SR94) | Following a review of the company’s acquisition pipeline and capital requirements, a special dividend of £17.5m (32.48p per share) is planned. Restructuring to reflect the company’s smaller size is also underway, targeting a c.30% reduction in head office costs. | ||
MTI Wireless Edge (LON:MWE) (£52m | SR86) | Israeli MoD has further increased its contract with PSK Wind Technologies to a total value of $8.5m. The previous increase valued the contract at $4.5m in June 2026. | RH note: there’s no reference to any impact on expectations. | |
Gattaca (LON:GATC) (£40m | SR89) | Revenue + 11% to £443.3m with underlying pre-tax profit +85% to £6.1m. Adj EPS +77% to 13.8p. FY27 outlook: expect growth in underlying pre-tax profit to £6.5m, in line with expectations. | GREEN = (Roland) | |
M Winkworth (LON:WINK) (£24m | SR90) | The company and non-exec chair Simon Agace have agreed a consent order that has been sealed by the court. Discussions remain ongoing with a view to reaching a settlement. The stay of proceedings has been extended until 23 Nov 26. | ||
Cadence Minerals (LON:KDNC) (£22m | SR36) | Commissioning completed in 30 days of the 45-day window. Approximately 6,200 wet tonnes of feed processed and approximately 2,800 wet tonnes of concentrate produced: mass recovery (by weight) of approximately 45%. | ||
Celebrus Technologies (LON:CLBS) (£19m | SR47) | Non-executive chairman Tom Skelton will retire on 31 Dec 26. A search is underway for his successor. |
Analyst notes
- Likewise (LON:LIKE)
Likewise: flooring supplier lifts profit guidance by 20% as Headlam assets add scale
Likewise appears to be executing flawlessly and benefiting from the failure of its main competitor. Today's upgrade lifts full-year profit guidance by c.20% with less than two months of the year remaining. Although the valuation looks full, I think this is justified by the current growth trajectory so I'm staying GREEN today.
- Gattaca (LON:GATC)
Gattaca: earnings up 77% as defence and infrastructure drive growth - still too cheap?
Today's results from this STEM specialist recruiter show good growth in Energy, Defence and Infrastructure - perhaps unsurprisingly. With positive momentum, a strong balance sheet and an undemanding valuation, I think it's reasonable to maintain our positive view today.
I'm comfortable raising our stance on this by one notch today. There are plenty of positives to consider: stable/rising earnings forecasts in recent months, good cash flow performance leading to debt reduction, and a successful route-to-market strategy raising margins. The valuation remains modest with a PE ratio of 10x, and the StockReport likes it too, calling it a Super Stock.
My impression is that Q3 growth has perhaps been slightly disappointing. The highest-margin division, Parameta, has seen 5% growth in ARR year-on-year and some observers may have been expecting a little more. It's worth noting in this regard that today's "in line" outlook statement referred only to EBIT, and not to revenue. Overall, for a business with such a fine record of profitability and such strategic importance in global financial markets, I continue to view its valuation (9x earnings) as undemanding.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
13 comments
Graham, you didn’t mention their custom silicon chip (FAESIC) is now in production , with the first product incorporating this new tech is expected to ship in early 2027. Gibberish to me I’m afraid, but is it meaningful?
good question Crusty. I'd prefer not to speculate on things I don't understand!
Could people on these discussions please say which share they are talking about otherwise it is utterly frustrating for the rest of us.
In this case I presume it is Focusrite (LON:TUNE) because I hold and so know it is bringing out its own silicon chip.
For those who want to know more about that chip we have been told that a lot will be said about it on the Capital Markets Day 25/11/26
I think this may be a result of how the new report is structured with the individual companies having their own analysis page. So, if the comment above was made on the Focusrite (LON:TUNE) page then it's obvious which company it relates to but not so clear when the comment is added to the overall daily report page.
Very decent update from Likewise (LON:LIKE) today. Had my eye on them for a while, I just can't pay up for 26 x forward earnings for a floor distributor.
More fool me, probably
$12 billion is an incredible amount. Donors presumably expect something in return, which leads to corruption and degradation of democracy.
I suspect all this spending is why politics is so contentious and bitter in the US.
For comparison the UK spent £97 million in the last general election. Something we can be grateful for.
TP Icap (LON:TCAP)
On track trading update seems fine to me , I bought in a while back due to lowly rating if believed bumper profits promised would materialise plus possibility of selling/floating part of the business.Not an easy company to get a grip on how much transparency they have ref future earning. Seems to be doing ok though even if the possible listing seems to have been ditched for. Current expectations are for increased profits next year too so hopefully they can keep overall positive momentum going.
I have also picked some up recently - in a bid to have some market exposure should the market cycle grind on longer but also potentially a beneficiary from rising Vol. For me, Q3 looks ok but it isn't motoring and obviously $ weakness is not our friend. I guess vol trends have not been unusual so far and investment banks have done quite well but not really down to trading vols. Longer term TP Icap (LON:TCAP) must be an AI victim but in the short term I can't see anyone worrying about that. Main risk for me therefore is US politics and $ hurting before trading strengthens.
Gattaca (LON:GATC) (I hold)
Morning Graham, would you be able to comment on the results from Gattaca please?
Thanks,
Richard
Morning Richard, that's been noted! Cheers.
Last month I commented that the Likewise (LON:LIKE) structural setup had never been stronger and that January’s trading update would be the first meaningful read. Well, a first read arrived this morning….
October revenue rose 36%, taking the YTD to +22%. Profit before tax is now expected to be at least £6m, up from at least £5m five weeks ago and a market forecast of £4m in July. That implies H2 profit of at least £4.7m, roughly double last year’s figure. The operational gearing is starting to show.
Delivery is still what counts, and today’s update doesn’t yet show how much Headlam volume Likewise will keep, but the early evidence is encouraging. I hold.
Thank you Paul for the inspiration to buy
I do find it helpful to summarise my thought process in writing. Always inspiration never advice. Good Hunting. Ian