Gattaca: earnings up 77% as defence and infrastructure drive growth - still too cheap?

Analyst’s view:
Today's results from this STEM specialist recruiter show good growth in Energy, Defence and Infrastructure - perhaps unsurprisingly. With positive momentum, a strong balance sheet and an undemanding valuation, I think it's reasonable to maintain our positive view today.
Up 7.6% to 136p (£43m) - Final Results for the year ended 31 July 2026
Small-cap recruiter Gattaca has outperformed its listed peers over the last couple of years as the company's management have delivered a return to growth despite difficult market conditions for the wider sector:
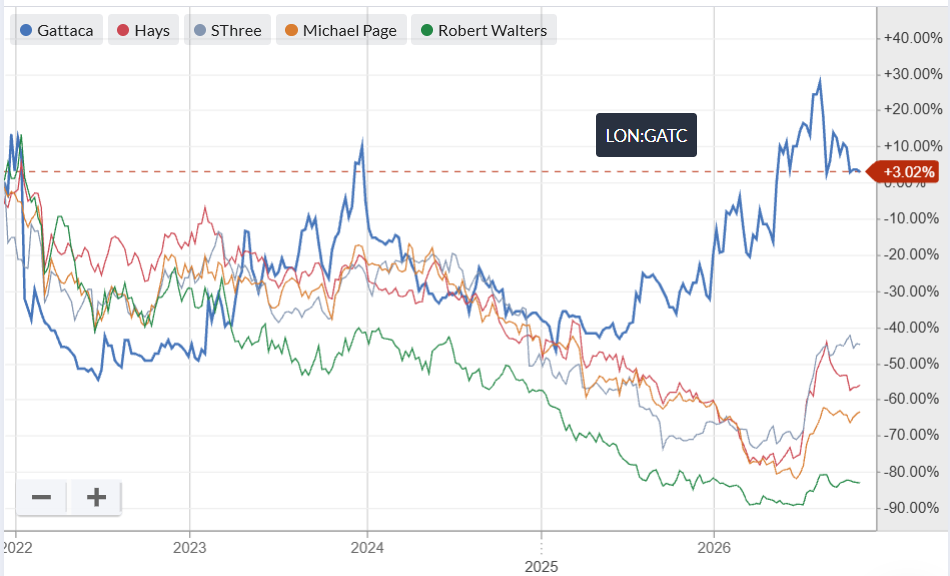
Today's full-year results cover the 12 months to 31 July and confirm that this specialist firm - which focuses on STEM recruitment - is performing well.
FY26 results summary
Today's headline numbers are in line with consensus expectations, benefiting from the contribution from last year's acquisition of InfoSec:
Revenue up 11% to £443.3m
Net fee income (NFI) up 11% to £43.2m
Permanent NFI down 5% like-for-like but up 4% including InfoSec
Contract NFI up 16%
Reported pre-tax profit up 119% to £5.7m
Adjusted earnings per share up 77% to 13.8p
Dividend up 100% to 6.0p per share
Net cash stable at £15.4m (FY25: £15.7m)
Strong cash generation is a hallmark of well-run recruiters and this appears to apply here. I'm happy to see Gattaca's net cash balance remained largely unchanged last year despite in an initial £1.5m outflow on the acquisition of InfoSec and last year's c.£1m dividend payout.
Gattaca's balance sheet appears to remain very strong, providing firepower for growth and supporting an increased dividend.
Sector performance: drilling down further into the company's results suggest that the Energy, Defence and Infrastructure sectors accounted for most of last year's organic growth, perhaps unsurprisingly.
I've used gross profit below as a proxy for net fee income:
Energy up 4.2% to £6.5m
Defence up 17% to £8.6m
Digital Technology up 10% to £3.4m
Infrastructure up 4.7% to £14.6m
Gattaca Projects down 44% to £1.2m
Other (including InfoSec) up 48% to £9.0m
The standout item from this list is probably the slump in Gattaca Projects NFI.
This unit is a mechanical mechanical engineering consultancy with a heavy focus on defence. Last year's fall in fee income occurred when "its largest defence sector client delayed or cancelled projects". Management says this business responded by diversifying its client base and will continue to pursue new growth opportunities.
Outlook
Today's results are in line with expectations and the company's guidance for FY27 is also unchanged.
The Board expects further growth in continuing underlying profit before tax in FY27, in line with current market expectations of £6.5m.
With thanks to broker Panmure Liberum on Research Tree, we can also see that EPS forecasts are unchanged today:
FY27E adj EPS: 14.4p (+6.5% vs FY26 consensus)
FY28E adj EPS: 16.5p (+14.6% vs FY27E)
FY29E adj EPS: 18.2p (+10.3% vs FY28E)
I would treat the outer year forecasts with a degree of caution, but it's clear that Gattaca has decent momentum at the moment.
Roland's view
Last year's results benefited from a prior upgrade to earnings forecasts that was ironically prompted by a slower ramp-up of headcount than originally planned. These extra costs will drop through into FY27 results, perhaps contributing to the more modest rate of growth forecast for this year.
I don't see this as a serious concern, given the continued strength of Gattaca's balance sheet and its undemanding valuation:
FY27E P/E of 9.4
FY27E forecast dividend yield: 5.1%
The caveat to this is my assumption that the recovery in recruitment activity will continue over the next two or three years. In Gattaca's context I think that's a reasonable assumption, but of course it's not guaranteed.
The StockRanks remain positive here, with Super Stock styling and a StockRank of 89 prior to digesting today's figures:
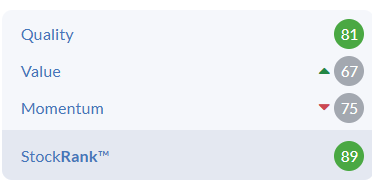
I suspect this factor score may improve after today on the back of Gattaca's improved quality metrics - today's results show return on equity improving to 12.5% (FY25: 6.5%).
We were positive on Gattaca in May and again in August. I'm going to extend that run and leave our GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Gattaca (2)
Comments here are also visible in the Daily Stock Market Report
Gattaca (LON:GATC) (I hold)
Morning Graham, would you be able to comment on the results from Gattaca please?
Thanks,
Richard
Morning Richard, that's been noted! Cheers.