Daily Stock Market Report (Mon 17th August 2026) - TIME, MWE, TEP, GATC, SPR, GMS

Good morning. Expectations for a US rate rise have eased, leaving the dollar weaker after US government data revealed that retail sales fell in July.
Oil prices have edged higher as the US and Israel show signs of stepping up pressure on Iran and Lebanon, respectively, in the Middle East.
Closer to home, Housing Secretary Angela Rayner is expected to announce changes to the UK’s planning system today. These are said to include increasing protection for pubs (from being converted to other uses) and making it easier for housebuilders to build new homes close to existing rail and underground stations.
Many of the UK’s listed housebuilders are trading at intriguing discounts to their book value, as we’ve discussed here a number of times recently. So it will be interesting to see how the market interprets today’s changes – while they may make it easier to secure permission for some new developments, they won’t necessarily do anything to address the pricing and cost pressures that are squeezing builders’ margins.
Overnight market movements:
The FTSE is up 0.2% at 10,776
S&P 500 is up 0.2% at 7,795
Brent crude is down 0.4% at $86.93/bbl
Gold is up 0.3% at $4,395/oz
Bitcoin is up 0.9% at $63,398
Dr James Fox joins me (Roland) today.
Wrapping up there for today, thanks for all your contributions.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£178bn | SR) | Tagrisso plus Orpathys demonstrated statistically significant and clinically meaningful improvements in progression-free and overall survival in MET-driven EGFR-mutated lung cancer after progression on Tagrisso. Separately, the company is discontinuing the eVOLVE-Lung02 Phase III trial after a planned review of trial data suggested the volrustomig combination was unlikely to meet either of the trial’s primary endpoints. | ||
Telecom Plus (LON:TEP) (£667m | SR72) | “Encouraging start” to five-year growth strategy. YTD annualised multiservice customer growth running “slightly ahead of our 10% target” and well ahead of the 3.9% achieved in FY26. FY27 Outlook: full-year guidance reiterated for adj pre-tax profit of £80-90m, with heavier than usual H2 weighting. | AMBER ↑ (Roland) Telecom Plus appears to be making progress on a number of problem areas highlighted in June’s FY26 results. What we don’t know yet is whether costs will also remain in line with expectations. FY27 profit guidance is reiterated today but management warns that there could be an 85% H2 weighting – even heavier than usual (given winter energy demand). I’m willing to turn neutral here, as Telecom Plus has a long and fairly respectable track record (prior to the current stumble) and I’m encouraged by the seeming return to a more active role of Chairman and shareholder Charles Wigoder. However, I’d caution that this remains a Contrarian situation with the possibility of further problems. | |
GCP Infrastructure Investments (LON:GCP) (£643m | SR93) | A loan secured against a portfolio of renewable energy projects in the UK has been repaid in full ahead of its expected June 2035 maturity, following a change of control at the borrower. The value of the repayment is “materially in line with the valuation” incorporated in the June 2026 net asset value. In line with the capital allocation policy, any excess cash will be used for share buybacks. | ||
Thungela Resources (LON:TGA) (£566m | SR76) | H1 revenue +2%, with headline earnings +150% to 480c per share. Dividend increased by 175% to 550c per share. H1 export saleable production +6% to 8.5Mt. 2026 outlook: full-year guidance reaffirmed. | ||
Optima Health (LON:OPT) (£269m | SR71) | Revenue +14.8% to £120.6m with pre-tax profit +11% to £14.2m. Net debt increased to £94.4m following acquisition of PAM Healthcare for £100m. FY27 outlook: the year has started with strong momentum. | ||
Gulf Marine Services (LON:GMS) (£208m | SR66) | An existing small-class vessel contract in the Gulf region has been extended by 183 days with two further three-month extension options thereafter. The current backlog stands at $659m. | AMBER = (Roland) [no section below] This contract extension sounds fairly small, financially, and there is no change to forecasts from broker Zeus today, with FY26E adj EPS pegged at 2.6c and expected to return to 4.2c in 2027 (the same level as 2025). Cuts to guidance and mediocre returns on equity have combined with geopolitical exposure to persuade me to turn neutral here in recent months. It’s also too soon to know whether the company’s decision to invest in additions to its fleet will pay off. The StockRanks see this as a Contrarian play and the discount to book value could be worth investigating. However, I don’t see any tangible reason to change my previous neutral view today. | |
Knights group (LON:KGH) (£154m | SR75) | Knights will acquire Thames Valley firm THP for £4m, with an initial cash payment of £2.4m and the remaining consideration paid over three years. The acquisition will add c.30 fee earners and add exposure in complementary areas such as Private Wealth, Family and Real Estate. | ||
Springfield Properties (LON:SPR) (£129m | SR91) | Land sale in Central Scotland for £12m, equivalent to 170 plots. Full cash consideration was received on completion. £6.5m of proceeds has been used to pay the final consideration for the acquisition of housebuilder Mactaggart & Mickel Group (acq. June 2022). All outstanding consolidation relating to this acquisition has now been satisfied. | GREEN = (Roland) [no section below] Graham upgraded our view on this Scottish housebuilder to GREEN in June and I’m happy to keep it there today. Today’s update shows the company realising value from its landbank and confirms that the balance sheet is now in a net cash position. With a strong pipeline of work for the Scottish renewable energy sector (see my Stock Pitch here) and a c.25% discount to book value, I continue to see value here, despite limited visibility on earnings. | |
Andrada Mining (LON:ATM) (£100m | SR26) | Subsidiary Uis Tin Mining has completed an agreement for a c.£4.4m, 10-year loan facility with local lenders. This is expected to provide funds for the construction and commissioning of the ore-sorting circuit at the Uis Mine, increasing tin output by 50%-70% to approx 2,500-3,000tpa. | ||
InvestAcc (LON:INAC) (£83m | SR8) | Has seen positive performance since announcing FY25 results. 2026 outlook: now expected FY26 revenue and EBITDA to be ahead of current expectations (prev. £25.7m and £9.1m respectively). | ||
First Tin (LON:1SN) (£72m | SR28) | Updated DFS and conceptual Phase 2 mine life extension deliver a combined post-tax NPV8 of A$246m at a spot price of US$40k/t, compared with A$98m in the 2024 DFS. | ||
Dotlines Global (LON:DOTL) (£67m | SR4) | Reports progress at a number of operating units, including a new ISP customer for the Catena software platform and additional customers for the Carnival Internet service. | ||
MTI Wireless Edge (LON:MWE) (£57m | SR90) | H1 revenue +11% to $26.7m with operating profit +21% to $3.0m. Earnings per share +15% to 2.88c, with net cash of $7.7m at 30 June 2026. 2026 outlook: "We have entered the second half well placed to achieve a good result for the year.” | GREEN ↑ (James) A strong first half at the headline level, with revenue up 11% and operating profit up 21%, although the growth came from irrigation and Israeli component distribution rather than the antenna division that carries the defence story, which fell 20% for a second quarter running. Management attributes this to timing, with $6m of orders won in April landing as revenue over the next 18 months. The balance sheet remains in good order with $8.2m of net cash and a 17.5% return on capital. Forecasts have not moved in three months and there’s cause to believe the stock will beat the projected $5m in net profit for the year. Today's fall looks like disappointment at unchanged guidance rather than anything in the numbers, and I have left my positive view unchanged. | |
Gattaca (LON:GATC) (£53m | SR90) | Expects to report FY26 net fee income +11% to £43.2m (+7% LFL). Contract NFI +16% with Permanent LFL NFI -3%. Due to improved productivity per head, now expects to report FY26 underlying pre-tax profit of c.£6.1m (previous guidance: £6.0m). FY27 outlook: expects a further improvement in pre-tax profit. | GREEN = (James) A strong finish to FY26, with underlying pre-tax profit of £6.1m against £3.3m last year on net fee income up 11% to £43.2m. That's operating leverage rather than growth alone – costs rose just 4.5%, and the group managed it with 4% fewer fee earners. The beat against May's guidance was only £0.1m, so there is little here the market hadn't already priced, and the shares have run around 50% since March. Strip out £15m of net cash and they still sit under 9x this year's earnings, which looks good value. My hesitation is cyclical: recruitment gears hard in both directions, this is the best profit in years, and permanent fees are slipping on a like-for-like basis. Enough to keep me positive, but investors need to remain watchful. | |
Time Finance (LON:TIME) (£49m | SR83) | Specialist lending group Bentley Park has made a recommended cash offer of 59.1p per share for TIME, valuing the business at £55.13m. | TAKEOVER (Roland) | |
Batm Advanced Communications (LON:BVC) (£42m | SR61) | General Meeting scheduled for 24 Sept 26 to seek shareholder approval for the sale of three of the Group’s remaining four non-core activities. See 22 June RNS for further details. | ||
Predator Oil & Gas Holdings (LON:PRD) (£29m | SR7) | Rig Contract Executed with Star Valley Drilling for Rig 205 to drill Snowcap-3 in Trinidad | Predator has signed a contract with Star Valley Drilling for Rig 205 to drill the Snowcap-3 well in Trinidad, starting once the MOU-6 well in Morocco is finished so the same management team can supervise each operation in turn. Earlier results indicated that Snowcap-2ST-1, Snowcap-1, and Rochard-1 wells hold a 600-foot column of oil | |
Defence Holdings (LON:ALRT) (£29m | SR3) | Commitment of £2 Million as Cornerstone Investor in UK Defence Fund | Defence Holdings PLC has announced £2m cornerstone commitment to a new UK Defence Fund, an FCA-authorised AIFM-managed vehicle taking minority stakes of £250,000 to £1m in pre-seed and seed defence technology companies. Fundraise closes around end-Q3, funded end-September, with full deployment targeted by March 2027. | |
Atome (LON:ATOM) (£27m | SR N/A) | The ANDE president in post when the January decrees were revoked has resigned. Paraguay’s government has formed a working group to redesign ANDE’s tariff regime, and is creating a new energy ministry and regulator. | ||
Tekmar (LON:TGP) (£20m | SR67) | Contract worth c.€1m (£860,000 awarded by a leading submarine cable contractor for concrete protection and stabilisation solutions on a major European offshore windfarm – delivery is scheduled within calendar 2026. | ||
Kelso group (LON:KLSO) (£16m | SR42) | Kelso, a 10% shareholder in TheWorks.co.uk, has set out its case for shareholders to vote for Resolution 15 at the 7 September AGM, which is the appointment of Graeme Coulthard as Director of The Works. Coulthard holds over 8%, first invested in 2020, and led Charterhouse’s 2010 acquisition of Card Factory. | ||
ARC Minerals (LON:ARCM) (£15m | SR8) | Drilling contractor selected for the imminent diamond drilling programme at PL135/2017, part of the Virgo project in the Zone 5 corridor of Botswana’s Kalahari Copper Belt. A survey has traced 14km of the rock contact that hosts copper elsewhere in the belt, and the drill targets are spread along it. | ||
Panther Metals (LON:PALM) (£14m | SR20) | Phase 1 metallurgical test on the Dotted Lake ultramafic intrusive in Ontario recovered approximately 38 wt.% magnesium using Extrakt’s leaching technology against the 19-25 wt.% ceiling seen in conventional single-stage leaching. | ||
Alien Metals (LON:UFO) (£11m | SR27) | Plan for twelve-month work programme for the 100%-owned Georgina Basin IOCG project in the Northern Territory (Australia), with more than 90 conceptual targets and technical review of the three advanced prospects at Leichhardt East, Leichhardt West, and Banks. |
Roland's Section
Time Finance (LON:TIME)
Up 9.4% at 58p (£48.6m) - Recommended Cash Acquisition of Time Finance - Roland - TAKEOVER
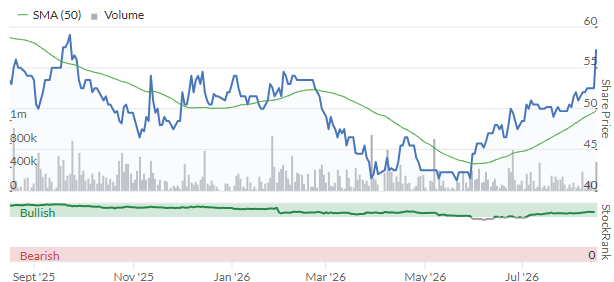
Another day, another takeover. A number of you in the comments seem disappointed by the offer for Time Finance this morning and at first glance I can see why this might be. Today’s cash offer of 59p per share is only in-line with the stock’s 52-week high:
The premium to recent share price levels is also a little below the 30%-40% we often look for:
+12.6% versus Friday’s closing price of 52.5p per share
+23.5% versus the three-month volume-weighted average of 47.84p per share
+27.5% versus the six-month volume-weighted average of 46.34p per share
A trade buyer consolidating the market?
The bidder is Bentley Park, the parent company of asset-based lender Ultimate Finance. So this is a trade deal, not a private equity takeout. My impression is that the two companies lending products overlap in a number of areas, such as asset-backed finance and invoice finance.
Bentley Park believes that the combined Ultimate Finance and Time Finance business would be well-positioned as a significant independent alternative lender with a combined net loan book size of nearly £650 million (based on the companies' respective unaudited loan books as at 30 June 2026). Bentley Park believes the Combined Group would have the scale, product breadth and funding infrastructure to serve UK SMEs across a full spectrum of their working capital and asset investment needs.
Ultimate is larger, with a net loan book of c.£429m at the end of June 2026 versus Time’s loan book of c.£218m.
The two companies are more evenly matched in terms of profit, though. Checking the 2025 accounts for Ultimate Finance Group Limited shows revenue of £54m and an operating profit of £7.5m.
The equivalent figures for Time Finance last year were £37.1m and £7.9m, so Time Finance seemingly enjoys a higher operating margin.
Is the price fair?
Today’s offer does not look overly generous compared to forecast earnings for Time Finance. The 59p bid represents a multiple of just 7.7x FY27 forecast earnings of 7.7p.
However, when valuing lenders we also need to consider net asset value and return on equity.
Time’s year-end was on 31 May. The company issued a trading update in June, which Graham covered here. This showed net tangible assets of £50.1m (54p per share) at the end of May 2026.
Based on consensus earnings forecasts, this suggests Time Finance generated a return on tangible equity of 13% last year.
For contrast, today’s 59p offer represents a 9% premium to tangible book value.
For a mature, slow-growing business I’d argue that this might be a fair price. But Time Finance is not mature or slow growing – earnings have been growing at double-digit rates in recent years.
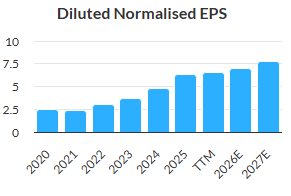
The latest forecasts I can see for Time Finance from house broker Cavendish suggest net tangible assets could reach 61.5p by May 2027. That would put today’s offer at a 4% discount to NTAV. This seems a little low to me, especially as I would expect the combined group to enjoy some cost savings from de-deduplication and greater scale. All in all, I don’t think this offer is overly generous.
Already a done deal?
Time’s Board notes that the offer “will present an opportunity for Time Finance Shareholders to accelerate the crystallisation of certain value from their investment”.
All three of the company’s largest shareholders plus its directors have already indicated their support, representing c.47.4% of shares in total:
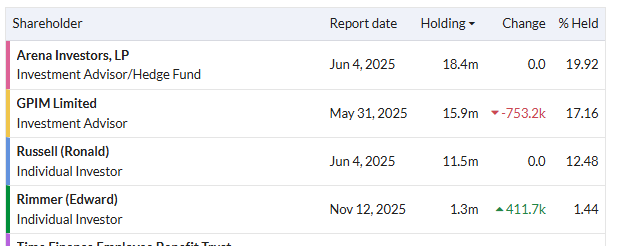
This leads me to speculate whether the decision to sell the business was prompted by one or more of the group’s largest shareholders, seeking an exit.
Based on this level of support, I think Bentley Park’s offer is near-certain to succeed unless a higher, competing bid emerges in the meantime.
Roland’s view
The Time Finance directors appear to have adopted a cakeist approach to justifying their recommendation of today’s offer. On the one hand, they say:
The Company has a demonstrable track record of delivering organic growth in its lending book for 20 consecutive quarters to 31 May 2026. The Time Finance Directors therefore remain confident in Time Finance's ability to succeed as an independent business.
On the other hand, they suggest that “the Acquisition presents a compelling route to fully realise the Company's long-term strategic and operational potential in the most efficient way possible”.
On balance, I think Time Finance shareholders are probably going to miss out on the benefit of continued profitable growth if this takeover succeeds.
However, I would caveat this by saying that Time Finance’s returns on equity (including goodwill related to past acquisitions) are distinctly average:
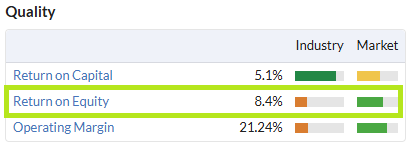
It’s also worth remembering that as we’ve seen numerous times over the years, small-cap niche lenders are relatively risky and can fall victim to unexpected problems.
Shareholders who want to oppose the offer will have the opportunity to vote no. A 75% vote in favour is required for the scheme to be approved, so it’s not impossible that a show of unity from private investors might successfully oppose the deal.
Unfortunately, I suspect today’s offer means we will lose another decent business from the AIM market.
Telecom Plus (LON:TEP)
Up 4% at 891p (£696m) - AGM Trading Update - Roland - AMBER ↑
Following June’s profit warning, the good news today is that Telecom Plus has left full-year guidance unchanged.
Execution across all operational areas is progressing at pace, and we remain confident in meeting our guidance for FY27 and on track to deliver on our long-term goal of £175 million of adjusted profit before tax by FY31.
The company expects to achieve an adjusted pre-tax profit of £80 to £90m in FY27, implying an ambitious c.20% compound growth rate between FY27 and FY31.
Gathering momentum?
Today’s AGM Trading update highlights some positive metrics suggesting this utility reseller (which trades at Utility Warehouse) might be regaining some of its lost momentum. These figures cover FY27 year-to-date (April - July):
Annualised multiservice customer growth is “running slightly ahead of our 10% target for the full year” and is well ahead of the 3.9% achieved in FY26.
Cross-selling activity is being ramped up, with c.17,000 core services cross-sold so far, putting the business on track for its target of 50,000 services cross-sold in FY27.
Insurance re-platforming onto OpenGI (an insurance tech platform) is progressing well, on track to launch motor insurance in H2 FY27.
New advertising and marketing campaign is on track to launch in Q3, including television and radio “activations”.
IT upgrades are progressing with an increasing proportion of customer interactions being managed with “no human intervention”.
Partner activity (self-employed sales agents) is running at record levels, with an average of c.4.9k Partners active each month so far this year (from c.4.2k in H2 FY26).
Partner recruitment is also performing well, with total partners now at >85k, from c.77k at the end of FY26.
Problem solving: these updates suggest Telecom Plus is dealing with the issues identified in June’s results – problems including renewed price competition from major energy suppliers, ageing IT and continued issues with its insurance offering, which is a relatively recent addition to the company’s portfolio.
Attractive returns from buybacks?
The company also confirmed that the £40m buyback programme announced in June is roughly 50% complete, with 2.44m shares repurchased at an average of 816.66p and £20m remaining to be deployed. This may have accounted for some of the recent strength in the share price:
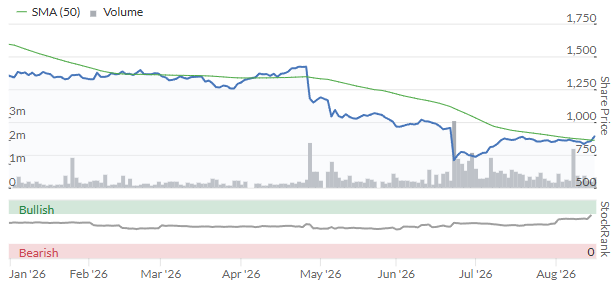
Telecom Plus abandoned its long-held dividend-only policy earlier this year, cutting the payout and switching some of its shareholder returns into buybacks. A further buyback is expected in FY27, with details to be announced in November.
Using the 8% pre-tax return hurdle favoured by Next suggests buying back shares could be generating value at current levels. Taking the mid-point of this year’s profit guidance suggests buying back shares could generate a 12% return at the current market cap.
The much-reduced dividend now offers a forward yield of c.3.8% – a far cry from the levels seen in the past, but in line with market averages.
Roland’s view
My conclusion in June was that Telecom Plus’s management had become complacent during a period of bumper profits and growth and had failed to plan for the (inevitable) normalisation of market conditions and increase in IT capabilities that would be required.
Today’s update suggests to me that progress is being made at remedying these shortcomings. This will come at a cost, though. Telecom Plus is planning to spend an additional £55m per year from FY27 onwards on a mix of price cuts, partner recruitment, marketing and IT upgrades.
This year’s pre-tax profit guidance of £80-90m is c.35% below last year and is expected to have a 15%/85% H2 weighting – even more skewed than the more normal 25/75 split reported last year.
An H2 weighting is normal for this business due to higher gas and electricity consumption during the winter. But the extreme H2 weighting suggests to me that visibility on full-year earnings could be pretty weak until quite late in the year.
I think it’s too soon to know how much confidence investors can have in Telecom Plus’s turnaround. But I’m encouraged to see that chairman Charles Wigoder now appears to be taking a more active role in running the business again.
Wigoder remains the group’s largest shareholder and ran the business for many years, prior to stepping down to a non-executive position more recently.
I was AMBER/RED on Telecom Plus in June, following a profit warning:
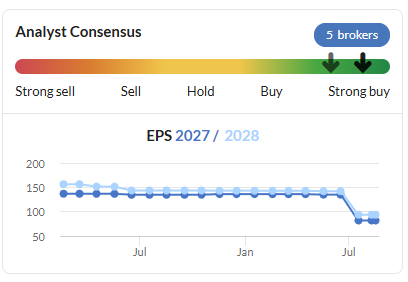
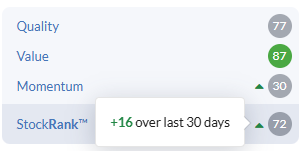
With guidance reiterated today and tentative signs of operational progress, I’m happy to return to a neutral view. I also note the StockRanks are looking increasingly positive, with Contrarian styling and a recent mini-Jump:
James's Section
MTI Wireless Edge (LON:MWE)
-6.6% at 62p (£53m) - Interim Results - James - GREEN ↑
Shares have really pulled back this morning, but on face value, the half was strong. Revenue rose 11% to $26.7m, operating profit 21% to $3.0m, and gross margin improved to 33.8% from 32.5%. Strip out Q1, which was reported in May, and the second quarter grew roughly 15% – an acceleration.
Revenue up 11% to $26.7m
Operating profit up 21% to $3m
Gross margin 33.8%, from 32.5%
Attributable profit up 15% to $2.49m (group net profit up 28% to $2.53m, flattered by minorities)
EPS 2.88 US cents, up 15%
My take is that the problem is in the antenna division. Revenue fell 20% to $6.6m and segment profit slipped to $596k from $696k. Management suggested the issue is timing – $6m of antenna orders were won in April and most of that revenue due in the next 18 months.
That covers some of it, but not all of it. The same 20% decline showed up in Q1, when the culprit was weak E-band 5G backhaul sales in India (and today’s statement confirms that Indian sales remain slow). This is the second consecutive quarter of decline in the division that carries the defence story, and only one of those quarters has a timing explanation.
It’s also worth considering that Israeli strikes in southern Lebanon over the weekend may be contributing to the pullback this morning.
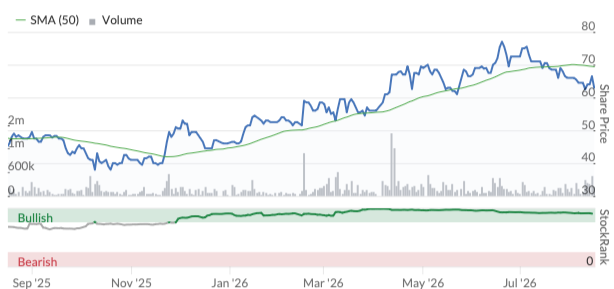
Let’s take a step back. MTI is an Israeli group built on one core skill – wireless communication in harsh environments – pointed at three different end markets: antennas for defence and 5G backhaul, Mottech's remote control systems for irrigation and water distribution, and MTI Summit, which distributes and integrates radio frequency components in Israel.
As management, and my colleague Ed Sheldon pointed out in his excellent June article, the company’s end markets are in growth mode. A management quote pulled from the FY results read:
Our target end-markets remain in growth mode. Military conflicts are increasingly reliant on electronics, a shift which is to MTI's advantage, especially when coupled to a global increase in government defence budgets. Demand is increasing for our ABS® antenna solution for E-Band 5G backhaul, representing a substantial opportunity over the medium term and scarcity of water is behind the ongoing drive by governments and businesses to significantly improve the efficient use of this fundamental resource.
That's the thesis. And with a market cap around £53m and revenue driven by a handful of sizeable contracts, lumpy half-years come with the territory – a couple of orders slipping a few weeks moves the division's numbers.
Thin coverage, but encouraging numbers
Just two brokers cover MTI, so there isn't much of a consensus to speak of – but their combined price target of $1.32 sits around 47% above where the shares opened this morning.
The quality metrics are the strongest part of the investment case. Return on capital is 17.5% and return on equity 17%, both ahead of the five-year average of around 15%. The operating margin is 11.6% and improving. The F-Score is 8 out of 9, the Z-Score of 5.24 sits firmly in the safe zone, and net gearing is minus 25% – $8.2m of cash against almost no debt. The QualityRank is 97 and the StockRank 90 – these are very strong indicators.
The valuation isn't demanding either. After this morning's fall the shares trade on around 14x forecast earnings, 8.8x EV/EBITDA and 1.4x sales, with a forecast yield near 4.4% covered 1.6x.
Forecasts still show 5.80 cents for 2026, below the 6.02 cents already earned on a trailing basis, and 5.90 cents for 2027. No growth is in the numbers at all.
That looks beatable. Attributable profit for the half was $2.49m, already half of the $5m the market expects for the full year – and the first half is normally the smaller one. Last year H1 delivered 43% of the annual figure, with the balance coming in H2.
James’s take
Today’s results are light on guidance – that’s not unusual. But after a significant pullback versus the prior year comparator in the antenna division, some investors will have wanted more reassurance about the second half than “in line with market expectations”.
However, nothing here is broken: two of the three divisions grew strongly, margins improved, returns on capital are 17% and the balance sheet still holds net cash.
The bit that’s missing is the confirmation. The April orders need to arrive, antennas need to stop shrinking, and neither broker has changed their forecasts in three months. Running some simple maths, if the year splits like last year's did, $5.8m of profit isn't a stretch, putting the shares on around 12.4x forward earnings – enticing for a company with a net cash position. Today's fall looks like disappointment at unchanged guidance rather than anything in the numbers, and I have left my positive view unchanged.
Gattaca (LON:GATC)
Down 0.7% at 168.25p (£53m) – Trading Update – James – GREEN =
Gattaca isn’t a stock I’ve followed particularly closely over the past couple of years – as far as I was concerned it was a suburb of Liverpool. That said, this is a very interesting business and a stock that has surged somewhere in the region of 50% since March. Today’s numbers reinforce why investors were bullish, but the modest pullback suggests the rapid appreciation may be slowing. The numbers are good, but nothing more than the market was expecting.
Net fee income up 11% to £43.2m (FY25: £38.8m), up 7% like-for-like
Contract NFI up 16%, up 14% LFL
Permanent NFI down 3% LFL, up 5% including the InfoSec acquisition
Underlying pre-tax profit c.£6.1m (FY25: £3.3m), against guidance of £6m
Net cash £15m (31 July 2025: £15.7m)
The first thing to note is that today's beat is small – £6.1m against £6m of guidance. But that guidance was only set on 14 May, when it was raised from £4.5m. So against where the year started this is a big improvement, and against what the market has expected since May it's a rounding difference. Consensus EPS of 13.3p hasn't moved in three months. That's why the shares aren't going anywhere today.
Gattaca is a specialist recruiter, formerly Matchtech, placing engineers and technical staff into infrastructure, defence, energy, mobility and digital technology. Ignore the £418m revenue line on the StockReport, which is mostly contractor payroll passing through. Net fee income is the number that matters.
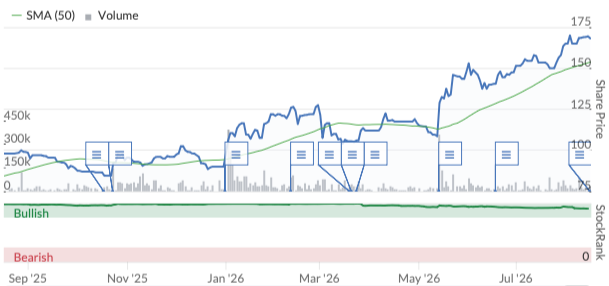
Underlying pre-tax profit rose 85%, from £3.3m to £6.1m, on net fee income up just 11%. That's some operating leverage. A recruiter's cost base is mostly consultants' salaries, so once that's covered, additional fee income falls largely to the bottom line. Gattaca's costs rose 4.5% while fees rose 11%, meaning £2.8m of the extra £4.4m of net fee income dropped through to profit. Conversion – profit as a share of net fee income – improved from 8.5% to 14.1%.
The impressive part is that it did this with fewer people. Sales headcount ended the year 4% below where it started, so each consultant billed materially more. Panmure Liberum made the same point in May, noting part of the upgrade came from not hiring as fast as planned.
That's worth pausing on, because it isn't repeatable. Headcount rose 3% in Q4 and management now plans "targeted investments in sales consultants". New consultants cost money months before they bill anything, so FY27 carries that expense up front while the revenue follows later.
Still not expensive
Mark ran these multiples in his May note when the shares were 130p. Forecasts haven't changed since, so the only thing that's moved is the price. At today's 168.25p:
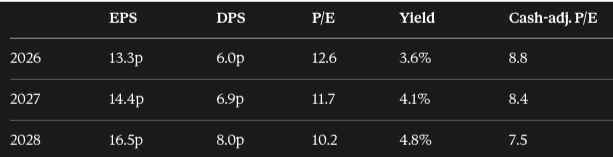
At 130p those P/Es were 9.8, 9 and 7.9, with a 4.6% yield on this year. So the rating is up by roughly a third. It's still not expensive – strip out the cash and you're paying under 9x this year's earnings. However, today's £15m of net cash is slightly below the £16.7m Mark's model assumed.
Only one broker covers the stock, and Panmure's 185p target is just 9% above the current price. The broker suggested the forecasts were “very cautiously set” in May.
James’s take
The valuation looks great, especially when adjusted for cash. However, I’m certainly cautious that recruitment is a cyclical business. This is seemingly the best year the business has had in years, and permanent fees, which usually turn first in a downturn, grew 5% at group level but slipped 3% excluding the InfoSec acquisition, and the board flags "cautious customer decision-making". That said, I’m keeping this on Green as the metrics still support some appreciation, but at this elevated price, investors should remain vigilant.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
10YR is currently heading towards 5%, creating a strong downward pressure on US stock prices.
This tightening will obviously trigger a downturn in London’s stock market.
All the best
Much appreciated the in-depth analysis of GATC this morning giving me cause for confidence and satisfaction from acting on previous similar bullish discussion notes provided by the team over the past 12 months
Can anyone suggest a tidy way to include in a portfolio the value of assets that Stockopedia doesn’t list, to make it easier to reconcile Stockopedia portfolio valuation with broker valuation?
I'd suggest a non-Stockopedia route : Sharesight.
Especially if you have multiple portfolios, and also need to do self assessment tax on investments.
Thanks, Boon
Snowball analytics
any views on Thungela (TGA)?
they look ridiculously cheap! £630m mkt cap over £270m Net cash on top
TGA (Thungela) was cheaper at the end of June. Unlikely go there until dividend paid.
I have an order in.
Bought in March 2025, stonking dividend in May then underwater until sold on spike in March 2026.
I was in sub 390p, sold 50% at 620p..
Definitely looking to get back in, as dont think the price or forecasts reflect the prospects, even at the current price
Any comment on Springfield Properties RNS would be appreciated if you have time Roland or James. We first invested after Graham upgraded to green on balance sheet strength and Stock Ranks 4/6/26. They bought a Scottish builder on the 22/6/26, now paid for after the land sale in today's announcement. We added at 109.48p this morning at approximately 10% more than our initial larger investment. Is an Ed's bowl taking shape here? Maybe Angela's announcement coming today on speeding up planning permissions, might help builders in general?
"Maybe Angela's announcement coming today on speeding up planning permissions, might help builders in general?"
Maybe, though Housebuilders do not usually want to to build in a falling house price environment.
https://www.cityam.com/house-p...
And next to a railway line. Triple glazing. No windows on one elevation. Foundations to the earths crust. Better than a motorway however. Always a race to the bottom when have no money.
Could you do a review of Telecom Plus please. Share price progress has been extremely poor over many months.
Morning Swall101,
Telecom Plus (LON:TEP) is on my list this morning!
Roland
Thanks for the great write up Roland. Appreciated as always.
I know it's too small for you guys to comment on but BSF Enterprise (LON:BSFA) - Great Initials! is well worth a quick peruse!
Good morning Roland!
If possible, please could you add MTI Wireless Edge (LON:MWE) to your deep-dives today?
Thanks for the suggestion, MTI Wireless Edge (LON:MWE) is in progress as I type.
Roland
Fantastic! Thank you!
Goodwin (LON:GDWN) Up 8% first thing this morning, presumably follow on from news last week, but the spread I'm seeing is also 8%ish
Only up 1% on my platform, it does have a wide spread at times.
Yes - think this was a blip -
Seeing Machines (LON:SEE) RNS launching a physical AI platform to improve interaction between robots and humans.
Paul McGlone, CEO said "Our technology is already protecting millions of drivers around the world by enabling vehicles to better understand human behaviour and respond to risk in real time. With the launch of our Physical AI Platform we are extending that capability into robotics, enabling machines to interact with people safely, naturally and intuitively.
"As robots begin moving beyond research labs and into factories, workplaces, hospitals, homes and public spaces, understanding people and the environment they're in becomes just as important as understanding the task they're performing. We believe our Human-Centred AI design philosophy will extend into a foundational capability for the next generation of robotics," he said.
Wow. But then I looked at the Stock Report - ouch. Fund raise on the way maybe. Thanks Stocko brings common sense to emotional buying.
Wow indeed from Seeing Machines (LON:SEE) .... Lots of big buzzy words. Very similar type of exciting statements as those that come out of pre-Series A startups.
The next big thing or lots of hot air? Time to decide!
Seeking Alpha has solo analysts providing the hard research required. Agree , don’t agree your choice. Often the benefit is the contributors who are good at bringing the contributor down a peg or two.
Seeing Machines (LON:SEE) Is worth study even if just for a buy out situation. It’s time I need or better some insider knowledge :)
Optima Health (LON:OPT) I would appreciate if you could have a look over their results reported today please.
Financial Highlights
ADJUSTED RESULTS*
FY26
FY25
Change
Revenue
£120.6m
£105.0m
15%
EBITDA
£20.1m
£17.6m
15%
EBITDA Margin
16.7%
16.7%
0bps
Operating Profit
£15.7m
£13.5m
16%
Profit before tax
£14.2m
£12.8m
11%
Net debt (excluding lease liabilities)
(£94.4m)
(£2.2m)
n/m
STATUTORY RESULTS
FY26
FY25
Change
Revenue
£120.6m
£105.0m
15%
EBITDA
£15.2m
£13.7m
11%
EBITDA Margin
12.6%
13.0%
(40bps)
Operating Profit
£4.0m
£3.2m
23%
Profit before tax
£2.5m
£2.6m
(4%)
Net debt
(£103.4m)
(£6.9m)
n/m
Time Finance (LON:TIME) cash offer at 59.1p . 46% of shareholders willing to accept the offer despite book at 81p !
Have held these for two years now and feel cheated!
When I saw the RNS I thought "argh I should have held on to these", then I saw the price offered....
Quite agree, I fortunately came in about 28p , but have bought many since [up to 50p]: on so much +tive news over last couple of years ,and full order book currently ,with more contracts signed ,[I believe] . It had become my major holding. With order book filling ,and debtors reducing ,looked a strong buy for me ,and then we get a poor offer . SO DISAPPOINTING. However that has been my lot with offers over the years HGM ,and especially SHG -both management stitchups ,as business was going so well. SHG was particularly painful ,just before gold 'flew'. Such is life ,it's strange ,Im making a decent profit overall , but it does'nt feel like it !! Tony
Tony, don't be too hasty like I was with Good Energy, selling on hearing the first off as a second, better, offer came along. I don't hold Time Finance (LON:TIME) as I sold my holding in 2023, funnily enough, at 28 pence.
Time Finance (LON:TIME): to me, that run up on the chart through 2023/24 looks like another win for a Stockrank strategy over a long-term hold strategy.
Arena (the 20% shareholder) has had a change in corporate strategy....
I'd hoped that it might have led to a bid from themselves. But now looks like they've been looking to divest their stake at whatever price...!
I wrote a long note about Arena and their strategy change about a week ago here: https://substack.com/@boonkoh/note/c-311863229?r=qpu4
Very mediocre bid. I will be voting against it.
(I hold in the Boon Fund)
Agreed - the share price has above 60p less than two years ago and the business has done nothing but improve since then. I will be voting against and we minority shareholders can block the deal at this price. We certainly need to let the board know of our feelings.
It is a very disappointing announcement, and I don't understand why Cavendish have a price target of £1.12 but are recommending a bid at a derisory 59p - the board have just rolled over and how can they state the offer to be 'fair and reasonable' if they are trading at a big discount to their assets?
Might be a good time to pick up a few Time Finance (LON:TIME) shares? in case an higher bidder emerges ,no much risk of going lower
I think this offer is too low, 12% premium is nothing, l would expect 30%, l hold.