Likewise: flooring supplier lifts profit guidance by 20% as Headlam assets add scale

Analyst’s view:
Likewise appears to be executing flawlessly and benefiting from the failure of its main competitor. Today's upgrade lifts full-year profit guidance by c.20% with less than two months of the year remaining. Although the valuation looks full, I think this is justified by the current growth trajectory so I'm staying GREEN today.
Up 4% at 44p (£161m) - Trading Update
When Likewise acquired some key assets from its failed rival Headlam in October, Graham lifted our view by two notches to GREEN, explaining that:
... this seems like a dream scenario for the company: the loss of a major competitor, the purchase of its most useful assets from administrators, and control of its leftover inventory. It doesn’t get much better than that in terms of a boost to competitive positioning.
Today's update suggests he was right to be optimistic. Likewise has lifted its 2026 pre-tax profit guidance by 20% with just two months remaining in the year. Management commentary suggests to me that Likewise is quickly absorbing some of Headlam's former trade.
Trading update: key points
The "positive sales trajectory" seen in Summer and early Autumn has continued.
October sales rose by 36.7% year-on-year.
Year-to-date sales growth of 22.8% vs FY25.
Sales growth seen across all the group's businesses.
2026 pre-tax profit now expected to be no less than £6.0m - that's 20% ahead of September's guidance of "not less than £5.0m".
Integration of Headlam assets
Likewise CEO Tony Brewer was CEO of Headlam for many years, so I'd expect him to have chosen well when buying assets from Headlam's administrators.
Today's commentary suggests integration is going well and adding useful capacity to Likewise's network to support its ambition of becoming the UK market leader. The main focus on the moment appears to be on restocking, replenishing inventories that were depleted during Headlam's final months:
Incoming deliveries to the Thatcham distribution centre started on 22 October. This facility will be integrated into Likewise's logistics network in November, improving coverage across the south of England, in particular.
Concept Flooring Supplies in the West Midlands is almost back to service as normal, following restocking.
Premium carpet brand Crucial Trading has placed orders to restock. Likewise is also restocking its outlets with the Headlam-exclusive flooring brands it acquired, in order to maintain continuity of supply for former Headlam customers.
Likewise is continuing to manage the sale of Headlam's remaining stock in order to "avoid any disruption" - i.e. to maximise returns and avoid a firesale situation that would depress margins.
Balance sheet impact: Likewise spent £14.9m on Headlam assets and is presumably incurring some additional working capital outflows in order to restock inventory and expand its delivery fleet.
Today's update reports that the company now owns eight freehold properties with a value of £56m "with just £11 million of fixed debt".
Fortunately (with foresight?) Likewise raised £32.5m in new equity prior to the Headlam administration. This has provided valuable firepower to support recent growth, but even so this year's balance sheet seems likely to show a significant net debt position.
According to updated forecasts from house broker Zeus today, 2026 year-end net debt is now expected to be £24.2m, falling to net debt of £11m in 2027.
For some context, Zeus expects Likewise to report EBITDA of £13.2m in 2026, implying a peak leverage multiple of 1.8x. While this needs watching, I don't see any reason why Likewise won't be able to deleverage as planned in 2027.
Updated broker forecasts
A key element of the business model here is that Likewise should become more profitability as it grows.
We've already seen this happening over the last few years:
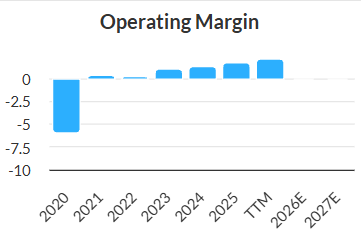
Broker Zeus now sees this process accelerating. Today's forecasts suggest Likewise's adjusted operating margin will reach 3.8% in 2026 and 4.1% in 2027 (previously 3.5% and 3.9%, respectively).
Zeus has also updated its 2027 revenue expectations from £210m to £230m, to reflect the expected contribution from Headlam assets.
These projections cascade down to the following upgraded earnings forecasts:
FY26E adj EPS: 1.5p (+19% vs 1.3p previously)
FY27E adj EPS: 1.7p (+25% vs 1.4p previously)
Roland's view
Likewise appears to be executing flawlessly, with expert management and a deep understanding of its marketplace. In addition, the company is benefiting from the failure of its main competitor.
As Graham suggested in October, this looks like a dream scenario.
While the valuation remains fairly full, on a FY27E P/E of 26, I think this needs to be seen in the context of Likewise's rapid sales growth and improving margins. In my opinion, there's a good chance Likewise will grow into its current valuation.
In addition, I wouldn't be surprised to see today's FY27 forecasts from Zeus upgraded again when the company issues more detailed FY27 guidance with its 2026 results.
Given the size of today's upgrade (with less than two months of the year remaining), I'm going to maintain our GREEN view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Likewise (4)
Comments here are also visible in the Daily Stock Market Report
Very decent update from Likewise (LON:LIKE) today. Had my eye on them for a while, I just can't pay up for 26 x forward earnings for a floor distributor.
More fool me, probably
Last month I commented that the Likewise (LON:LIKE) structural setup had never been stronger and that January’s trading update would be the first meaningful read. Well, a first read arrived this morning….
October revenue rose 36%, taking the YTD to +22%. Profit before tax is now expected to be at least £6m, up from at least £5m five weeks ago and a market forecast of £4m in July. That implies H2 profit of at least £4.7m, roughly double last year’s figure. The operational gearing is starting to show.
Delivery is still what counts, and today’s update doesn’t yet show how much Headlam volume Likewise will keep, but the early evidence is encouraging. I hold.
Thank you Paul for the inspiration to buy
I do find it helpful to summarise my thought process in writing. Always inspiration never advice. Good Hunting. Ian