TP ICAP facing slight risk of downgrades but overall picture remains promising

Analyst’s view:
My impression is that Q3 growth has perhaps been slightly disappointing. The highest-margin division, Parameta, has seen 5% growth in ARR year-on-year and some observers may have been expecting a little more. It's worth noting in this regard that today's "in line" outlook statement referred only to EBIT, and not to revenue. Overall, for a business with such a fine record of profitability and such strategic importance in global financial markets, I continue to view its valuation (9x earnings) as undemanding.
Down 2% at 314p (£2.27bn) - Trading Statement
This large global broker has issued a solid trading update.
Key points:
Year-to-date revenue +9% at constant currency rates, +7% at actual currency rates
Q3 better than that at +11% (constant rates), +11% (actual rates).
Q3 performance by division
Global Broking (responsible for more than half of total revenues) led the way with 16% growth in Q3.
Energy & Commodities grew by 7%, while Liquidnet fell 1% and the high-margin data division Parameta Solutions was flat year-on-year.
For some context, in H1 the divisional breakdown of revenue and profits between broking and Parameta was as follows. These were the two largest contributors to the group's profits:
Global Broking: £770m revenue, £159m adj. EBIT
Parameta: £97m revenue, £36m adj. EBIT.
Outlook
TP ICAP is "comfortable with full year 2026 market expectations for adjusted EBIT, subject to foreign exchange movements."
These expectations are for £367m of adjusted EBIT (range £357-378m).
Commentary
The broking division enjoyed "strong momentum" helped by "strong strategic execution" and "supportive market conditions".
E&C is "well-positioned for a recovery in its markets", which is an acknowledgement that these markets have not yet recovered. This is due to "depressed levels of activity in global Oil futures markets". This seems paradoxical as Iran-related price volatility would have initially increased volumes, but the subsequent lack of physical flow has apparently depressed volumes. Perhaps this division could be a future beneficiary of a peace deal with Iran?
Liquidnet "continued to execute well" although "equities block trading market was subdued, as the Middle East conflict continued to weigh on market risk appetite and client trading behaviour". Another division that would benefit greatly from the cessation of hostilities, perhaps?
Parameta saw ARR grow 5% year-on-year. It sounds a little quiet in Q3, but there is some good news for Q4: "subsequently, Parameta Solutions has closed its largest US buy-side new logo contract to date".
Estimates
Cavendish says that they do not expect material changes to their forecasts after today's update. I think there could be slight downgrades in store, given that Cavendish say that they "are looking for further revenue growth" in Parameta and Liquidnet by year-end.
Graham's view
My impression is that Q3 growth has perhaps been slightly disappointing. The highest-margin division, Parameta, has seen 5% growth in ARR year-on-year and some observers may have been expecting a little more. It's worth noting in this regard that today's "in line" outlook statement referred only to EBIT, and not to revenue.
At the interim results, at a share price of 321p, I maintained our fully positive stance on this share. I'm inclined to do that again today, primarily on valuation grounds:
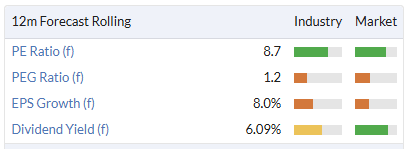
For a business with such a fine record of profitability and such strategic importance in global financial markets, I view this valuation (9x earnings) as undemanding.
As I noted at the interims, the market has seemed to be a little disappointed with recent updates. Based on the share price reaction then, the market seemed to expect another upgrade (which did not materialise).
Today, again, the market seems a little disappointed and it is fair to think that there could be slight forecast downgrades coming.
But look at the big picture: earnings forecasts have, overall, been quite resilient over the past year.
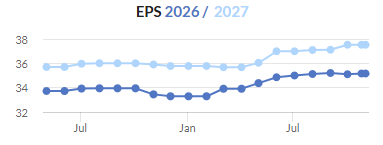
There are some macro factors beyond the company's control - it can't determine trading volumes - but the track record says that in general the company can generate a solid profit margin in all sorts of market conditions. That will once again be the case in 2026.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on TP Icap (2)
Comments here are also visible in the Daily Stock Market Report
TP Icap (LON:TCAP)
On track trading update seems fine to me , I bought in a while back due to lowly rating if believed bumper profits promised would materialise plus possibility of selling/floating part of the business.Not an easy company to get a grip on how much transparency they have ref future earning. Seems to be doing ok though even if the possible listing seems to have been ditched for. Current expectations are for increased profits next year too so hopefully they can keep overall positive momentum going.
I have also picked some up recently - in a bid to have some market exposure should the market cycle grind on longer but also potentially a beneficiary from rising Vol. For me, Q3 looks ok but it isn't motoring and obviously $ weakness is not our friend. I guess vol trends have not been unusual so far and investment banks have done quite well but not really down to trading vols. Longer term TP Icap (LON:TCAP) must be an AI victim but in the short term I can't see anyone worrying about that. Main risk for me therefore is US politics and $ hurting before trading strengthens.