Daily Stock Market Report (Thur 6th August 2026) - BOY, PSN, WPP, HBR, PZC, TCAP, OSB, MER, DEVO

Strait of Hormuz: Iran and Oman are preparing a joint statement about their agreement for a new shipping route through the Strait of Hormuz.
While the agreement doesn’t mean that the Strait will reopen soon, it will provide a management plan that both countries are happy with. Oman and Iran border the Strait at its narrowest point, and eastwards of that point.
According to Iranian state television cited by Bloomberg, reopening the Strait will require “a change in US behavior”. The US blockade of Iranian ports continues.
The oil price hasn’t moved much in response to this latest development, but at about $79-$80, it's a long way off its recent highs. A sign that all sides might gradually be figuring out a path towards peace?
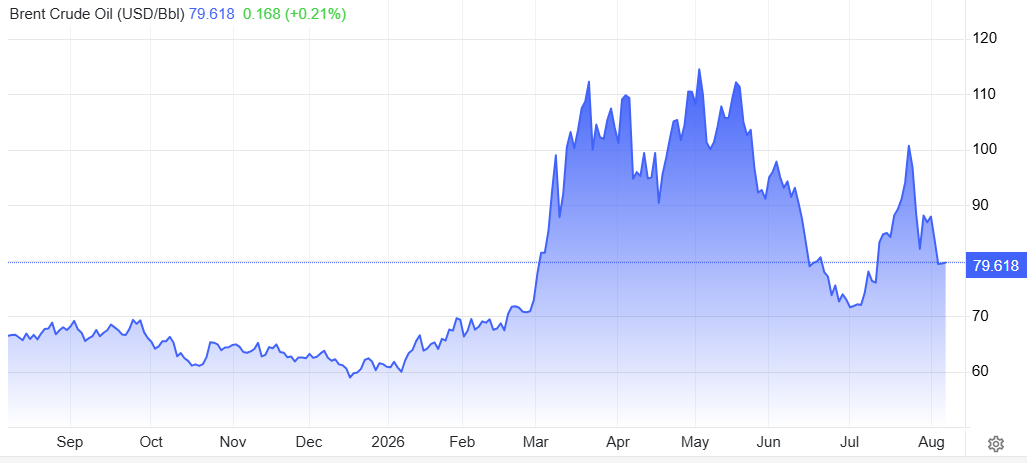
Brent crude oil price. Source: Trading Economics.
Overnight market movements:
The FTSE is up 0.2% at 10,895
S&P 500 is up 0.2% at 7,753
Brent crude (October) is flat at $79.45/bbl
Gold is up 0.3% at $4,260/oz
Bitcoin is unchanged at $64,800
Leaving it there for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Admiral (LON:ADM) (£11.4bn | SR61) | Revenue flat at £3.1bn with pre-tax profit from continuing operations -18% to £429.2m. Adjusted EPS -18% to 109.0p, interim dividend -39% to 70.5p. £45m share buyback. Notes challenging market conditions. | ||
Metlen Energy & Metals (LON:MTLN) (£5.9bn | SR45) | Revenue +11% to €4.0bn with net profit +23% to €313m and EPS of €2.18. Outlook: reaffirms 2026 EBITDA guidance of €1.00-1.15bn and medium-term EBITDA target of c.€1,920-2,080m. | ||
Harbour Energy (LON:HBR) (£3.7bn | SR98) | H1 production +4% to 509 kboepd. Revenue +20% to $6.4bn with adj EBITDAX +15% to $4.5bn. Free cash flow +c.30% to $1.8bn and net debt of $5.4bn (0.7x leverage). 2026 Outlook upgraded: production guidance 490-500 kboepd (prev. 480-500 kboepd) and free cash flow of c.$1.8bn (prev. c.$1.4bn). Minimum $800m shareholder return, including $250m buyback announced today. | AMBER/GREEN ↑ (Roland - I hold) [no section below] Full-year production is now expected to be in the top half of the guidance range for 2026, while free cash flow guidance has been upgraded on the back of higher oil and gas prices – commodity producers are always a leveraged play on commodity prices. Net debt has also fallen from $6.3bn at the end of Q1, demonstrating strong cash generation. While the current net debt of $5.4bn is only equivalent to leverage of 0.7x EBITDAX, this multiple could increase if oil prices were to fall sharply. A conservative investor might suggest that maximising debt reduction when oil prices are high is more sensible than providing additional shareholder returns, but that’s not what is happening. Instead, the company now plans to return a minimum of $800m to shareholders in 2026, including “at least $500m” in addition to the ordinary dividend (which offers a 7%+ yield). With the stock trading on a P/E of 5 and this level of shareholder returns on offer, I think it would be churlish of me to maintain my neutral view from May – Harbour shares are cheaper today then they were then, even though the outlook has improved. I’m moving up to AMBER/GREEN, with the caveat that if commodity prices reverse, today’s upgraded guidance could also reverse. | |
Persimmon (LON:PSN) (£3.6bn | SR80) | H1 home completions +13% with average sale price +1%. Underlying pre-tax profit +3% to £170.1m with interim dividend maintained at 20p per share. Net debt of £165m at 30 June. 2026 outlook: on track for completions of c.12,500 homes, “at the upper end of previous guidance”. Underlying PBT to be in line with market expectations. | AMBER/GREEN = (Roland) I don’t see much to dislike about these results. Unlike some peers, Persimmon appears to be generating sustainable returns from a difficult housing market. While first-half land spending has driven a surprising shift to net debt, my feeling is that some of this is timing related. Full-year cash/debt guidance is unchanged and suggests a more moderate position. With the stock on a P/E of 11 and offering a covered 5.5% yield, I’m happy to remain broadly positive here. | |
WPP (LON:WPP) (£3.3m | SR83) | SP +25% Revenue less pass-through costs -5.6% to £4,745m with headline operating profit -2.7% to £398m. Adj EPS -24.5% to 15.1p. H1 performance “in line with our expectations”. Business is transitioning into a single integrated company. 2026 Outlook: continue to expect improving LFL revenue trajectory, albeit still negative. Maintains guidance for full-year adj operating margin of 12% to 13%. | AMBER/GREEN ↑ (Roland) The market has taken a very positive view of today’s half-year results after WPP’s Q2 revenue came in ahead of expectations. I’m also encouraged by emerging evidence of progress with the group’s restructuring into a cohesive, tech-enabled operating company. Disposals are helping to manage debt and today’s guidance suggests a significant improvement in profit margins in H2. I’ve decided to take a chance and reverse my AMBER/RED view of a year ago to be broadly positive today. WPP is trading on a single-digit P/E but remains one of the largest companies of its type in the world. Earnings forecasts suggest a return to growth from 2027. While the stock may not fully regain former highs, I’m fairly confident it should be worth more than it is at the moment. | |
Hikma Pharmaceuticals (LON:HIK) (£3.3bn | SR81) | Revenue +3% with operating profit +30% to $336m and adj operating profit +9% to $405m. Adj EPS +5% to 128c. 2026 outlook reiterated for revenue growth of 2% to 4% and adj operating profit of $720 to $770m. | ||
Quilter (LON:QLT) (£2.8bn | SR90) | AuMA +11% to £157.4bn with net inflows of £5.8bn and “positive markets”. Adj pre-tax profit +12% to £112m and adj EPS +13% to 6.1p. 2026 outlook: currently expect H2 adj profit to be “a mid-single digit percentage above the first half level”. | ||
TBC Bank (LON:TBCG) (£2.7bn | SR74) | H1 net profit +13% to GEL 751m with return on equity of 23.5%. Outlook: on track for 2026-28 group financial targets of 15%+ annual loan book growth and 23%+ ROE. | ||
TP Icap (LON:TCAP) (£2.5bn | SR96) | SP -7% Revenue +8% to £1,292m with pre-tax profit +10% to £135m and adj EPS +10% to 19.3p. New £30m buyback. 2026 outlook: expect to achieve adjusted EBIT in line with current market expectations. | GREEN = (Graham)
This is something of a head-scratcher. I’m inclined to leave our existing GREEN stance unchanged because the company appears to be doing just fine. It appears that those trading the stock were expecting another upgrade - which in a year of geopolitical turmoil, especially in the energy markets, has a degree of logic behind it. I can see why there might be some disappointment that an upgrade has not materialised But it’s not the company’s fault that its share price was pushed up to 350p by people who thought another upgrade was coming. | |
Serco (LON:SRP) (£2.4bn | SR78) | Revenue +4% to £2.5bn with underlying operating profit +10% to £157m and adj EPS +6% to 10.17p. Adj net debt reduced by 12% to £228m. 2026 outlook: on track for the full year; revenue, profit and free cash flow guidance unchanged but net debt now expected to be c.£240m (prev. c.£165m). | ||
Derwent London (LON:DLN) (£2.3bn | SR75) | H2 net rental income -1.2% to £92.9m with EPRA EPS -6.7% to 48.7p and total accounting return -0.4%. EPRA NAVps -2.1% to 3,157p due to yield expansion and a £46m provision. Outlook: 2026 EPS guidance upgraded to +0% to +3% (prev. -3% to -5%). 2027 and 2030 guidance unchanged. | ||
Osb (LON:OSB) (£1.94bn | SR75) | SP -11% Pre-tax profit -3% to £187.2m due to higher impairment charge and overheads. Net loan book +1.3% to £26.3bn with 10% increase in originations to £2.3bn. Net interest income +1% with net interest margin -7bps to 2.23% due to additional funding costs. Cost:income ratio stable at 40.1% (H1 25: 40.3%). 2026 outlook downgraded: Net Interest Margin now expected to be 2.15% to 2.2% (prev. c.2.25%), with RoTE of c.12.5% (prev. “low teens”). | BLACK (AMBER/GREEN ↓) (Graham) [no section below] Nudging our stance on this down slightly as the company's 2026 RoTE guidance falls to 12.1% (vs. expectations of 13.1%). Net interest margin was supposed to come in at 225 basis points but due to "strong competition in the retail savings market and elevated retail funding costs" this will not quite be achieved. This in turn dampens the RoTE result that is achievable. There is also a warning that this pressure on funding costs could have "a modest impact on our 2027 mid-teens RoTE aspiration". When covering this company previously, I said that I didn't need it to earn a very high RoTE, as its earnings multiple was so cheap. The earnings multiple today, after this sell-off, is about 7x (share price 507p vs. an adjusted EPS forecast of 73.9p at Cavendish). On next year's forecasts, the P/E falls to 6x. This is the sort of level where I'm often willing to accept some fragility to the earnings forecasts, but in the case of a bank I may need to be a little more selective. OSB is also undergoing a CEO transition. I'm still positive on the risk/reward here but to reflect the possibility that RoTE remains under pressure, I'm switching us down to AMBER/GREEN. I'm very open to going back to fully GREEN here at the next update. Tangible net asset value is 584p per share. | |
Bodycote (LON:BOY) (£1.57bn | SR80) | Statement Regarding Possible Offers for Bodycote (y’day evening) | Bodycote has received two possible offers from private equity buyers. | TAKEOVER (Roland) [no section below] |
Wizz Air Holdings (LON:WIZZ) (£1.19bn | SR65) | Revenue +5.5% with operating loss of €183.3 (Q1 25: op profit of €27.5m). Total CASK (cost) +5.1% with Fuel CASK +21.3%. Net debt +3.9% to €5.1bn. Q1 load factor 90.9%, expect H1 load factor to be flat year-on-year. | ||
Serica Energy (LON:SQZ) (£879m | SR79) | Production of 44,700 boepd (H1 25: 24,700 boepd) with Q2 production of 50,200 boepd. Revenue $677m with EBITDAX of $301m (H1 25: $118m) and free cash flow of $184m (H1 25: $26m). 2026 outlook: on track to deliver production of c.65 kboepd following completion of Sprint Energy transaction, which is expected in October. | ||
Morgan Advanced Materials (LON:MGAM) (£664m | SR66) | Revenue +3.1% to £518.1m with adj operating profit +5.5% to £57.8m. Adj EPS +8.1% to 10.7p. Turnaround efforts delivering progress. Outlook: expect constant currency revenue +c.2% for the full year with adj operating profit “broadly in-line” with H1. | ||
Michael Page (LON:PAGE) (£617m | SR63) | Gross profit -1.1% to £385.2m with pre-tax profit of £6.5m (H1 25: £0.2m). 2026 outlook: expect operating profit in line with consensus of c.£28m. | ||
Harworth (LON:HWG) (£470m | SR17) | Property group Peel Holdings has made a cash offer of 172.5p for each Harworth share. The offer values Harworth at a 20% premium to the closing price on 5 August and a 37% premium to the volume-weighted average price over the last month. Peel already owns 29.96% of Harworth through a subsidiary. | TAKEOVER | |
PZ Cussons (LON:PZC) (£465m | SR80) | Revenue +5.4% to £541.4m with LFL revenue +5.8%. Adj pre-tax profit +21.9% to £50.1m with adj EPS -2.7% to 7.14p (in line). FY27 outlook: the current year has started in line with expectations. | AMBER/GREEN = (Roland) [no section below] Shares in this consumer goods firm have risen by more than 30% since I covered the company in a Stock Pitch in May. Given that today’s outlook and FY27 guidance are in line with expectations, I’m not surprised to see the share price ease slightly. For me, the key elements of today’s results are continued above-inflation LFL sales growth of 5.8% and a return to mid-teens returns on capital, with an underlying ROCE of 18.7% (my calculation). Cash generation also looks healthy to me – I calculate free cash flow excluding disposal proceeds of £24m, versus £28m of net profit for the year. These are the sort of metrics I look for in a good quality consumer goods business. PZ Cussons isn’t as cheap as it was earlier this year, but I’m encouraged by progress. Given today’s in-line FY27 guidance, I don’t see any reason to change our previous view today. | |
Thor Explorations (LON:THX) (£368m | SR95) | Ongoing diamond drilling program beneath the current Segilola Gold Mine open pit continues to intersect high grade gold mineralisation which remains open at depth. “Our drilling has intersected multiple strong intercepts which include grades between 5 and 11 g/t gold at mineable widths.” | ||
Mears (LON:MER) (£358m | SR96) | SP +3% H1 revenue flat at £560m with adj pre-tax profit -10% to £28.9m, in line with expectations. Adj EPS -9% to 6.2p. Average daily net cash -57% to £29.7m. Margins lower due to a period of new contract starts, but remains within target range. Outlook: margin guidance for the current year is maintained towards the lower end of the 5-6% medium-term target range. | AMBER/GREEN = (Graham) [no section below] Forecasts were left unchanged at Panmure Liberum this morning after what was described as a "positive set of results". As a writing team, we've been moderately positive here and I can see the case for us to be more positive. Mears is a Super Stock (StockRank 96) and earnings forecasts have been trending upwards for the past year. However, the StockRank value statistics are based on historical numbers only and therefore won't be aware that EPS is about to take a dip as some contracts (e.g. asylum accommodation and the Afghan Relocation and Assistance Policy contract) reach their intended expiration date. As an outsourced service provider, I would expect a modest earnings multiple and the current 10x multiple is in line with what I'd automatically assume is fair value. Given that earnings are expected to trend downwards and the valuation multiple seems about right to me, I'm therefore inclined to leave this on AMBER/GREEN. | |
YouGov (LON:YOU) (£306m | SR63) | YOU expects to deliver full-year performance in line with the previously issued guidance at HY26 results. Intends to commence a buyback after the FY26 results announcement in October, in lieu of FY26 annual dividend (there’s “a dislocation between the Group's intrinsic value and the market value”). Current CEO to become a NED. His successor will join the company in November and become CEO by 1st February 2027. | ||
Frp Advisory (LON:FRP) (£301m | SR56) | 4,916,332 Placing Shares have been placed at 115p. No current director or member of senior management participated in the Placing. | ||
Pensana (LON:PRE) (£238m | SR5) | The Company has received US$15m and is actively engaged in securing the US$150m outstanding. Cascade has advised that it is in continued discussions at the highest levels with its backers, the State of Qatar, and that the funding is nearing completion with the second tranche due shortly. | ||
Petrotal (LON:PTAL) (£229m | SR98) | H1 2026 production averaged 13,726 bopd, tracking 3% ahead of budget expectations. Unrestricted cash of $105.4m. CEO: Q2 production puts the company “in good position to meet our annual production and EBITDA guidance.” | ||
Cab Payments Holdings (LON:CABP) (£196m | SR36) | H1 adjusted profit after tax up 152% to £13.6m. Outlook: “Looking to H2, the Group expects to drive higher client volumes and activity, underpinned by strong client relationships, new market opportunities, and execution of a healthy pipeline…” Remains confident in delivering medium-term guidance. | ||
Galantas Gold (LON:GAL) (£187m | SR25) | Chile's National Geology and Mining Service, the Servicio Nacional de Geología y Minería, has issued approvals relating to the operational restart of the Andacollo Gold project in Chile's Coquimbo Region under its previously authorized operating configuration. | ||
Ferrexpo (LON:FXPO) (£171m | SR n/a) | Following an unscheduled review by tax authorities relating to compliance with currency control restrictions, subsidiary FPM has been issued with a penalty of approximately UAH 35.3 billion (c.US$788 million). FPM is disputing the report’s findings. The penalties remain unconfirmed during the review process. | Shares are currently suspended. | |
Devolver Digital (LON:DEVO) (£79m | SR39) | SP -62%. Proposed cancellation of AIM listing. Tender offer for $5m at tender price 16p. Board has approved a second tender offer for up to $5m within 12 months of cancellation, on similar terms (priced based on an independent third-party valuation at the appropriate time). | TAKEOVER/Desliting (Graham) no section below] These proposed tender offers simply aren’t big enough to compensate for the loss of the listing. Why not seek a buyer for the whole business instead of delisting? It's relevant that the CEO and COO are major shareholders. There is a concert party owning 31% of the company; today's announcement outlines that 25% of the stock is held by insiders, while another 25% is owned by "strategic holders in the games industry". Usually, I trust that a company with a market cap approaching £100m (this was £79m last night) is not at great risk of delisting for no good reason. However, today's note says that "the lack of share price improvement, despite sustained operational improvement, has meant that few of the above equity holders have been willing or able to sell shares into the market. This has impacted staff morale in certain cases." To me, this is a case of the company taking the ball and going home: the share price isn't high enough (not their own fault, naturally) and so they would rather not bother with the listing at all. That's fair enough if they are able to push the delisting through, but it's a stark warning to the rest of us that we need to be even more careful about the delisting risks that may linger in our portfolio. | |
Helix Exploration (LON:HEX) (£68m | SR7) | CEO: "Rudyard has now moved into a continuous filling cycle, underpinning Helix's transition into a revenue generating producer and processor of helium from two revenue centres in Montana and Oklahoma.” | ||
Kromek (LON:KMK) (£52m | SR86) | Successful delivery of the third milestone under its enablement agreement with Siemens Medical Solutions USA, Inc. Has received the third payment instalment of $2.5m. 555,687 options issued to KMK’s CEO and COO with exercise price of 1p (latest share price: 7.92p). | ||
Corero Network Security (LON:CNS) (£42m | SR21) | Revenue +42%. ARR +12% ($24.1m). EBITDA c. $2.6m. Notable contract win post period end ($1.4 million, 3-year contract). “Corero remains well positioned to build on this strong first-half performance, and we are confident in delivering continued growth in H2." | ||
Jersey Oil and Gas (LON:JOG) (£36m | SR28) | The North Sea Transition Authority has approved an extension to the Second Term of the P2170 "Verbier" licence as part of aligning the duration with that of the P2498 "Buchan Horst" licence. | ||
Time Out (LON:TMO) (£33m | SR21) | MO has secured a landmark location at The Crown Estate's 10 Piccadilly development (55 Regent Street) to open Time Out Market London, its first market in its home city. Expected to open in summer 2028. | ||
Fusion Antibodies (LON:FAB) (£13m | SR1) | IP Australia has issued a notice of acceptance in respect of the Company's Australian patent application no. 2019365135. The application covers two families of antibodies, and the methods for designing such antibody libraries. | ||
Tekcapital (LON:TEK) (£10m | SR12) | Net Assets: US$201.7m (Dec 2025: US$55.1m), reflecting portfolio appreciation and disciplined capital allocation. NAV per Share: US$0.78. "H1 2026 has been the most consequential period in Tekcapital's history.” | GN Note: the numbers here are based on an “independent valuation” of the patent portfolio at recent investee Vesari Inc. TEK invested $60,950 in Vesari and its position is now valued at $149,583,0000. | |
Ingenta (LON:ING) (£10m | SR84) | Acquisition of an initial 24.9% equity stake in FirstAida, which has “a suite of AI-based legal software and services”. Initial consideration: 798,000 Ingenta shares. Ingenta has the option to acquire the remaining 75.1%, subject to performance targets, through the issue of c. 2 million new Ingenta shares. Max consideration including defcon is equivalent to c. £2.3m based on Ingenta’s latest share price. |
Graham's Section
TP Icap (LON:TCAP)
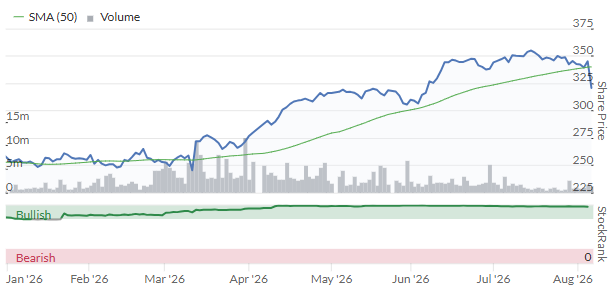
Down 7% at 321p (£2.3bn) - Interim Results - Graham - GREEN =
The market has reacted negatively to these results, but if we zoom out, the share price is unchanged - even a little higher) than it was when we last looked at it in May.
It has given back some of the gains of recent months:
Let’s see what happened at this large broking company in H1:
Revenue +8% at constant currency
EBIT +13% at constant current (£152m)
There are currency headwinds to the above numbers (actual revenue growth only 6%, actual EBIT growth only 9%). The simple explanation is that dollar weakness makes dollar earnings less valuable when reported in pounds sterling.
Outlook: in line with expectations.
We delivered a strong first half financial performance, and demonstrated significant strategic and
operational progress. The Group is well-diversified and built on a modern, scalable platform, and we
have clear opportunities for profitable growth across each of our divisions.
We remain confident in the outlook for 2026, and the Board expects to achieve Adjusted EBIT in line with current market expectations, subject to foreign exchange movements.
Estimates: Cavendish have left their FY26 estimates unchanged, but they increase forecasts for the “outer years” (FY27 and FY28) by 2%.
FY26: adj. EBIT forecast £369m (previously £368m)
FY27: £386m (previously £377m)
FY28: £414m (previously £405m)
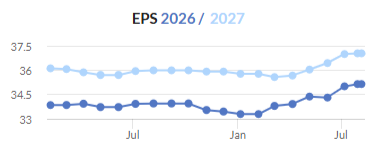
Buyback: a new £30m buyback will also help to boost earnings per share, so that EPS forecasts for future years are raised by nearly 4%. The new EPS forecast for FY27 is 39.5p (vs. 36.2p for the current year).
Graham’s view.
This is something of a head-scratcher. I’m inclined to leave our existing GREEN stance unchanged because the company appears to be doing just fine.
It appears that those trading the stock were expecting another upgrade - which in a year of geopolitical turmoil, especially in the energy markets, has a degree of logic behind it. I can see why there might be some disappointment that an upgrade has not materialised.
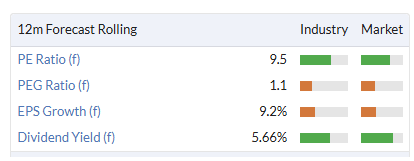
As things stand, the estimates say that revenues will grow 6% this year, and then stay flat in FY27.
So from a growth perspective, there’s little excitement on offer with this one.
From my point of view, the lack of growth is already priced in at this valuation:
City forecasts have been gradually gliding higher, so it’s not as if the business has been underperforming:
It’s not the company’s fault that its share price was pushed up to 350p by people who thought another upgrade was coming. We’ve been GREEN on this and I’m leaving us GREEN on it today.
Roland's Section
Persimmon (LON:PSN)
Up 4% at 1,167p (£3.8bn) - Half Year Results - Roland - AMBER/GREEN =
Today’s results from this FTSE 100 housebuilder are relatively unexciting, but they are in line with guidance and suggest to me the company is getting to grips with the current environment and generating sustainable returns.
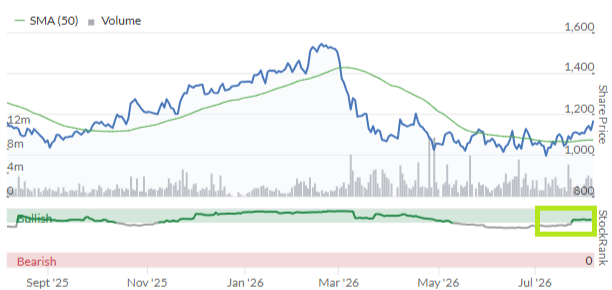
Persimmon shares have now risen by more than 20% from their 52-week lows. I note the StockRanks have also turned positive recently (although this isn’t quite a full Jump):
H1 results: key numbers
The headline numbers in today’s results mostly seem to be moving in the right direction:
Completions: up 13% to 5,189
New home average sale price +1% to £285,752
Revenue up 13% to £1.48bn
Underlying pre-tax profit up 3% to £170.1m
Importantly, we’re given guidance relative to expectations:
On track for completions of c.12,500, at the upper end of previous guidance (consensus: 12,242)
Underlying pre-tax profit expected to be in line with expectations (consensus: £454m)
If I was to be critical, I would point out that completing more houses than expected without a corresponding increase in profits suggests that margins may be slightly lower than anticipated.
That view is borne out in this morning’s results, which show Persimmon’s underlying operating margin falling to 12.8% (H1 25: 13.1%).
However, the more important measure of capital employed is stable, with a statutory figure of 10.6% (H1 25: 9.9%).
Adjustments vs reality: I’ve quoted underlying profit and margin figures above, but fortunately these are fairly close to the statutory numbers – reported pre-tax profit in H1 was £168m, only £2m below the underlying figure.
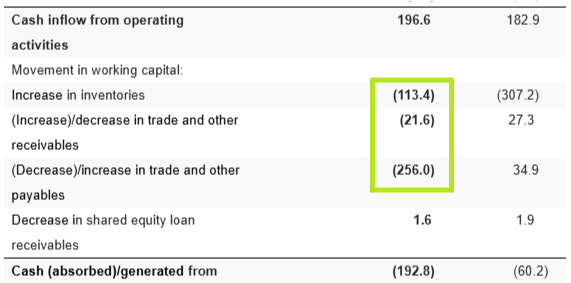
However, there is one niggle here that I think is worth understanding – Persimmon has moved from a net cash position of £117m at the end of 2025 to a net debt position of £165m at the end of June. That’s a £282m cash outflow in six months.
The company says this reflects “a period of investment in the first half” and expects the year-end position to be somewhere “between £100m net debt and £100m of net cash”, in line with previous guidance (although quite a wide range).
Checking the cash flow statement shows the reason for this – a £391m working capital outflow during the period:
Source: Persimmon H1 2026 results
Land purchases: the majority of this outflow relates to land purchases, which totaled £271m during the period. This included £198m related to the settlement of land creditors (deferred payment for previously contracted purchases).
I think this means that the heavy outflow in H1 was a timing effect as much as anything – actual H1 land purchases of 2,110 plots remained well below the 5,729 plots purchased during the same period last year. It looks like the company is remaining selective in adding to its land bank.
Outlook
I don’t have any serious concerns with today’s results. I’m pleased to see volumes improving at the same time as the company is maintaining a satisfactory return on capital (i.e. covering its likely cost of capital).
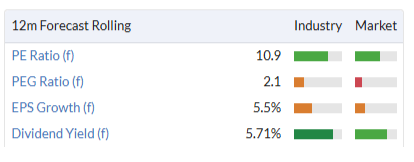
Assuming EPS estimates remain unchanged after today’s results, I think Persimmon shares continue to look reasonably valued:
Roland’s view
Persimmon is relatively unusual in this sector in that it isn’t trading at a discount to book value. However, I think this is more a reflection of its business model and land-buying practices than its valuation.
The only niggle I might have is that I would prefer to see the company maintaining a more unambiguous net cash position. However, I don’t see the current level of borrowing as an issue unless housing market conditions become far worse and volumes dry up – hopefully unlikely.
For now, the combination of a forecast P/E of 11 and prospective 2027 earnings growth of 5% looks fairly attractive to me. The forecast dividend yield of 5.5% also seems fairly safe, unlike the situation at some peers.
While there’s clearly still some downside risk, given the uncertain state of the UK housing market, Persimmon operates at a relatively low average price point with high volumes and appears to be trading successfully in current conditions.
I’m quite comfortable maintaining my previous AMBER/GREEN view today.
WPP (LON:WPP)
Up 25% at 384p (£4.1bn) - Interim Results - Roland - AMBER/GREEN ↑
Former FTSE 100 member WPP is the top riser on the UK market this morning, up by more than 20% following half-year results that suggest performance could be less bad than expected this year.
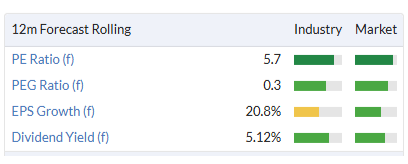
I suspect this is an example of a business that’s simply become too cheap – prior to this morning’s gains WPP shares were trading at less than six times forecast profits. Notwithstanding relatively high leverage, that looks low to me unless you think the business is in terminal decline:
Today’s half-year numbers do not look especially good in themselves, but in this case I think it’s the direction of travel that matters. It also looks like Q2 revenue came in ahead of analysts’ expectations:
H1 revenue less pass-through costs down 4.7% like-for-like (Q1: -6.7%, Q2: 2.8%)
Q2 LFL revenue ahead of analysts’ forecasts for a c.6% decline (see here)
Headline operating profit down 3.4% to £398m
Headline operating margin up 0.2% to 8.4%
Adjusted net debt reduced by 10% to £2,935m
Average adjusted net debt reduced by 2% to £3,304 (2.18x TTM EBITDA)
Regional trading: in contrast to a number of companies I’ve covered here in recent weeks, WPP seems to be trading more strongly outside North America. The company’s largest market by profit was also the only one where comparable profits fell in H1:
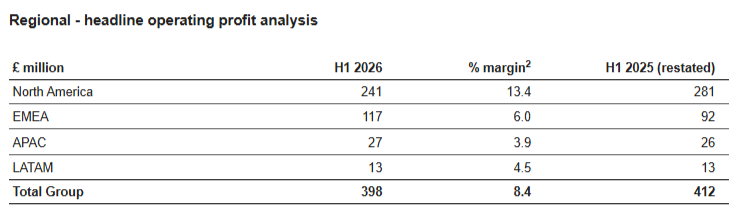
Despite this, the North American market still seems much healthier than WPP’s operations elsewhere based on its profit margins – more than double any other region.
Restructuring progress: the other important element is continued progress with the wholesale restructuring of this business by CEO Cindy Rose, who was previously a senior Microsoft exec and appears to be placing the business on a much more integrated and tech-centric footing:
We are firmly on track with Phase 1 of our Elevate28 plan to stabilise the business. Our objective for the first half was to put in place the building blocks of the new organisational structure and this is now complete. We are successfully transitioning from a complex holding company to a single, integrated company - with four operating units across four regions, all underpinned by WPP Open, our agentic marketing platform, which enables and connects everything we do.
Big ad groups like WPP historically operate as a group of semi-autonomous agencies, acquired over many years. Rose appears to be unwinding this model and integrating or disposing of many of WPP’s operating businesses.
Cash proceeds from disposals are expected to top £200m this year and the company says it’s making progress on “further potential asset disposals”. Press reports suggest this could include the group’s remaining 40% stake in market research agency Kantar.
Outlook
The main elements of WPP’s full-year guidance appear to be unchanged today, but I think it’s fair to say that Q2 and H1 revenue were at the upper end of expectations. If this trend continues, the full-year decline in LFL revenue could be smaller than expected.
This guidance also implies a big improvement in profit margins in H2:
H2 LFL revenue less pass-through costs to decline by “low to mid-single digits”
2026 headline operating margin: 12% to 13% (vs 8.4% in H1)
Total cash restructuring costs of c.£250m
Now expect disposal-related activity to generate cash proceeds of at least £200m
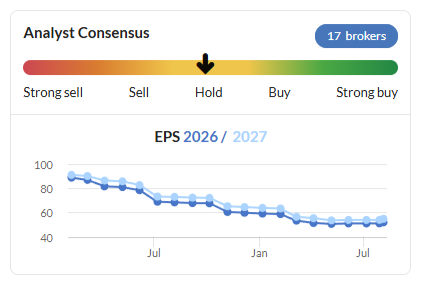
I don’t have access to broker forecasts today, but my guess is that we could see some modest upgrades to EPS estimates over the coming days. Consensus estimates have already edged higher recently, according to the StockReport:
Roland’s view
Assuming no changes to 2026 EPS estimates today, WPP now trades on a 2026E P/E of 7.4 with a 3.8% dividend yield. If earnings have bottomed out – as forecasts suggest – then this could be an attractive entry point for this business, in my view.
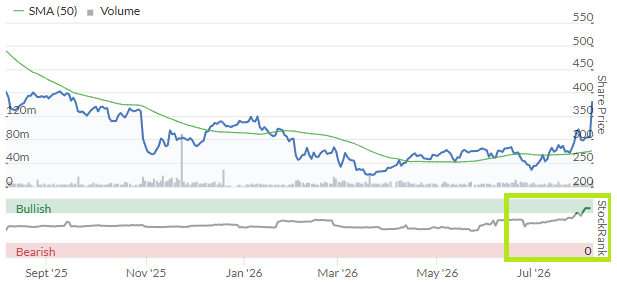
After all, today’s share price gain has only taken the stock back to where it was a year ago:
While I think the internet and AI have probably permanently changed this business, WPP remains one of the largest companies of its type in the world. It’s interesting to remember just how far its shares have fallen – down by nearly 80% in 10 years:
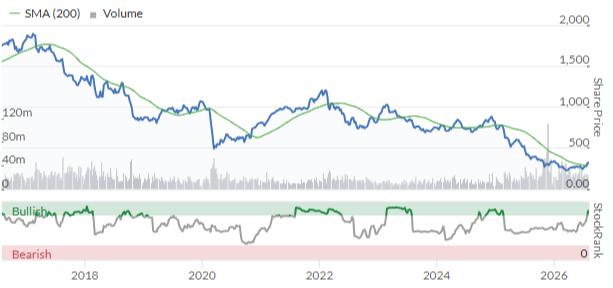
The recent increase in StockRank may also be encouraging:
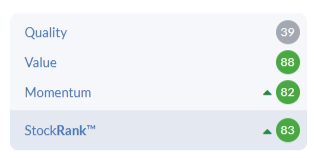
High Value and Momentum ranks indicate a Turnaround. But if margins continue to recover and improve the company’s quality metrics, this could become a Super Stock.
The last time we covered WPP was one year ago, when I took an AMBER/RED view following a profit warning.
The shares are back where they were 12 months ago, but I think quite a lot has changed in the business since then. I’m going to take a chance and move our view up by two notches to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Good article on Osb (LON:OSB), Paragon Banking (LON:PAG) and Shawbrook (LON:SHAW)
https://substack.com/inbox/pos...
Hargreaves Lansdown (HL) Maybe I expect too much, but as a shareholder of Amaroq (Amaroq (LON:AMRQ) within an HL account I have today been messaged:
'Amaroq Ltd – Exchange Change
Amaroq Ltd has moved its listing from the Alternative Investment Market (AIM) to the Main Market of the LSE as of 31 July 2026. For more information, please see the company announcement.'
To get such a message some 6 days after the event does not, to me at least, reflect that well on HL.
Thanks for sharing your views on Osb (LON:OSB) , Graham. Disappointing today, watching a large chunk of your paper profits going up in smoke, but it’s not the end of the world. Nothing wrong with the business and it still looks cheap (cheaper?) with a very acceptable yield. Carry On Holding.
re: TCAP. That's covered now!
TP Icap (LON:TCAP) (I hold) could be a buy at this level, although I prefer to wait to see signs of an upturn before jumping in.
TP Icap (LON:TCAP) is one I have owned and followed, and noticed it always travels well and then sells off on results announcements. Time to buy is therefore usually after results.
Thanks, l topped up today.
Everplay (LON:EVPL) looking interesting, share price looks bombed out and priced to go bust! Near enough 50m net cash, what am I missing? Recent update in line and seemed ok
I have held Everplay (LON:EVPL) previously, sold at profit and now looking to re-enter. As you say, shares appear friendless at the mo. Maybe the 2nd half weighting, recent in line statement and delay to HLLV game contribute? Look decent value and a bid may appear at these levels....
I see bestwick has been a large seller last couple of years, overhang fears maybe?
I have bought and sold Everplay (LON:EVPL) over the years since it was Team17, keeping a small position but have been slowly increasing my position all year. Computer gaming stocks are rare in the UK and unlike Frontier Developments (LON:FDEV), Everplay (LON:EVPL) is more diversified (more lower cost games) and pays a dividend. Like Murray suggests this could attract on offer at this price given the number of mid caps currently being bought up. Keyword Studios was bought about 2 years ago.
Excellent trading update today from Corero Network Security (LON:CNS) .
They aren't just another virus and malware detection company, they screen out the unwanted traffic generated from multiple sources as a result of infection by the above. They manage to "wash" incoming network data to prevent access being denied to legitimate users by sheer volume of bad traffic generated by robot software on multiple hosts as a result of infection. They partner with multiple companies such as Juniper Networks -now owned by HP .
A drop in turnover and earnings as a result of changing to a subscription model has hit the share price recently but this is now working its way through to the bottom line and a much improved, Ebitda positive, year end is predicted.
I recently listened to an impressive interview of the CEO on ZEUS.
You might consider commenting on why Tritax Big Box REIT (LON:BBOX) [I hold] have gone down so sharply today. the company seems an interesting long-term investment, with their forthcoming data centres near Heathrow etc. And good barriers to entry with excellent niches, and, as fare as I can tell, good management.
I was looking to get in here as some of the billions released from the Segro takeover must surely flow towards BBOX. The equity issue provides a nice little dip so bought a few today.
Hardly a sharp drop for Tritax Big Box REIT (LON:BBOX) at 4% is it nettle? Personally I consider it a minor correction in line with the extra share subscription, Slightly opportunistic as the SP had increased closer to the NAV perhaps? But as a bigger player with good Data Centre pipeline and working capital requirements to fund seems a smart move. Hopefully the market will acknowledge this and push the SP back up once the extra shares have been digested and the funds start to be deployed.
Isn't the price change mostly because they are offering £350m of new shares at 164p, so the open market has drifted towards that price? I assume this was simply the price they found institutional investors were willing to pump £350m in at when being asked to move quickly
thanks for all these answers. sensible and helpful!
Tekcapital (LON:TEK) (I hold) Setting aside the astonishing (unbelievable?) valuation of Vesari, TEK still has a share price less than 50% of its NAV. Significant elements of the components of this NAV are based on stock market valuations. The NAV position will be clearer if Guident achieves is planned IPO this year.
I held a few years ago.Sold because I lost all faith in the manager.
I'm not surprised you lost faith! All of the Tekcapital (LON:TEK) investments that have made it to a stock market quote have failed miserably. They each appear to have been floated way too early and with insufficient capital to reach profitability.
The Versari holding looks incredibly suspicious to me. We are supposed to believe that Clifford Gross gifted 51% of this vehicle to Tekcapital (LON:TEK) and low and behold a couple of months later some IP valuation service says says Versari's IP is worth $293m!!! Well that's nice, isn't it? So generous of Dr Gross too. In other news, flying pigs have recently been seen circling the offices of Tekcapital (LON:TEK)!
I cannot say what I think about Gross in a public forum. To be fair I got a discount on the glasses with built in speakers and they do work! I was lucky to get out without a loss when I sold TEK when yet another placing happened.
Bodycote (LON:BOY) bid does not seem that generous to me, but with two bidders then the price could go higher. Not sure why the board are recommending them, they should be trying to get the best deal.
We've been having a version of this same conversation on The Shareholders Board recently. I think it's a combination of not properly aligned director incentives and pressure from UK institutional owners for liquidity events to boost performance and/or pay redemptions.
For those with an interest in risky pre-profit growth stocks, suggest taking a look at Ceres Power Holdings (LON:CWR) and reviewing against Bloom Energy (NYQ:BE) . If you believe the technology case - it is off around 50% from recent highs, may have just broken the downtrend and now has positive news. Valued around 2% of the EV of Bloom. Licensed model rather than going it alone.
RE :OSB
The reason for the fall in profit is given in the paragraph. My bold...
"Profit before tax reduced to £187.2m (H1 2025: £192.3m) due to a higher impairment charge and higher administrative expenses which more than offset an increase in net interest income and a lower fair value loss on financial instruments"
NIM is one metric to be concerned about. OSB is currently looking at NIM circa 220 whilst I seem to recall that Paragon is in the region of 300.
For me however, the biggest concern is the higher impairment charge. I doubt that the BTL market is going to improve any time soon.
Hold neither OSB or Paragon.
I recently wrote about Figma,. (NYQ:FIG) as an interesting play on a relatively new IPO for design tool. Since then their shares are up around 25% but last nights results threaten to throw most of the gain away (down 15% pre market).
Beat revenue and increased guidance for the year but increased costs around AI and compensation packages have weighed heavy. I still think the future is bright for them and this may present as a good buying opportunity as I feel its overdone - the compensation pay outs are just par for the course. But will keep an eye on margins going forward.
Would welcome thoughts on Osb (LON:OSB) I hold and am still 20% up after today’s fall but wondering if now might be the time to bail out?
Another day, another whack. That’s three in a week. Today it’s the turn of Osb (LON:OSB. Down heavily on a reduction in net interest margin. Other than that I can’t see anything to get worked up about, but the market disagrees. I would welcome your views, Graham.
Osb (LON:OSB) : "We have seen strong competition in the retail savings market and elevated retail funding costs so far this year."
Well, it depends whether you think this is temporary or permanent. Do they just not have a good enough franchise to attract retail deposit inflows anymore? Or is it just temporary competition in the market? A permanently lower NIM, if that is the case, is something to be "worked up about" as a shareholder.
More worryingly for non-OSB shareholders... is this because overall savings demand in the market has dropped, hence increased competition for a smaller pool? That would be worrying as it has implications for UK consumer financial health. Or is it OSB-specific and they're losing out market share to competitors in the deposit space?
Actually there is a strong case to be made that the UK savings rate is far too high recently and this is holding back growth - Neil Woodford has talked a lot about this. If we could unlock some of these savings it could give a real boost to the economy.
With respect to OSB, yes there seems to be increased competition for retail saving and this is pushing up their funding costs - I don't see how OSB have any particular moat with attracting savers so I am personally staying away from this stock.
Indeed. All the neobanks and smaller FIs have jumped on the retail funding bandwagon.
Over the past year, I've been approached by a few banks looking to hire roles to spearhead their customer acquisition activities for saving deposit accounts. The competition ferocity is definitely heating up. So not surprised there will be losers who aren't doing as good a job...
Its nuts that even Santander Group is offering 4.5% instant access savings (via their subsidiary Cahoot).
I don't think the moat is in attracting savers but efficiency in loaning money without going to market.
I would wager their BTL lending is down due to government overregulation in that market.
Most buy to let landlords are selling at least part of their portfolio. Can't see why anyone would move into that market given the government changes. I think the market for Osb (LON:OSB) is down a lot and will keep drifting down until the regs are changed.
Same every year on results ..then it claws it's way back
Another positive update from Persimmon (LON:PSN) today. Compare and contrast recent updates with other housebuilders like Taylor Wimpey (LON:TW.) who have been issuing profits warnings.
Persimmon is the only housebuilder I hold now, and it’s one to buy or add to on weak spells for the share price. Housebuilders are classic cyclical investments to look to buy on the big dips and take advantage of big share price gains and dividend increases when the eventual recovery comes.
Persimmon (LON:PSN) we’re paying £2.35 a year in the last boom period for housebuilders. Share price then in 2021 peaked at nearly £30. So it’s down around 60% from that peak now. Current dividend of 60p a year is still a useful 5.6% while holding and waiting patiently for the upturn.
TP Icap (LON:TCAP) (no holding) I provocatively suggest all a little underwhelming ? whilst nothing wrong, with their main customers knocking the ball out of the park shouldn't these numbers be a little more impressive ...im struggling a little to see the attraction and not much to change my mind today but be very happy to hear im wrong.
TP Icap (LON:TCAP)
I have a holding here - if i am being frank i dont really know how they make their moeny i was simply doing some bottom feeding and rating looked "cheap" and theer was potential to list part of their buisnes in us (i think) - its rerated nicely so p/e is nearly up to 10 now - normally tahts not expensive but must i dont have much of a handle on hos sustainable their earnings are - earnings have materially ramped up so i am guessing the market is slightly worried what some of they have now may not be sustainable long term perhaps ? its tricky to make much sense of the outlook - it seems confident - but then they throw in the dreaded phrase.
To support this, we intend to maintain the flexibility to invest for profitable growth
I get it that one often has to invest for growth - but its often a cover stroy for spending more now as the current stuff wont provide reasonable organic growth in line with inflation.
as ever well could brokers have bad news lined up for future years ? overall though if the current earnings are sustaniable thats good news - i do slightlky worry though with tehnn above phrase - te proof of ten pudding is pobably what brokers say about next year compared to their opinion before today - they will have access to better tealves than me.
I could be tempted to bank my profit and move on but with p/e of 10 or less if there are no hidden broker nasties i may hang around. shame we cant get a bit more straight talking warts and all northern grit ref what is really happening under then bonnet - £260 mill is decent profits though - lets see how brokers adjust 2027 expectations today if its buisness as usual thats a decent update.
TP ICAP - they have a great stock rank. A lot of money in the bank and a decent dividend too. I wonder if they are cheap enough to entice a buyer from across the pond? I have held for a while and considering they were 245p in March, today's 20p drop to 325p isnt a big deal
No news on Parameta float and return of the proceeds of that to shareholders at all? Before it was said that market conditions were not right. If they are not right now one wonders just what they have to be for the sale to proceed? Or has it all quietly been dropped....?
TP Icap (LON:TCAP) Personally I was a bit surprised they proposed to sell Parameta. I would have thought it belongs better within the group than outside, and they may be having second thoughts.
TP Icap (LON:TCAP) Solid results IMHO with 8% growth despite US/Iran conflict impact. The transformation is clearly working - more digitisation, increased efficiency taking out costs and releasing capital. This is delivering widening margins, another £30m share buy-back, dividend +8% and bolt-on acquisitions.
The creation and development of a series of trading platforms Fusion, Liquidnet (incorporating Neptune) builds a strategically strong market position and improves quality of earnings.
Disappointing that it appears that the Parameter float is on permanent hold. They'll need to get it growing in order to attain the lofty valuations that have been attributed to this division.
On a p/e of 9.5 and yielding 5+% this is a cheaply rated growth stock.
Mr Market hasn't liked these results - down 22p to 323p as I post -6.4%.
Now down 8.77% disappointing and no comment from Stocko writers.
Agreed. Can you feature tomorrow per chance, Graham and Co please?
As TP Icap (LON:TCAP) was a very luckily timed buy the big dip buy for me at £1.06p I won’t be selling despite being underwhelmed by their update today.
The 17% dividend yield at the £1.06p buy price (assuming the final is at least held) is worth having every year. And there’s a risk that TCAP could be yet another UK Company to fall to a foreign bid.
Disappointment is the flat Parameta performance which makes a US listing unlikely unless that eventually improves.
Also this section from their update today might well also explain the negative share price reaction:-
“Cash flow
The Group's net cash balance at the end of the period was £652 million, compared to the previousyear-end closing balance of £903 million on 31 December 2025. Over two-thirds of the movement incash reflects a £174 million change in net settlement balances contained in working capital, which wastemporary and reversed immediately after the period end.
Other working capital outflows of £96 million (H1 2025: £128 million) reflected an increase in accounts receivable, following higher revenue,and the payment of annual bonuses. As a result, the operating cash outflow in the period was £77million (H1 2025: cash inflow of £24 million).
Notable investing and financing activities during the period included capital expenditure of £42million (H1 2025: £36 million), the increase largely due to office fit-out costs for our new Manila andBelfast hubs. We also acquired Vantage Capital Markets for a cash consideration of £22 million, paiddividends of £84 million, and almost completed the £80 million share buyback announced in March.”
EPS growing 10% and on a PE under 10 with a 5.5% yield - I'd say this this looks reasonably compelling. Wil add some if it falls any further. I can't say I understand the business particularly well but on the numbers it looks good value.
My guess is the market is unwilling to rate voice revenue that high and evidence that information and electronic are long term compounders (exchange like) is slow to emerge so that rating of 10 might look optically cheap but .... it's also normal for a company whose revenue faces technological challenges. The history of currency trading is the main concern. I think.
I’m a long time TCAP holder, and have added today. The results look fine to me. I always worry about very old litigation returning to bite the firm, but there is no sign of that here.
TCAP benefits from volatility. I think that’s like to come in spades once the autumn comes round. I’m amazed that it has escaped a bid so far.
To me TCAP is a financial plumbing provider, giving price transparency when called for, or secrecy when it is preferred. It is a necessary service, but is becoming almost entirely IT based rather than voice. It is a people business, so bonuses have to be expected.
Why are Diageo (LON:DGE) reporting in the middle of the day? Is it because they have a dual listing?
might be the excuse but bad news travels slowly.....
Offer deadline for Spire Healthcare (LON:SPI) takeover today - wonder how that will play out ?
There was also an after hours update / share offering from Tritax Big Box REIT (LON:BBOX) yesterday, would appreciate any thoughts!
Tritax Big Box REIT (LON:BBOX) I hold
I happened to see the RNS about the intention to raise money via a placing after the market closed yesterday. I posted the news here at the time. I noticed that there was a retail offer but when I checked the Retail Book web site, the BBOX placing wasn't listed. I then received an email to say that AstonGirl had replied to my post. When I read her response I saw that another RNS had been issued a few minutes after the one I posted about. This provided the details I needed to enable me to apply through my broker as I happened to have some spare cash in my iSA.
Whilst the short notice is frustrating, it's a good thing for small investors to be offered the same terms as the big boys. For them, investing is a 24 hour business. As a small investor I suppose. we have to accept that we may need to make quick decisions if we want to be offered the same terms as them. We are not a company's top priority when it comes to raising money and opportunities can come out of the blue so it's helpful to set up alerts to RNS's on the stocks you are interested in. You also need to have some cash waiting to invest!
They raised the money at a slight discount to the market price of £1.64. £350m to invest in data centres. They sate they have secured a further 235MW of grid connection agreements. I hold as BBOX are developing a decent Data centre portfolio. With the loss of SEGRO (LON:SGRO) BBOX is now the main play. Data centres are not universally popular but I feel they are important to help the UK transform in many ways including net Zero (I note the irony of the energy they use in this comment). I am involved in monitoring river water quality, concerns about the environment etc through our local Citizen Science group.
Well done Stockopedia for alerting us by James Fox study on the 24th June, of what an attractive investment opportunity Bodycote might prove to be. I am kicking myself for not acting on the information, rather than just reading it today.
Please could you cover Mears (LON:MER) H1 results this morning? Looks like steady progress.
That's noted, Paul! Thanks
Diageo (LON:DGE) have their FY results out today as well but at 10am I think
Morning Alex, we'll keep an eye out for these.
Roland