Foxtons - running hard to stand still, while racking up the debt.
Analyst’s view:
This looks like a fairly poor quarter, although there is a specific reason for the lettings weakness. Zooming out, the company looks to be running hard to stand still, with acquisitions required to offset the impact of weakness in the UK housing market. Trading profits for FY26 are said to be in line with expectations. However, these were slashed earlier in the year. With just the seasonally weakest quarter to go, an in-line statement isn't unexpected, but we don't get an update on net debt, and the previous trends were not encouraging.
The risks, as I see them, are with FY27. If UK house prices fall in response to recent interest rate increases, they will face further pressure on sales fees. For lettings, things should be more robust, and smaller landlords exiting the sector in response to the higher regulatory burden may provide a medium-term tailwind for rents. However, in the short term, the impact may be fewer properties to let.
This is undoubtedly a cyclical business, and at some point will turn upwards. However, there are few signs that they are managing to arrest the near-term dive, despite pulling on the yoke as hard as they can. It looks like we didn't review the company after the big profits earlier in the year, so this is a belated reduction in our view from me today, but one also backed by more recent trends.
+1% to 36p - Q3 2026 Trading Update
It is well known that the UK housing market has been pretty weak for sales transactions for several years now. Like many estate agents, Foxtons has responded by focussing on the lettings side of the market.
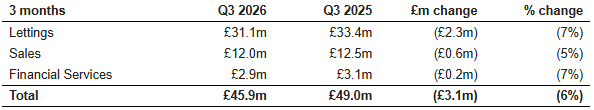
However, in this quarter lettings revenue also takes a back step:
There are specific reasons for this:
Q3 revenue declined by £2.3m, or 7%, to £31.1m, after a £2.7m impact from elevated tenant-led early terminations following the introduction of the Renters' Rights Act ("RRA") on 1 May 2026, as previously flagged at the Interim Results
They say they would have grown revenue without this effect, but also highlight that £1.0m of that revenue came from acquisitions, so LFL organic revenue is down.
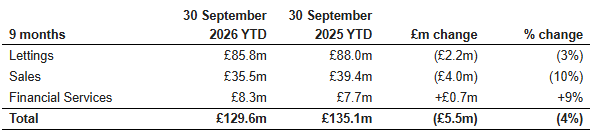
Both lettings and financial services look better on the 9m comparison:
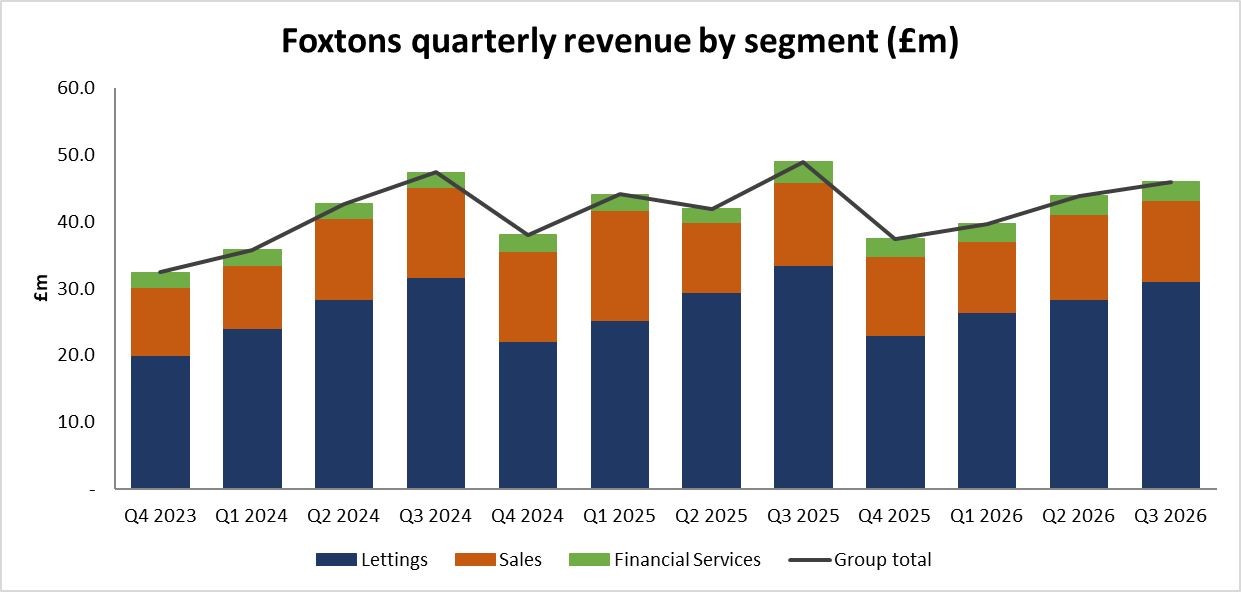
There is a considerable seasonal aspect to Foxton's business, and Q3 is always the strongest quarter:
On a rolling 12-month basis, the trends are largely the same:
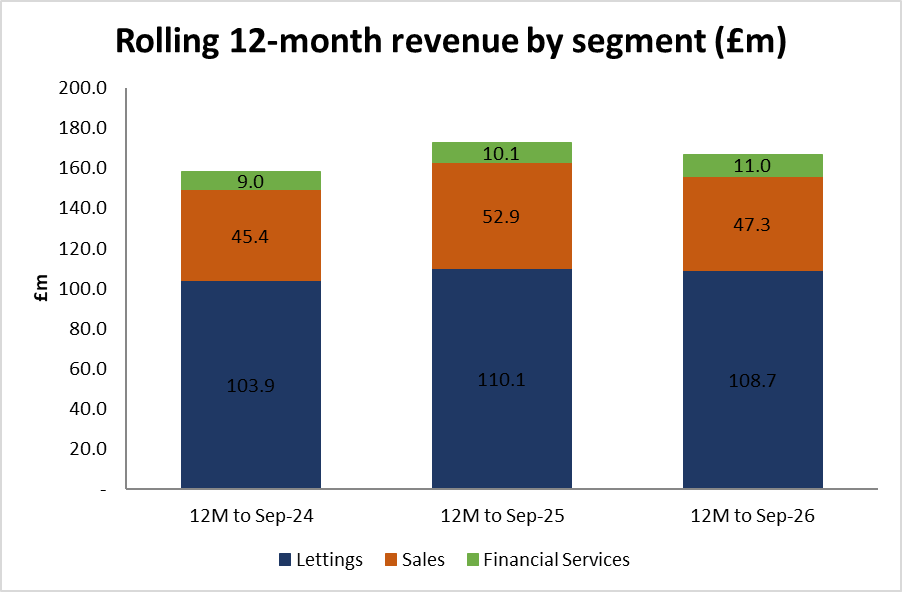
On sales, they say:
Foxtons' like-for-like transaction volumes remained broadly stable. Still, average revenue per transaction declined 8%, reflecting a mix weighted towards lower-value properties, as higher mortgage rates impacted buyer affordability at higher price points.
This is with largely flat house prices. I expect revenue to decline further if we see any actual house price falls.
The reality is that there is little sign of recovery in any of their markets, and acquisitions and any inflationary price increases are just offsetting the impact of a weak housing market.
While the impact of tenant-led early terminations may have largely abated, I wonder where growth in lettings will come from, with many smaller landlords looking to exit the market given the increased regulatory burden. In time, this may lead to strong rent increases as supply is removed from the sector, but this will take time to work through the market.
Profitability:
There is also an update on profitability:
The Group is trading in line with management's expectations and expects full-year adjusted operating profit to be within the £17m to £19m range guided in July.
While on the surface this may be good news, the July update was a major profits warning:
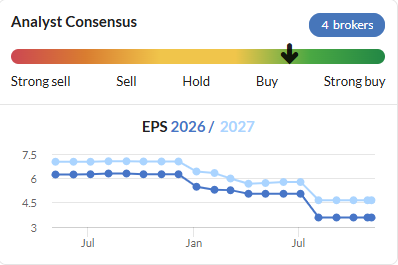
With Q4 the historically weakest quarter, things would have had to go seriously wrong for a further downgrade.
However, unless these trends improve, I still see risks to the FY27 numbers.
Balance sheet:
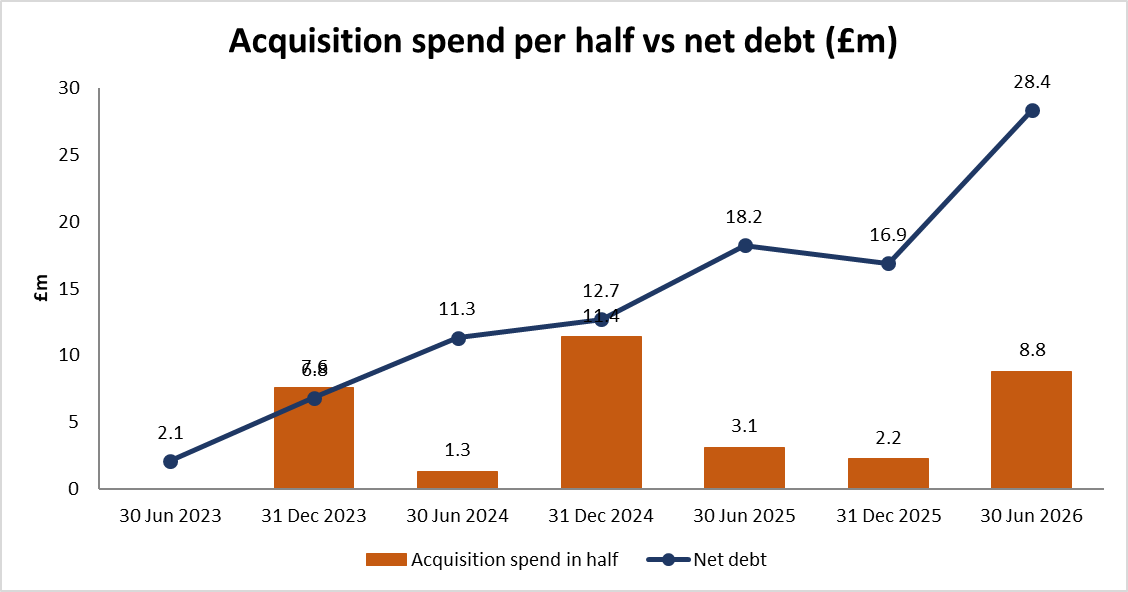
The company don't give an update on net debt in this quarterly update. However, net bank debt has been rising over the past few years, largely driven by acquisitions. This took a further jump at the half-year:
A cumulative look at this suggests they have generated little free cash flow over this period:
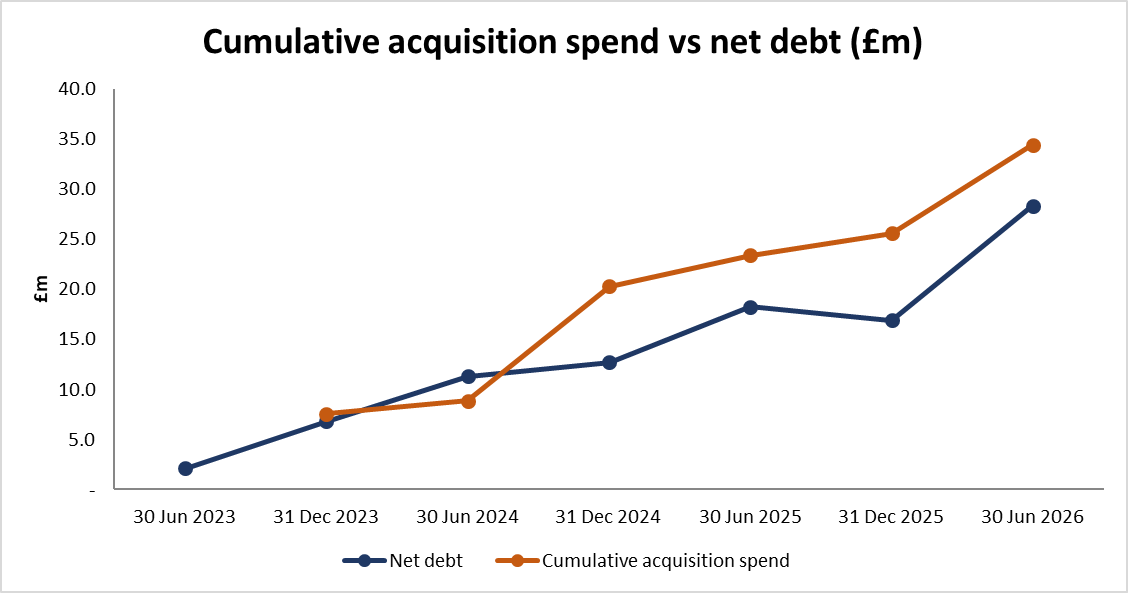
There has been a 3% dividend, which is ok, but nothing to write home about, and a share buyback at the end of 2025 and into 2026. However, in hindsight, they appear to have destroyed shareholder value by buying back shares at a premium to today's price using debt, which will have to be repaid through future cash flow.
They said they completed four further acquisitions in September, so I wouldn't be surprised to see net debt jump in the future. Panmure Liberum see net debt staying largely static into the year-end at £27.4m excl. leases. However, again, the forecast reduction into Fy27 looks at risk to me. Especially if they continue to try to offset revenue declines with further acquisitions.
While the absolute level of debt may not be a solvency risk at the moment, it could well start to restrict shareholder returns if it increases any further.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Foxtons (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?