FRP down 3% on a declining cash balance and modest H2 outlook

Analyst’s view:
Trying to piece together the slight drop in the share price today (assuming it's not random noise), my best guess is that it has been triggered by the sharp fall in the cash balance, which is only partially explained by the EBT (the cash balance fell by over £10m in six months, with only £5.6m having been loaned to the EBT). It's also worth highlighting that H2 might be noticeably quieter than H1. FRP has already achieved 53% of the full-year revenue forecast, and 52% of the full-year EBITDA forecast, and yet it hasn't raised expectations today. So while H1 got a boost from the Autumn budget, and there is no similar catalyst expected in H2. We've been moderately positive on this share but I am struggling to find too many reasons to get involved at the current share price - so let's switch to neutral.
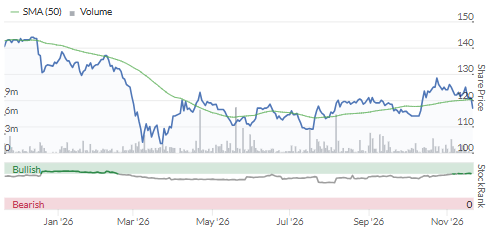
Down 3% at 117p (£303m) - Half Year Trading Update
Today's update says that FRP is "on track to meet current full year expectations" but the share price has nevertheless dropped by a few percentage points.
This is a professional services firm focusing on restructuring advice, corporate finance, and related advisory services. It competes with BTG Consulting (LON:BTG) (Begbies Traynor).
H1 has been quite good:
Revenue +13% (£98m)
Underlying adjusted EBITDA +9% (£25m)
Net cash has taken a hit: from £26.2m in April, it fell to £15.5m by the end of October. This is also slightly lower year-on-year (it was £16.5m in October 2025).
A partial explanation is provided:
In the half FRP loaned the Employee Benefit Trust (EBT) £5.6m to buy back FRP shares that will be used to satisfy share option awards under the Group’s Long Term Incentive Plan (LTIP) to help retain key people including those who join via acquisition.
Even with this being a loan, there is a real cost involved. I certainly wouldn't want to look past this.
Remember that all of the "adjusted" profit measures, such as adjusted EBITDA, exclude the impact of share-based payments.
Outlook
Before stating that they are on track to meet expectations, FRP gives us a macro comment:
Across the UK, business confidence remains subdued following the 2026 Autumn Budget, with continued uncertainty around costs, investment and the wider economic outlook. Firms operating in the UK continue to face cost pressures from people costs, debt service, suppliers and energy; as well as navigating the impact of technological and AI disruption. FRP’s range of specialist services support clients at every stage of the corporate lifecycle.
As a restructuring specialist, it's not necessarily bad news for FRP if business confidence is subdued in the short-term.
Consensus estimates (FY April 2027): revenue of £184m and underlying adjusted EBITDA of £48m.
Thanks to Cavendish for publishing a new note today - the basic EPS estimates (not accounting for dilution) are 11.5p for FY27 and 11.9p for FY28. So the earnings multiple is about 10x.
CEO comment (excerpt):
“In the first half there was a solid contribution from our Corporate Finance business, with many deals completing ahead of the Autumn Budget...
We continue to pursue disciplined and profitable compounding growth through a combination of organic expansion, selective acquisitions, and investment in our infrastructure and people.”
Graham's view
Trying to piece together the slight drop in the share price today (assuming it's not random noise), my best guess is that it has been triggered by the sharp fall in the cash balance, which is only partially explained by the EBT (the cash balance fell by over £10m in six months, with only £5.6m having been loaned to the EBT).
It's also worth highlighting that H2 might be noticeably quieter than H1. FRP has already achieved 53% of the full-year revenue forecast, and 52% of the full-year EBITDA forecast, and yet it hasn't raised expectations today.
So while H1 got a boost from the Autumn budget, and there is no similar catalyst expected in H2.
I also consider that the curent earnings multiple of 10x is quite full for a professional services firm.
So overall, there are good reasons for the share price to lose some momentum at current levels.
We've been moderately positive on this share but I am struggling to find too many reasons to get involved at the current share price - so let's switch to neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on BTG Consulting (1)
Comments here are also visible in the Daily Stock Market Report
Frp Advisory (LON:FRP) I'd say this looks very good value at current price - consistently growing at more than 10% yet trading on a PE of about 9 and with a near 5% dividend yield. It should also act as a useful hedge in the event of an economic slowdown given its focus on insolvency. It's true that as a professional services firm it will probably never attract a premium rating, but it has previously commanded a PE ratio of around 14-15 so I'd argue it looks undervalued at current share price. Everything is down today so I don't think the slight fall today is due to anything in the update - all looks pretty positive to me.