Funding Circle Holdings upgrades earnings guidance again, pre-tax profit now 10% higher

Analyst’s view:
Leaving aside a couple of minor quibbles, I'm confident that today's upgrade is material and highlights the strong momentum in this refocused business. The valuation continues to look reasonable to me given the improved profitability of the business, so I'm leaving our moderately-positive view unchanged.
Up 12% to 234p (£685m) - Trading Update
In January I upgraded our view on this SME lender to AMBER/GREEN, following a previous upgrade to earnings.
Today we have another upgrade to earnings, suggesting the strong momentum reported previously is continuing.
The CEO is brief but positive today (my emphasis):
We’ve carried the strong momentum seen in the first half of 2026 into the autumn, and SME demand has remained resilient despite continued macro uncertainty. As a result, we are upgrading our FY26 expectations.
Key points:
H1 momentum has continued into H2, with "sustained market demand and ongoing feature innovation".
We now expect FY26 revenue to be at least £275m with profit margins of c.16%. This implies pre-tax profit of at least £44m.
Previous guidance was FY26 revenue of £255m and pre-tax profit more than £40m (i.e. at least 15.7% margin).
The £25m share buyback announced in September is ongoing, with £5m purchased so far. In total, Funding Circle has now repurchased 19% of its share capital since commencing capital returns.
EPS estimate: Broker Cavendish has issued a brief note today but has not yet updated its forecasts.
Today's upgrade is equivalent to a 10% rise in forecasts, so I would guess that a revised FY26 EPS estimate might be in the region of 12p.
Roland's view
I'm not completely sure of the tax situation here, as broker forecasts I can see seem to imply a much higher rate of tax than that shown in the company's half-year results. I'd want to clarify this before investing.
Another point to note is that a new CEO is due to start work in the coming months, so it may be worth looking out for any change to strategy or disclosure in the results.
Leaving these minor quibbles aside, today's upgrade is clearly material and highlights the strong momentum in this refocused business.
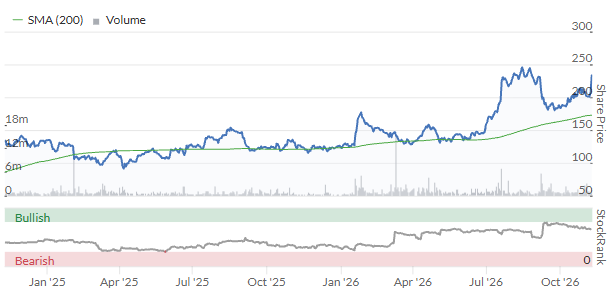
While specialist lending always carries some risk, Funding Circle's half-year results highlighted the increasingly attractive profitability of this business:
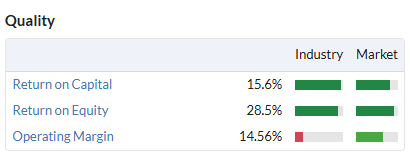
With a price-to-book ratio of c.2.9x after this morning's gains, I think some of the good news is already priced in. But I'm happy to maintain my previous AMBER/GREEN view today given the strong momentum on display here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Funding Circle Holdings (2)
Comments here are also visible in the Daily Stock Market Report
That would be Funding Circle Holdings (LON:FCH) and Watches of Switzerland (LON:WOSG)
yes it would