Gear4music: revenue up 6%, but warehouse costs cut first-half EBITDA to £5.7m
Analyst’s view:
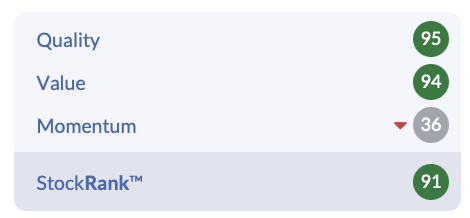
The market doesn’t like today’s update from G4M. But it’s not terrible – revenue growth of 6% in this environment is respectable. Now, this stock does look cheap today and the StockRank is a high 91. However, there is not much earnings growth forecast in the medium term and the share price trend is starting to look ugly. Given the lack of momentum here, I’m going to downgrade the stock from GREEN to AMBER/GREEN.
Down 5% at 220p (£49m) - Half Year Trading Update
Online music retailer Gear4music has today provided a half-year trading update for the six months to 30 September 2026.
Highlights:
Total revenue of £85.4m, up 6% (in line with Board expectations against very strong prior-year comparatives)
UK revenue of £51.0m, up 3%
European and Rest of the World revenues of £34.4m, up 11%
Gross margin expected to be 27.6% (FY26 H1: 28.0%; FY25 H1: 26.7%)
Gross profit expected to be £23.6m (FY26 H1: £22.6m; FY25 H1: £16.5m)
EBITDA expected to be £5.7m (FY26 H1: £6.5m; FY25 H1: £2.9m), reflecting the previously reported setup costs associated with the new automated UK warehouse
"We are pleased to report further revenue and gross profit growth in the first half, building on the significant progress achieved in FY26 and against very strong prior-year comparatives. Our performance reflects the strength of our customer proposition in a challenging environment for discretionary consumer spending.”
Operational update:
“We continue to invest in our e-commerce platform and operational capabilities to support sustainable, profitable growth over the medium and longer term. The development of our new automated UK warehouse continues to progress and is an important part of this investment, with the anticipated initial setup costs reflected in our first-half earnings.”
Outlook:
“We are well prepared for the important peak trading period. With this key part of the year still ahead, the Board continues to expect the Group's financial performance for the year ending 31 March 2027 to be in line with consensus market expectations."
* Gear4music provides these figures for consensus market expectations for the year ending 31 March 2027: revenue of £200.2 million, EBITDA of £16.0 million and profit before tax of £6.0 million.
Ed’s view:
The market doesn’t like today’s update. At one stage, the stock was down 8%.
It’s not a terrible update though. Top-line growth of 6% is respectable in this environment (a 'challenging environment for discretionary consumer spending') and the growth from Europe and Rest of the World is decent at 11%.
On the downside, we learn that EBITDA for the period is expected to be £5.7m versus £6.5m a year earlier. This reflects the previously reported setup costs associated with the new automated UK warehouse.
The company believes that this warehouse will help to support sustainable, profitable growth over the medium and longer term. However, investors are often turned off by investments to support growth.
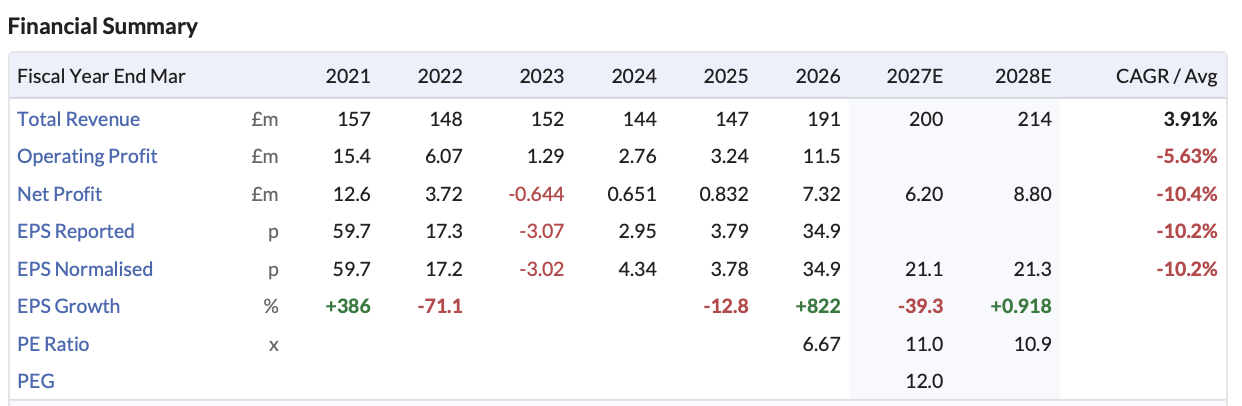
Now, the valuation here is quite low at present (Stockopedia gives G4M a 94 for value). With analysts forecasting EPS of 21.1p for FY27 (versus 34.9p in FY26), we are looking at a P/E ratio of about 10.4.
However, analysts don’t expect much earnings growth in the medium term. For FY28, the EPS forecast is 21.3p.
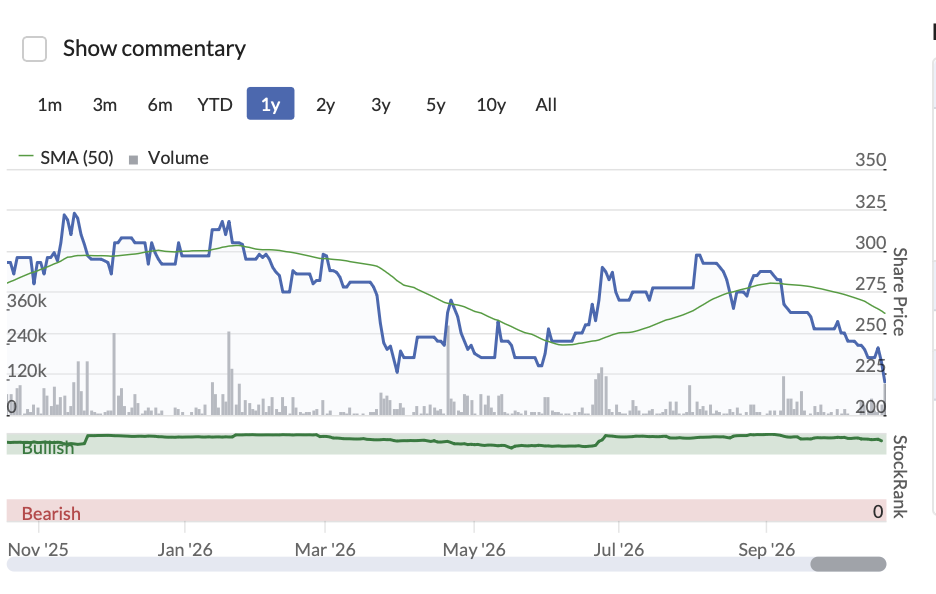
Looking beyond the financials, the share price trend is beginning to look a little ugly. Right now, the stock is trading below its 50-day and 200-day moving averages (and we just had a bearish ‘death cross’ pattern where the 50-day crossed below the 200-day).
The StockRank is also falling. In early September it was 98 whereas today it’s 91.
One other potential negative worth highlighting is brand engagement. Today, Gear4music only has 118k subscribers to its YouTube channel versus 1.06m for Andertons.
They could definitely do more here. Because YouTube can be a great platform for exposure, brand engagement, and sales (I’ve personally bought several guitars from Andertons in recent years on the back of their fantastic YouTube videos).
Given the lack of earnings growth and the falling share price, I’m going to downgrade G4M to AMBER/GREEN today. It does look cheap, however, the momentum is weak.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Gear4music (HOLDINGS) (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?