Daily Stock Market Report (Tue 20th Oct 2026) - CRPR, WIX, G4M, SBRE, BPM

Budget speculation is now in full swing ahead of next Wednesday, 28th October.
According to the BBC, citing Treasury sources, Chancellor John Healey is refusing to entertain CGT increases.
Some of the items that I’ll be looking out for in the Budget include:
Increased taxes on the gambling sector
Your First Home and its positive impact on the housebuilders
Changes to taxes on ecommerce (The Times reported last week that “Amazon, eBay and Temu will be forced to collect VAT to fund business rate cuts for high street shops”)
Overnight market movements:
The FTSE is down 0.6% at 10,705
S&P 500 is unchanged at 7,690
Brent crude (December) is up 1.4% at $110.95/bbl
Gold is down 0.5% at $4,120oz
Bitcoin is down 0.4% at $81,600
Ed Sheldon joins me today.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BHP (LON:BHP) (£158bn | SR90) | Copper production was lower in Q1, reflecting planned grade declines, scheduled maintenance, disruptions from severe weather, stops for safety, and the conveyor failure at Carrapateena. The bulk commodities delivered a strong start to FY27. Full-year guidance remains unchanged. | ||
Anglo American (LON:AAL) (£46bn | SR71) | Operational performance was resilient across the business. Copper production decreased by 5% to 174,900 tonnes. Premium iron ore production decreased by 4% to 13.8 million tonnes. The sale of the Steelmaking Coal business in Australia to Dhilmar is on track to complete by Q1 2027. Teck merger continues to progress. On track to meet 2026 guidance. | ||
Bunzl Public (LON:BNZL) (£8.9bn | SR93) | Group revenue grew by 3.1% at constant exchange rates. Underlying revenue increased by 3.7%. Operating margin was in line with the company's expectations. The group continues to perform in line with expectations and reiterates its full year outlook. | ||
Zegona Communications (LON:ZEG) (£3.9bn | SR77) | Robert Samuelson, Zegona's Chief Operating Officer, passed away peacefully but very unexpectedly yesterday. | ||
Plus500 (LON:PLUS) (£2.3bn | SR61) | Plus500 has conditionally agreed to acquire the full ownership of Guru Corretora de Títulos e Valores Mobiliários Ltda, a regulated broker-dealer in Brazil. This acquisition provides Plus500 with a direct local presence in Brazil and further accelerates its growth strategy in Latin America. | ||
Oxford Nanopore Technologies (LON:ONT) (£2.1bn | SR45) | The company has appointed Sebastian Kronmueller as Chief Business Development Officer (CBDO), effective 4 January 2027. He joins from Philips, where he is Head of Strategy and Ventures. | ||
Genuit (LON:GEN) (£731m | SR54) | Revenue for the nine months ended 30 September 2026 of £464.5m was up 3.5% YoY year on a reported basis and down 4.3% on a like-for-like basis. Strong balance sheet with leverage of 1.5x at end September 2026 and no near-term maturities. As a result of challenging market conditions, the group now expects full year underlying operating profit to be approximately £84m (in its May update, it guided to the lower end of £94.7m and £105.5m). | PROFIT WARNING | |
Galliford Try Holdings (LON:GFRD) (£677m | SR95) | Galliford Try appointed to £5.0bn Pagabo Major Works framework. | ||
XP Power (LON:XPP) (£496m | SR68) | Q3 order intake was £106.8m, 22% higher than the preceding quarter and 93% higher than the comparative period in constant currency. Q3 revenue was £63.8m, up 12% on the preceding quarter and up 10% on the comparative period in constant currency. Net debt at 30 September 2026 was £4.5m. FY26 expectations remain unchanged. | ||
Wickes (LON:WIX) (£490m | SR86) | “With our strong sales performance and with a good productivity plan in place, we are on track to meet consensus expectations which on average show a growth in adjusted PBT of c. 10% for 2026.” | AMBER/GREEN ↑ (Graham) | |
Gulf Keystone Petroleum (LON:GKP) (£489m | SR76) | Operational & Corporate Update & Gulf Keystone to combine with ShaMaran Petroleum | “Following completion of the Transaction, shareholders of Gulf Keystone and shareholders of ShaMaran will each own approximately 50% of the shares in the Combined Company.” | TAKEOVER |
Sabre Insurance (LON:SBRE) (£452m | SR86) | Full-year earnings guidance reiterated, with profit before tax for 2026 expected to be slightly higher than 2025. | AMBER/GREEN= (Graham) | |
GB (LON:GBG) (£362m | SR48) | H1 revenue of £139.5m (up 1.4% at constant currencies). H1 adjusted operating profit reduces to £27m (H1 last year: £29.5m). FY27 outlook is in line with recently revised market expectations. | ||
Tharisa (LON:THS) (£356m | SR99) | The operating subsidiary, Tharisa Minerals, received its first wheeled renewable energy from Etana Energy in September 2026. The initial supply is expected to meet approximately 10% of the Tharisa Mine's current monthly electricity demand. | ||
Capita (LON:CPI) (£356m | SR18) | Postponing its Capital Market Event, previously planned for 4th November, as the Group maintains its focus on improving the service delivery on the Civil Service Pension Scheme contract. | ||
Optima Health (LON:OPT) (£268m | SR42) | H1 revenue approx £96m, c. 60% ahead of H1 last year, reflecting an acquisition and growth. Trading remains in line; on track to deliver FY27 results in line. | ||
B.P. Marsh & Partners (LON:BPM) (£241m | SR64) | NAV per share 1,048.5p (Jan 2026: 1,009.9p) after payment of £13m of dividends (36.29p per share). Consolidated PBT £22.8m (H1 last year: £32.1m). Liquidity of £37.4m. | AMBER/GREEN= (Graham - I hold) | |
Gulf Marine Services (LON:GMS) (£213m | SR54) | 9-month period: adjusted revenue +10%, adjusted EBITDA flat ($81.5m). Net leverage ratio 1.55:1. “We maintain our guidance for the Adjusted EBITDA for 2026 to be in the range of US$ 105 - 115 million, assuming the geopolitical situation doesn’t materially impact vessel utilization.” | ||
Trifast (LON:TRI) (£117m | SR83) | Trading in the current financial year to date is in line with market expectations. Revenue decline moderated to 4.2%. | ||
James Cropper (LON:CRPR) (£67m | SR93) | H1 ahead of expectations. Now expects full-year Adjusted EBITDA to be approximately 10% to 20% ahead of current market expectations of £9.4m. | AMBER/GREEN= (Ed S) | |
Gear4music (HOLDINGS) (LON:G4M) (£49m | SR91) | H1 revenue +3%. “Revenue growth in line with Board expectations against very strong prior-year comparatives”. EBITDA £5.7m. Continues to expect FY27 to be in line. | AMBER/GREEN↓ (Ed S) | |
Rockfire Resources (LON:ROCK) (£19m | SR23) | Molaoi zinc deposit in Greece. Laboratory results from hole HMO-021 have been received. “Multiple zinc intervals were encountered including a considerable zone of 11m width.” | ||
Shearwater (LON:SWG) (£17m | SR77) | New £1.7m contract with an existing Central Government customer to provide threat intelligence capabilities. | ||
IXICO (LON:IXI) (£17m | SR23) | Revenues up 28% to £8.3m, beating market expectations. Year-end order book £16m. EBITDA loss “is expected to improve on market expectations”. |
Edward's Section
James Cropper (LON:CRPR)
Up 6% at 740p (£67m) - Trading Update - Ed S - AMBER/GREEN =
Advanced Materials and Paper & Packaging specialist James Cropper has today provided us with a trading update for the six months ended 26 September 2026 (H1 FY27). Here’s what it has told us:
The group delivered a strong performance during H1 FY27, with trading ahead of the Board's expectations, principally reflecting a much stronger than anticipated performance by the group’s Paper & Packaging business from a combination of revenue growth and cost management.
As a result of the performance delivered in the first half, together with the Board's current assessment of the outlook for the remainder of the financial year ending 27 March 2027, the Board now expects full-year adjusted EBITDA to be approximately 10% to 20% ahead of current market expectations of £9.4 million.
This gives a range of expected full-year adjusted EBITDA of approximately £10.3 million to £11.3 million.
“The progress reflects the benefits of the actions we have taken to improve operational performance alongside continued positive momentum across the group. As a result, our expectations for full-year adjusted EBITDA have increased by 10-20%.”
Ed’s view:
We’ve covered James Cropper here at Stockopedia a few times this year. In early January, Roland looked at it in a Stock Pitch (this is a useful report if you’d like to learn more about this niche business).
Then, in April, Roland covered a full-year trading update. At the time, he upgraded the stock to an AMBER/GREEN rating on the back of an improved balance sheet and earlier-than-expected recovery in profitability.
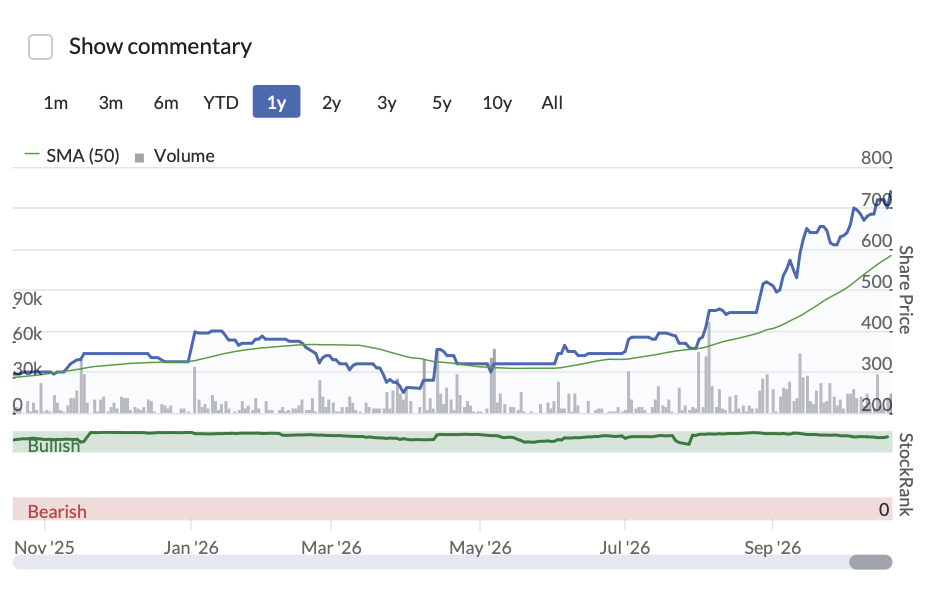
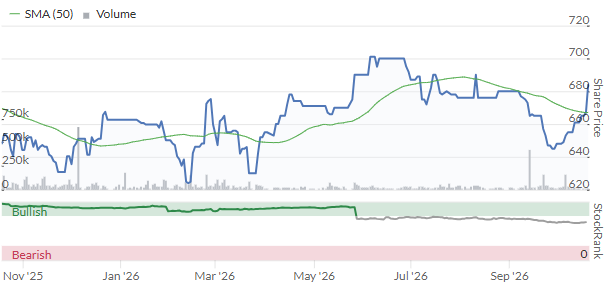
Since that upgrade, the stock has performed really well, rising from around 355p to 740p – a gain of more than 100%. Note that Stockopedia rates it as a ‘Super Stock’ and gives it a StockRank of a high 93.
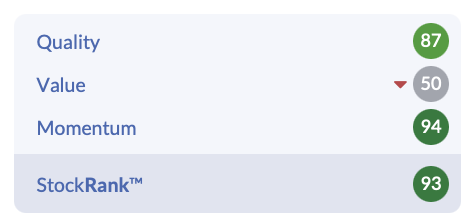
Now, today’s update has resulted in a decent move higher (+6% as I write) and it’s easy to see why. In H1, trading during the period was ahead of the Board’s expectations thanks to a strong performance in Paper & Packaging driven by a combination of revenue growth and cost management (in September we heard that this division was seeing high demand from established customers augmented by new business wins, accelerating the momentum delivered in the second half of FY26).
As a result, the group is now expecting full-year adjusted EBITDA of approximately £10.3m to £11.3m (versus market expectations of £9.4m). For reference, adjusted EBITDA was £8.9m in FY26 and £6.7m in FY25, so we have a clear upward trend in profitability here.
Note that the midpoint of the guidance range (£10.8m) would represent year-on-year growth of 21%. The upper point of the guidance range would represent growth of 27%.
Given the increase in profitability, I think the risk/reward proposition here still looks relatively attractive, despite the big move higher in the share price this year. Going into today’s report, brokers were looking for 45.6p per share in earnings for FY27 versus 30.8p in FY26.
Assuming that the EPS forecast moves higher after today’s update, we are probably looking at a low-to-mid teens P/E ratio here. I see that as reasonable given the profit growth – the price-to-earnings-to-growth PEG) ratio is going to be well under one.
On the downside, revenue growth forecasts are a little underwhelming. For FY27, revenue is expected to be £102m, which would only represent growth of 2.7% year on year (in September the company told us that Advanced Materials revenue remains broadly in line with the same period in the prior year).
There’s also a little bit of debt on the balance sheet – at 28 March, net debt was £8.1m (down from £12.9m a year earlier). This should be manageable though (using the mid-point of today’s adjusted EBITDA guidance range of £10.8m we get a net-debt-to-adjusted-EBITDA ratio of 0.75).
Overall, I’m positive on the outlook here. I’m going to leave the stock on AMBER/GREEN.
Gear4music (HOLDINGS) (LON:G4M)
Down 5% at 220p (£49m) - Half Year Trading Update - Ed S - AMBER/GREEN ↓
Online music retailer Gear4music has today provided a half-year trading update for the six months to 30 September 2026.
Highlights:
Total revenue of £85.4m, up 6% (in line with Board expectations against very strong prior-year comparatives)
UK revenue of £51.0m, up 3%
European and Rest of the World revenues of £34.4m, up 11%
Gross margin expected to be 27.6% (FY26 H1: 28.0%; FY25 H1: 26.7%)
Gross profit expected to be £23.6m (FY26 H1: £22.6m; FY25 H1: £16.5m)
EBITDA expected to be £5.7m (FY26 H1: £6.5m; FY25 H1: £2.9m), reflecting the previously reported setup costs associated with the new automated UK warehouse
"We are pleased to report further revenue and gross profit growth in the first half, building on the significant progress achieved in FY26 and against very strong prior-year comparatives. Our performance reflects the strength of our customer proposition in a challenging environment for discretionary consumer spending.”
Operational update:
“We continue to invest in our e-commerce platform and operational capabilities to support sustainable, profitable growth over the medium and longer term. The development of our new automated UK warehouse continues to progress and is an important part of this investment, with the anticipated initial setup costs reflected in our first-half earnings.”
Outlook:
“We are well prepared for the important peak trading period. With this key part of the year still ahead, the Board continues to expect the Group's financial performance for the year ending 31 March 2027 to be in line with consensus market expectations."
* Gear4music provides these figures for consensus market expectations for the year ending 31 March 2027: revenue of £200.2 million, EBITDA of £16.0 million and profit before tax of £6.0 million.
Ed’s view:
The market doesn’t like today’s update. At one stage, the stock was down 8%.
It’s not a terrible update though. Top-line growth of 6% is respectable in this environment (a 'challenging environment for discretionary consumer spending') and the growth from Europe and Rest of the World is decent at 11%.
On the downside, we learn that EBITDA for the period is expected to be £5.7m versus £6.5m a year earlier. This reflects the previously reported setup costs associated with the new automated UK warehouse.
The company believes that this warehouse will help to support sustainable, profitable growth over the medium and longer term. However, investors are often turned off by investments to support growth.
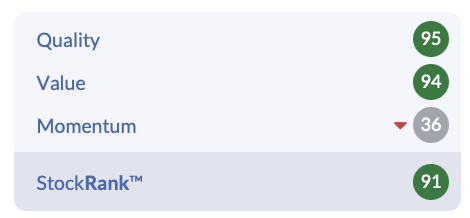
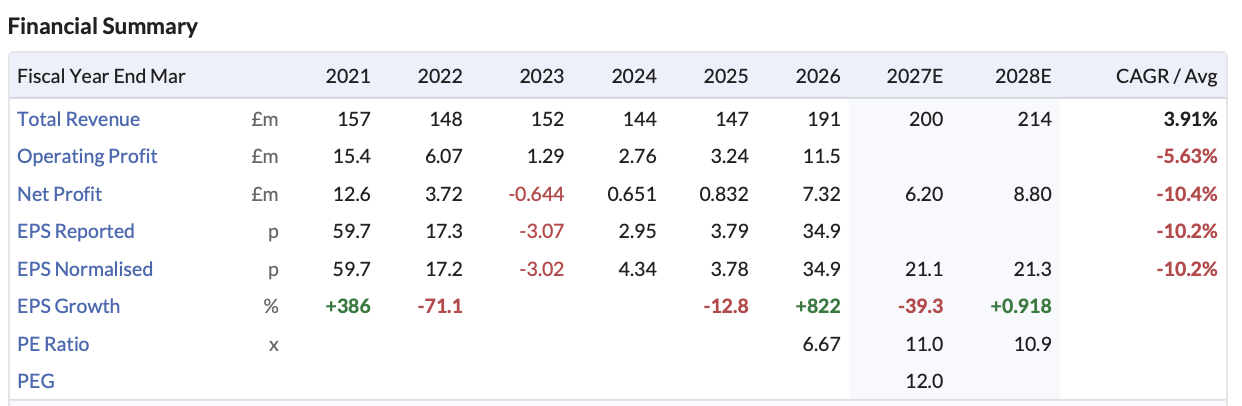
Now, the valuation here is quite low at present (Stockopedia gives G4M a 94 for value). With analysts forecasting EPS of 21.1p for FY27 (versus 34.9p in FY26), we are looking at a P/E ratio of about 10.4.
However, analysts don’t expect much earnings growth in the medium term. For FY28, the EPS forecast is 21.3p.
Looking beyond the financials, the share price trend is beginning to look a little ugly. Right now, the stock is trading below its 50-day and 200-day moving averages (and we just had a bearish ‘death cross’ pattern where the 50-day crossed below the 200-day).
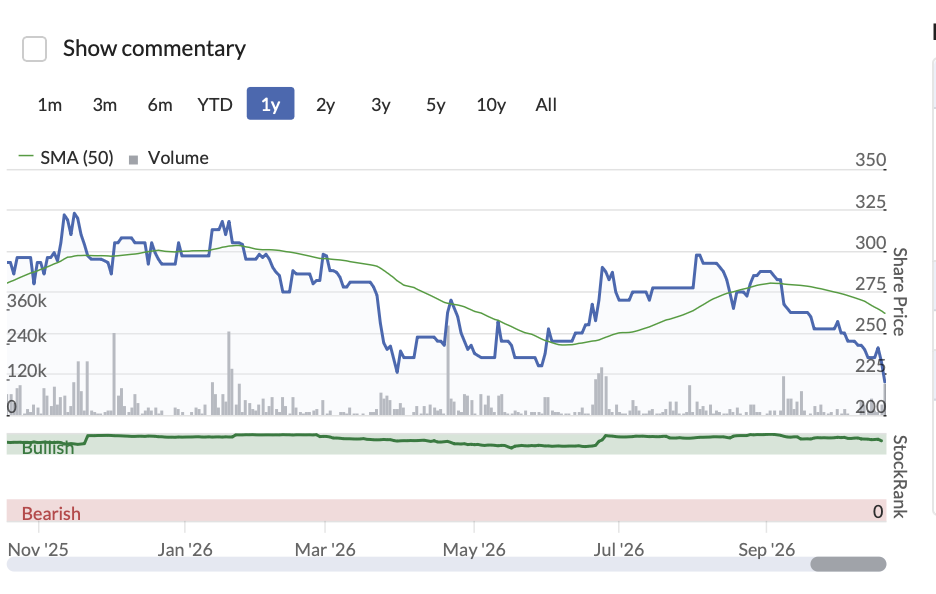
The StockRank is also falling. In early September it was 98 whereas today it’s 91.
One other potential negative worth highlighting is brand engagement. Today, Gear4music only has 118k subscribers to its YouTube channel versus 1.06m for Andertons.
They could definitely do more here. Because YouTube can be a great platform for exposure, brand engagement, and sales (I’ve personally bought several guitars from Andertons in recent years on the back of their fantastic YouTube videos).
Given the lack of earnings growth and the falling share price, I’m going to downgrade G4M to AMBER/GREEN today. It does look cheap, however, the momentum is weak.
Graham's Section
Wickes (LON:WIX)
Up 4% at 224.2p (£510m) - Q3 Trading Update - Graham - AMBER/GREEN ↑
We don't cover this one very often; let's try to rectify that a little.
Today's update is confident: "On track to meet market forecasts for 2026 adjusted PBT"
This table provides a lot of detail: what I'm going to take away from it is that year-on-year revenue growth trends have been improving as the year progressed. 1.8% growth in Q1, 2.3% in Q2, and now 4.5% in Q3.
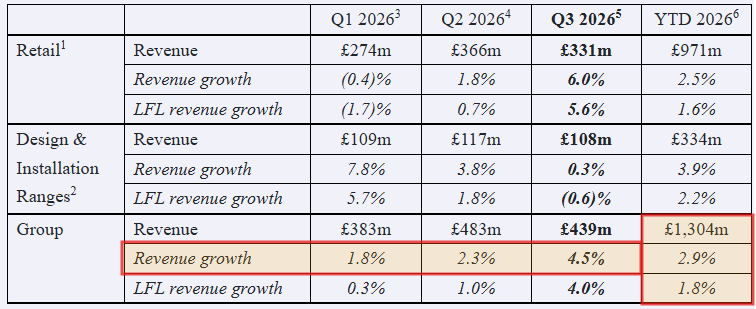
The "second derivative" is therefore positive: not only is the company is growing, but the growth rate itself is improving.
The other key takeaway for is that the "Retail" segment is doing much better than "Design and Installation Ranges". As we don't cover Wickes too often, let's get a precise definition of this:
Design & Installation Ranges revenue includes all product categories which could be sold as part of a design and/or installation and where the majority of sales of those products are designed and/or installed. This relates principally to projects such as kitchens and bathrooms, sold by our Design Consultants, as well as Wickes Solar.
Any other interesting snippets from today's update?
Within Retail, TradePro sales were up 8%. TradePro membership also up 8%.
Design & Installation: "our Bespoke Kitchen ranges are seeing customers being more considered for larger purchases".
In 2026, Wickes will open 5 new stores (total estate is around 230)
Outlook:
Our value-led and differentiated business model leaves us well-positioned to continue outperforming the market. With our strong sales performance and with a good productivity plan in place, we are on track to meet consensus expectations which on average show a growth in adjusted PBT of c. 10% for 2026.
Graham's view
I have a generally positive impression of recent performance at Wickes. They say they are taking market share, which seems to ring true from the growth figures shown.
There is a little consumer hesitiation when it comes to larger projects, especially high-end kitchens ("Bespoke Kitchens"). This is not the company's fault - just a reminder of how economically sensitive the sector is.
Forecasts have held steady here for a while, with only a gentle downward slope in EPS forecasts seen earlier this year:
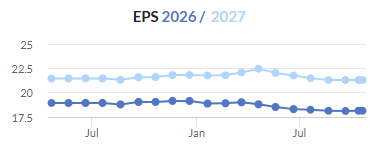
At at PE ratio of 10x, I was inclined to leave us neutral on this share.
However, I've just checked the full-year results for 2025 and this year's interims, and I see that the company's average net cash position last year was £153m.
In H1, the net cash position closed at around the same level. At a £500m market cap, this is a significant number,
Yes, there are significant leases involved here - but I'm still willing to give Wickes a lot of credit for having a £150m cash balance. It covers about a quarter of the present value of all future lease liabilities.
The company has been paying out an attractive dividend yield, covered by earnings:
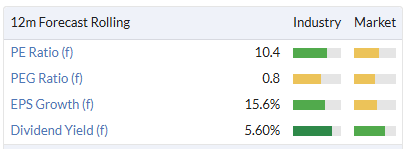
Considering the acceleration in the growth rate, the strong cash balance, and the reasonable valuation, I'm willing to bump up our stance on this to a moderately positive one.
Sabre Insurance (LON:SBRE)
Down 9.5% at 167.8p (£409m) - Trading Update - Graham - AMBER/GREEN =
Sabre Insurance Group plc (the "Group" or "Sabre"), one of the UK's leading motor insurance underwriters, today provides an update on trading for the period from 1 July 2026 to 30 September 2026.
At first glance, this trading update looked fine to me - "Full-year earnings guidance reiterated, with profit before tax for 2026 expected to be slightly higher than 2025"
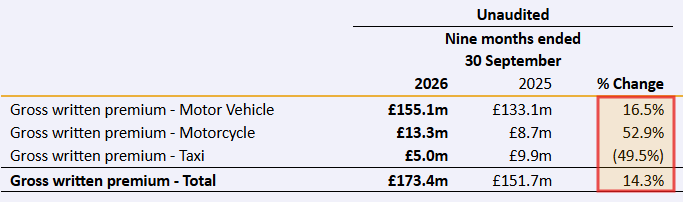
However, checking the note from Panmure Liberum, I see that they have in fact reduced their GWP (gross writen premium) estimate for the current year by 2.3%, from £236m to £231m.
The new estimate represents year-on-year growth of a little less than 14%.
The growth rate so far this year has been better than that, at 14.3%:
FY27 and F28 also see GWP shaved by small amounts (estimates cut by 0.4%).
Thankfully, the company's pre-tax profit estimates for each year have only received the slightest of trims, e.g. the current year's PBT estimate moves from £52m to £51.9m. Slightly better than last year's £51m result.
So I think it is fair to say that profit is tracking in line. The PBT cut is not material.
The more interesting line is the revenue line - why the pullback in growth expectations?
The company does explain why this is happening, without explicitly telling us that revenue might miss expectations:
Full-year earnings guidance reiterated, with profit before tax for 2026 expected to be slightly higher than 2025
Year-on-year premium growth is expected for the full-year, although growth is likely to moderate in the final quarter as Sabre's pricing discipline is maintained
In the market trends section, they tell us that claims inflation is still running at between 6% and 7%, and that "pricing does not appear to have kept up with the level of claims inflation".
As a result, "Material market-wide price increases are likely to be required to cover claims inflation, which we expect to provide additional momentum to our growth, although the timing remains uncertain".
In other words, Sabre thinks that other insurers have not yet raised prices to the level required.
And in the short-term, to maintain "pricing discipline", they are going to sacrifice some growth. Either growth or profitability needs to be sacrificed, and they have chosen growth.
The CEO comment emphasises this philosophy:
"I am very pleased with our performance through the first nine months of 2026. Our continuing focus on "profit as the target and volume as an outcome" underpins our confidence in delivering a strong full-year result, which we expect will be slightly ahead of 2025.
We have maintained pricing discipline, strong premium volumes and a robust solvency position despite continuing weak market conditions.
We will continue to apply this discipline and focus as we move into 2027 rather than pursue volume for its own sake.
Graham's view
I appreciate this philosophy. An insurer's job is not to pursue growth for the sake of growth. Their job is price their policies sensibly and generate ROE.
Sabre has been doing this:
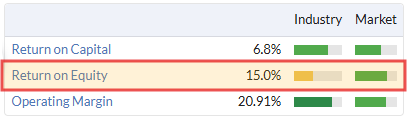
In August, at the full-year results, Roland was moderately positive on the stock. The market cap is a little lower today as the market digests the disappointment of slightly lower growth. But in the big picture, I expect that little has changed. So I'll leave Roland's moderately positive stance in place.
PBT growth might limited for the next couple of years, but I suspect that the main attraction here is actually the yield. The majority of EPS gets paid directly to the company's shareholders:
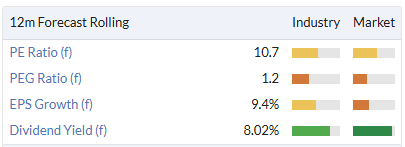
B.P. Marsh & Partners (LON:BPM)
Up 1% at 676.4p (£244m) - Half-year Results - Graham - AMBER/GREEN=
[At the time of publication, Graham has a long position in BPM.]
B.P. Marsh & Partners Plc (AIM: BPM), the specialist private equity investor in early-stage financial services businesses, announces its unaudited Group Half Year Results for the six months to 31 July 2026...
We already had an H1 update from BPM in September.
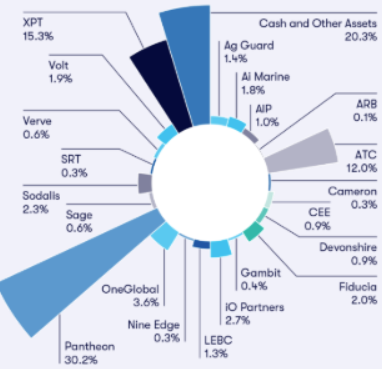
That day, I reduced our stance on the stock as it seemed to me that the growth at the main investee, Pantheon Specialty, was tracking a little below par. This single investment - where BPM owns 41% of it - is worth about 30% of BPM's total assets.
So my main interest in these half-year results is any update relating to Pantheon.
But first, the big picture:
BPM's NAV improves to £372m (Jan 2026: £360m), despiting paying £13m of dividends.
Fully diluted NAV per share increases to 996p (Jan 2026: 959.8p).
So there's been plenty of progress to maintain the upward trajectory of NAV and NAV per share over the six-month period, despite the dividends paid.
And the discount to NAV per share, at the current share price, is 32%.
That level of discount says very clearly that the market is nervous about BPM's portfolio valuations, its skill at managing the portfolio, or both! As a shareholder here, I do think the market is perhaps being too timid.
CEO comment from Dan Topping:
“I am pleased to report another strong period for B.P. Marsh. The first half of the financial year saw us convert value built up across the portfolio into cash, delivering meaningful returns to shareholders while continuing to invest for future growth...
Our approach builds on the partnership-led model established by Brian Marsh OBE, which has delivered compound NAV growth of 10.9% a year since flotation, after distributions. With £37.4m of available cash, no debt and a robust pipeline, the Group remains well placed to continue delivering long-term value for shareholders.”
One thing I do appreciate very much about BPM is how they have managed the problem of cash drag. A victim of their own success, they've had "too much" cash on their books, but have gradually reduced it via new investments (both debt and equity) and dividends. It strikes me that £37m is probably still a little too high.
Pantheon: I don't see anything new in today's section on Pantheon:
...Pantheon has established itself as a high-quality, scalable independent specialty broking platform with a growing reputation for the placement of complex risks. Revenue is budgeted to approach £27.7m in the 2026 financial year, compared with approximately £23.8m in 2025, with strong margins and significant cash generation supporting continued reinvestment and growth. Pantheon remains the largest contributor to the Group's NAV, demonstrating the significant value created since the Group's original investment.
The metrics here are quite remarkable:
Date of initial investment: June 2023
31 July 2026 valuation: £112,360,000
Cost of Equity: £32,800,025
Equity stake: 41.0%
Pantheon's weight in the portfolio now exceeds 30%:
Group Outlook is strong:
"With £37.4m of Group funds at 31 July 2026, no debt, a growing income base and a robust pipeline, the Group remains well positioned to balance selective new investment with continued returns to shareholders, and to support its entrepreneurial management teams as they grow their businesses."
Graham's view
I am happy to continue holding a small position here, as the 32% discount to NAV does look rather excessive to me.
Even if Pantheon Specialty turned out to be worthless, and was given a valuation of zero, the stock would still be trading at a discount to NAV (the Pantheon investment is valued at £112m, while the gap between NAV and market cap is £128m).
So I think that BPM's share price already punishes it more than enough for not having a very concentrated portfolio.
I could be wrong, of course. But the track record here is genuinely outstanding. So this is a bet I'm personally very comfortable with. I'll leave us on AMBER/GREEN for now, as I wait for a fresh update on Pantheon.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
re B.P. Marsh & Partners (LON:BPM) This article on buyouts and M&A might be of interest as background info on the state of play, even if it does not mention their direct holdings
B.P. Marsh & Partners (LON:BPM)
cheers useful summary and it can only be good for BPM if the trend is towards acquisition of the ready made entity type that BPM is helping incubate. How big is to big to buy in though ?
Ocado (LON:OCDO) Was going to short these, then they started rising.
Never step in front of a bus going the other way, so I abandoned that idea.
I assume someone is going to bid, but who would take on this car crash?
the mighty house of JP Morgan have upgraded target price to 460p today.
Stockopedia team request/suggestion for an article:
Stockrank is based on the market that the share is in.
What about dual-listed companies? eg Wise (LON:WISE) that is listed in New York and London? Presume it has two different stock ranks for the exact same financials.
I would be curious to know how Stockrank, for the same company, is different when comparing markets, by looking at all the dual listed shares.
Unfortunately, I only have the UK country subscription.... so if Stockopedia could do this as an article?
Would shed light on how different markets average "value" "quality" and "momentum" metrics differ.
Wise (LON:WISE) 49 SR & Green rating , i am bit confused
That's the Stockrank for the UK listing or the USA listing?
Look at the price, not the Stock Ranks, anything could happen to that. I will try to buy in the lower 700's on the LSE or not at all.
Wise (NSQ:WSE) 76 SR
TA!
Very interesting. Wise (LON:WISE) appears much more attractive compared to US shares. Vindicates them choosing a dual listing!
In theory the same company, so held in higher regard in the US is positive and maybe a disconnect that can be traded.
Maybe can see how trading goes in the US so can be ahead of the market at the UK off. That's trading and I'm crap at it and need to allow for spread and FX etc.
B.P. Marsh & Partners (LON:BPM)
another good 6 month period here - fully diluted NAV per share up from 960p to 996p - plus 36p per share of dividends have been voted in the period.they have calculated total shareholder return of 7% which is excellent for 6 monthn period,
Graham made some excellent comments about Pantheon their biggest investment (by current value) on 22nd September in that growth kinda appear to be not quite at rate previously expected (previosuly something apporaching £30 mill sales had been mentioned) . looking at 12 month uplift in Pantheon value thats only 1.3% higher total value for that company (actual value has gone up more due to extra investment) If we look at expected sales growth thats 16% if we compare 2026 forecasts to 2025. so the valuation increase here looks pretty modest last 12 months. Note i would say based on the 2025 accounts the £275 mill valuation of the company looks pretty "steep" PANTHEON SPECIALTY LIMITED had profit after tax of under £10 million - so i think that business needs to show continued progress towards figure of £15 to £20 mill perhaps? - or at minimum keep churning out double digit growth long term - note the trading entity voted £9 million of dividends up to the parent company so that suggests that suggests there is the potential for some decent dividends to be received while they hold.
overall still trending nicely with decent uplifts in value and some decent divi payouts - with shareprice being pretty much where it was 2 years ago its pretty simple that its looking better value than it did in november 2024 when price first popped above 700p due to increase discount to NTAV. Perhaps though the 700p might have been slighty ahear of itself. Should there be an extra discount given to reflect the fect that Pantheon is worth 46% of the market cap - yes i think that is very fair and reaosnable so i can see the logic as to why the shareprice discount to NTAV may stay high until there is more tangible progress ref Pantheon - i would deffo prefer they were reducing stake rather than increasing - i suspect the main bods there who sold out kinda wanted to bank some real rewards ref their hard work so i aint gonna grumble about the extra investment.
Nothing specific but the news that Microsoft has pulled from the Essex data centre on concerns over Grid issues should be very concerning for the Govenrment going forward ( what is the knock on effect?) Frankly this is a very Millipeed centred mess as the long term issues of paying operators for power they generate but cannot pass to the Grid are coming back to haunt. At present the more wind mills etc we build the bigger the annual bill. This is a Labour party scandal that it seems keen to gloss over at a time when public spending is out of control
Speaking in my back bench MP voice ' something must be done about it'
The problems with developing the grid are partly down to 3 vested interests arguing with each other and a poor planning system. Not fixing it is no more Labour than Con. Poland seems to have managed it.
Like a lot in this country we spend more time argung about what is necessary. I live in Shropshire and our current MP ( hopefully gone after the next election) is championing those who oppose Grid upgrades in pure NIMBY way because it means more pylons ( in an area where some already exist). Nobody is prepared to pay for the cost of placing the required cabling undergrpound which carries a cost of 3 times a pylon. In the meantime surplus electricity from renewables in North Wales is not able to pass into the Grid so the tax payer foots the bill. This is happening now and nobody has a clue when there will be a decision or which way it will be. Like all Labour Cabinet Ministers the energy secretary ( at least it is no longer Millipeed) has zero business experience....on and on we go into every decreasing circles
Presumably you feel the Conservative ministers who failed to implement improvements to the grid over the previous 10 years or so also lacked business experience?
The system is broken. By Millibund was a special case. He's creating war in the Falklands (agree with that has found the next thing to have relevance. We need oil and the Falklands is the next North Sea which bailed us out of the IMF and gave Mrs T a fillip which Mr M is hoping to gain). We need students to invent something useful other than a how to make Molotov cocktail and bring down capitalism.
Millibund's green head will prevent him from allowing any oil extraction in the Falklands. The Argentinians will also make that difficult,
The Millipeed is a complete liability -anyone recall the much vaunted Ed stone when he was Labour leader? That went well did it not?
Hi Peter The Grid issues have become intractable ( could cost tax payers some £4bn pa if you believe some figures by 2030 ) Trouble is Nat Grid is not a public company and BJ was bad at detail like that. At least Burnham has agreed on Jackdaw now just Rosebank to go . We need a mix of energy until we can rely on renewables , have you got your heat pump yet?
Well don't rely on Rolls-Royce Holdings (LON:RR.) and their SMRs. RR might need some cashflow from Defence but whilst Welfare sucks that out of the economy, this or past governments ain't gonna help RR in solving the issue.
Was hoping a couple of US non-revenue guys were going to step up in the small nuke space but it's taking time.
Mr Musks flying car is aspirational but as with Jobs it's marketing rather than saving the planet.
Natural resources will always be in demand - lithium, copper, zinc, yellow cake, and hate me oil and gas and hate me more coal.
Gold is the future of finance.
Can't figure out Silver - can't palm the wife on it anyway so only industrial at the moment and largely a paper manipulated commodity so touch with care.
SRT Marine Systems (LON:SRT) just wondering, did anyone catch anything new about this company on Mello yesterday?
Me to I am a holder and like the Management so keen for anyone else's perspective. It may go the way of Windward me thinks
Transcript here https://earningscalls.dev/transcripts/srt-marine-systems-plc_srt_earnings_call_transcript_2026-10-19?utm_source=chatgpt.com
thank you very much Islandhome
Shearwater (LON:SWG) Beginning to look quite interesting although very much a micro cap. Big contract win and has about 30% of market cap in cash. Spread not to bad. DYOR but I may take a small bite here. Not the most liquid as you would expect
Shearwater (LON:SWG)
the problem with shearwater is that for its entire history it strikes me as being lifestyle business for directors and nothing more. whats the point of all this revenue if you arent book at least say 10% margins. i suspect they had/have a real low quality business - if your product is good why are you not delivering a profit for shareholers. How can management be in place if they have had £500 mill of income - taken chunky payments for themselves and handed nothing out to shareholders and made nothing for shareholders in ten years.
Who knows though Volex (LON:VLX) used to be a basket case back in the day for many years and thats now a decent company. Personally i am not minded to give this company the benefit of the doubt until they start delivering some real profit for shareholders at both pat level and cash level too and dont take the micky ref options
looking at ye trading update - well all they mentioned is ebitda - not real profits - and increase in cash was like £500k - woop de do as mature business would nice if cashflow was higher than profits bearing in mind amortisation charge.
Could they be in sweet spot now ? yep - could shareprice do fantasically well - well yes if they could get 10% flowing through to bottom line and keep increasing sales that would transform the prospects of the company.
Green shoots yes - but no cake with cherry on top on based on past performace i would be slightly skeptical they will do great things.
shareholers - a freudian slip - either way made me smile , agree on the face of it this looks very interesting but banked most my profits due to their history - watch it fly!
Shearwater (LON:SWG) Consistent loss maker. Can't see why you would buy at this point.
Nice update from Wickes (LON:WIX) this morning. My prevous comment on Co v B&Q remains apposite. Remarkably good quarter but can it be maintained given winter weather is upon us
James Cropper (LON:CRPR)
I was fortunate to see the turnaround potential some time ago. Buying at a little over 300p. My interest taken initially by the advanced materials division, but on digging further the likely turnaround in the paper division loomed into view.
As always when one is fortunate to spot a turnaround early you wish you had bought more. Hey ho half a loaf! Hopefully the share price will react better tha my holding in Volex (LON:VLX) to a very positive update.
Volex (LON:VLX) Was my largest holding yesterday and just got larger this morning. Very well run company and the opportunity too good to miss. Berenberg has raised target price to 750p from 700p
James Cropper (LON:CRPR) update implies its Paper & Packaging turnaround is running well ahead of plan. The Board now expects FY27 EBITDA of £10.3–11.3m, 10–20% ahead of market expectations of £9.4m, with P&P credited for most of the beat.
If the market has read the Earnings Surprise textbook, the shares should Jump this morning and then drift higher. I hold.