Wickes: sales growth speeds up to 4.5% in Q3, on track for full-year forecasts

Analyst’s view:
Considering the acceleration in the growth rate, the strong cash balance, and the reasonable valuation, I'm willing to bump up our stance on this to a moderately positive one.
Up 4% at 224.2p (£510m) - Q3 Trading Update
We don't cover this one very often; let's try to rectify that a little.
Today's update is confident: "On track to meet market forecasts for 2026 adjusted PBT"
This table provides a lot of detail: what I'm going to take away from it is that year-on-year revenue growth trends have been improving as the year progressed. 1.8% growth in Q1, 2.3% in Q2, and now 4.5% in Q3.
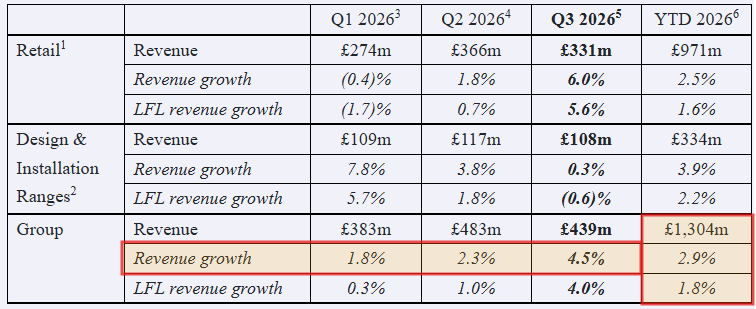
The "second derivative" is therefore positive: not only is the company is growing, but the growth rate itself is improving.
The other key takeaway for is that the "Retail" segment is doing much better than "Design and Installation Ranges". As we don't cover Wickes too often, let's get a precise definition of this:
Design & Installation Ranges revenue includes all product categories which could be sold as part of a design and/or installation and where the majority of sales of those products are designed and/or installed. This relates principally to projects such as kitchens and bathrooms, sold by our Design Consultants, as well as Wickes Solar.
Any other interesting snippets from today's update?
Within Retail, TradePro sales were up 8%. TradePro membership also up 8%.
Design & Installation: "our Bespoke Kitchen ranges are seeing customers being more considered for larger purchases".
In 2026, Wickes will open 5 new stores (total estate is around 230)
Outlook:
Our value-led and differentiated business model leaves us well-positioned to continue outperforming the market. With our strong sales performance and with a good productivity plan in place, we are on track to meet consensus expectations which on average show a growth in adjusted PBT of c. 10% for 2026.
Graham's view
I have a generally positive impression of recent performance at Wickes. They say they are taking market share, which seems to ring true from the growth figures shown.
There is a little consumer hesitiation when it comes to larger projects, especially high-end kitchens ("Bespoke Kitchens"). This is not the company's fault - just a reminder of how economically sensitive the sector is.
Forecasts have held steady here for a while, with only a gentle downward slope in EPS forecasts seen earlier this year:
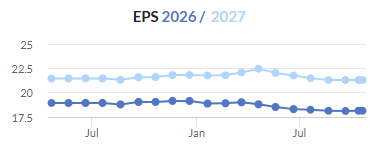
At at PE ratio of 10x, I was inclined to leave us neutral on this share.
However, I've just checked the full-year results for 2025 and this year's interims, and I see that the company's average net cash position last year was £153m.
In H1, the net cash position closed at around the same level. At a £500m market cap, this is a significant number,
Yes, there are significant leases involved here - but I'm still willing to give Wickes a lot of credit for having a £150m cash balance. It covers about a quarter of the present value of all future lease liabilities.
The company has been paying out an attractive dividend yield, covered by earnings:
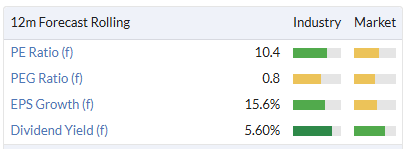
Considering the acceleration in the growth rate, the strong cash balance, and the reasonable valuation, I'm willing to bump up our stance on this to a moderately positive one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Wickes (1)
Comments here are also visible in the Daily Stock Market Report
Nice update from Wickes (LON:WIX) this morning. My prevous comment on Co v B&Q remains apposite. Remarkably good quarter but can it be maintained given winter weather is upon us