James Cropper: full-year EBITDA now 10–20% ahead of expectations
Analyst’s view:
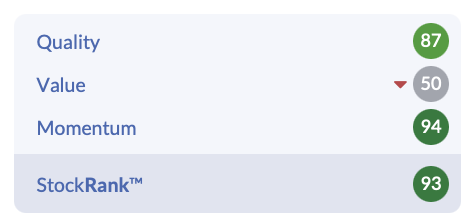
This is an encouraging update from James Cropper. The company now expects full-year adjusted EBITDA to be approx. 10% to 20% ahead of current market expectations and in the range of £10.3m to £11.3m. With the valuation looking reasonable, and the stock commanding a StockRank of 93, I’m going to leave CRPR on an AMBER/GREEN rating.
Up 6% at 740p (£67m) - Trading Update
Advanced Materials and Paper & Packaging specialist James Cropper has today provided us with a trading update for the six months ended 26 September 2026 (H1 FY27). Here’s what it has told us:
The group delivered a strong performance during H1 FY27, with trading ahead of the Board's expectations, principally reflecting a much stronger than anticipated performance by the group’s Paper & Packaging business from a combination of revenue growth and cost management.
As a result of the performance delivered in the first half, together with the Board's current assessment of the outlook for the remainder of the financial year ending 27 March 2027, the Board now expects full-year adjusted EBITDA to be approximately 10% to 20% ahead of current market expectations of £9.4 million.
This gives a range of expected full-year adjusted EBITDA of approximately £10.3 million to £11.3 million.
“The progress reflects the benefits of the actions we have taken to improve operational performance alongside continued positive momentum across the group. As a result, our expectations for full-year adjusted EBITDA have increased by 10-20%.”
Ed’s view:
We’ve covered James Cropper here at Stockopedia a few times this year. In early January, Roland looked at it in a Stock Pitch (this is a useful report if you’d like to learn more about this niche business).
Then, in April, Roland covered a full-year trading update. At the time, he upgraded the stock to an AMBER/GREEN rating on the back of an improved balance sheet and earlier-than-expected recovery in profitability.
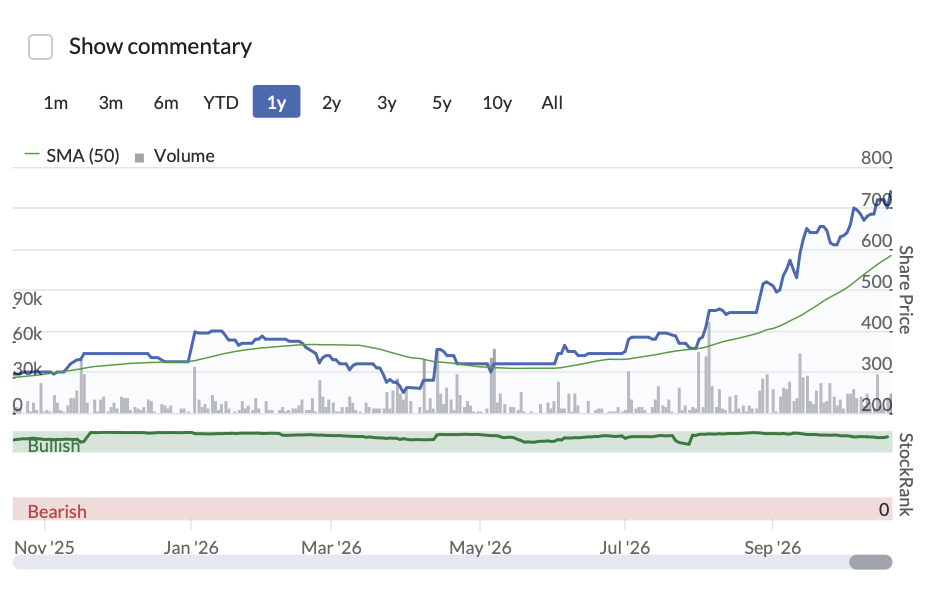
Since that upgrade, the stock has performed really well, rising from around 355p to 740p – a gain of more than 100%. Note that Stockopedia rates it as a ‘Super Stock’ and gives it a StockRank of a high 93.
Now, today’s update has resulted in a decent move higher (+6% as I write) and it’s easy to see why. In H1, trading during the period was ahead of the Board’s expectations thanks to a strong performance in Paper & Packaging driven by a combination of revenue growth and cost management (in September we heard that this division was seeing high demand from established customers augmented by new business wins, accelerating the momentum delivered in the second half of FY26).
As a result, the group is now expecting full-year adjusted EBITDA of approximately £10.3m to £11.3m (versus market expectations of £9.4m). For reference, adjusted EBITDA was £8.9m in FY26 and £6.7m in FY25, so we have a clear upward trend in profitability here.
Note that the midpoint of the guidance range (£10.8m) would represent year-on-year growth of 21%. The upper point of the guidance range would represent growth of 27%.
Given the increase in profitability, I think the risk/reward proposition here still looks relatively attractive, despite the big move higher in the share price this year. Going into today’s report, brokers were looking for 45.6p per share in earnings for FY27 versus 30.8p in FY26.
Assuming that the EPS forecast moves higher after today’s update, we are probably looking at a low-to-mid teens P/E ratio here. I see that as reasonable given the profit growth – the price-to-earnings-to-growth PEG) ratio is going to be well under one.
On the downside, revenue growth forecasts are a little underwhelming. For FY27, revenue is expected to be £102m, which would only represent growth of 2.7% year on year (in September the company told us that Advanced Materials revenue remains broadly in line with the same period in the prior year).
There’s also a little bit of debt on the balance sheet – at 28 March, net debt was £8.1m (down from £12.9m a year earlier). This should be manageable though (using the mid-point of today’s adjusted EBITDA guidance range of £10.8m we get a net-debt-to-adjusted-EBITDA ratio of 0.75).
Overall, I’m positive on the outlook here. I’m going to leave the stock on AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on James Cropper (3)
Comments here are also visible in the Daily Stock Market Report
James Cropper (LON:CRPR)
I was fortunate to see the turnaround potential some time ago. Buying at a little over 300p. My interest taken initially by the advanced materials division, but on digging further the likely turnaround in the paper division loomed into view.
As always when one is fortunate to spot a turnaround early you wish you had bought more. Hey ho half a loaf! Hopefully the share price will react better tha my holding in Volex (LON:VLX) to a very positive update.
Volex (LON:VLX) Was my largest holding yesterday and just got larger this morning. Very well run company and the opportunity too good to miss. Berenberg has raised target price to 750p from 700p
James Cropper (LON:CRPR) update implies its Paper & Packaging turnaround is running well ahead of plan. The Board now expects FY27 EBITDA of £10.3–11.3m, 10–20% ahead of market expectations of £9.4m, with P&P credited for most of the beat.
If the market has read the Earnings Surprise textbook, the shares should Jump this morning and then drift higher. I hold.