Daily Stock Market Report (Tue 14th April 2026) - ATYM, IMB, CRPR, ITRK, GMS, MAB1, PAGE, ABDP, SRT

Good morning!
Markets are set to open little changed today. The FTSE is at 10,580.
The current US-Iran ceasefire has one week left until expiry.
Late last night, Bloomberg reported that the two sides are now talking about where they might hold face-to-face negotiations to extend the ceasefire. The US blockade of Iran's coastline is now in force.
With macro developments being quieter today, let's focus on company news...
Leaving it there for now, thanks everyone.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BP (LON:BP.). (£91bn | SR87) | Reported upstream production in the first quarter is expected to be broadly flat compared to the fourth quarter 2025. The oil trading result is to be “exceptional”. Net debt to rise to $25-27 billion. | ||
Imperial Brands (LON:IMB) (£24bn | SR72) | SP -7% Reiterating full-year guidance. On track to deliver at least high-single digit earnings per share growth and at least £2.2 billion of free cash flow for the full year. | AMBER/GREEN = (Graham) There's no hidden profit warning contained in this update. What we do have are some amber flags: an H2 weighting, a potentially risky shift in strategy, and unimpressive growth from next-gen products. But in reality I think that little has changed. Full-year guidance has been reiterated, and I think it's natural that there might be some profit-taking after a very strong bull run and a lukewarm trading update. So I'll leave our existing moderately positive stance unchanged. | |
Intertek (LON:ITRK) (£5.9bm | SR43) | SP +12% Strategic Review initiated to evaluate the potential separation, either through a sale or demerger, of Intertek Energy & Infrastructure from Intertek. Trading statement: full year guidance confirmed. | AMBER = (Roland - I hold) [no section below] Intertek is considering splitting its business in two by separating its two lowest-margin divisions (2025: 11.1% & 8.7%) from its three higher-margin divisions (2025: 30.4%, 22.6% & 13.0%). The Industry & Infrastructure and Energy divisions both have significant exposure to cyclical sectors such as oil, shipping and automotive, so my feeling is that grouping them could be logical. Perhaps coincidentally, this strategic review follows an extended period of share price underperformance and sluggish revenue growth. My guess is that focusing on its core businesses (ex-infrastructure and energy) might help Intertek regain its previous premium share price rating. As a long-term holder my view on the suggested split is fairly neutral at this stage. From a value perspective, I think Intertek looks more attractive than in the past, but I would note the recent negative trend in earnings forecasts. Given today’s in-line trading update, I’m going to leave our neutral view unchanged today | |
Oxford Instruments (LON:OXIG) (£1.47bn | SR72) | Full-year performance in line with market expectations. Order intake up c. 8% organically, book-to-bill c. 1.07. | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.24bn | SR94) | Q1 production impacted by unusually heavy rains. The Company plans to review its copper production guidance for FY2026 on an ongoing basis. Previously disclosed production guidance was 50-54k tonnes of copper. | AMBER ↓ (Roland) While weather-related disruption is outside the company’s control, I would argue that meeting full-year copper production targets now looks quite challenging without a strong recovery in grade. I don’t know how likely this is. We’ll have to wait until May for the company to provide updated full-year guidance. The other factor to consider is the copper price. Further gains could support higher profits even with lower production. I recognise the opportunity here, but I’d note that 2026 consensus had already drifted lower prior to today. On balance, I think this is a more speculative situation than it was in the past, so I’m moving my view down by one notch to neutral. | |
Pagegroup (LON:PAGE) (£435m | SR51) | SP +2% Q1 gross profit falls 4.9%. “Resilient performance”, but “Ongoing subdued levels of client and candidate confidence impacting decision making”. CEO: “Whilst we have seen signs of a normalisation in trading in some of our markets, the increased geopolitical and macro-economic risks due to the conflict in the Middle East create a heightened degree of uncertainty in the outlook for the rest of the year.” | AMBER/RED = (Graham) [no section below] The relentless decline in profitability at mainstream recruiters continues, with EMEA and the UK described as "tough" (nothing new there). Gross profit is down 7% in Germany, 11% in the UK, and 14% in France. At constant currencies, there was small growth in the Americas and better growth in Asia-Pac (+9%), which does lend credence to the argument that the problems are at least partly economic and geographical rather than structural. PAGE's heavy concentration in Permanent recruitment (vs. Temporary/Contract) also leaves it with a greater exposure to cyclical economic trends. Even still, I would continue to treat all recruiters very cautiously, including PAGE. These shares are very cheap if conditions can recover, especially in Europe and the UK. But I fear that the sector has permanently changed, with the influence of new technological tools, and that prior levels of profitability are no longer possible. | |
ACG Metals (LON:ACG) (£356m | SR46) | Revenue $135.6m, adj. EBITDA $76.3m. Net assets $49.8m. “The planned transition to copper production in the middle of 2026 represents an exciting and transformational next phase for the Company…” | ||
Tharisa (LON:THS) (£346m | SR100) | Quarterly PGM production at 34.3 koz, PGM prices averaging at US$3 038/oz (previous quarter: US$2 208). Net cash $54.7m. Guidance: Production guidance for FY2026 is set at between 145 koz and 165 koz PGMs and 1.50 Mt to 1.65 Mt of chrome concentrates. | ||
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£333m | SR73) | £1.4m acquisition of a “UK consumer platform attracting millions of web visits annually, providing guidance, tools, and services to homeowners and prospective buyers”. | GREEN = Graham [no section below] A £1.4m acquisition might not move the needle but this does look like a neat little acquisition of a trusted website. The synergies from acquiring an asset like HomeOwners Alliance Ltd (HOA) are pretty clear: MAB will get the opportunity to "engage with customers earlier in their homebuying journey" and "broaden MAB's role across the wider home-moving process". HOA is a trusted source of advice for home buyers and provides quotes for a wide range of related services - mortgages, conveyancing, etc. Recent full-year results from MAB disclosed a very modest net debt position of £3m (relative to adj. PBT of over £36m) so there are no balance sheet reasons for them to refrain from making a small acquisition like this. I retain my positive stance on this quality stock (QualityRank 85). | |
| Porvair (LON:PRV) (£336m | SR75) | AGM Trading Update | PRV has performed in line with expectations in the first four months of the year, delivering constant currency revenue growth of 5%. | |
Ab Dynamics (LON:ABDP) (£262m | SR49) | Revenue -16%, adj. operating profit -16% (£9.1m). “H1 performance reflects previously guided second half bias for FY 2026, with full year adjusted operating profit expected to be in line with current market expectations.” Zeus forecasts published in March: FY26 adjusted EPS 77p, FY27 adjusted EPS 85.2p. | AMBER = (Graham) [no section below] Our prior caution on this continues to make sense to me, with declining revenues and profits in H1, and a large H2 weighting in store for the current year (usually a source of risk). By my calculations, the company has only generated 37% of the full-year adjusted operating profit forecast in H1, leaving a large gap to bridge in H2. While I have a generally positive view of the company and of management, this degree of reliance on the second-half performance makes me nervous. On the other hand, for long-term fundamental value, the stock is now trading at a much cheaper multiple (13x) than has been historically typical for it. The net cash position (£39m) also offers reassurance. So for long-term investors who are willing to put up with fragile and uncertain demand, especially out of China, and a large H2 weighting in the current year, it could be worth taking a fresh look at this. | |
Petrotal (LON:PTAL) (£252m | SR91) | Group production averaged 14,907 bopd in Q1, down 2% QoQ. Total cash of $128.1 million as of March 31, 2026 ($104.2 million unrestricted). Development program at Bretana: in the final stages of securing a drilling contractor. Drilling activities targeted to resume by October. | ||
Serabi Gold (LON:SRB) (£242m | SR99) | Quarterly gold production of 12,042 ounces, a 20% increase from Q1-2025. Cash of $64.4m. Commenced installation of a 4th ball mill at Palito Complex; will increase annual processing throughput to 330ktpa in 2027. Two underground fatalities in January. Production guidance at 53,000 ounces to 57,000 ounces. | ||
Gulf Marine Services (LON:GMS) (£232m | SR87) | Revenue up 12%, adj net profit up 30% to $41.8m. Net debt down 22% to $157m (1.4x leverage). Events in the Middle East are causing some disruption and management are evaluating the impact on operations and outlook. | AMBER/RED ↓ (Roland) [no section below] Today’s results look fine to me and appear to be largely as expected. Revenue and day rates are up, debt is down and an additional leased vessel is helping to offset lower utilisation rates. However, I see little point in getting too far into last year’s numbers given the impact of the situation in the Middle East. Management says one customer has declared force majeure so far and that previous 2026 EBITDA guidance ($105-115m) is now under review – an update will be provided “when the situation becomes clearer”. While geographic diversification is a priority, I would speculate that it could become more difficult to secure higher day rates against a backdrop of falling fleet utilisation. Similarly, I can’t help feeling that the recent decision to acquire a new vessel may have been poorly timed. While there may still be some value on offer here, I’ve opted to downgrade our view by one notch to reflect the uncertain outlook and falling fleet utilisation – not an attractive combination, in my view. | |
SRT Marine Systems (LON:SRT) (£219m | SR35) | Further to last night’s placing announcement, SRT has raised gross proceeds of c.£16m, placing c.19.5m shares at 82p. Proceeds will be used to strengthen balance sheet, accelerate product development and support contract delivery. | AMBER = (Graham) [no section below] Pleased to see that I stayed neutral on this stock last month, despite H1 revenues nearly doubling and pre-tax profit rising 48% (to £3.1m). The ValueRank was still only 15 (it has since risen to 31, which is still pretty poor), and I've been a long-term sceptic on SRT and how it communicates to the stock market. It turns out now that despite the company's apparent financial success, after many years of promise, it is still not self-funding. The H1 report showed cash increasing by c. £20m to £42m, but the company has raised an additional £16m in fresh equity, at a 5.7% discount to the prevailing share price, for various reasons which I consider to be rather vague. A naive reading of the H1 balance sheet would have suggested that the balance sheet was already strong, with customers paying upfront for their orders. So my sceptical attitude here is only entrenched by the news of this fundraising. | |
Mkango Resources (LON:MKA) (£146m | SR9) | Companies are included in a consortium to deliver “a full circular UK supply chain for rare earth neodymium-iron-boron ("NdFeB") magnets used in the automotive sector.”. | ||
Amcomri (LON:AMCO) (£115m | SR69) | 2025 revenue up 22%, pre-tax profit up 145% to £4.1m. Continued growth in both divisions “despite some weaknesses in certain end markets”. Outlook: 2026 has started well and is in line with expectations. | ||
Orosur Mining (LON:OMI) (£78m | SR12) | Drilling 100m west of Pepas intersects “significant gold mineralisation”, including 26.4m at 2.85g/t AU and 14.45m at 8.27g/t Au. | ||
Agronomics (LON:ANIC) (£70m | SR53) | Received approval in Japan and Brazil to import and sell the world’s first non-browning banana variety. | ||
DP Poland (LON:DPP) (£66m | SR18) | Total system sales +18.2% in Poland and +28.8% in Croatia. Six new stores added; 141 stores at quarter end, plus 71 Pizzeria 105 locations. | ||
Hemogenyx Pharmaceuticals (LON:HEMO) (£63m | SR9) | Submitted Annual report to FDA under IND application for HG-CT-1. Includes details of ongoing Phase 1 study, stability information and updated trial plans. | ||
Zenith Energy (LON:ZEN) (£52m | SR37) | Tunisia has now recognised that the Robbana and El Bibane production concessions are held by Zenith’s fully-owned subsidiary, EPT. The authorities have also confirmed that c.3,987 barrels of oil produced from the concessions since 2022 and held unsold are owned by EPT. A further 8,000 barrels remain in storage at Robbana, where facilities have suffered “extensive vandalism and theft” and will be non-operational for at least a year. | ||
hVIVO (LON:HVO) (£51m | SR51) | Signed Clinical Trial Agreement to conduct a trial to test Traws’ tivoxavir marboxil ("TXM"), using the hVIVO Influenza Human Challenge Study Model. Majority of revenue to be recognised in 2026. | ||
Cobra Resources (LON:COBR) (£46m | SR13) | Reports results from 12 reverse circulation drillholes from the Blue Rose copper-gold-molybdenum discovery. Considers the “grade, width and depth profile of results to date to be highly encouraging”. | ||
Enwell Energy (LON:ENW) (£45m | SR85) | Production licences remain suspended. SC exploration planning continues. “The operating environment in Ukraine remains very challenging”. Cash of $93.3m, majority in Ukrainian Hryvnia. | ||
PROCOOK (LON:PROC) (£41m | SR79) | Full-year revenue up 23% to £85.5m, ahead of expectations. Outperformed wider UK kitchenware market by 20% across full year. Operating profit & PBT expected to be in line with expectations. | ||
PCI- PAL (LON:PCIP) (£36m | SR55) | Achieved various new compliance standards, enhancing its ability to support enterprise customers operating in highly regulated environments, particularly in the United States and the healthcare sector. | ||
James Cropper (LON:CRPR) (£27m | SR90) | Expects FY26 revenue up 4%, with adj EBITDA of £8.8m, approx 10% ahead of expectations and +30% versus last year. Net debt to EBITDA now <1x. Outlook: “confident in the medium-term prospects of both divisions”. | AMBER/GREEN ↑ (Roland) I’m upgrading our view today to reflect Cropper’s improved balance sheet and earlier-than-expected recovery in profitability. The main risk here seems to be a lack of visibility on FY27 – forecasts are unchanged today, but the company warns that the outturn for the Advanced Materials division (the group’s main profit engine) will be dependent on “customer demand patterns and broader market conditions”. | |
First Property (LON:FPO) (£20m | SR80) | FY26 pre-tax profit (y/e 31 March) is expected to exceed current market expectations. Group has benefited from one-off profits on the disposal of two properties. | ||
Cirata (LON:CRTA) (£19m | SR2) | Q1 2026 was cash flow positive, for the first time in the company’s history. Good momentum with Q1 FY26 closing annualised contract value of $4.9m. Outlook reaffirmed: targeting cash flow breakeven in FY26. | ||
Sosandar (LON:SOS) (£15m | SR68) | Revenue up 14% to £42m, pre-tax profit expected to be £0.4m, in line with expectations. Net cash of £8.4m. | ||
Block Energy (LON:BLOE) (£14m | SR33) | Executed agreement with Zhijiang Sanning Energy Co Ltd for the farmout of Project III. Will include up to $75m carry comprising appraisal drilling and early facilities construction. Sanning to acquire 51% of Project III, with Block owning 49% and retaining operatorship throughout appraisal. |
Graham's Section
Imperial Brands (LON:IMB)
Down 7% to £28.77 (£22.5bn) - Trading Update - Graham - AMBER/GREEN =
As a BATS shareholder, I note that BATS is also down today - by about 4%.
At first glance, I thought that this IMB update was fine, but the market was evidently hoping for more.
Headline:
Trading update: reiterating full-year guidance; positive start to 2030 transformation.
First half highlights:
H1 net revenue: low single digit growth in tobacco and next-gen products.
H1 adjusted operating profit: slightly higher compared to H1 2025. Growth to accelerate in H2, in line with previous guidance for an H2 weighting.
For the full year:
We reiterate our full-year guidance for FY26 of low-single-digit tobacco and double-digit NGP net revenue growth, three to five per cent Group adjusted operating profit growth and at least high-single-digit earnings per share growth, all at constant currency,
Free cash flow is to be “at least £2.2bn”.
Tobacco will have small net revenue growth even as volumes decline.
Next-gen products will see market share growth and “mid to high single digit” net revenue growth.
The next-gen category includes tobacco heated products, vape and “modern oral” (nicotine pouches).
So what’s the catch? Here’s one: the company is planning to give up some market share:
While market share remains important, we continue to balance share and value. Having successfully stabilised our aggregate share across our top five markets, we continue to evolve our approach to reflect changing market dynamics and our focus on more profitable segments, to deliver long-term, sustainable value creation. As such, we anticipate some overall modest aggregate share reduction across the top five markets in H1, alongside growth in tobacco adjusted operating profit.
There’s nothing inherently wrong with prioritising profitability over market share, but what’s the endgame here? IMB’s big strategic wins have been in the budget categories left behind by the other majors - the fast-growing budget cigarette brand Paramount already has 5% market share in the UK, for example.
A strategic shift towards profitability, at the expense of market share, will see IMB competing head-on with BATS and Philip Morris.
Again - there’s nothing inherently wrong with that choice. But as a potentially risky strategic direction, I can see why it might cause some IMB shareholders to bank their profits.
5-year chart:
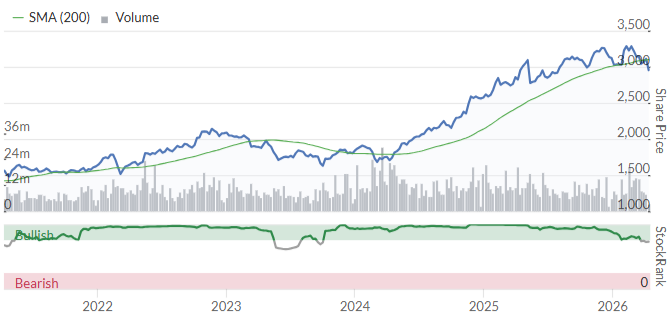
Leverage: “to remain at the lower end of our 2.0-2.5 range for net debt to EBITDA”.
Graham’s view
There’s no hidden profit warning contained in this update. What we do have are the following amber flags:
An H2 weighting needed to hit forecasts (although this is not news).
A shift in strategy away from what has strategically worked, towards more direct competition with its peers.
Next-gen products, which are the only possible engine of volume growth, potentially only seeing mid single digit revenue growth, if they come in at the low end of the range.
On the bright side, it’s still not exactly expensive. The P/E multiple is about 8x, based on current-year earnings (FY September 2026).
And with buybacks, the share count is on the decline, gradually making dividends more affordable:
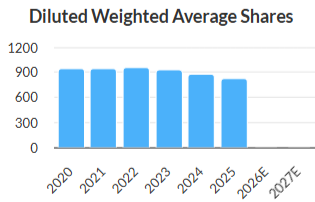
I’m a little biased when it comes to this sector. I’ve always thought, despite the ethical problems with it, that it was objectively-speaking a source of good investment ideas.
Therefore, despite the market’s dissatisfaction with today's update, I’m inclined to leave our existing AMBER/GREEN stance unchanged. The shares have had a great run, and it makes sense that there’d be profit-taking on a lukewarm update. But in reality, I think that little has changed here.
Indeed, I’d argue there’s more value on offer now than there was in November, when Roland covered it at a £25bn market cap. The market cap is only £22.5bn today - about ten times forecast free cash flow for this year
Roland's Section
Atalaya Mining Copper SA (LON:ATYM)
Down 1% at 796p (£1.2bn) - Q1 2026 Operations Update - Roland - AMBER ↓
This Spanish copper miner has delivered a decidedly mixed update today. Copper production fell sharply during the first quarter and the company is reviewing its full-year guidance with a view to restating it with Atalaya’s Q1 financial results in May.
My reading of this RNS is that it’s quite negative, but I can also see some positives that I will try and highlight. It’s worth remembering we’re in a strong bull market for copper at the moment – so even a weaker-than-expected production result could still support rising profits.
Here are the main points from today’s quarterly update, as I see them:
Q1 production affected by “unusually heavy rains”, also affected peers in the region;
Expect to recover “a portion of the production shortfall”;
Q1 copper production of 9,939t (-30% vs Q1 25 and -14% vs Q4 25);
Average realised copper price in Q1 of $5.87/lb (Q4 25: $5.10/lb, Q1 25: $4.26/lb);
No impact yet from events in the Middle East, but unit prices for key consumables such as explosives and diesel could be affected in the coming months. Some hedging is already in place.
Outlook
In my view, the highlights table at the top of today’s RNS is potentially misleading, as it includes details of Atalaya’s previous 2026 guidance for full-year copper production of 50,000 to 54,000 tonnes.
Only by reading further down do we discover that this guidance is now under review:
Following the impact of rainfall during the Period, the Company plans to review its copper production guidance for FY2026 on an ongoing basis and will provide further updates when the Company reports its Q1 2026 Financial Results in May 2026.
Doing the maths suggests that Atalaya would need to produce at least 13.3kt of copper quarterly for the remainder of the year to stay within the previous guidance range.
This appears to be theoretically possible, but I would argue that it’s highly dependent on a recovery in the copper grade of the ore being processed. Lower grades were a big factor in the fall in Q1 production:
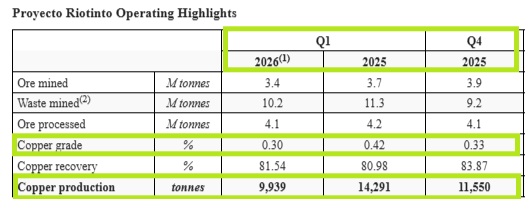
The company says that lower grades in Q1 were exacerbated by the use of low-grade stockpiled ore due to mine access problems in heavy rainfall. However, I’d note that ore grades were already much lower in Q4 last year.
I don’t know enough about the company’s assets to understand whether a recovery in grades is likely.
Updated estimates: with thanks to broker Canaccord Genuity for publishing on Research Tree today, we can see that earnings estimates for FY26 and FY27 have been left unchanged.
FY26E adj EPS: €0.99
FY27E adj EPS: €1.31
I would guess these estimates will be revisited in May when the company provides updated guidance and information on Q2 trading.
Roland’s view
My interpretation of this update is that a cut to production guidance and earnings forecasts is relatively likely, unless rising copper prices save the day.
This may well happen – the red metal is currently trading at near-record highs after a multi-year bull run:
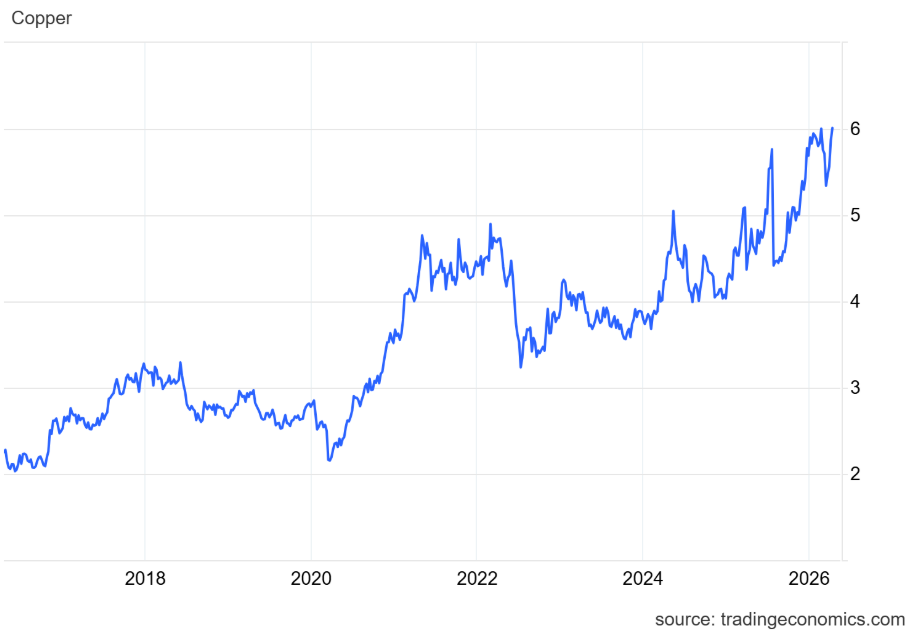
Another potential positive is that inventories of copper concentrate rose by 20% to 5,083 tonnes during the quarter. I’m not sure why sales were held back or slowed, but strong copper prices may give Atalaya the opportunity to sell down inventories at higher copper prices later in the year, supporting earnings.
Of course, I’ve no idea if or how the current geopolitical situation may impact copper demand and pricing as the year unfolds.
What I do know is that consensus estimates for Atalaya have already started to slip this year:
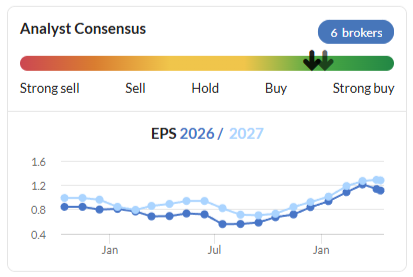
While the shares are looking cheaper than when I last reviewed this stock, I think the company’s High Flyer styling could come under pressure unless the price of copper continues to rise.
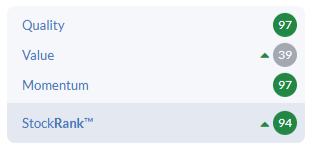
As I commented in January, I think Atalaya’s valuation is more directly linked to the price of copper than it was 12 months ago, when the shares were trading in line with book value (versus 2.4x today).
In my view, this has become a more speculative situation than it was in the past. When combined with today’s weak Q1 update, I think it’s appropriate for me to move our view to neutral. AMBER
James Cropper (LON:CRPR)
Up 25% at 350p (£33m) - Full Year Trading Update - Roland - AMBER/GREEN ↑
James Cropper plc (AIM: CRPR), the Advanced Materials and Paper & Packaging group, is pleased to announce a trading update for the financial year ended 28 March 2026 ("FY26").
Today’s full-year update includes details of improved trading and an upgrade to FY26 guidance.
The details are fleshed out in a broker update from Shore Capital that’s available on Research Tree. This explains why Shore’s analysts have translated today’s 10% upgrade to EBITDA into a 33% increase in FY26 EPS forecasts.
FY26 trading update
Revenue appears to have been stronger than expected during the second half of the year. The resulting operational gearing has resulted in a much-improved profit performance.
FY26 revenue up 4% to £103m (+6% versus previous forecast of £96.8m);
FY26 adj EBITDA up 30% to £8.8m (+10% versus previous forecast of £8m);
FY26 net debt of £8.3m (FY25: £12.9m), giving a net debt/EBITDA ratio of <1x.
Both the company’s operating divisions appear to have performed slightly better than expected in terms of revenue, with Advanced Materials up by a “low double-digit percentage” and Paper & Packaging “broadly in line with FY25” despite the previously-reported loss of a major customer.
Overall group profitability improved thanks to these higher revenues. But I think there are some nuances worth noting relating to the profitability of each division.
Advanced Materials: “increased investment in operating costs to support medium-term growth” meant that adjusted EBITDA only rose by a “high single-digit” percentage, lagging revenue growth. While investment to support longer-term growth is important, in my view it’s crucial that this is done with clear line-of-sight to commercial opportunities. I think the trend here could be worth watching.
Paper & Packaging: this legacy business generated a reduced EBITDA loss for the full year, but returned to EBITDA profitability in H2.
Current trading & FY27 outlook
Trading momentum into the new financial year has been positive, with the Group's strategy and operational improvement programme continuing to track in line with the Board's strategic plan.
Management caution that the “ultimate impact on markets and input costs” of events in the Middle East remains uncertain. However, Cropper “is actively managing its position through hedging, pricing actions and procurement discipline”.
Cropper CEO David Stirling has stopped short of providing FY27 guidance today and has instead emphasised his confidence in “the medium-term outlook”.
Today’s commentary suggests to me that while performance in Paper & Packaging is expected to improve further, there’s some uncertainty about the outlook for Advanced Materials:
Advanced Materials: “... the Group expects growth in the current year to be linked to customer demand patterns and broader market conditions.”
Paper & Packaging: confident in delivering further improvements to performance, expect to achieve full-year positive adjusted EBITDA.
Updated broker forecasts
EBITDA is a useful metric for lenders. But as we often comment, the number of costs excluded from this figure mean it’s less useful for equity investors (who can only benefit from bottom line earnings).
For these reasons, we often see EBITDA growth translate into a smaller increase in EPS.
However, today we have an interesting and rare reversal of this pattern – the increase in Cropper’s FY26 adjusted EPS forecasts is three times larger than the rise in EBITDA forecasts (estimates from Shore Capital):
FY26E adj EBITDA +10% to £8.8m
FY26E adj EPS +33% to 45.4p
There are two reasons for the much larger EPS upgrade:
Cropper booked a £4.4m impairment charge against P&P assets last year (and a £7.2m charge in FY24). This means that depreciation charges are lower than in the past – the assets have already been written down. This is likely a one-off gain, unless further impairments follow.
The second reason is more positive – lower interest costs due to the reduction in net debt.
What about FY27?
Shore Capital has left FY27 forecasts unchanged today. The broker says that this is “erring on the side of caution” but acknowledges the obvious macro risks.
This introduces the risk that Cropper’s earnings growth could pause this year – current FY27 adj EPS forecasts stand at 44.1p, marginally below the revised FY26 estimate.
Roland’s view
James Cropper is an illiquid small cap stock with a large spread. With shares like this, upgrades (or downgrades) can result in disproportionate share price moves.
I would argue we’ve seen that this morning – early gains of over 30% have now pared back to c.25%, at the time of writing.
While this increase is below today’s upgrade to FY26 estimates, these are for last year’s earnings. The market looks forward and there’s no change to forward earnings estimates today.
I took a broader look at this business in a Stock Pitch at Christmas and my view of the opportunities and risks is largely unchanged following today’s update.
The StockRanks also remain fairly positive:
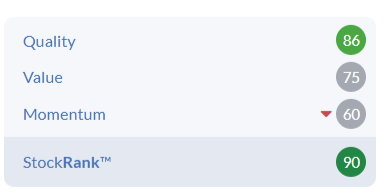
Despite some uncertainty around FY27, I am encouraged by the recovery in profitability suggested by today’s update – today’s adjusted figures suggest a FY26 return on equity of c.12% (although I would also like to see the unadjusted figures!).
The valuation also remains quite reasonable, in my view, on a forward P/E of around 8.
We’ve been neutral on this stock in previous coverage, but I think it’s fair to move up one notch today in reflection of the company’s improved balance sheet and profitability. AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Understandably few people are looking at the Cirata (LON:CRTA) news today. For a stock that (as Wandisco) once traded at 1348p and is now at 16p there is clearly a huge amount of trust to be rebuilt. But today they announced the start of positive cash flow, which is a signal I like. I noted a year ago that there might be some good news appearing,and while I am still not a holder I appreciate that this teeny turnaround might give a brave investor a fine opportunity.
They are developing the capacity in renewables, and the build up has been encouraged by incentives. One of the large background problems, as I understand it, is that the Grid as it is concurrently configured cannot always use it efficiently. For example excess capacity of Offshore Wind power for the needs of users of Scotland/The North when it occurs cannot be stored, and the excess is 'dumped' i.e shut down because there is no way currently of using it in the broader National Grid. This resulted in Govt. Shut Down payments providers of circa £1.4bn in 2025.
I suspect that when the Grid is sufficiently structured for this capacity, and/or off grid power generation increases (domestic roof & plug-in solar & heat pumps etc) like the electric car build up, subsidies and tax exemptions will start to evaporate as the Govt looks to claw back revenues.
Then we will see for providers as the renewables tide goes out, who has been swimming naked.
By the time the grid can handle the North/South problem for offshore wind we should have enough well spread nuclear power to largely offset the need for an expensive grid restructure, but the next ten years are difficult.
what is potentially good is that as electric car useage increases - electric companies can encourage car charging to be done at times when theer is clealry a surplus - your average person in the street moans we dont have enough electric to charge em - but the reality is it probbaly creates extra useage (and revenuw) at night - when that would just be dead generation. obviously it would help if we got more reasonably priced charging points on terraced streets - that may be biggest block to electric car uptake at present (other than price)
my main gripe is the charging structure seems to be suited to help power companies rather consumers - not sure how thats best fixed but seems rigged at present if they pay everyone highest price quoted,
Its not as bonkers as it sounds - people can try and earn a little money by timing their washing machines and dishwashers to run at off-peak times. That then reduces the peak load.
The Telegraph can always be relied upon to adhere to its anti-renewables agenda, for e.g. taking a stated fact (there might be more solar output than grid demand on a sunny weekend in May) and turning it into a sensationalist headline (solar power threatens to overwhelm the grid), thereby perpetuating the mistaken view that all this green energy carry on is a terrible mistake.
Interesting discussion on Renewables. Just to clarify, my posts are from an investment perspective.
The bit that interests me most is when something that should incur a cost is being offered "free" or at a subsidised rate. Whether it is affordable housing or energy, subsidised means someone , somewhere pays for the subsidy and may well be distorting the market as a consequence.
These subsidies have been going on for a while in Housebuilding and Renewables and are the principle reason why I have been negative ( and still are) on these sectors). I am confident that Housebuilding will once again prove to be a reasonable investment at some stage, however, I don't have that faith in Renewables.
I would expect that when we have enough renewable capacity, the subsidies that Renewables have come to expect will be phased out. Such is the complexity of the market, I wouldn't be surprised that if some ageing but essential Renewable assets would need some form of Nationalisation ( another subsidy) but one which may sit more comfortably with a left leaning Government rather than bailing out Renewable shareholders.
I don't have any special insights here above and beyond other subscribers. I just think that the risk and reward for this sector is not worth consideration for myself. Others may think otherwise.
I am aware that we are building Renewable infrastructure very quickly. In my experience, building quickly means building expensively. Another cost which will need to be accounted for at some stage - but by whom?
The costs of solar installations have fallen dramically even in the UK. The only time the UK housing market has had adequate supply is when Council Housing was in full swing. Everyone should have a secure roof and energy imo.
Drax is my example of subsidies which keep it going. For that reason I find it uninvestable.
We have an extra two sessions on the show this afternoon...
It is a free to view Investment Trusts and Funds show this afternoon and all are welcome...
You can register for free here: https://www.melloevents.com/mitf140426
The full agenda is below (subject to minor changes):
1:00pm Company Presentation from VietNam Holding (LON:VNH)
Craig Martin (Co-Chairman of Dynam Capital) presenting and available for Q&A
1:30pm Company Presentation from Foresight Solar Fund (LON:FSFL)
Toby Virno (Investment Manager) presenting and available for Q&A
2:00pm Company Presentation from Smithson Equity Fund
Simon Barnard (Portfolio Manager) presenting and available for Q&A
2:30pm Keynote Speaker: Emma Bird, Winterflood Securities
Emma will provide an update on the investment trust sector to conclude the webinar
3:00pm Company Presentation from AVI Japan Opportunity Trust
Nicola Takada Wood (Managing Director, Japan) presenting and available for Q&A
The agenda has a bit for many different types of investors including exposure to renewable energy infrastructure, the Asia market or to a concentrated portfolio of high-quality, small and mid-cap (SMID) global companies. We also have an educational round up of the wider sector.
Hope to see you on Zoom again today at 1pm.. https://www.melloevents.com/mitf140426
"Solar Power threatens to overwhelm electricity grid"
Rather unexpected article in the Telegraph which states that Solar Power cannot be turned off and and that the current rate of solar development will overwhelm the electricity grid. The Telegraph then goes on to say
"Households could be paid to consume excess supply for the first time, say energy chiefs"
I double-checked to make sure that I was not reading an old article from Aprils fools day, but no, it is dated today and seems to have been written in all seriousness.
The article goes on to discuss a situation in May when solar generation at 18 gigawatts could exceed consumption - which may be as low as 12 gigawatts and that there might be the possibility of blackouts, as occurred in Spain where solar destabilised the grid.
Another source in the article describes the situation as "free power". Hopefully this is reflected in customer bills - but somehow I doubt it.
Better go and price a battery
Or are they just doing their usual of throwing stones at renewables to bang their mantra of drill, drill, drill...
Trump's farce in the ME has only shown the need to move as quickly as possible to renewable none fossil energy.
"Or are they just doing their usual of throwing stones at renewables to bang their mantra of drill, drill, drill..."
It is not written as a comment article. The report from which the article is drawn has been produced by NESO . Kayte O’Neill, Neso’s operating chief is quoted in the article.
This article (if accurate) highlights the issue with renewables, namely intermittent relatability and lack of storage of the energy or alternatively a massive investment in storage which has other environmental impacts. So unfortunately not producing our own fossil fuels leaves us with the type of situation that we have today and also at the whim of importing it from Russia/ME/USA which has separate reliability issues.
My electricity is supplied by Octopus and I regularly get "free electricity"sessions when there is excess power. It may just be an hour from 1800 to 1900 or it can happen around mid day. It's not life changing amounts but I reckon it's worth about £25 a year to me.
The scheme referred to in the Telegraph is feasible and as long as the energy company signs up to it, consumers will benefit a little.
this is either nonsense article - or higlights how shit we are at managing the grid - we have known for years the profile of whats coming - its pretty basic stuff - its up to the job of the powers that be to manage this sytem effortlessley. just look at how much money the original tesla big battery saved austrialia when it turned up and added flexibility - battery may not be cheap -but it should be fantastic tool to smooth out the load variance if it can suckup ecess spikes - that should have huge paybacks as it can even out spikes where energy companies charge an arm an a leg at top whack then demand spikes up - and make a killing if we are stupid enough to pay em to stop generating when deamnd drops off a cliff.
its no different to the fact demand drops overnight and peaks when everyone makea cup of tea at the same time.
note i think we would all agree our energy grid stability is top notch - i think its ranked 3 in the world for big countries ? i suggest this article is scaremongering nonsense - note no bad thing if thos in charge are flagging up "we need to improve the grid stability " - we probbaly have underinvested
this is the detail here - imho a storm in a teacup
note they directly claim renewables here - but imho large spikes were an issue before renewables came into the equation surely - just seems like are east target when similar issues existed before renewables (i do condcede renewables do have more variability ref - and one needs to up ones game a bit)
n its report, Neso said there was a 75pc chance that national demand would plunge to a record low during the late May bank holiday weekend, as households were less likely to be at home.
The previous record low of 12.8 gigawatts was set last May – but grid chiefs expect it could drop to 11 gigawatts this year.
By comparison, passive generation from wind and solar farms could be around 18 to 19 gigawatts at the same time.
The imbalance highlights the challenges posed by a renewables-based electricity grid, where supply becomes heavily dependent on the weather.
This is basically hyperbole vis "overwhelm" Many, many (too many) years ago I worked for a time in the national grid helping to build their charging system for putting power into the network.
All the power stations and providers were listed and we calculated what each added so they could be paid and incentivised to add power when it was needed, remove it when it was not.
You have baseload (stuff like nuclear, coal) and variable load (stuff like renewables or turbines that can be spun up and down) and storage (like Dinorwig or, these days, batteries). There is also the interconnector to sell excess capacity to the continent or buy it (from France's many Nuclear stations) when needed.
There was an interesting game where the producers were trying to predict peak days so they could adjust their output for the maximum return and the Grid were trying to outwit this with their pricing. Nice bit of game theory and maths in that.
All the above to say that: the grid doesn't get overwhelmed in toto, it just sometimes has more power than it needs and the producers can conceivably get paid (or ordered) to take their power offline - spin down a gas turbine, disconnect a wind or solar farm etc.
Rather than do that it can make sense to encourage people to use as much of the power as they can at that point (make hay whilst the sun shines) and use less in other circumstances.
Exactly as the old "economy 7" tariffs to consumers used to work and modern EV charging tariffs do now where people can get "free" or very low rate Kwh at certain times (which can be used for the whole home not just for a car). There are ads on the TV for some suppliers' smart tariffs that already offer times when electricity is "free"
Oh and the Spanish issue wasn't too much power it was too much low-inertia input i.e. stuff that can be turned off more easily and not maintain the phase compared to turbines that keep spinning.
Plenty of good tech solutions to that (flywheels etc.) but the easiest and immediate one is just get people to use a bit more whilst the they are built or the natural rise in demand over the years starts to consume enough.
If anyone is interested (Including foreign not so friendly governments) the UK Power grid data is all live!
UK GRID LIVE DATA HERE"- https://www.energydashboard.co...
CLICK on Sites at the top and you can view any of over 3,000 UK power Stations
PS - YES batteries are required AND they are being built - I live in east Anglia and there is a rush to add new cables from Offshore wind farms to the grid (Including much debate about underground v pylon from NIMBY's). Battery stations are being built as well - Quick AI search
Just build some battery storage (or other energy storage) - sorted !
We shall all have jam. Tomorrow.
But will we still be able to call it Jam? - UK Marmalade to be renamed "Citrus Marmalade"
what I take from this, is that when my Eon 18 month fixed price deal ends in June I shall be contacting Octopus. Nuff said.
James Cropper (LON:CRPR)
Positive update despite the company’s preferred use of ebitda.
The value is in the Advanced Materials division, but the progress at the Paper division is encouraging and if it can move into profit, even if small this should provide an increasing tailwind. Given the family ownership and origins of the company it is unlikely to be sold.
I seem to recollect Roland I think writing a piece on the potential of James Cropper some months ago and would welcome any further views from the Team.
I have a reasonable holding.
Morning Jonno,
We're definitely planning to take a look at James Cropper (LON:CRPR) this morning - stay tuned!
Roland
Thank you Roland.
I look forward to your view
Atalaya Mining Copper SA (LON:ATYM) on the face of it the results don't look too special with a thumping great 1st quarter loss BUT I don't understand / know what the SP is that they refer to and they don't define it. That said, I used to work in a very well known specialist Emerging Markets Fund Management back office and it took a good year to find out what AuM meant so I'm not too bright !
I have no idea what to think of the RNS and need to go back to do some background reading and DYORing. Lol.
Serabi Gold (LON:SRB) strong update with room for growth. A ten-bagger over 30 months now, amazingly, and still top ranked.